
 Wearable Skin Adhesives Market | 2026-2036
Wearable Skin Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Skin Adhesives Market Intelligence
The divergence between premium silicone formulations and commodity acrylic tiers is hardening as device OEMs impose stricter wear-time and biocompatibility specifications. 3M leverages its medical tape heritage to sustain high-margin positions in long-duration wearable applications. Henkel AG & Co. KGA anchors European supply chains with specialized UV-curable adhesive platforms. Scapa Group competes through flexible manufacturing configurations that serve mid-volume device contracts.
Wearable skin adhesives comprise pressure-sensitive bonding systems engineered for direct dermal contact, typically incorporating silicone, acrylic, or hydrocolloid chemistries with controlled moisture vapor transmission rates between 200 and 2000 g/m²/day to manage transepidermal water loss during device wear. Their primary commercial purpose is securing continuous glucose monitors, cardiac patches, and drug delivery systems to skin surfaces across 7- to 14-day wear cycles. Silicone segments lead value generation due to gentler removal profiles that reduce medical adhesive-related skin injury in elderly populations. Hydrocolloid formulations represent the fastest-growing chemistry as ambulatory wound care expands beyond hospital settings. Acrylic technology occupies mature, cost-sensitive channels where hospital procurement prioritizes unit economics over extended wear performance.
FDA 21 CFR Part 820 quality system regulations and ISO 10993 biological evaluation standards shape material selection and clinical validation burdens for adhesive suppliers seeking US market access. The EU MDR and REACH chemical restrictions impose parallel compliance architectures that favor larger manufacturers with dedicated regulatory affairs functions. Stakeholders must monitor evolving state-level Medicaid reimbursement policies for remote therapeutic monitoring as these coverage decisions will determine homecare volume trajectories independent of technical adhesive performance.
Market Dynamics
FDA biocompatibility requirements and ISO 10993 standards are compressing qualification timelines for new adhesive formulations while simultaneously raising capital barriers for market entry. Device OEMs now mandate 14-day wear validation before contract consideration, forcing suppliers to front-load clinical testing expenditures.
Growth Catalysts
- Remote Patient Monitoring Expansion:Homecare settings are extending adhesive deployment for continuous glucose monitors and cardiac patches outside hospital walls, creating pull-through demand for gentle-removal silicone chemistries.
- ISO 10993-5 Cytotoxicity Standards:Harmonized biological evaluation protocols are accelerating regulatory clearance velocity for qualified suppliers who maintain pre-submitted master files with FDA.
- Aging Demographics in the United States:Diabetes prevalence and chronic wound management needs among elderly populations are sustaining recurring adhesive consumption for long-duration wearable devices.
Market Restraints
- Silicone Raw Material Concentration:Specialty medical-grade silicone supply concentrates among a limited cohort of petrochemical refiners, exposing formulators to input cost volatility and allocation risk during supply shocks.
- EU MDR Technical Documentation Burden:Enhanced clinical evidence requirements for skin-contact devices are extending time-to-market for European launches and favoring incumbent players with established quality management systems.
- Acrylic Substitution Ceiling:Cost-sensitive hospital procurement channels continue specifying commodity acrylic adhesives despite inferior biocompatibility profiles, capping premium chemistry penetration in acute care settings.
Strategic Opportunities
- Pediatric Wearable Applications:Neonatal monitoring and infant respiratory patches represent an underpenetrated segment where ultra-gentle silicone removal properties command substantial pricing premiums over standard formulations.
- Medicaid Reimbursement Expansion:State-level coverage determinations for remote therapeutic monitoring are creating reimbursement tailwinds that will independently drive homecare volume regardless of technical adhesive specifications.
- Hydrocolloid-Wearable Convergence:Ambulatory wound care devices integrating absorbent hydrocolloid layers with electronic sensors are opening hybrid application spaces beyond traditional glucose monitoring.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993-10 sensitization and irritation studies require 16-26 week completion timelines, compressing product development cadences and delaying revenue recognition for new formulations.
- Adhesion-Skin Integrity Trade-off Engineering:Formulators face persistent technical constraints balancing secure 14-day device retention against medical adhesive-related skin injury prevention in fragile elderly dermis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Skin Adhesives Market |
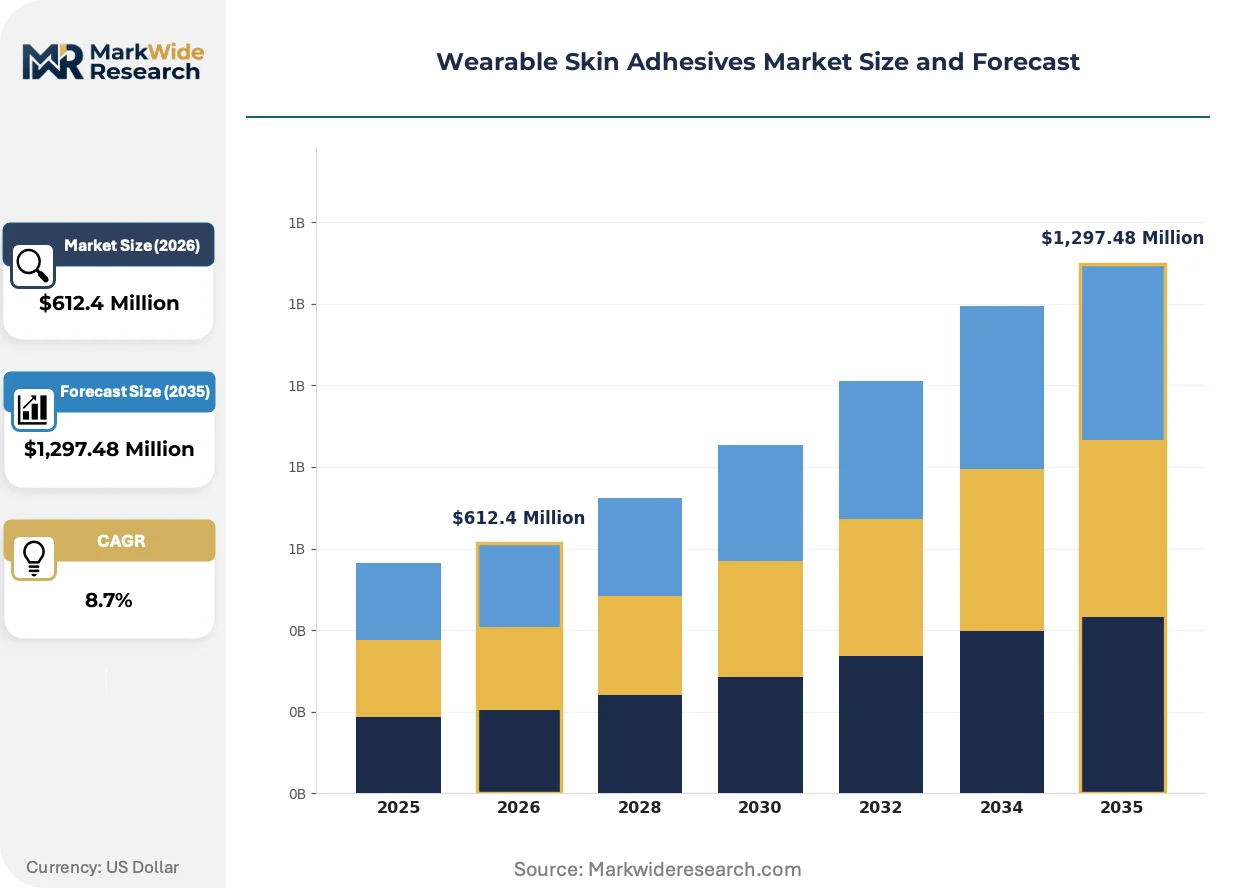
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid, Silicone, Acrylic, TPU Application: Chronic Wounds, Postoperative Care, Sports Medicine, Aesthetic Procedures End User: Hospitals, Homecare Settings, Long-term Care Facilities, Athletic Trainers Distribution Channel: Online Retail, Pharmacies, Hospital Supply, Medical Device Distributors |
| Companies Covered | Adhesives Research, Scapa Group, 3M, Polymer Science, Inc., Lohmann GmbH & Co. KG, Henkel AG & Co. KGA, Dow Corning, Avery Dennison Corporation, H.B. Fuller, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Skin Adhesives Market Strategic Shifts & Innovations
Moisture management technologies and regulatory harmonization efforts are restructuring how adhesive suppliers compete. Formulation science is pivoting toward biomimetic approaches that replicate skin barrier function rather than simply adhering to it.
Silicone gel adhesive platforms with tunable tack profiles are decentralizing the traditional trade-off between initial bond strength and gentle removal. Cardiac patch manufacturers are adopting these materials at accelerated pace to support 7- to 14-day wear cycles without epidermal stripping. The technology is decentralizing procurement authority from hospital central supply toward device OEMs who specify exact moisture vapor transmission rates.
EU MDR Article 10 technical documentation requirements are mandating clinical performance data for all skin-contact device components. Adhesive suppliers must now generate biological evaluation reports equivalent to finished device manufacturers. European contract manufacturers are responding by consolidating supplier panels to reduce audit burden and traceability complexity.
Direct-to-consumer wearable brands are unbundling traditional distribution through medical device distributors. Continuous glucose monitor users now purchase replacement adhesives through manufacturer subscription portals rather than pharmacy channels. This pattern is most visible in the United States where DTC penetration for diabetes management devices exceeds other geographies.
Wearable Skin Adhesives Market Segmentation
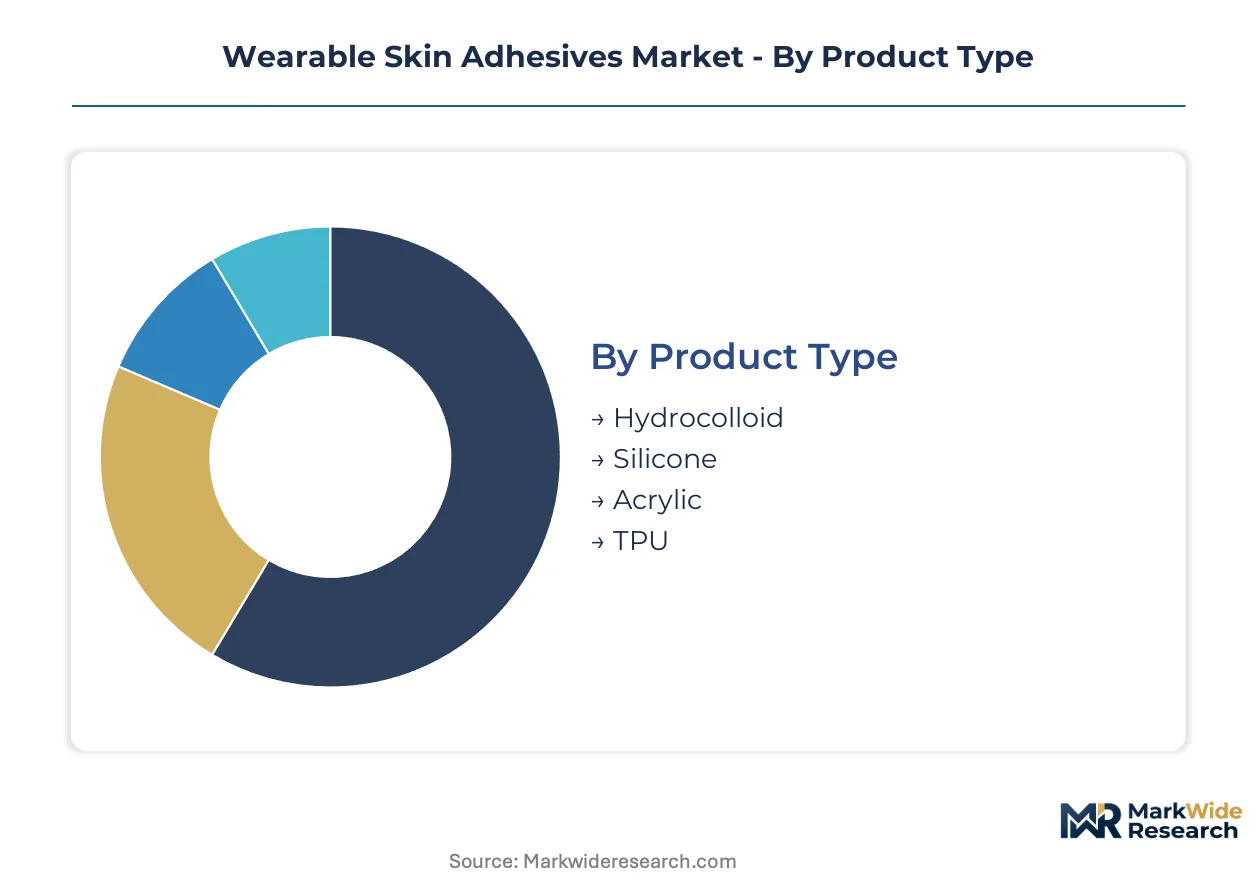
Wearable skin adhesives demand fragments across chemistry types, clinical applications, and procurement channels. Each segmentation axis carries distinct margin profiles and regulatory burdens that reshape supplier priorities.
Product Type:
Formulation chemistry determines moisture vapor transmission rates, wear duration, and removal trauma profiles.
- Silicone:Gel-based systems with tunable tack enable 7- to 14-day wear cycles without epidermal stripping. Demand concentrates in continuous glucose monitors and cardiac patches for elderly populations where medical adhesive-related skin injury prevention drives procurement specifications.
- Hydrocolloid:Absorbent carboxymethylcellulose matrices manage exudate while maintaining sensor adhesion. Ambulatory wound care expansion beyond hospital settings is accelerating deployment in hybrid electronic-absorbent devices.
- Acrylic:Cost-optimized pressure-sensitive adhesives serve acute care procurement channels prioritizing unit economics over extended wear performance.
- TPU:Thermoplastic polyurethane films provide moisture barrier properties with elastic recovery for motion-intensive applications.
Mature deployment sits with acrylic formulations. Newer deployment is concentrated in hydrocolloid-wearable hybrid configurations.
Application:
Clinical use cases impose divergent wear-time requirements and biocompatibility validation thresholds.
- Chronic Wounds:Venous leg ulcers and diabetic foot lesions require absorbent adhesive platforms with integrated moisture management. Homecare reimbursement expansion for remote therapeutic monitoring is extending device deployment outside wound clinic settings.
- Postoperative Care:Surgical incision monitoring patches demand sterile-grade adhesion with predictable removal timelines. Hospital infection control protocols favor single-use disposables over reusable alternatives.
- Sports Medicine:Kinesiology tapes and motion-tracking patches prioritize elastic recovery and sweat resistance over extended wear duration.
- Aesthetic Procedures:Post-treatment recovery patches for laser and injectable procedures command premium pricing for gentle-removal formulations.
Volume concentration rests with chronic wound management. Margin expansion is steepest in aesthetic procedure channels.
End User:
Procurement authority varies across institutional buyers, direct consumers, and specialized care providers.
- Hospitals:Central supply departments negotiate multi-year contracts based on total cost of ownership metrics. Group purchasing organizations aggregate demand across health system networks.
- Homecare Settings:Patients and caregivers purchase replacement adhesives through manufacturer subscription portals or durable medical equipment suppliers. Remote patient monitoring expansion is decentralizing procurement from institutional to individual decision-makers.
- Long-term Care Facilities:Skilled nursing operators balance resident skin integrity protocols against staff application efficiency requirements.
- Athletic Trainers:Sports medicine professionals source specialized tapes through direct-to-practitioner distributors with rapid replenishment cycles.
Institutional procurement dominates hospital and long-term care channels. Direct-to-consumer velocity is climbing fastest in homecare settings.
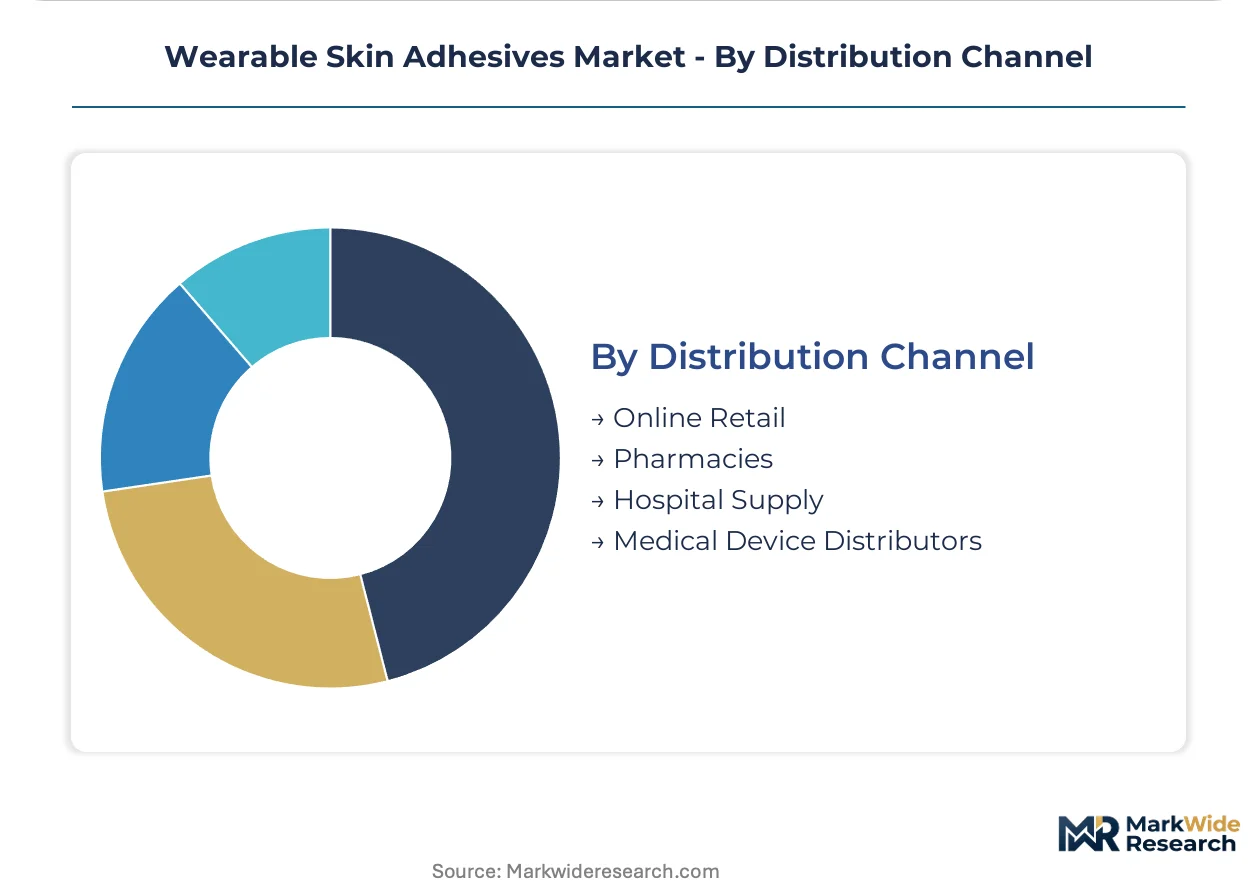
Distribution Channel:
Channel selection determines pricing transparency, inventory carrying costs, and end-user technical support access.
- Online Retail:Manufacturer-direct subscription portals bypass traditional medical device distributors. Continuous glucose monitor users in the United States increasingly replenish adhesives through automated delivery programs.
- Pharmacies:Retail pharmacy chains stock over-the-counter kinesiology tapes and basic wound care adhesives with limited clinical guidance.
- Hospital Supply:Integrated delivery networks maintain consignment inventory arrangements with preferred adhesive suppliers.
- Medical Device Distributors:Specialized distributors provide technical field support and regulatory documentation for OEM device manufacturers.
Traditional hospital supply retains volume concentration. Online retail is capturing share fastest in patient-directed replenishment segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American adhesive formulation activity, with 3M's medical tape heritage concentrating R&D and manufacturing capacity in the Upper Midwest corridor.
United States
FDA 21 CFR Part 820 quality system regulations and ISO 10993 biological evaluation standards govern material selection for continuous glucose monitors and cardiac patches. Diabetes prevalence among aging populations in Florida and Arizona sustains recurring adhesive consumption for long-duration wearables. The Boston-Cambridge medical device cluster houses specialized contract manufacturers serving CGM OEMs with validated silicone platforms.
Germany
EU MDR Article 10 technical documentation requirements mandate clinical performance data for all skin-contact device components. Henkel AG & Co. KGA anchors European supply chains from Düsseldorf with UV-curable adhesive platforms. The Baden-Württemberg precision manufacturing belt hosts mid-volume device contract manufacturers consolidating supplier panels to reduce audit burden.
United Kingdom
NHS England remote therapeutic monitoring reimbursement policies determine homecare volume trajectories for wound care adhesives. Scapa Group operates flexible manufacturing configurations serving device OEMs from Greater Manchester. The Oxford-Cambridge life science corridor attracts hydrocolloid-wearable hybrid developers seeking proximity to clinical validation partners.
Japan
PMDA biocompatibility protocols align with ISO 10993-5 cytotoxicity standards, accelerating regulatory clearance for qualified suppliers. METI industrial policy supports domestic production of medical-grade silicone formulations. The Kansai region around Osaka hosts specialized converters serving cardiac patch manufacturers with 7- to 14-day wear validation capabilities.
China
NMPA medical device registration requirements impose parallel compliance architectures for skin-contact adhesive imports. The Yangtze River Delta concentration around Shanghai houses contract manufacturers supplying global CGM brands with cost-optimized acrylic formulations. Domestic demand for aesthetic procedure recovery patches drives premium pricing for gentle-removal silicone platforms in Shenzhen-Guangzhou corridor.
Wearable Skin Adhesives Market Key Industry Players
Premium-margin players sit above commodity-margin players across biocompatibility validation depth and wear-time specification tiers. The supplier base concentrates among diversified materials conglomerates with dedicated medical divisions and specialized adhesive pure-plays with flexible manufacturing configurations. Three archetypes dominate: integrated petrochemical-to-adhesive formulators with captive silicone supply, regional contract manufacturers with rapid formulation iteration capabilities, and medical tape heritage players with long-duration wear validation libraries. Competitive dynamics center on strategic partnerships with device OEMs and geographic expansion through qualified contract manufacturing networks.
Within the diversified conglomerate tier, 3M and Henkel AG & Co. KGA exemplify scale-driven positions anchored by medical tape heritage and UV-curable platform specialization respectively. Scapa Group occupies the flexible manufacturing archetype, serving mid-volume device contracts with rapid configuration adjustments. Among adhesive specialists with focused medical portfolios, Lohmann GmbH & Co. KG represents the European contract manufacturing consolidation trend, reducing traceability complexity for skin-contact device OEMs navigating EU MDR documentation burdens.
| Leading Market Players |
|---|
| Adhesives Research |
| Scapa Group |
| 3M |
| Polymer Science, Inc. |
| Lohmann GmbH & Co. KG |
| Henkel AG & Co. KGA |
| Dow Corning |
| Avery Dennison Corporation |
| H.B. Fuller |
| Others |
Cost & Logistics Intelligence
REACH chemical restrictions and ISO 10993 biocompatibility mandates gate qualified supply and premium-tier pricing access for wearable skin adhesive suppliers. Device OEMs now require 14-day wear validation documentation as a baseline for contract eligibility, compressing the supplier pool to formulators with pre-submitted FDA master files and captive silicone refining relationships.
Pricing Analysis
Value-based pricing anchored to medical adhesive-related skin injury reduction outcomes dominates silicone tier negotiations with long-term care facilities and pediatric device manufacturers. Pricing stratifies across premium silicone, standard hydrocolloid, and economy acrylic tiers based on ISO 10993-5 cytotoxicity certification depth and moisture vapor transmission rate specifications. Cost compression in acrylic formulations is intensifying because hospital group purchasing organizations aggregate demand across multi-year contracts prioritizing unit economics. Homecare direct-to-consumer channels show least price sensitivity due to Medicaid reimbursement tailwinds for remote therapeutic monitoring.
Supply Chain Analysis
Regional distribution centers in Minneapolis, Düsseldorf, and Osaka operate hub-and-spoke patterns serving device OEM clusters with validated silicone platforms. Manufacturing concentrates in the United States, Germany, and Japan where FDA 21 CFR Part 820, EU MDR, and PMDA quality system regulations align with ISO harmonization. Specialty medical-grade silicone feedstock draws from petrochemical refiners in the United States and Germany, exposing formulators to allocation risk during supply shocks. Single-source vulnerability concentrates in UV-curable adhesive precursor supply. Distribution runs through medical device distributors with technical field support capabilities for OEM validation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wearable skin adhesives sector sits in a chemistry-transition phase as silicone gel platforms displace legacy acrylic formulations in 7- to 14-day wear applications. This replacement cycle favors suppliers with tunable tack profiles and pre-validated biocompatibility libraries.
For Market Incumbents: To counter commodity acrylic substitution pressure from cost-optimized Asian contract manufacturers, deepen captive silicone supply relationships and expand UV-curable platform capacity in Düsseldorf-adjacent manufacturing corridors. Prioritize ISO 10993-10 sensitization study pre-submission to FDA to compress 16-26 week validation timelines for new device OEM partnerships. For New Entrants and Emerging Players: Pediatric wearable applications represent the most penetrable white-space segment where ultra-gentle removal properties command substantial pricing premiums over standard formulations. Neonatal monitoring patches and infant respiratory devices lack dedicated adhesive suppliers with validated 7-day wear biocompatibility. Pursue direct-to-consumer subscription portal partnerships with CGM manufacturers bypassing traditional pharmacy distribution. For Investors and Strategic Acquirers: State-level Medicaid reimbursement expansion for remote therapeutic monitoring is the leading indicator that homecare volume trajectories will decouple from hospital procurement cyclicality. Target flexible manufacturing specialists with rapid formulation iteration capabilities serving mid-volume device contracts. Watch for EU MDR technical documentation burden consolidation signals among European contract manufacturers reducing supplier panel complexity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Master File Pre-Submission | FDA pre-submitted biological evaluation reports accelerate 14-day wear validation for CGM OEMs. |
| Silicone Gel Platform Capacity Expansion | Tunable tack manufacturing in Minneapolis corridor supports cardiac patch 7- to 14-day wear cycles. |
| Pediatric Wearable Certification Investment | Ultra-gentle removal validation opens neonatal monitoring segments with premium pricing power. |
| Direct-to-Consumer Portal Integration | Manufacturer subscription bypasses pharmacy channels for diabetes management adhesive replenishment. |
| EU MDR Supplier Panel Consolidation | Reduced audit burden positions qualified formulators for Baden-Württemberg device contract manufacturing. |
Research Approach
FDA 510(k) filings, EU MDR technical documentation databases, and ISO 10993 biological evaluation standards formed the secondary backbone of this analysis. Primary interviews with adhesive formulation scientists, device OEM procurement managers, hospital GPO contract specialists, and regulatory affairs directors at silicone refiners were combined with secondary validation. Customs records tracking medical-grade silicone feedstock imports and hospital procurement database analysis provided demand-side triangulation. Bottom-up adhesive consumption modeling and top-down device shipment estimates were reconciled across chemistry type and application segments.
Historical trendline analysis of continuous glucose monitor and cardiac patch deployment patterns informed the projection framework. Segmentation modeling across chemistry type, clinical application, end-user procurement channel, and regional regulatory cluster captured demand fragmentation. CAGRs were derived from fitted growth curves applied to validated baseline consumption estimates. Key forecast inputs included Medicaid reimbursement policy trajectories for remote therapeutic monitoring and EU MDR implementation timelines for skin-contact device components.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silicone raw material allocation disruptions and state-level coverage determination volatility for homecare wearables. Outputs reflect documented assumptions regarding ISO 10993-5 cytotoxicity standard harmonization and device OEM validation requirement stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Australia Sealants Market
Adhesives & Sealants
Die Attach Materials Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Global Slack Wax Market
Adhesives & Sealants
High Temperature Adhesives and Sealants Market
Adhesives & Sealants
Global Non-Woven Adhesives Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Fabric Adhesive Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
Global Lithium Ion Battery Binders Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Epoxy Glue Market