
 Global Fire-Resistant Coating Market | 2026-2036
Global Fire-Resistant Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fire-Resistant Coating Market Foresight
Commercial construction is consolidating its share of fire-resistant coating procurement as developers specify higher-performance intumescent systems for steel frameworks. Akzo Nobel N.V. leverages its European certification portfolio to anchor premium specifications across Middle Eastern megaprojects. Sherwin-Williams Company sustains North American channel dominance through its Carboline subsidiary and broad distribution infrastructure. PPG Industries competes on marine and industrial specialization, extending its protective coatings expertise into offshore fire protection.
Fire-resistant coatings are reactive surface treatments formulated with intumescent binders, cementitious aggregates, or silicone polymers that expand or insulate substrates when exposed to temperatures exceeding critical thresholds, primarily engineered to prolong structural steel integrity during fire events. Intumescent formulations char into insulating layers at elevated temperatures, while cementitious variants provide passive thermal mass through sprayed mineral fiber blends. Water-based intumescent technologies lead volume consumption in building applications due to lower volatile organic compound profiles and simplified site application, whereas solvent-based systems retain margin concentration in marine and aerospace segments where durability specifications remain stringent.
The US National Fire Protection Association standards, China's GB 14907 steel structure fireproofing code, and the EU Construction Products Regulation collectively mandate minimum fire resistance ratings that shape product formulation requirements and market access conditions across jurisdictions. Regulatory divergence between ASTM E119 testing protocols and European EN 13381 classifications forces manufacturers to maintain multiple certification streams, elevating compliance costs for mid-scale suppliers. Stakeholders must monitor evolving green building certification schemes that increasingly weight low-emission fire protection materials alongside traditional performance benchmarks.
Market Dynamics
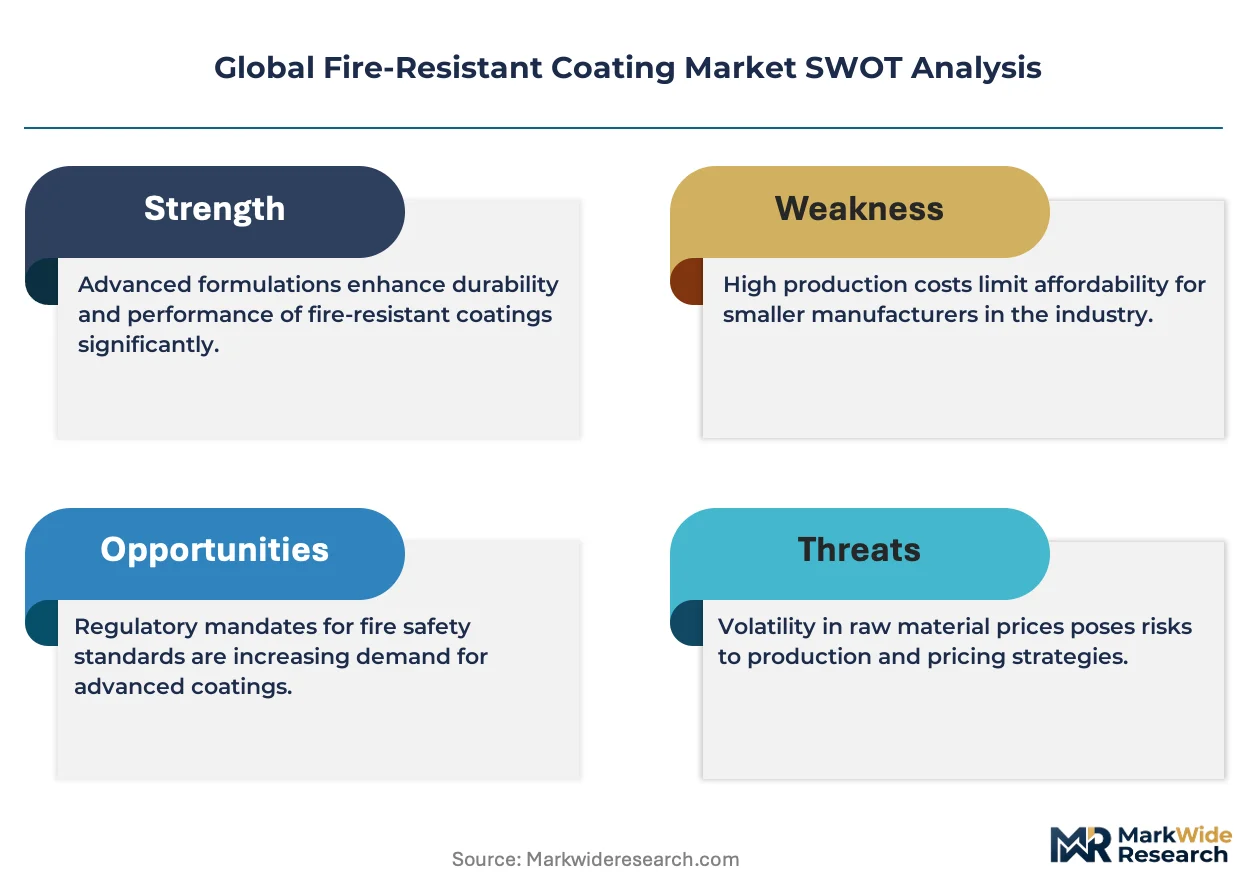
Certification divergence between ASTM E119 and EN 13381 test protocols is fragmenting supplier compliance portfolios and elevating entry barriers for mid-scale manufacturers seeking multi-jurisdictional market access.
Growth Catalysts
- UAE Civil Defense mandates:Megaproject specifications in Dubai and Abu Dhabi now require third-party certified intumescent systems, pulling procurement toward pre-qualified international suppliers with established testing documentation.
- China's GB 14907 tightening:Steel structure fireproofing standards are concentrating demand among domestic construction firms with certified supply chains, compressing vendor qualification timelines.
- Intumescent water-based formulations:Lower volatile organic compound profiles are displacing solvent systems in commercial building applications where green building certification schemes weight emission metrics.
Market Restraints
- Epoxy resin input volatility:Petrochemical feedstock cost swings compress margin predictability for intumescent binder production, particularly affecting smaller compounders without long-term supply agreements.
- Testing infrastructure concentration:Accredited fire resistance laboratories cluster in Germany, the United Kingdom, and the United States, creating geographic bottlenecks for certification throughput.
- Cementitious substitution ceiling:Spray-applied mineral fiber blends face thickness and weight constraints that limit specification reach in high-rise steel frameworks.
Strategic Opportunities
- Saudi Arabia's giga-project pipeline:NEOM and Red Sea Development Authority procurement frameworks create entry points for certified coating suppliers willing to establish local technical service presence.
- Offshore wind tower protection:Marine-grade intumescent specifications for North Sea and Baltic installations merge fire resistance with corrosion protection in a single treatment protocol.
- EU Construction Products Regulation harmonization:CE marking mutual recognition is simplifying cross-border specification for pan-European contractors, reducing duplicate testing expenditure.
Industry Challenges
- Fire test engineer scarcity:Qualified personnel capable of interpreting ASTM E119 and EN 13381 divergence are concentrated among incumbent certification bodies, constraining supplier technical staffing.
- Multi-standard inventory complexity:Manufacturers must maintain parallel formulation variants to satisfy jurisdiction-specific approval lists, elevating working capital requirements and obsolescence risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fire-Resistant Coating Market |
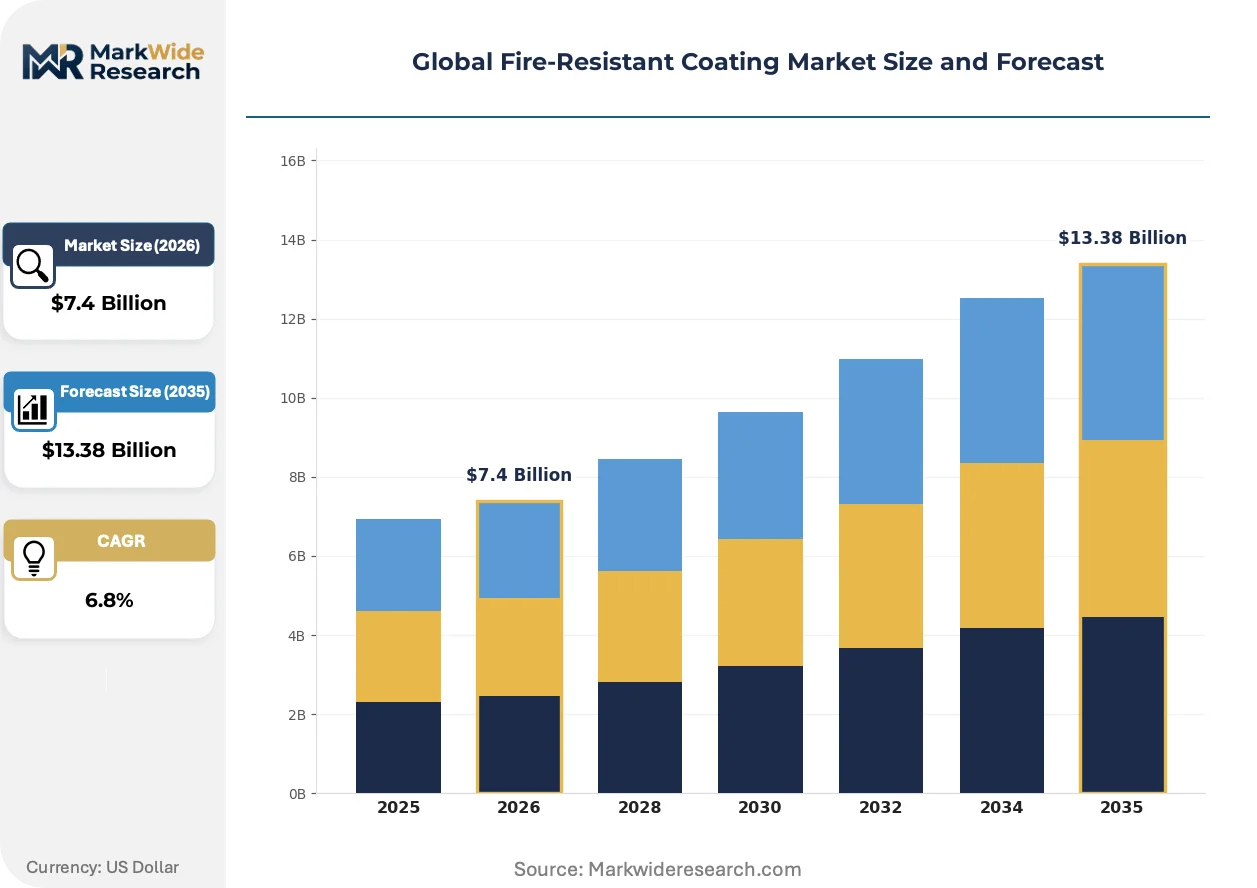
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intumescent, Cementitious, Silicone, Epoxy, Acrylic Technology: Intumescent Char, Cement-Based, Water-Based, Solvent-Based, Polymer-Based Application: Building & Infrastructure, Marine, Power Plants, Oil & Gas Facilities, Aerospace End User: Construction Firms, Shipbuilders, Energy Sector, Aircraft Manufacturers, Industrial Plants |
| Companies Covered | Akzo Nobel N.V., Sherwin-Williams Company, PPG Industries, Jotun, Hempel A/S, BASF SE, Nippon Paint Co. Ltd., 3M, Carboline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fire-Resistant Coating Market Shifts & Advancements
Formulation chemistry and application methodology are converging around thinner-film intumescent systems that reduce material volume while extending fire resistance ratings. Three developments are compressing competitive positioning.
Hybrid intumescent-silicone polymer systems are consolidating specification preference in aerospace and marine segments where combined thermal and environmental protection is non-negotiable. Boeing and Airbus tier-one suppliers are qualifying these formulations for engine nacelle and cargo bay applications. The technology is consolidating supplier tiers by merging two previously separate coating categories into single-source procurement.
REACH authorization requirements for flame retardant additives are forcing reformulation of legacy halogen-based intumescent chemistries across EU member states. Manufacturers are pivoting toward phosphorus-nitrogen synergists that maintain char formation without SVHC classification. Building product distributors in France and Germany are accelerating inventory rotation to de-risk stranded stock positions.
Specification authority is migrating from general contractors to specialist fire protection consultants who control submittal approval workflows on complex steel frameworks. Engineering firms in Singapore and Australia are bundling coating selection with structural fire engineering services, compressing direct manufacturer influence over product selection. This shift is most visible in high-rise commercial towers where performance-based design approaches dominate.
Global Fire-Resistant Coating Market Segmentation
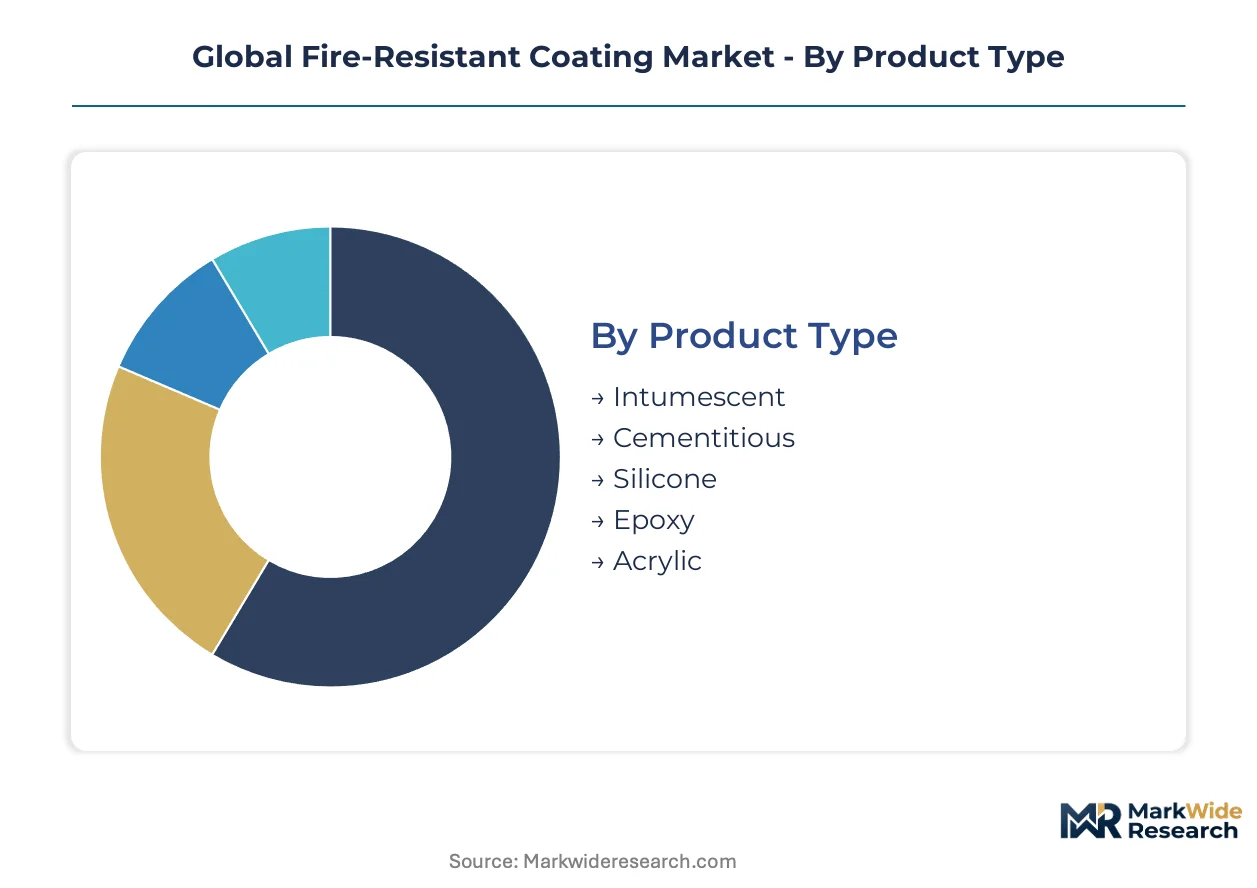
Fire-resistant coating procurement divides sharply by substrate requirements, regulatory testing protocols, and application environment severity. Specification authority migrates differently across these axes, with architects controlling product-type selection while contractors dominate technology choices based on site logistics.
Product Type:
Cost tier separates buyers in this category, with premium intumescent systems commanding specification in high-visibility commercial steel while cementitious alternatives serve budget-constrained industrial projects.
- Intumescent:These formulations expand into insulating char layers when exposed to temperatures exceeding critical thresholds, typically formulated with ammonium polyphosphate and pentaerythritol binder systems. Demand concentrates in UAE megaprojects and Saudi giga-developments where Civil Defense mandates require certified third-party documentation for structural steel protection.
- Cementitious:Spray-applied mineral fiber blends provide passive thermal mass through Portland cement and vermiculite aggregates, favored in power plant boiler housings and petrochemical facilities where thickness tolerance exceeds aesthetic constraints. China's domestic construction firms specify these systems heavily under tightening GB 14907 procurement frameworks.
- Silicone:High-temperature elastomeric coatings maintain flexibility across thermal cycling extremes, specified for aerospace engine nacelles and exhaust stack applications.
- Epoxy:Thermosetting resin systems bond aggressively to prepared steel substrates, dominating offshore platform specifications where corrosion-fire dual protection is mandatory.
- Acrylic:Water-dispersed film formers serve decorative architectural applications with modest fire rating requirements, common in institutional interior steel.
Volume sits with cementitious systems in industrial infrastructure; growth tilts toward intumescent formulations as commercial construction specifications tighten globally.
Technology:
Application methodology and volatile organic compound compliance drive technology selection, with water-based systems displacing solvent alternatives wherever green building certification schemes operate.
- Intumescent Char:Reactive chemistry produces multicellular carbonaceous foam at elevated temperatures, with char expansion ratios determining fire resistance duration. REACH authorization pressures in Europe are forcing phosphorus-nitrogen synergist reformulations to replace legacy halogen-based additive packages.
- Cement-Based:Hydraulic binder systems cure through moisture retention, requiring controlled application environments but eliminating solvent emission concerns entirely.
- Water-Based:Aqueous dispersion technologies dominate commercial building procurement in Germany and France where distributor inventory rotates rapidly to de-risk stranded stock from evolving emission regulations.
- Solvent-Based:Hydrocarbon carrier systems retain specification in marine and aerospace segments where film integrity under salt spray and thermal shock remains non-negotiable.
- Polymer-Based:Hybrid silicone-acrylic chemistries merge environmental durability with intumescent response, gaining traction in offshore wind tower applications across the North Sea.
Water-based technologies capture the steepest expansion trajectory as emission regulations tighten; solvent systems defend margin concentration in performance-critical niches.
Application:
End-use environment severity determines specification grade, with hydrocarbon fire exposure in oil and gas facilities demanding fundamentally different chemistry than cellulosic fire scenarios in commercial buildings.
- Building & Infrastructure:Steel framework protection in high-rise commercial towers and transportation hubs constitutes the largest addressable volume, with Singapore and Australian engineering firms bundling coating selection into performance-based design services.
- Marine:Vessel superstructure and engine room applications require IMO-compliant formulations that resist salt corrosion while maintaining fire integrity, with shipbuilders in South Korea and Japan driving specification for hybrid protective systems.
- Power Plants:Boiler casing and turbine hall applications specify cementitious systems for thermal mass and acoustic dampening alongside fire protection.
- Oil & Gas Facilities:Hydrocarbon pool fire exposure mandates epoxy-intumescent hybrids with rapid char formation under extreme heat flux conditions.
- Aerospace:Engine nacelle and cargo bay applications qualify through Boeing and Airbus tier-one supplier networks, with hybrid intumescent-silicone systems consolidating single-source procurement.
Building and infrastructure commands absolute volume; aerospace and offshore wind applications are climbing fastest as specialized fire-marine dual specifications proliferate.
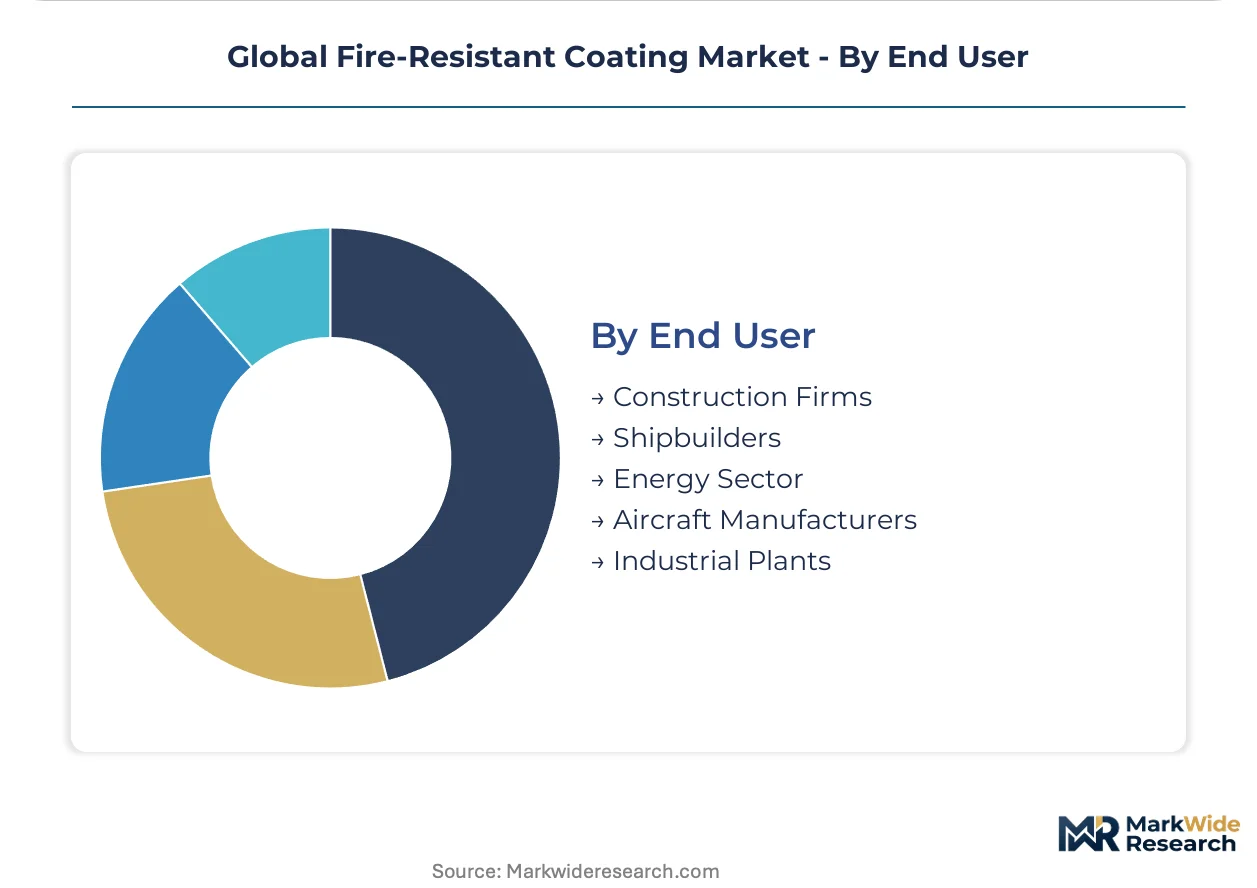
End User:
Procurement sophistication varies dramatically, with aircraft manufacturers maintaining captive specification authority while construction firms delegate coating selection to specialist fire protection consultants.
- Construction Firms:General contractors in the UAE and Saudi Arabia increasingly defer to pre-qualified supplier lists established by Civil Defense and giga-project authorities, compressing direct manufacturer access.
- Shipbuilders:South Korean and Japanese yards specify through classification society approval frameworks, with Lloyd's Register and DNV certification gates filtering vendor participation.
- Energy Sector:Utility procurement departments balance first-cost against lifecycle inspection requirements, favoring cementitious systems where accessibility permits thickness.
- Aircraft Manufacturers:Boeing and Airbus maintain proprietary qualification protocols that consolidate supplier tiers through exhaustive thermal and environmental testing.
- Industrial Plants:Owner-operator engineering departments in petrochemical and chemical processing specify through corporate engineering standards that often mandate specific brand approvals.
Construction firms drive absolute consumption volume; aircraft manufacturers and offshore wind developers are gaining share fastest as specification complexity concentrates procurement among qualified suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in the Middle East and China's coastal manufacturing belts concentrate fire-resistant coating procurement through infrastructure-heavy development programs and steel-intensive construction codes.
United States
Commercial high-rise construction in Manhattan and Chicago drives specification for ASTM E119-certified intumescent systems. The National Fire Protection Association standards mandate minimum fire resistance ratings that shape formulation requirements across jurisdictions. Houston's petrochemical corridor demands epoxy-intumescent hybrids for offshore platform dual-protection specifications.
Germany
Industrial facility retrofits in the Ruhr region and North Rhine-Westphalia sustain cementitious system procurement for power plant applications. REACH authorization requirements for flame retardant additives force phosphorus-nitrogen synergist reformulations across EU member states. Munich's aerospace cluster qualifies hybrid intumescent-silicone systems for engine nacelle applications through tier-one supplier networks.
China
Steel-intensive megaprojects in Shanghai and Shenzhen concentrate demand for GB 14907-compliant fireproofing systems. The Ministry of Ecology and Environment tightening emission standards displaces solvent-based formulations in favor of water-dispersed technologies. Beijing-Tianjin-Hebei's construction firms consolidate procurement among domestic suppliers with certified supply chains.
United Arab Emirates
Megaproject specifications in Dubai and Abu Dhabi require third-party certified intumescent systems per Civil Defense mandates. The UAE's pre-qualified supplier lists compress vendor qualification timelines for international coating manufacturers. Jebel Ali's industrial zone anchors distribution infrastructure serving Saudi Arabia's giga-project pipeline.
Saudi Arabia
NEOM and Red Sea Development Authority procurement frameworks create entry points for certified coating suppliers establishing local technical service presence. The Saudi Fire Code adoption of international testing protocols aligns specification requirements with European EN 13381 classifications. Riyadh's commercial tower boom bundles coating selection with performance-based structural fire engineering services.
Global Fire-Resistant Coating Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation-integrated players commanding premium specifications while regional compounders serve price-sensitive industrial accounts. The vendor base clusters around three tiers: multinational coating houses with multi-jurisdictional certification portfolios, mid-scale specialists focused on marine or aerospace niches, and domestic suppliers serving localized construction markets. Two dominant competitive moves define current positioning: backward integration into intumescent binder production to secure supply chain control, and technology licensing agreements that accelerate access to jurisdiction-specific approval lists.
Among European-headquartered coating houses, Akzo Nobel N.V. and Hempel A/S exemplify the certification-heavy archetype that anchors premium specifications across Middle Eastern megaprojects. Sherwin-Williams Company represents the distribution-integrated model, sustaining North American channel dominance through broad infrastructure and subsidiary specialization. PPG Industries occupies a position within the marine-industrial hybrid tier, extending protective coatings expertise into offshore fire protection applications where dual-specification requirements concentrate procurement authority.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Sherwin-Williams Company |
| PPG Industries |
| Jotun |
| Hempel A/S |
| BASF SE |
| Nippon Paint Co. Ltd. |
| 3M |
| Carboline |
| Others |
Supply & Pricing Matrix
Epoxy resin feedstock volatility cascades through intumescent binder production costs, compressing margin predictability for compounders without long-term petrochemical supply agreements while forcing project-based pricing premiums in the UAE and Saudi Arabia where Civil Defense certification requirements concentrate procurement among pre-qualified international suppliers.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard contract pricing as Dubai megaproject deadlines compress vendor qualification windows. Three-tier pricing structure across premium certified, standard compliant, and economy industrial tiers separates Akzo Nobel and Sherwin-Williams specifications from regional compounders serving cementitious power plant applications. Pricing pressure stems from China's GB 14907 tightening as domestic construction firms consolidate procurement among certified supply chains, squeezing imported formulation margins. General contractors in industrial infrastructure remain most price-sensitive; aircraft manufacturers and offshore wind developers exhibit lowest sensitivity due to performance-based design mandates.
Supply Chain Analysis
Single-source vulnerability sits with German and UK accredited fire resistance laboratories, where ASTM E119 and EN 13381 testing infrastructure bottlenecks certification throughput for mid-scale manufacturers seeking multi-jurisdictional market access. Raw material sourcing draws from China for ammonium polyphosphate, the Netherlands for pentaerythritol, and US Gulf Coast for epoxy resin feedstocks. Tariff exposure on phosphorus-nitrogen synergist imports from EU member states under REACH authorization timelines elevates working capital requirements for parallel formulation variants. Distribution runs through Jebel Ali's industrial zone anchoring Middle Eastern megaproject logistics, with Carboline and Hempel maintaining captive technical service presence in Riyadh and Dubai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fire-resistant coating sector is executing a technology-transition phase as water-based intumescent formulations displace solvent systems in commercial construction, driven by green building certification schemes weighting emission metrics alongside traditional ASTM E119 and EN 13381 performance benchmarks.
For Market Incumbents: Anchor premium positioning through backward integration into intumescent binder production, securing captive supply of ammonium polyphosphate and pentaerythritol against petrochemical feedstock volatility. Expand certification engineering teams in Germany and the UK to relieve fire test engineer scarcity constraining technical staffing. Defend against phosphorus-nitrogen synergist reformulation costs by accelerating inventory rotation in French and German distribution channels before REACH authorization deadlines strand legacy halogen-based stock. For New Entrants and Emerging Players: Launch via specialist fire protection consultant partnerships in Singapore and Australia, where engineering firms bundle coating selection with structural fire engineering services and compress direct manufacturer influence. Target Saudi Arabia's NEOM and Red Sea Development Authority procurement frameworks, where giga-project technical service requirements create entry points for certified suppliers establishing local presence. Penetrate offshore wind tower specifications in the North Sea through hybrid intumescent-silicone polymer formulations merging fire resistance with corrosion protection. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale marine-industrial specialists with Lloyd's Register and DNV approval portfolios in South Korea and Japan, where shipbuilder consolidation is compressing vendor tiers. Long-term viability hinges on jurisdiction-specific certification assets rather than formulation IP alone, given regulatory divergence between ASTM E119 and EN 13381 protocols. Watch for EU Construction Products Regulation harmonization progress as the inflection signal simplifying cross-border specification and reducing duplicate testing expenditure for pan-European contractors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Binder Production | Captive supply of ammonium polyphosphate secures margin control against epoxy resin volatility. |
| Certification Laboratory Capacity Expansion | Additional ASTM E119 and EN 13381 testing throughput relieves geographic bottlenecks in Germany and UK. |
| Local Technical Service Establishment | Saudi giga-project mandates require on-site fire engineering support for Civil Defense approval workflows. |
| Phosphorus-Nitrogen Synergist Reformulation | REACH-compliant additive packages prevent SVHC classification stranding legacy halogen inventory. |
| Hybrid Polymer System Development | Intumescent-silicone chemistries consolidate aerospace and offshore wind procurement into single-source relationships. |
Research Methodology
Independent corroboration across fire protection engineering consultants, coating formulator R&D directors, and construction firm procurement leads underwrites the qualitative findings in this study. Primary interviews with UAE Civil Defense certification officers, German REACH compliance specialists, and Chinese GB standards implementation teams combined with secondary validation from SEC 10-K filings of listed coating manufacturers, customs trade data on ammonium polyphosphate imports, and accreditation body testing volume disclosures. Bottom-up project pipeline tracking across NEOM, Red Sea Development Authority, and Dubai megaprojects triangulates against top-down market sizing from protective coatings industry associations.
Rate-of-change decomposition across product type, technology, application environment severity, and end-user procurement sophistication drives the analytical framework over the projection horizon. Segmentation dimensions modeled include intumescent versus cementitious versus silicone formulation chemistry, water-based versus solvent-based carrier systems, building infrastructure versus marine versus aerospace end-use, and construction firm versus aircraft manufacturer versus shipbuilder purchasing authority. CAGRs derive from installed steel protection volume growth adjusted for specification upgrade intensity in commercial high-rise and offshore wind applications.
Regulatory timeline acceleration, petrochemical feedstock disruption, and fire test laboratory capacity constraints are the dominant revision risks that could alter trajectory assumptions across the analysis window. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
South Korea Automotive OEM Coatings Market
Coatings
Global Floor Coatings Market
Coatings
Fluoropolymer Coating Market
Coatings
North America Anti-Friction Coatings Market
Coatings
Batters and Coatings Market
Coatings
Anti-Friction Coatings Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Corrosion Protection Polymer Coating Market
Coatings
Cladding Coatings Market
Coatings
North America Hydrocarbon Fire Intumescent Coating Services Market
Coatings
Global Polyurea Coating Market
Coatings
Mold Release Coatings Market
Coatings
Global Sputter Coatings Market
Coatings
Vacuum Coating Machine Market
Coatings
Anti-Adhesion Coatings Market
Coatings
Global Smart Coating Market