
 Liquid-Applied Roof Coating Market | 2026-2036
Liquid-Applied Roof Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid-Applied Roof Coating Market Analytics
FM Approval 4470 and UL 790 certification cycles are redrawing competitive access, favoring manufacturers with in-house fire-resistance and wind-uplift testing capabilities. Sika AG leverages its European formulation expertise and North American production footprint to sustain specification-grade positioning across commercial membrane-over-metal assemblies. PPG Industries anchors its presence through water-borne acrylic R&D pipelines tied to LEED-compliant building envelopes. RPM International Inc. competes via specialty silicone portfolios designed for ponding-water resistance on flat commercial decks.
Liquid-applied roof coating denotes a fluid-applied, monolithic membrane that cures to form a seamless elastomeric barrier, typically formulated with acrylic emulsions, silicone polymers, or polyurethane resins at dry-film thicknesses of 20 to 40 mils for waterproofing and UV protection. The technology serves primarily to extend existing roof service life, reduce thermal transfer, and seal irregular substrates without mechanical fastening. Silicone formulations now dominate the product-type margin pool due to superior ponding-water tolerance and low-VOC compliance, while water-based acrylics lead volume in maintenance and restoration applications where cost sensitivity shapes procurement. Reflective technology represents the fastest-growing technology segment as building codes in warm-climate zones mandate minimum solar reflectance values for cool-roof credits.
EPA ENERGY STAR certification, California Title 24 Building Energy Efficiency Standards, and ASTM D6083 performance specifications collectively shape formulation chemistry, VOC thresholds, and eligibility for utility rebate programs across the United States. The country's national building code bodies at state and municipal levels are tightening cool-roof mandates, directly steering specification toward high-reflectance silicone and hybrid systems in new construction and reroofing cycles. Stakeholders must monitor emerging state-level amendments to IECC and ASHRAE standards that will recalibrate minimum thermal emittance and solar reflectance requirements for coating eligibility in public and commercial procurement.
Market Dynamics
California Title 24 and cascading state-level cool-roof mandates are compressing specification windows toward high-reflectance silicone formulations, forcing reformulation cycles and certification investments across the supply base.
Growth Catalysts
- Energy code tightening:California Title 24 and ASHRAE 90.1 amendments in Texas, Florida, and Arizona mandate minimum solar reflectance thresholds for commercial reroofing, pulling silicone and hybrid systems into specification.
- Utility rebate programs:Municipal utilities across Sun Belt metropolitan areas tie incentive eligibility to ENERGY STAR certification and ASTM D6083 compliance, accelerating reflective coating adoption on aging flat roof stock.
- Service life extension economics:Building owners facing full membrane replacement costs are specifying 20-40 mil liquid-applied systems to defer capital expenditure, particularly on metal and modified bitumen substrates.
Market Restraints
- Silicone resin supply concentration:Key silicone intermediate production clusters in Germany and China expose formulators to freight cost volatility and force majeure risk during regional energy disruptions.
- Application labor scarcity:Skilled sprayer certification for high-build elastomeric systems remains concentrated among union roofing contractors in legacy markets, constraining deployment velocity in secondary metros.
- Substrate compatibility limitations:Acrylic emulsions exhibit poor adhesion to certain thermoplastic polyolefin membranes without proprietary primers, restricting specification scope in TPO-dominant commercial portfolios.
Strategic Opportunities
- Metropolitan heat island mitigation:Chicago, New York, and Philadelphia are piloting municipal cool-roof ordinances with accelerated permitting for high-reflectance installations, opening Northeast markets historically dominated by black EPDM.
- Photovoltaic integration:Rooftop solar developers are specifying white silicone base coats beneath panel arrays to reduce operating temperatures and improve electrical output, creating specification pull-through.
- Water-borne hybrid R&D:Formulators combining silicone durability with acrylic cost structures are targeting LEED v4.1 low-emitting materials credits, accessing premium positioning in institutional procurement.
Industry Challenges
- FM Approval 4470 certification timelines:Fire-resistance and wind-uplift testing cycles extend 18-24 months, delaying product launches and freezing specification-grade positioning for mid-tier manufacturers.
- Weather-dependent application windows:Silicone and polyurethane chemistries require specific temperature and humidity ranges for proper cure, compressing install seasons in northern climates and inflating project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid-Applied Roof Coating Market |
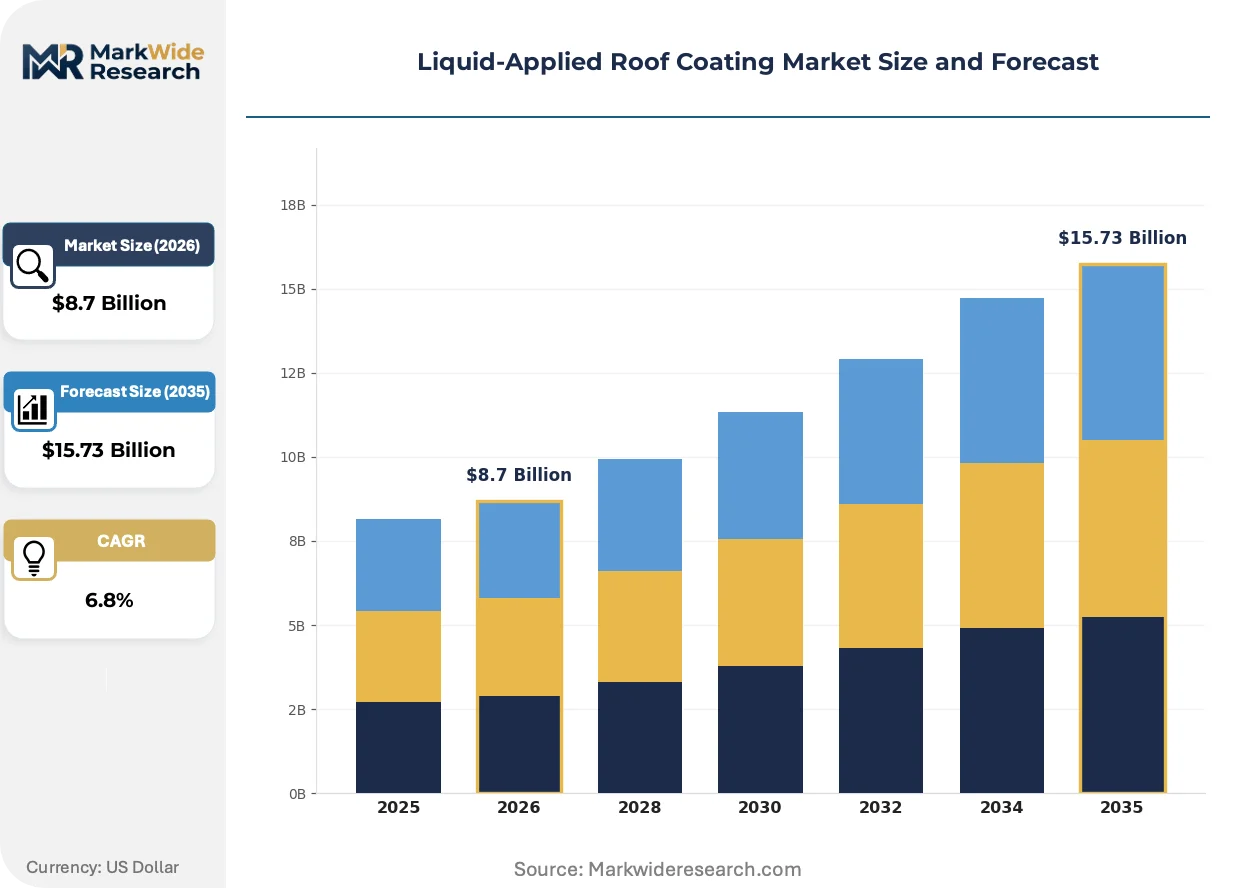
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Silicone, Polyurethane, Bitumen End User: Commercial, Industrial, Residential, Government Application: New Construction, Repair, Restoration, Maintenance Technology: Water-Based, Solvent-Based, Hybrid, Reflective |
| Companies Covered | Sika AG, BASF SE, Dow Inc., Akzo Nobel N.V., The Sherwin-Williams Company, PPG Industries, RPM International Inc., GAF Materials, Johns Manville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid-Applied Roof Coating Market Evolving Landscape
Formulation chemistry is splitting along performance-versus-cost fault lines as building codes harden and buyer sophistication deepens across commercial and institutional segments.
Silicone roof coating technology is bifurcating the specification landscape. High-solids, low-VOC formulations now dominate new commercial construction in California and Texas, while maintenance-grade water-borne acrylics retain volume in cost-sensitive restoration work. This split is compressing mid-tier polyurethane positioning and forcing manufacturers to choose certification depth over portfolio breadth.
EPA ENERGY STAR certification requirements are tightening solar reflectance minimums for steep-slope eligibility, disqualifying legacy acrylics that yellow under UV exposure. Formulators are responding with titanium-dioxide-loaded topcoats and inorganic pigment stabilization. The institutional sector—particularly K-12 and municipal buildings—is most affected, with procurement officers now requiring third-party reflectance retention data at 3-year intervals.
Building owners are unbundling coating specification from traditional roofing contractor relationships, engaging directly with manufacturer-certified applicator networks for warranty continuity. This disintermediation is most visible in Sun Belt property management portfolios, where asset managers centralize procurement across multi-site holdings and demand single-source accountability for material and labor performance.
Liquid-Applied Roof Coating Market Segmentation
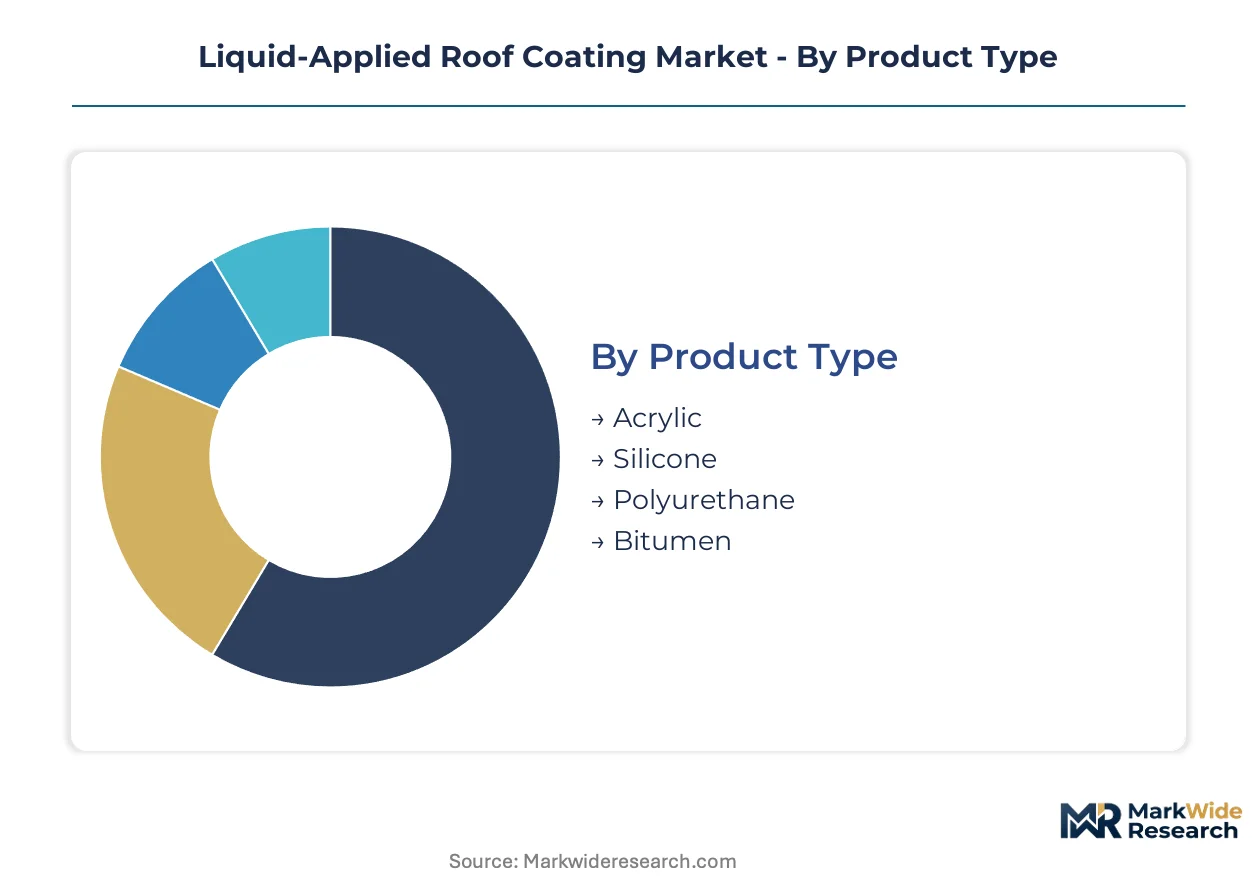
Liquid-applied roof coating procurement channels diverge sharply by performance tier and application complexity. Specification-grade silicone systems flow through manufacturer-direct certified applicator networks, while commodity acrylics distribute through traditional roofing supply houses serving maintenance contractors.
Product Type:
Channel mix splits between specification-grade direct sales for high-performance chemistries and distribution partnerships for volume maintenance products.
- Silicone:High-solids formulations cure to seamless elastomeric membranes with superior ponding-water tolerance and UV stability. Demand concentrates in California and Texas commercial reroofing, where Title 24 and ASHRAE 90.1 amendments mandate minimum solar reflectance thresholds that disqualify lower-grade alternatives.
- Acrylic:Water-borne emulsions dominate cost-sensitive restoration work through distributor networks serving maintenance contractors. Volume concentrates in Sun Belt metropolitan areas where utility rebate programs tie incentive eligibility to ENERGY STAR certification and ASTM D6083 compliance.
- Polyurethane:High-build spray-applied systems serve industrial facilities requiring chemical resistance and mechanical durability.
- Bitumen:Solvent-based cutback formulations retain niche positioning in modified bitumen substrate compatibility.
By volume, acrylic leads through distributor channels. By growth pace, silicone is climbing the fastest on specification-grade direct sales.
End User:
Cost tier stratification separates premium institutional procurement from price-driven residential maintenance.
- Commercial:Property managers across multi-site Sun Belt portfolios centralize procurement through manufacturer-certified applicator networks demanding single-source warranty continuity. Capital deferral economics drive 20-40 mil system specification over full membrane replacement on aging flat roof stock.
- Industrial:Facilities with chemical exposure and heavy mechanical traffic specify polyurethane and high-build silicone systems through direct specification.
- Residential:Homeowners and small contractors access acrylic maintenance products through retail roofing supply channels.
- Government:K-12 and municipal buildings require third-party reflectance retention data at 3-year intervals, tightening qualification windows.
Commercial captures the largest revenue pool. Government procurement shows the steepest specification tightening.
Application:
Application method determines crew certification requirements and seasonality constraints.
- New Construction:Specification-grade silicone and hybrid systems integrate into LEED-compliant building envelopes during original roof assembly.
- Repair:Spot applications address localized membrane failures on commercial portfolios.
- Restoration:Full-system overlays extend service life on metal and modified bitumen substrates facing capital replacement decisions.
- Maintenance:Recoating cycles sustain reflectance performance and warranty continuity on existing installations.
Restoration commands premium pricing per square foot. Maintenance generates recurring volume through cyclical recoating.
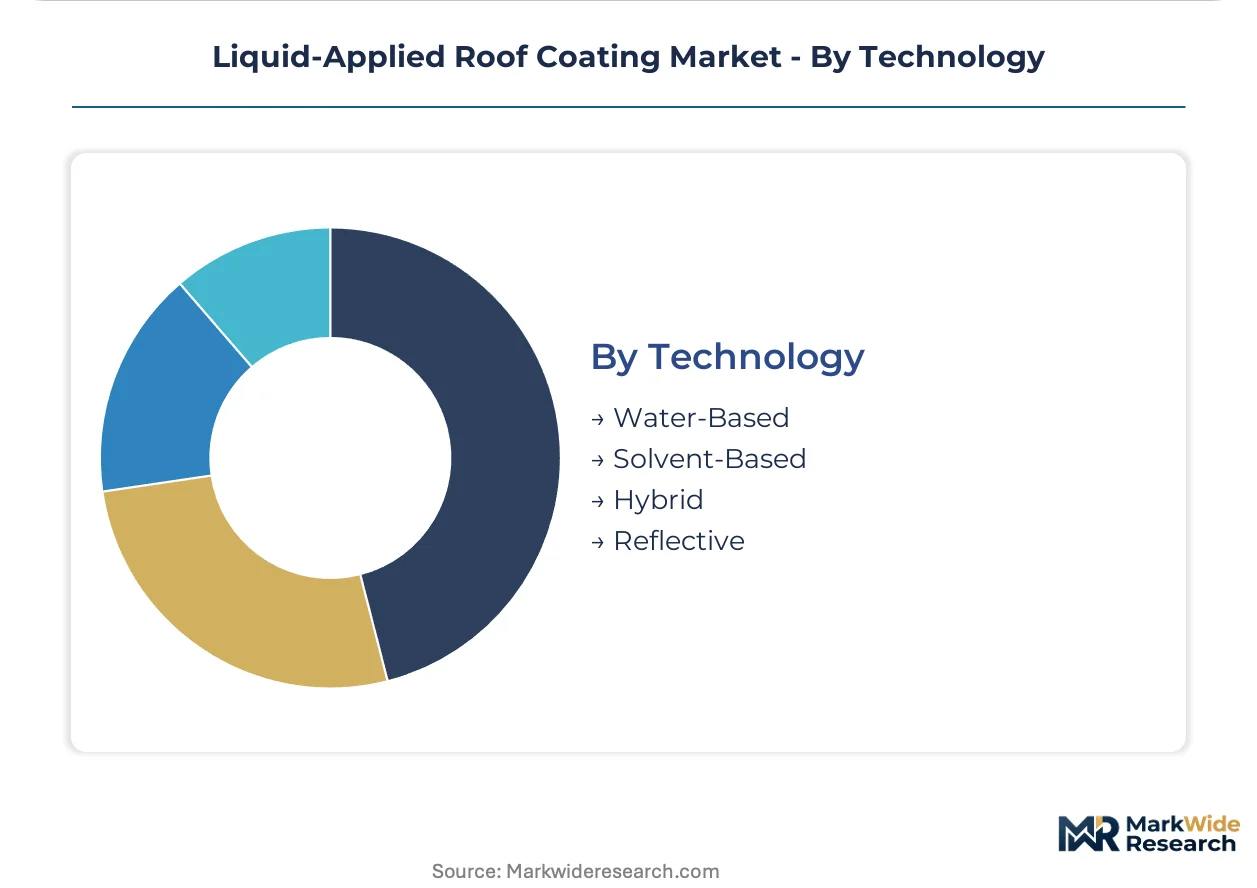
Technology:
Formulation chemistry channels through distinct regulatory compliance pathways.
- Water-Based:Low-VOC acrylic emulsions access LEED v4.1 low-emitting materials credits and municipal procurement preferences.
- Solvent-Based:Higher-solids bitumen and polyurethane systems face tightening VOC thresholds in California and Northeast jurisdictions.
- Hybrid:Silicone-acrylic combinations target intermediate performance positioning with balanced cost structures.
- Reflective:Titanium-dioxide-loaded and inorganic-pigment-stabilized formulations meet EPA ENERGY STAR steep-slope eligibility requirements.
Water-based systems dominate unit volume. Reflective technology is gaining share fastest on code-mandated cool-roof adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston's petrochemical corridor underwrites United States dominance in silicone intermediate supply chains, while Rotterdam's liquid bulk terminals anchor European formulation distribution across the Rhine basin.
United States
Commercial building stock aging past 20-year service life drives restoration demand across Sun Belt metropolitan areas. California Title 24 and ASHRAE 90.1 amendments in Texas, Florida, and Arizona mandate minimum solar reflectance thresholds for commercial reroofing. Dallas-Fort Worth and Phoenix concentrate specification-grade silicone procurement through manufacturer-certified applicator networks serving multi-site property portfolios.
Germany
Industrial facility renovation cycles and stringent energy efficiency targets for commercial building envelopes sustain polyurethane and silicone system demand. REACH regulation and the EU Green Deal's building renovation requirements tighten VOC thresholds and mandate performance documentation. The Rhine-Ruhr industrial corridor hosts formulation R&D clusters supplying high-solids systems across Central European markets.
China
Rapid urban commercial construction and government-mandated green building standards accelerate water-borne acrylic and silicone coating adoption. GB standards for building energy efficiency and provincial dual carbon implementation targets shape procurement specifications. The Yangtze River Delta manufacturing belt concentrates domestic production capacity serving both local restoration demand and export formulation supply.
India
Commercial real estate expansion and rising awareness of cooling-load reduction economics drive reflective coating specification in high-temperature zones. Bureau of Indian Standards certification requirements and state-level energy conservation building codes establish performance baselines for cool-roof materials. Maharashtra and Gujarat industrial corridors concentrate distributor networks supplying acrylic maintenance products to cost-sensitive maintenance contractors.
Australia
Severe UV exposure conditions and commercial roof asset management programs sustain premium silicone specification for service life extension. National Construction Code energy efficiency provisions and state-level sustainable building policies mandate thermal performance documentation. Sydney and Melbourne metropolitan areas concentrate certified applicator networks serving institutional and commercial portfolio managers.
Liquid-Applied Roof Coating Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and geographic coverage dimensions. The vendor base splits between multinational chemical conglomerates with integrated resin production and regional formulators focused on application-specific performance tiers. Three archetypes dominate: integrated resin-to-coating manufacturers, specification-grade formulators with captive testing facilities, and regional maintenance-product distributors. Competitive moves concentrate on FM Approval and UL certification acquisition to unlock commercial specification, and direct applicator network expansion to capture warranty-continuity revenue streams.
Within the integrated chemical conglomerate tier, Sika AG, BASF SE, and Dow Inc. occupy positions defined by backward control over silicone intermediate supply and transatlantic production footprints. These entities exemplify the certification-heavy specification-grade archetype through in-house fire-resistance and wind-uplift testing capabilities. Their geographic naming conventions—Swiss, German, and US corporate origins respectively—anchor their regional market presence without implying exclusive territorial focus.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Dow Inc. |
| Akzo Nobel N.V. |
| The Sherwin-Williams Company |
| PPG Industries |
| RPM International Inc. |
| GAF Materials |
| Johns Manville |
| Others |
Value Network & Pricing Analysis
FM Approval 4470 and UL 790 certification regimes gate both supply qualification and price differentiation simultaneously, compressing specification windows toward manufacturers with in-house testing capabilities while fragmenting the remainder into commodity tiers. This regulatory architecture concentrates pricing power among certified incumbents serving institutional procurement, while cost-sensitive maintenance segments trade through distributor channels on volume terms.
Pricing Analysis
Three-tier pricing structure across specification-grade, distributor-grade, and maintenance-grade levels separates warranty-backed silicone systems from commodity acrylics and spot-repair products. Certification depth and solar reflectance retention data drive price differentiation, with ENERGY STAR-eligible formulations commanding premiums over yellowing-prone legacy acrylics. Cost compression in water-borne tiers is intensifying because raw material volatility in silicone intermediates squeezes mid-tier polyurethane positioning. Residential maintenance contractors exhibit highest price sensitivity, while multi-site commercial property managers prioritize single-source warranty continuity over unit cost.
Supply Chain Analysis
Inventory lead times for silicone intermediates stretch 8-12 weeks from German and Chinese production clusters, exposing formulators to freight cost volatility and force majeure risk during regional energy disruptions. Raw material sourcing draws from petrochemical feedstocks in the US Gulf Coast, siloxane monomers in the Rhine-Ruhr corridor, and titanium dioxide pigments from eastern Chinese processing facilities. Single-source vulnerability concentrates in silicone resin supply, where three intermediate producers serve the North American formulation base. Distribution runs through manufacturer-certified applicator networks for specification-grade systems and traditional roofing supply houses for volume maintenance products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a certification-entrenchment defensive moat, where 18-24 month FM Approval and UL testing cycles create switching costs that freeze out mid-tier competitors and lock institutional procurement relationships.
For Market Incumbents: Consolidate specification-grade positioning by deepening captive silicone intermediate supply through backward integration into German or Chinese resin production, while expanding certified applicator networks in Sun Belt metropolitan areas to capture warranty-continuity revenue streams. Defend against emerging water-borne hybrid entrants by accelerating titanium-dioxide-loaded topcoat R&D to maintain ENERGY STAR eligibility thresholds.
For New Entrants and Emerging Players: UL 790 fast-track certification programs offer the most viable entry path for regional formulators targeting municipal heat island mitigation pilots in Chicago, New York, and Philadelphia, where accelerated permitting for high-reflectance installations opens specification windows historically dominated by black EPDM. White silicone base coats beneath photovoltaic arrays present a penetrable niche with specification pull-through from rooftop solar developers seeking operating temperature reduction.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicone-acrylic hybrid R&D pipelines as LEED v4.1 low-emitting materials credits reshape institutional procurement requirements. Acquisition targets should profile regional formulators with captive applicator networks in secondary Sun Belt metros, where labor scarcity constrains deployment velocity and creates consolidation value. Watch for state-level IECC and ASHRAE standard amendments as inflection signals that would recalibrate minimum thermal emittance requirements and reshape coating eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Fast-Track Investment | FM Approval 4470 and UL 790 testing cycles unlock commercial specification-grade positioning. |
| Backward Integration into Silicone Intermediates | German and Chinese resin production clusters reduce freight cost exposure and force majeure risk. |
| Certified Applicator Network Expansion | Sun Belt metropolitan areas concentrate multi-site property management procurement centralization. |
| Water-Borne Hybrid R&D Pipeline | LEED v4.1 low-emitting materials credits access premium institutional positioning. |
| Photovoltaic Integration Partnership | Rooftop solar developers specify white silicone base coats for operating temperature reduction. |
Research Methodology
Initial hypotheses were tested against primary input from commercial roofing contractors, building envelope consultants, municipal procurement officers, and manufacturer technical directors, and refined through secondary validation against customs trade data, SEC 10-K filings, EPA ENERGY STAR certification databases, and ASTM standard documentation. Bottom-up volume estimates from certified applicator network capacity and top-down market sizing from construction spending flows were triangulated to converge on segment-level figures.
Variance decomposition across the projection horizon isolates drivers by product type chemistry, end-user procurement tier, application method complexity, and regional regulatory cluster stringency. CAGRs were derived from segment-level growth rate blending weighted by base-year revenue shares, with inputs including California Title 24 amendment trajectories, utility rebate program expansion schedules, and commercial building stock aging curves.
Decision-makers should treat outputs as directional under assumptions of continued energy code tightening and stable silicone intermediate supply; material deviation through regulatory rollback or regional production disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Europe Metal Finishing Market
Coatings
Coating Pre-Treatment Market
Coatings
Physical Vapor Deposition (PVD) Coatings Market
Coatings
Acrylic Coating Market
Coatings
Polyvinylidene Fluoride (PVDF) Coatings Market
Coatings
Biopolymer Coatings Market
Coatings
Metallic Powder Coating Market
Coatings
Global Sputter Coatings Market
Coatings
Automotive Refinish Coatings Market
Coatings
Global Metal Coatings Market
Coatings
Mexico Floor Coatings Market
Coatings
Ultraviolet (UV) Coatings Market
Coatings
ASEAN Protective Coatings Market
Coatings
Gelcoat Market
Coatings
Canada Protective Coatings Market
Coatings
Topcoat Market