
 Global Polymer Market | 2026-2036
Global Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polymer Market Outlook
Saudi Arabia's mega-cracker complexes on the Gulf Coast is tilting low-cost polyethylene supply toward Asian converters. ExxonMobil Corporation leverages integrated upstream-downstream assets across the US Gulf Coast to sustain margin capture on specialty grades. INEOS AG anchors European olefin production through its Cologne-Rotterdam pipeline network. BASF SE differentiates via high-performance polyamide compounds for electric vehicle thermal management.
Polymers are macromolecular substances composed of repeating monomer units linked by covalent bonds, with molecular weights typically exceeding ten thousand daltons, synthesized through addition or condensation reactions. These materials function as structural and functional substitutes for metals, ceramics, and natural materials across industrial and consumer applications. Thermoplastics dominate volume flows due to reprocessability and recycling compatibility, while elastomers command premium positioning in sealing and vibration-dampening applications. Injection molding technology captures the largest share of conversion value, though blow molding retains structural importance in packaging throughput.
REACH registration requirements in Europe and FDA food-contact regulations in the United States constrain formulation freedom and elevate compliance costs for compounders serving regulated end uses. China's GB standards and dual carbon goals from MEE are tightening emissions benchmarks for virgin polymer production, favoring producers with carbon capture integration or bio-feedstock pathways. Stakeholders must monitor feedstock volatility between naphtha and ethane cracking economics while positioning for circularity mandates that will reshape virgin-capital allocation decisions.
Market Dynamics
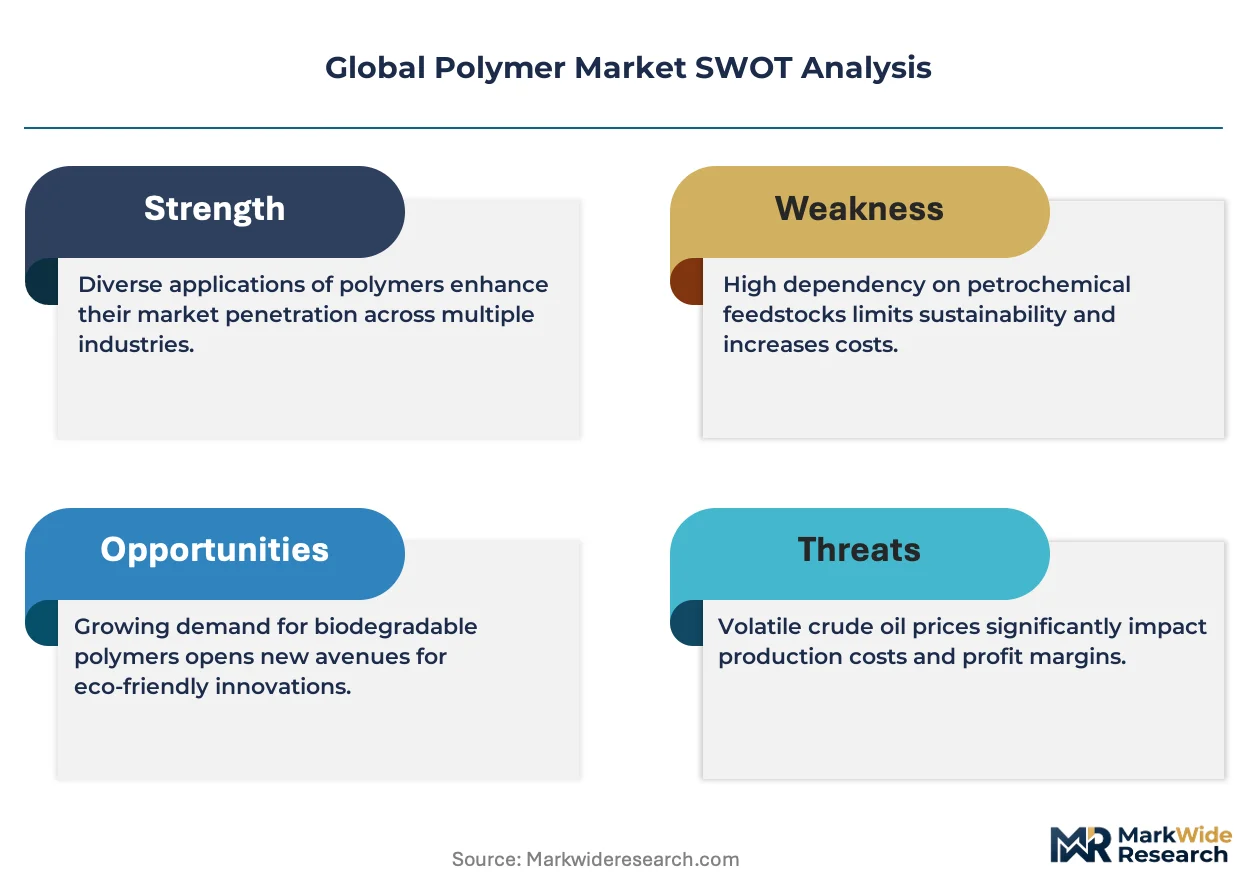
The polymer sector is undergoing a feedstock pivot as naphtha-ethane cracking economics diverge and carbon border adjustments penalize high-emission virgin production, forcing capital redeployment toward bio-based and recycled feedstock integration.
Growth Catalysts
- EU Green Deal mandates:Binding recycled content targets for packaging and automotive applications are pulling investment toward chemical recycling infrastructure and bio-polymer capacity expansion across European compounding facilities.
- Automotive lightweighting programs:Germany and Japan are accelerating engineered polymer substitution for metal components in battery enclosures and structural elements, with thermal management grades capturing priority specification slots.
- Yangtze River Delta concentration:China's petrochemical corridor is consolidating downstream converter demand, creating clustered offtake agreements that de-risk greenfield polymer investments through captive volume commitments.
Market Restraints
- Naphtha price volatility:Asian crackers dependent on liquid feedstock face margin compression when oil-linked naphtha spikes against US ethane-advantaged competitors, constraining pricing flexibility for commodity polyethylene grades.
- Saudi supply concentration:Gulf Coast mega-cracker complexes control low-cost polyethylene export volumes, creating single-source dependency risks for Asian converters without diversified feedstock hedging strategies.
- REACH registration friction:ECHA compliance timelines and data-sharing costs for novel polymer additives extend time-to-market for European compounders, favoring incumbents with existing substance dossiers.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic polymer compounding incentives are attracting capacity for electric vehicle connector housings and medical device components previously imported from ASEAN sources.
- Chemical recycling scale-up:Pyrolysis and depolymerization technology convergence with carbon capture integration is opening circular feedstock pathways that qualify for EU ETS exemptions and premium brand offtake contracts.
- Bio-based polyamide development:Castor oil-derived monomers and fermentation-based feedstocks are penetrating performance textile and automotive under-the-hood segments where scope-3 emissions face downstream customer audit.
Industry Challenges
- Polymer characterization skill scarcity:Rheology modeling and molecular weight distribution analysis for recycled feedstock qualification outpaces technical training pipeline output, creating bottlenecks at certification laboratories.
- Multi-standard compliance complexity:Simultaneous FDA food-contact, REACH SVHC, and China's GB standard adherence requires parallel testing protocols that extend formulation development cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polymer Market |
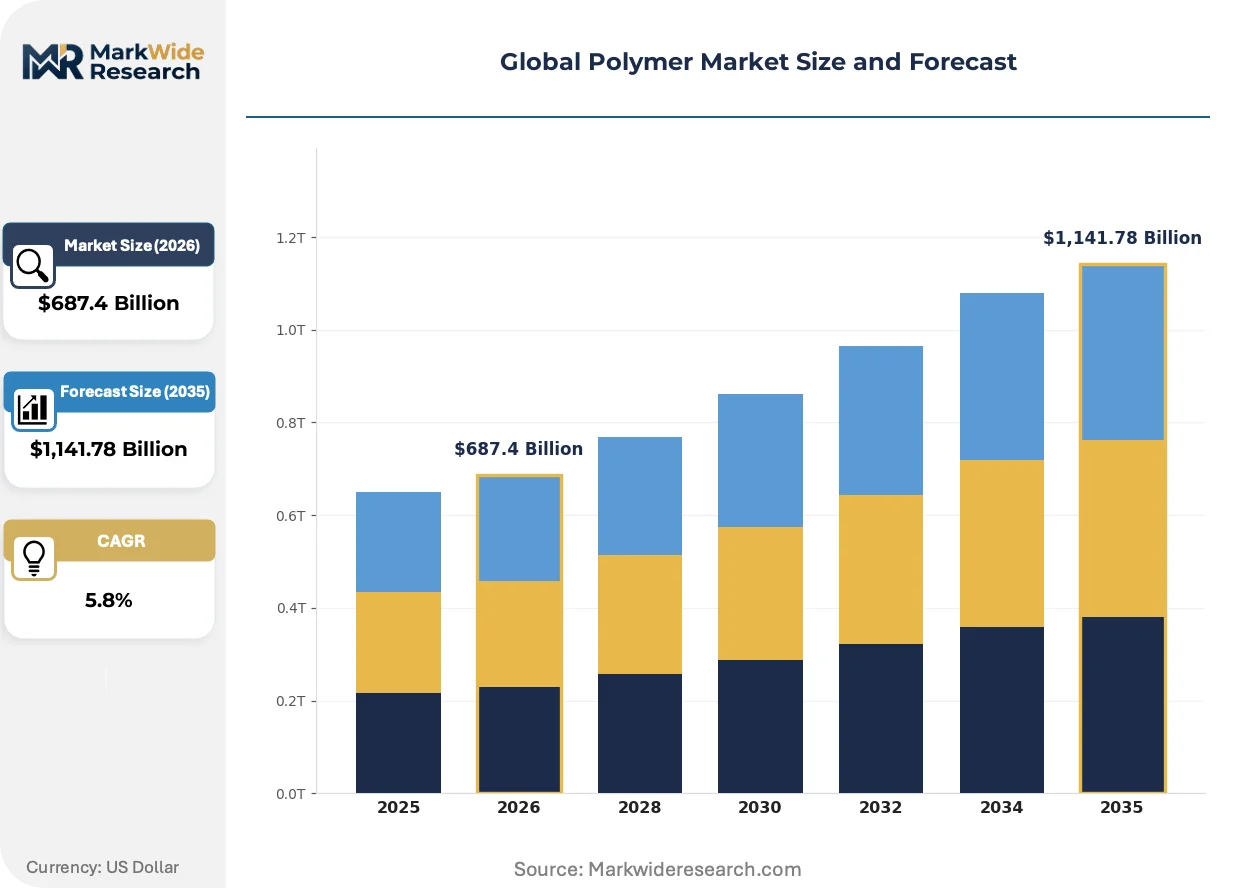
| Market Size in 2026 | $687.4 Billion |
| Market Size in 2035 | $1,141.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastics, Thermosetting Plastics, Elastomers, Blends End Use Industry: Automotive, Construction, Packaging, Consumer Goods Form: Powder, Granules, Sheets, Films Technology: Injection Molding, Extrusion, Blow Molding, Thermoforming |
| Companies Covered | ExxonMobil Corporation, INEOS AG, BASF SE, LG Chem, Evonik Industries AG, Dow Inc., LyondellBasell Industries N.V., Covestro AG, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polymer Market Strategic Shifts
Advanced recycling technologies and molecular design tools are compressing the performance gap between virgin and circular polymers, while regulatory carbon accounting is embedding emissions transparency into material specification workflows.
Enzymatic depolymerization of polyethylene terephthalate is rendering obsolete mechanical recycling's contamination-intolerance constraints. Beverage brand owners and textile spinners are piloting enzymatic routes at commercial scale in France and Japan. The technology is enabling food-grade rPET output from mixed-waste feedstocks previously downcycled into fiber applications.
REACH SVHC candidate list expansion is accelerating substitution of phthalate plasticizers and brominated flame retardants in European electrical housing and automotive interior compounds. Compounders are reformulating with bio-based plasticizers and phosphorus-nitrogen synergist systems to maintain UL94 ratings. Wire and cable segments face the steepest retooling costs due to legacy certification dependencies.
Automotive OEMs are unbundling material certification from volume supply agreements, forcing compounders to pre-qualify grades across multiple tier-1 molders without guaranteed offtake. This procurement fragmentation concentrates qualification spending on a shrinking pool of global resin suppliers with dedicated automotive technical service teams. The pattern is most pronounced in German and South Korean electric vehicle supply chains.
Global Polymer Market Segmentation
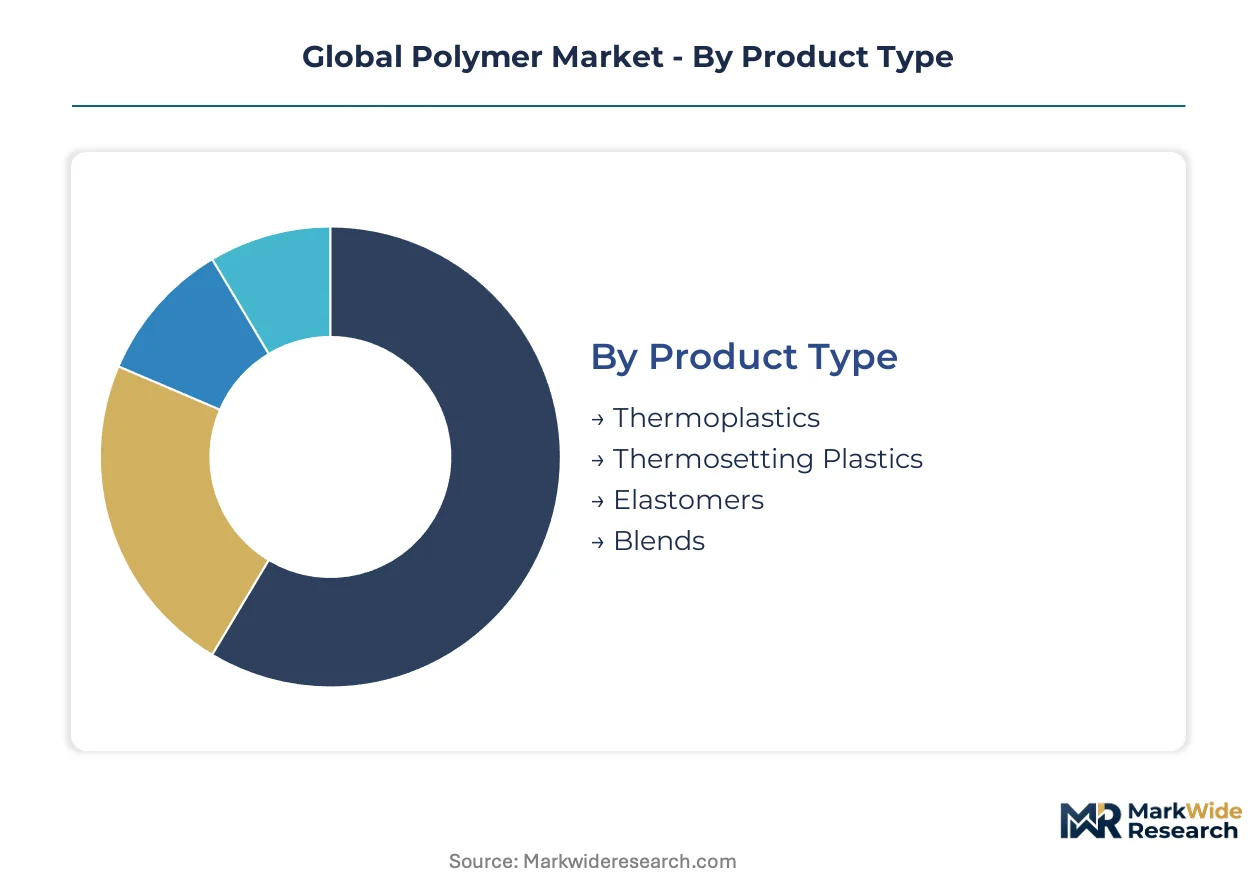
Segmentation reveals how polymer value migrates across technical specifications and conversion methods. Technical service intensity varies dramatically by form and processing technology, reshaping supplier-customer relationships.
Product Type:
After-sales technical support requirements differ sharply across polymer families, with engineering grades demanding sustained formulation assistance while commodity resins operate on transactional specifications.
- Thermoplastics:Linear or branched macromolecules soften reversibly upon heating, enabling reprocessing and mechanical recycling compatibility. Automotive battery enclosures in Germany and Japan specify flame-retardant polyamide and PBT compounds requiring thermal management validation. REACH SVHC restrictions on halogenated additives are accelerating reformulation service contracts.
- Thermosetting Plastics:Cross-linked networks formed through irreversible curing reactions deliver dimensional stability under thermal load. Epoxy and phenolic systems dominate electric motor insulation and semiconductor encapsulation where outgassing specifications from Japanese automotive OEMs mandate batch certification support.
- Elastomers:Cross-linked rubbery networks with glass transition temperatures below service range enable sealing and vibration isolation.
- Blends:Physical combinations of immiscible polymers achieve property synergies unavailable in single-resin systems.
By volume, thermoplastics lead. By growth pace, elastomers in electric vehicle sealing applications are expanding most quickly.
End Use Industry:
Application-specific certification burdens segment customer support costs, with automotive and medical end uses imposing the steepest compliance documentation requirements.
- Automotive:Structural and functional polymer substitution for metal components drives specification complexity. Battery enclosure grades from BASF and Covestro require simultaneous UL94 V-0, OEM-specific fogging tests, and crashworthiness validation. German KBA type-approval documentation extends compounder technical service obligations through vehicle platform life cycles.
- Construction:Pipe, insulation, and membrane applications demand long-term durability certification under varying climatic exposure. PVC pressure pipe compounds for China's Yangtze River Delta infrastructure projects require GB standard adherence plus MEE emissions documentation for carbon disclosure mandates.
- Packaging:Food-contact compliance and recyclability design dominate specification workflows.
- Consumer Goods:Aesthetic and tactile properties drive color-matching and surface finish technical support intensity.
Packaging commands the highest shipment volumes. Automotive engineered grades are gaining share fastest through electrification-driven material substitution.
Form:
Physical presentation determines logistics economics and converter equipment compatibility, with powder and granule formats requiring differentiated handling infrastructure investments.
- Powder:Fine particulate morphology enables rotational molding and coating applications where melt homogeneity depends on particle size distribution control. Rotomolded fuel tanks and agricultural tanks specify powder grades with narrow melt flow ranges, necessitating supplier quality certification support.
- Granules:Pelletized form dominates thermoplastic conversion through extrusion and injection molding. Bulk handling systems at Chinese Yangtze River Delta converter clusters favor granule formats with standardized bulk densities for pneumatic conveying optimization.
- Sheets:Flat extruded or calendered products serve thermoforming and fabrication workflows.
- Films:Thin-gauge extruded or cast products address packaging and membrane applications.
Granules lead by tonnage. Powder formats for rotational molding are climbing fastest in agricultural and industrial tank segments.
Technology:
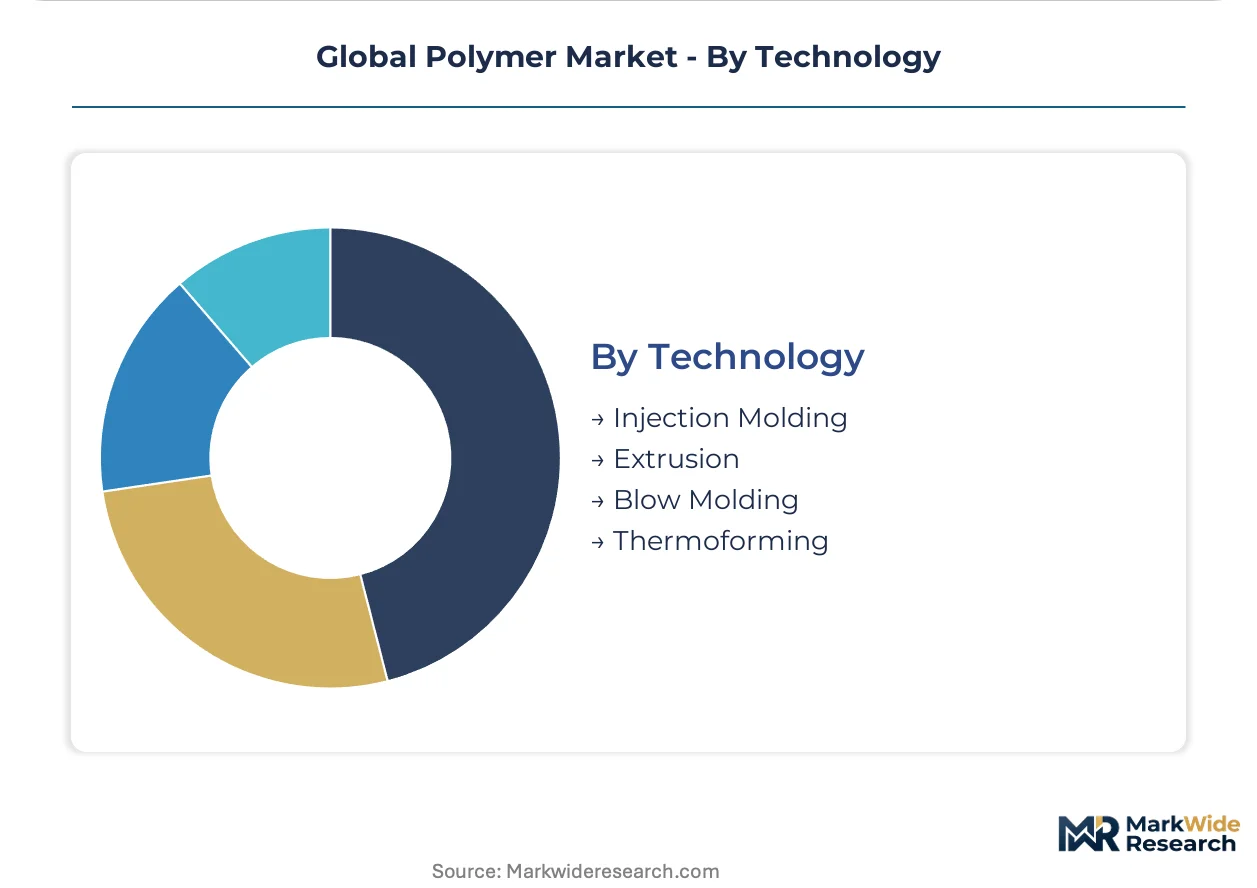
Conversion method selection locks in capital equipment requirements and cycle economics, with mold design and process optimization services representing the primary after-sales value capture mechanism.
- Injection Molding:High-pressure cavity filling enables complex geometry production with tight dimensional tolerances. Automotive connector housings and medical device components require rheology modeling support and gating optimization services from compounders with dedicated processing laboratories.
- Extrusion:Continuous profile and sheet production demands screw design and die flow balancing expertise. Pipe and profile converters in India's PLI-supported specialty chemicals corridors seek technical partnerships for multi-layer barrier structure development.
- Blow Molding:Parison inflation process dominates hollow packaging and fuel tank fabrication.
- Thermoforming:Sheet heating and vacuum/pressure forming serves shallow-draw packaging and industrial applications.
Injection molding captures the highest value per kilogram processed. Blow molding retains volume leadership in packaging throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE's dual carbon goals are redirecting capital flows across China's petrochemical corridors while REACH and EU Green Deal mandates reshape European compounding economics. Feedstock cost differentials between ethane-advantaged Gulf producers and naphtha-dependent Asian crackers are redrawing trade flows.
China
Automotive electrification and battery enclosure demand are pulling engineered polymer consumption toward the Yangtze River Delta. MEE emissions benchmarks and dual carbon goals favor producers with carbon capture integration or bio-feedstock pathways. Shanghai-Ningbo petrochemical clusters are consolidating downstream converter demand through captive volume commitments.
Germany
KBA type-approval documentation extends compounder technical service obligations through electric vehicle platform life cycles. EU Green Deal recycled content targets pull investment toward chemical recycling infrastructure across North Rhine-Westphalia. Cologne-Rotterdam pipeline networks anchor European olefin production for automotive thermal management grades.
United States
FDA food-contact regulations constrain formulation freedom for compounders serving regulated packaging end uses. ExxonMobil leverages integrated upstream-downstream assets across the Gulf Coast to sustain margin capture on specialty grades. Houston-Beaumont petrochemical complexes maintain ethane cost advantages over naphtha-dependent competitors.
Saudi Arabia
Gulf Coast mega-cracker complexes control low-cost polyethylene export volumes tilting supply toward Asian converters. SFDA and national industrial development programs support downstream diversification beyond commodity grades. Jubail industrial city clusters are expanding specialty chemical derivatives for automotive and construction applications.
Japan
METI automotive lightweighting programs accelerate engineered polymer substitution for metal components in battery enclosures. JIS standards and OEM-specific fogging tests impose batch certification requirements on epoxy and phenolic systems. Nagoya-Tokyo industrial corridors concentrate electric motor insulation and semiconductor encapsulation demand.
Global Polymer Market Competitive Environment
Capability concentration sits with integrated petrochemical majors possessing dedicated automotive technical service teams; scale advantage sits with Gulf-based ethane crackers commanding export volume leverage. The vendor base stratifies across three tiers: upstream-integrated majors with pipeline networks and cracker assets; regional compounders with formulation laboratories serving tier-1 molders; and specialized bio-polymer developers capturing EU ETS exemptions. Dominant competitive moves include backward integration into bio-feedstock cultivation and strategic partnerships for pyrolysis-based circular feedstock offtake.
Within the integrated major tier, ExxonMobil Corporation and BASF SE exemplify divergent geographic anchoring strategies. ExxonMobil's US Gulf Coast position leverages ethane cost structures against naphtha-dependent rivals. BASF SE occupies a European compounding position differentiated through high-performance polyamide qualification support. INEOS AG represents the pipeline-network archetype, with Cologne-Rotterdam infrastructure sustaining margin capture across commodity and specialty grades.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| INEOS AG |
| BASF SE |
| LG Chem |
| Evonik Industries AG |
| Dow Inc. |
| LyondellBasell Industries N.V. |
| Covestro AG |
| SABIC |
| Others |
Value Chain & Pricing Dynamics
Saudi Arabia's Gulf Coast mega-cracker complexes anchor low-cost polyethylene export volumes, concentrating margin capture at the upstream feedstock tier while Asian converters absorb naphtha-linked volatility. This upstream concentration funnels pricing power toward ethane-advantaged producers and fragments margin pools across differentiated European compounders.
Pricing Analysis
Geographic price spreads between US ethane-advantaged Gulf Coast producers and Asian naphtha-dependent crackers exceed sustained differentials seen in prior cycles. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales technical service intensity. Cost compression in commodity polyethylene grades is intensifying because Saudi export volumes tilt spot market liquidity. Tier-1 automotive molders exhibit lowest price sensitivity due to platform-specific qualification lock-in, while packaging converters in China's Yangtze River Delta clusters face highest sensitivity to resin cost swings.
Supply Chain Analysis
Extended payment terms from Asian converters are forcing European compounders to deploy supply-chain finance facilities to maintain working capital velocity. Feedstock sourcing concentrates in Saudi Arabia, the United States, and China, with naphtha and ethane cracking economics diverging sharply. Raw material dependencies center on crude oil derivatives, bio-based castor oil feedstocks, and pyrolysis-derived circular monomers. Single-source vulnerability risks emanate from Gulf Coast polyethylene export concentration. Distribution runs through pipeline networks in Europe, bulk vessel charters to Asia, and rail-tanker flows across North American converter clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for automotive battery enclosure qualification are expanding faster than base resin volumes, creating a service-attach opportunity that compounds lifetime customer value. This recurring-revenue layer rewards compounders with dedicated processing laboratories and OEM-specific certification capabilities.
For Market Incumbents: Build formulation moats around REACH-compliant additive systems that substitute halogenated flame retardants and phthalate plasticizers. Secure backward integration into bio-feedstock cultivation or pyrolysis-based circular feedstock offtake to defend against carbon border adjustment pressures. Anchor capacity expansion in India's PLI-supported specialty chemicals corridors to capture electric vehicle connector housing demand migrating from ASEAN sources. For New Entrants and Emerging Players: Pursue white-space positioning in enzymatic depolymerization technology deployment for food-grade rPET output from mixed-waste feedstocks previously downcycled. Target India's domestic compounding incentives for medical device components and electric vehicle applications where import substitution creates penetrable demand. Lead with carbon capture integration or fermentation-based monomer pathways to qualify for EU ETS exemptions and premium brand offtake contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chemical recycling infrastructure and bio-polymer capacity expansion. Long-term viability over the next decade favors targets with existing REACH substance dossiers and dedicated automotive technical service teams rather than commodity resin exposure. Watch for pyrolysis technology convergence with carbon capture integration as the inflection signal for circular feedstock pathway economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Feedstock Cultivation | Castor oil-derived monomers from dedicated agricultural partnerships secure scope-3 emissions compliance for EU automotive specifications. |
| Chemical Recycling Capacity Expansion | Pyrolysis and depolymerization scale-up qualifies output for EU ETS exemptions and premium brand offtake contracts. |
| Long-term Supply Agreement with Yangtze River Delta Clusters | Captive volume commitments from Chinese converter clusters de-risk greenfield polymer investments through demand visibility. |
| Joint Venture for Automotive Thermal Management Grades | BASF and Covestro partnerships with German OEMs concentrate qualification spending on pre-certified compound portfolios. |
| Green Manufacturing Transition with Carbon Capture Integration | MEE dual carbon goals favor Chinese producers with emissions documentation for virgin polymer production benchmarks. |
Study Parameters
A spread of perspectives from polymer plant managers, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors converged on the working assumptions shaping this analysis. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH registration databases. Bottom-up volume modeling across product types, end-use industries, and regional production hubs triangulated with top-down macroeconomic indicators.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeling spanning thermoplastic grades, conversion technologies, and automotive electrification content per vehicle. CAGRs derived from historical trajectory analysis and forward-looking capacity expansion announcements incorporated feedstock cost differentials between naphtha and ethane cracking economics. Industry-specific inputs included MEE emissions benchmarks, EU Green Deal recycled content targets, and automotive platform lifecycle documentation requirements.
Sensitivities concentrate around feedstock price volatility, carbon border adjustment implementation timelines, and enzymatic depolymerization technology scale-up rates. Forecasts reflect assumptions on regulatory enforcement intensity and circular feedstock pathway commercialization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Paste PVC Resin Market
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
Epoxy Casting Potting Resin Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
Medical Grade Liquid Crystal Polymer Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
Homopolymer Resins Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
Ethylene Acrylic Acid (EAA) Copolymers Market
Polymers & Resins
North America Thermoplastics Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
Polypropylene and High-Impact Polystyrene Market
Polymers & Resins
Global Acrylic Polymer Market