
 Marine Nanocoating Market | 2026-2036
Marine Nanocoating Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Nanocoating Market Insights
Self-healing polymer networks and graphene-enhanced matrices is tilting marine coating formulations toward multi-functional, single-layer systems that combine corrosion inhibition with drag reduction. Nippon Paint Marine Coatings dominates Asian shipyard supply through captive technical service teams embedded at major build sites. Tesla NanoCoatings leverages its electrochemical deposition expertise to serve offshore platform operators in the Gulf of Mexico. Nanovere Technologies anchors North American distribution through direct relationships with naval defense contractors requiring ITAR-compliant supply chains.
Marine nanocoatings constitute thin-film surface treatments, typically 50–500 nanometers in thickness, engineered from ceramic oxides, fluoropolymers, or hybrid organic-inorganic matrices via sol-gel or chemical vapor deposition processes; these films create superhydrophobic or omniphobic barriers that block chloride ion ingress, biofilm adhesion, and ultraviolet degradation on submerged and atmospheric marine surfaces. Ceramic-based formulations command premium positioning due to their thermal stability and extended service intervals in ballast tank applications. Sol-gel technology leads deposition method adoption because of ambient-temperature processing compatibility with large hull sections. Anti-fouling applications attract the fastest formulation innovation as International Maritime Organization vessel performance standards tighten biocide discharge limits.
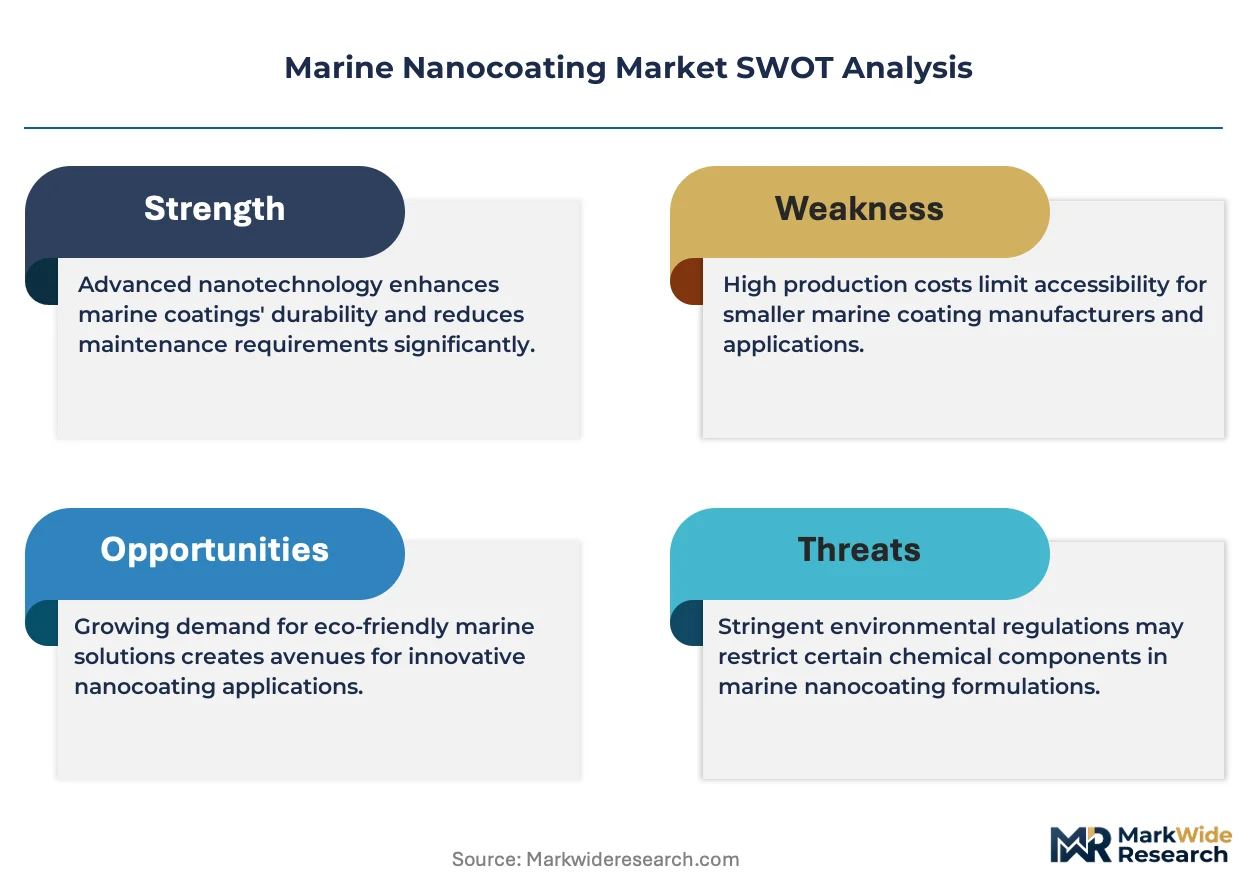
The International Maritime Organization, the EPA under the Clean Water Act Vessel General Permit, and the EU REACH Regulation collectively restrict tributyltin and copper-based biocide release, directly redirecting R&D investment toward silicone-based and hybrid nanocoating platforms. Classification societies including DNV and Lloyd's Register now incorporate coating performance durability into vessel carbon intensity ratings, tightening product qualification pathways. Stakeholders must monitor evolving port-state enforcement of biofouling management standards and pre-position compliant coating portfolios before mandatory in-water cleaning prohibitions expand.
Market Dynamics
Marine nanocoating development pivots on tightening International Maritime Organization biocide discharge limits, which compress formulation cycles and redirect R&D toward silicone-based and hybrid platforms that eliminate copper tributyltin entirely.
Growth Catalysts
- EU Green Deal maritime emissions targets:Vessel operators in Hamburg and Bremerhaven face carbon intensity rating pressure, accelerating dry-dock conversion to low-VOC nanocoating systems.
- Sol-gel ambient-temperature processing:Large hull section compatibility at Asian shipyards eliminates thermal curing bottlenecks, shortening newbuild coating windows.
- Commercial shipping fleet fuel economics:Anti-fouling nanocoatings reduce drag coefficients measurably, cutting bunker consumption and extending between-dock intervals for container operators.
Market Restraints
- Raw material concentration in ceramic oxide supply:Specialty alumina and silica precursor production clusters in Chinese industrial zones, exposing formulators to export control volatility.
- REACH registration cost burden:Novel nanomaterial substance dossiers require toxicological data packages exceeding €200,000 per formulation, freezing SME participation.
- Performance validation timelines:DNV and Lloyd's Register seawater immersion testing protocols demand 36-month exposure cycles before type approval.
Strategic Opportunities
- Offshore platform asset integrity:Gulf of Mexico operators seek electrochemical deposition expertise for subsea structural protection beyond conventional epoxy limits.
- Naval defense ITAR-compliant supply chains:North American contractors require domestic nanocoating sources for classified vessel programs, creating captive procurement relationships.
- Ballast tank thermal stability requirements:Ceramic-based formulations command premium positioning where service intervals exceed fifteen years.
Industry Challenges
- Formulation chemist scarcity:Hybrid organic-inorganic matrix design requires rare expertise spanning polymer science and marine corrosion electrochemistry.
- Port-state biofouling enforcement fragmentation:In-water cleaning prohibitions vary by jurisdiction, complicating fleet-wide compliance strategies for multinational operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Nanocoating Market |
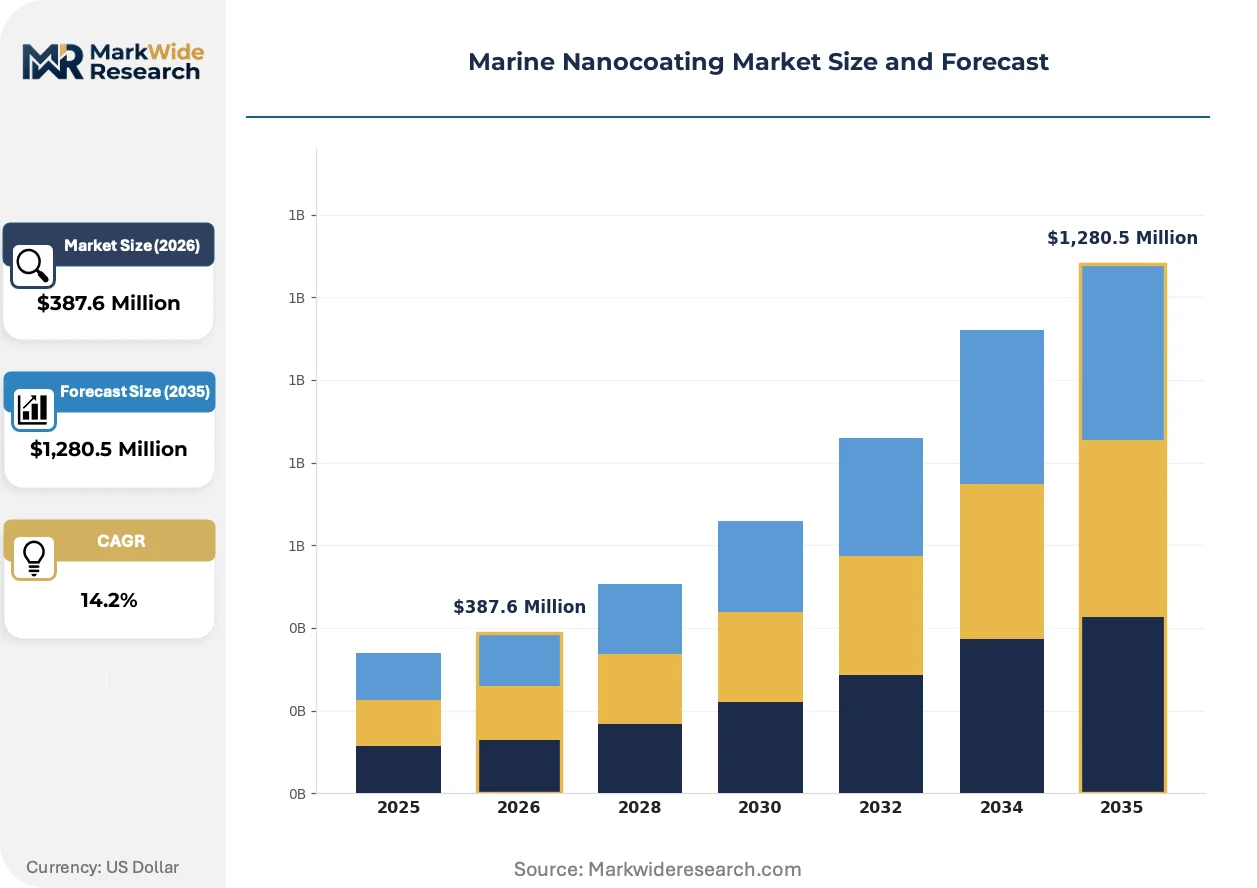
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone-Based, Ceramic-Based, Polymeric, Fluoropolymer, Hybrid Nanocoatings Technology: Sol-Gel, Layer-by-Layer Assembly, Chemical Vapor Deposition, Plasma Polymerization, Electrochemical Deposition Application: Corrosion Protection, Anti-Fouling, Ultraviolet Resistance, Ice Resistance, Self-Cleaning End User: Shipbuilders, Boat Repair Facilities, Offshore Structures, Naval Defense, Commercial Shipping |
| Companies Covered | Nippon Paint Marine Coatings, Nanovere Technologies, Tesla NanoCoatings, IGL Coatings, Guangzhou Sysmyk New Material Technology, Marine NanoTech, OxoChem, Vetro Power, Nasiol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Nanocoating Market Trends and Innovations
Formulation science is converging toward multi-functional single-layer systems that collapse previously separate corrosion inhibition and drag reduction treatments into unified deposition processes.
Graphene-enhanced polymer networks are digitizing coating performance monitoring through embedded conductivity sensors that transmit real-time hull condition data to shore-based analytics platforms. Offshore platform operators in the Gulf of Mexico pilot these systems for predictive maintenance scheduling. The structural consequence is digitizing asset integrity management from calendar-based dry-docking to condition-triggered intervention models.
EPA Clean Water Act Vessel General Permit revisions tighten copper discharge thresholds for vessels operating in US territorial waters. Coating manufacturers reformulate biocide-free silicone elastomer topcoats to maintain fouling release without biocidal mechanisms. Commercial shipping fleets serving trans-Pacific routes face the steepest compliance ramps as California port authorities enforce pre-arrival hull inspection mandates.
Shipyard procurement departments unbundle coating application from material supply, contracting directly with nanocoating formulators while retaining separate applicator relationships. Japanese newbuild yards lead this separation, negotiating technical service embedding separately from product procurement. The shift is most pronounced in Germany's Hamburg-Bremerhaven cluster where shipowners demand direct formulation traceability for carbon intensity certification.
Marine Nanocoating Market Segmentation
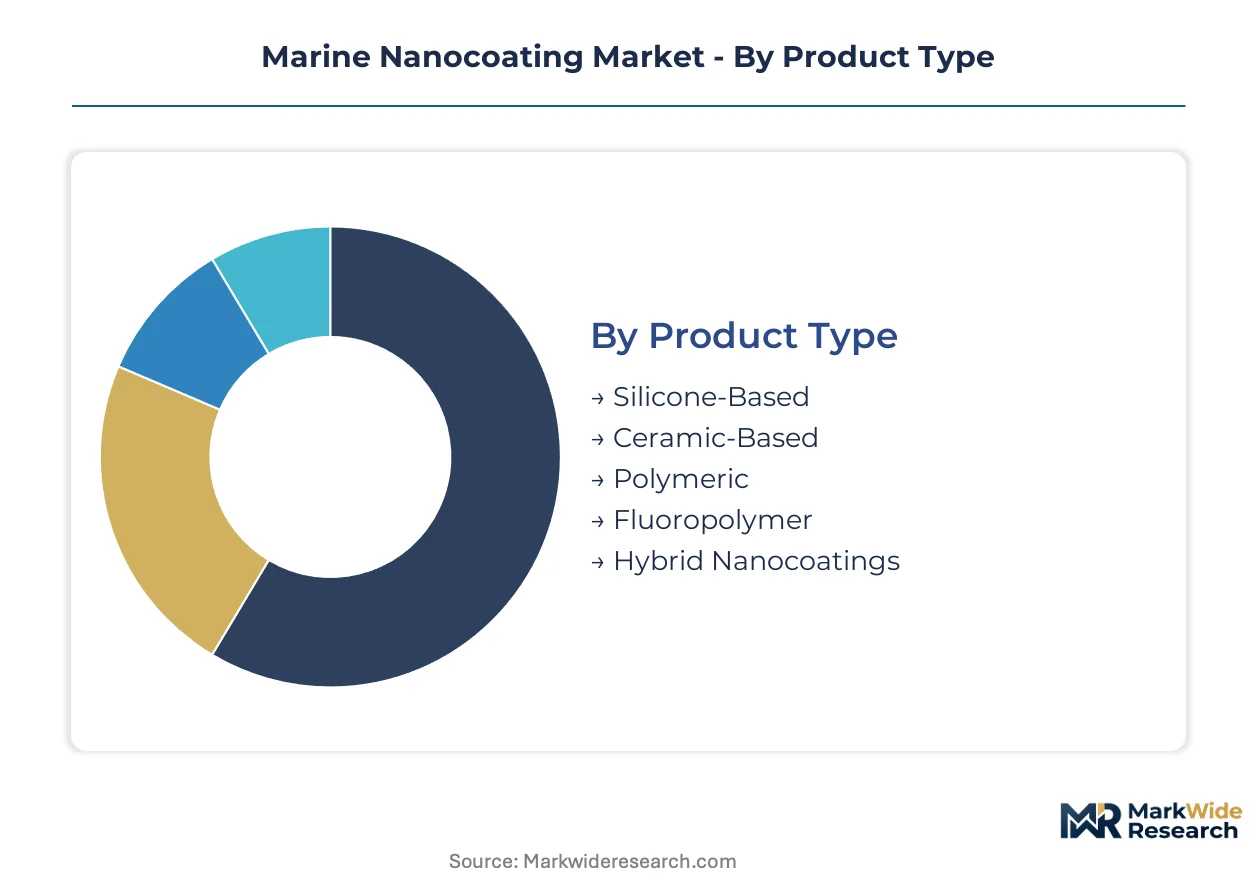
Marine nanocoating procurement decisions diverge sharply across vessel lifecycle stages, with newbuild specifications favoring integrated coating systems while dry-dock maintenance drives spot-application technologies. Segment boundaries blur as multi-functional formulations collapse corrosion, fouling, and UV protection into single-layer depositions.
Product Type:
Replacement cycles stretch from five-year hull recoating intervals to fifteen-year ballast tank ceramic installations, creating divergent inventory and technical service models across formulation categories.
- Ceramic-Based:Alumina-silica matrices deliver thermal stability exceeding 400°C for engine exhaust stacks and ballast tank internals. German shipyards in Hamburg specify these formulations for LNG carrier cargo containment systems where service intervals must span entire charter periods. REACH registration costs concentrate supply among large chemical conglomerates with dedicated nanomaterial dossier teams.
- Silicone-Based:Elastomeric foul-release surfaces eliminate biocide discharge through mechanical action rather than chemical toxicity. California port authorities enforce pre-arrival hull inspection mandates that accelerate silicone adoption on trans-Pacific container routes. EPA Vessel General Permit copper thresholds tighten each revision, redirecting formulation R&D toward silicone platforms.
- Hybrid Nanocoatings:Organic-inorganic matrices combine sol-gel ceramic durability with polymer flexibility for dynamic hull sections.
- Fluoropolymer:Perfluorinated chains create omniphobic barriers for superyacht atmospheric surfaces requiring UV stability.
- Polymeric:Acrylic and epoxy nanocomposites serve budget-sensitive fishing fleet operators in Mediterranean repair yards.
Ceramic-based formulations anchor the volume base in long-service ballast applications while silicone-based systems gain share at the steepest rate under tightening biocide discharge regimes.
Technology:
Capital intensity separates ambient-temperature deposition methods compatible with outdoor shipyard conditions from vacuum-chamber processes restricted to component-level manufacturing.
- Sol-Gel:Hydrolysis-condensation reactions deposit ceramic-oxide films at 20-80°C, eliminating thermal curing infrastructure for hull sections exceeding 300 meters. Asian newbuild yards in South Korea and Japan deploy mobile spray rigs that accelerate coating windows during monsoon season construction schedules. The method dominates anti-fouling application where film thickness uniformity directly impacts drag coefficients.
- Electrochemical Deposition:Controlled potential electrolysis builds dense, adherent ceramic layers on complex subsea geometries inaccessible to spray application. Gulf of Mexico offshore platform operators specify this method for structural nodes and riser joints where mechanical damage risk exceeds conventional epoxy limits. Tesla NanoCoatings maintains captive technical teams at Port Fourchon supply bases.
- Chemical Vapor Deposition:Gas-phase precursor reactions require vacuum chambers limiting application to small components and sensors.
- Plasma Polymerization:Ionized monomer deposition creates pinhole-free barriers for electronics enclosures and navigation equipment.
- Layer-by-Layer Assembly:Sequential polyelectrolyte adsorption enables nanometer-precise thickness control for research vessels requiring optical clarity.
Sol-gel processing commands the installed equipment base while electrochemical deposition expands most quickly in offshore asset integrity contracts.
Application:
Performance validation timelines stretch from 12-month accelerated weathering for UV resistance claims to 36-month seawater immersion for anti-fouling type approval, segmenting qualification pathways.
- Anti-Fouling:Foul-release and biocide-free surfaces reduce hull roughness penalties that cost container operators millions in annual bunker consumption. International Maritime Organization vessel performance standards tighten biofouling management requirements, compressing between-dock intervals for non-compliant fleets. Classification society carbon intensity ratings now incorporate coating condition assessments.
- Corrosion Protection:Chloride ion barrier films extend steel service life in splash zones and ballast tanks where cyclic wetting accelerates pitting. Offshore structure operators in the Gulf of Mexico prioritize these applications given replacement costs for subsea production hardware. DNV and Lloyd's Register incorporate coating durability into vessel inspection regimes.
- Ultraviolet Resistance:Transparent ceramic topcoats protect superstructure coatings from photodegradation in tropical latitudes.
- Ice Resistance:Low-surface-energy formulations reduce ice accretion on fishing vessels and Arctic supply ships.
- Self-Cleaning:Photocatalytic titanium dioxide surfaces decompose organic contaminants on yacht atmospheric surfaces.
Corrosion protection anchors the revenue base in offshore capital equipment while anti-fouling climbs the fastest on regulatory pressure and fuel economics.
End User:
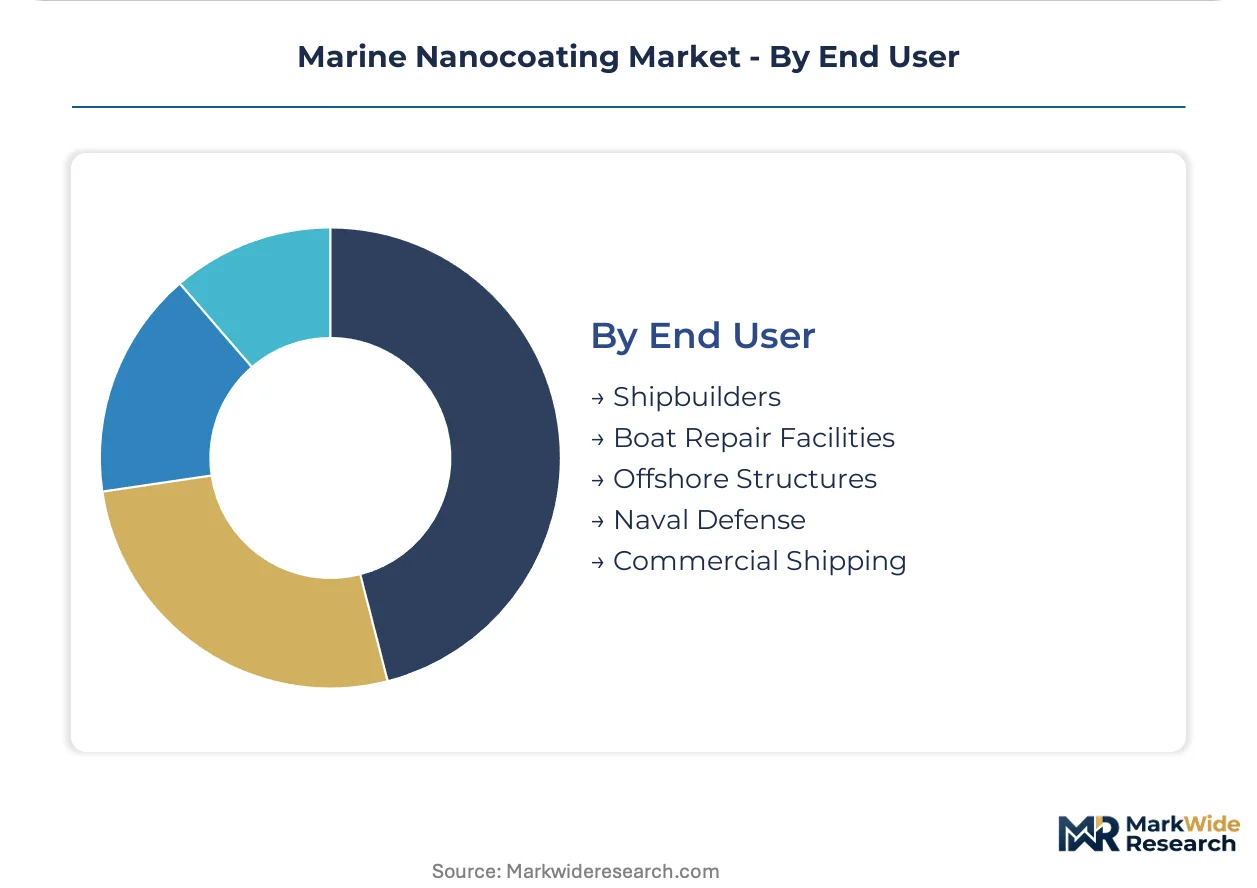
Procurement authority fragmentation separates shipyard newbuild specifications from fleet operator maintenance decisions, creating dual-channel sales complexity.
- Commercial Shipping:Container, tanker, and bulk carrier operators quantify coating ROI through fuel consumption deltas and dry-dock interval extensions. EU Green Deal maritime emissions targets concentrate demand in Hamburg and Bremerhaven where carbon intensity ratings determine port fee structures. Fleet managers unbundle coating supply from shipyard application contracts to secure direct formulation traceability.
- Naval Defense:Classified vessel programs require ITAR-compliant supply chains with domestic manufacturing and cleared personnel. Nanovere Technologies maintains direct relationships with US Navy procurement offices for submarine and surface combatant applications. Security clearance requirements create captive supplier relationships resistant to price competition.
- Shipbuilders:Japanese and South Korean newbuild yards negotiate technical service embedding separately from product procurement.
- Boat Repair Facilities:Mediterranean and Caribbean yacht service centers drive seasonal demand spikes for cosmetic refinishing.
- Offshore Structures:Platform operators in the Gulf of Mexico seek electrochemical deposition expertise for subsea asset integrity beyond diver-accessible limits.
Commercial shipping anchors the volume base in anti-fouling consumption while naval defense gains share at the steepest rate on security-driven supply chain requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial shipping operators and naval procurement offices concentrate demand across four distinct national markets, each shaped by local regulatory enforcement and shipyard infrastructure.
Germany
Hamburg and Bremerhaven anchor Europe's largest ship repair and newbuild cluster, where EU Green Deal maritime emissions targets accelerate dry-dock conversion to low-VOC nanocoating systems. REACH registration requirements for novel nanomaterials exceed €200,000 per formulation, freezing SME participation and consolidating supply among large chemical conglomerates. Fleet operators in these port cities unbundle coating supply from shipyard application contracts to secure direct formulation traceability for carbon intensity certification.
United States
EPA Clean Water Act Vessel General Permit revisions tighten copper discharge thresholds for vessels operating in US territorial waters, redirecting formulation R&D toward biocide-free silicone platforms. Offshore platform operators in the Gulf of Mexico seek electrochemical deposition expertise for subsea asset integrity beyond conventional epoxy limits. Naval defense contractors require ITAR-compliant supply chains with domestic manufacturing and cleared personnel for classified vessel programs.
Japan
Japanese newbuild yards lead procurement unbundling, negotiating technical service embedding separately from product procurement. METI standards for marine coating durability influence classification society protocols across Asia-Pacific. South Korean and Japanese shipyards deploy mobile sol-gel spray rigs that accelerate coating windows during monsoon season construction schedules.
South Korea
Asian newbuild yards in South Korea favor sol-gel ambient-temperature processing for large hull sections exceeding 300 meters, eliminating thermal curing infrastructure bottlenecks. DNV and Lloyd's Register seawater immersion testing protocols demand 36-month exposure cycles before type approval, compressing between-dock intervals for non-compliant fleets. Container operators quantify coating ROI through fuel consumption deltas and dry-dock interval extensions.
China
Specialty alumina and silica precursor production clusters in Chinese industrial zones, exposing formulators to export control volatility. MEE environmental standards for marine coating emissions tighten in parallel with international biocide discharge limits. Guangzhou-based material technology firms serve domestic shipbuilding demand while navigating dual carbon goals for industrial decarbonization.
Marine Nanocoating Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that fragments between captive technical service teams and independent formulation suppliers. Large chemical conglomerates with dedicated nanomaterial dossier teams consolidate ceramic-based supply under REACH cost pressure, while regional specialists embed directly at major build sites. Three archetypes dominate: integrated coating-applicator hybrids, pure-play nanomaterial formulators, and electrochemical deposition specialists. Competitive moves concentrate on technical service embedding contracts and geographic expansion through port-proximate supply bases.
Within the integrated service tier, Nippon Paint Marine Coatings exemplifies the Asian shipyard supply model through embedded technical teams at major build sites. Tesla NanoCoatings occupies a position among electrochemical deposition specialists serving offshore platform operators in the Gulf of Mexico. Nanovere Technologies anchors the naval defense procurement vector through ITAR-compliant supply relationships with North American contractors. These three firms represent distinct competitive positioning archetypes without implying specific market share or financial performance claims.
| Leading Market Players |
|---|
| Nippon Paint Marine Coatings |
| Nanovere Technologies |
| Tesla NanoCoatings |
| IGL Coatings |
| Guangzhou Sysmyk New Material Technology |
| Marine NanoTech |
| OxoChem |
| Vetro Power |
| Nasiol |
| Others |
Pricing and Supply Chain Analysis
Specialty alumina and silica precursor production clusters in Chinese industrial zones concentrate upstream supply, concentrating margin pools among REACH-registered formulators with dossier capabilities and freezing SME participation under €200,000 substance registration burdens.
Pricing Analysis
Cost-plus contracts with ceramic oxide indexation dominate procurement between formulators and shipyard operators, with pricing stratifying across ITAR-certified, classification-society-approved, and uncertified formulation tiers. REACH registration costs and 36-month DNV immersion testing protocols differentiate premium tiers from standard offerings. Price erosion runs through uncertified silicone-based supply as California port enforcement accelerates biocide-free conversion. Commercial shipping fleets exhibit highest price sensitivity due to bunker-cost ROI calculations, while naval defense contractors accept premiums for ITAR-compliant domestic sourcing.
Supply Chain Analysis
Export control volatility around Chinese specialty ceramic precursor flows constrains formulator procurement flexibility, with supply concentration in Jiangsu and Shandong provinces feeding global sol-gel production. Formulation draws from alumina nanoparticles, silica sols, and graphene additives as critical inputs. Single-source vulnerability persists in electrochemical deposition electrolyte supply for Gulf of Mexico offshore applications. Distribution runs through technical service embedding contracts at major Asian and German shipyard clusters, with direct procurement relationships increasingly unbundling material supply from application services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through REACH nanomaterial dossiers and 36-month classification society approval cycles creates formidable defensive moats, with incumbent formulators leveraging sunk certification costs to resist displacement.
For Market Incumbents: Insulate market position by deepening captive technical service teams at Hamburg-Bremerhaven and Asian shipyard clusters to lock in unbundled procurement relationships. Accelerate backward integration into ceramic precursor supply to mitigate Chinese export control exposure. Prioritize graphene-enhanced formulation R&D to extend performance differentiation beyond commodity silicone platforms.
For New Entrants and Emerging Players: Build out electrochemical deposition capabilities targeting Gulf of Mexico offshore platform operators, where subsea asset integrity requirements exceed conventional epoxy limits and Tesla NanoCoatings maintains limited presence. Target naval defense ITAR-compliant supply chains as the most penetrable segment, exploiting security clearance bottlenecks that constrain incumbent capacity expansion. Pursue direct contracting relationships with North American defense procurement offices rather than shipyard channel competition.
For Investors and Strategic Acquirers: Capital is best deployed toward formulators with existing REACH dossiers and classification society type approvals, where regulatory entrenchment compounds switching-cost advantages over the projection horizon. Acquisition candidates should demonstrate embedded technical service contracts at priority shipyard clusters. Watch for EPA Vessel General Permit copper threshold tightening as the signal indicating accelerated biocide-free formulation conversion and premium pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Precursors | Captive alumina-silica supply mitigates Chinese export control volatility for REACH-registered formulators. |
| Technical Service Embedding Contracts | Direct shipyard relationships in Hamburg and Bremerhaven secure formulation traceability for carbon intensity certification. |
| Graphene-Enhanced Formulation Development | Embedded conductivity sensors enable predictive maintenance contracts with Gulf of Mexico offshore operators. |
| ITAR-Compliant Supply Chain Certification | Cleared personnel and domestic manufacturing unlock naval defense procurement relationships resistant to price competition. |
| Silicone Platform R&D Expansion | Biocide-free foul-release coatings align with EPA Vessel General Permit tightening and California port enforcement. |
Research Methodology
Operator-level perspectives from shipyard procurement directors, fleet technical managers, offshore platform asset integrity engineers, and naval defense supply chain officers anchored the qualitative base. Primary interview findings triangulated against customs trade data for ceramic precursor flows, DNV and Lloyd's Register type approval registries, EPA Vessel General Permit revision documentation, and SEC filings from listed chemical conglomerates. Bottom-up vessel fleet coating demand estimates reconciled with top-down formulation manufacturer revenue analysis across the projection horizon.
Scenario-bracketing framed volume and value outputs across product type, technology method, application segment, and end-user category dimensions. Modeled segmentation captured ceramic-based, silicone-based, hybrid, fluoropolymer, and polymeric formulation tiers against sol-gel, electrochemical deposition, and chemical vapor deposition technology splits. Anti-fouling, corrosion protection, and UV resistance application demand curves derived from fuel economics modeling and regulatory compliance cost analysis. CAGRs computed from annual progression rates between base and terminal year values, with fleet expansion schedules and port-state enforcement timelines as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive technical service expansion or precursor supply acquisitions by REACH-registered majors would shift competitive dynamics. Material shifts in EPA copper discharge thresholds, EU Green Deal implementation pace, or Chinese ceramic precursor export licensing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
United Arab Emirates Floor Coatings Market
Coatings
Stealth Coating Material Market
Coatings
Global Sputter Coater Market
Coatings
Global Pipe Coatings Market
Coatings
Vacuum Coating Machine Market
Coatings
Coating Auxiliaries Market
Coatings
Water-Based Alkyd Coatings Market
Coatings
Global Polytetrafluoroethylene (PTFE) Coatings Market
Coatings
United States Floor Coatings Market
Coatings
Food Grade Ceramic Coatings Market
Coatings
Extrusion Coating Market
Coatings
Europe Super Hydrophobic Coatings Market
Coatings
Canada Protective Coatings Market
Coatings
Global Metal Coatings Market
Coatings
Thermal Barrier Coatings Market
Coatings
Packaging Coatings Market