
 Coatings and Fillings Market | 2026-2036
Coatings and Fillings Market Size, Share, and Industry Trends Forecast 2026-2036
Coatings and Fillings Market Analysis
Specialty ingredient distribution is narrowing as consolidated food manufacturers demand direct technical partnerships from suppliers. Cargill, Incorporated leverages its global oilseed processing network to secure captive supply of coating fats for chocolate and confectionery applications. Barry Callebaut AG anchors its position through backward integration into cocoa sourcing and bean-to-bar processing capabilities. Kerry Group plc differentiates by embedding taste and nutrition science directly into customer co-development programs.
Coatings and fillings comprise formulated layers and interior compositions applied to enhance protection, appearance, flavor, texture, or structural integrity in finished goods, typically involving controlled viscosity between 500 and 15,000 centipoise and precise thermal stability parameters. Acrylic formulations dominate architectural and decorative applications due to their UV resistance and water-borne compatibility, while polyurethane systems command premium positioning in automotive and aerospace for abrasion resistance and chemical tolerance. Powder coatings represent the fastest-expanding form segment as manufacturers eliminate solvent handling and volatile organic compound compliance costs.
The European Chemicals Agency enforces REACH registration and restriction protocols that govern substance authorization across coating chemistries, while the FDA maintains food-contact notification requirements for fillings used in baked and confectionery goods in the United States. Germany's Federal Institute for Risk Assessment and the EPA's Toxic Substances Control Act collectively shape permissible additive lists and migration limits that determine market access for imported formulations. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions to anticipate reformulation cycles and raw material substitution timelines.
Market Dynamics
EU REACH chemical registration protocols are forcing simultaneous reformulation across food-contact coatings and industrial protective layers, compressing supplier timelines and redrawing raw material qualification requirements.
Growth Catalysts
- Automotive lightweighting mandates:German OEMs along the Rhine corridor are specifying high-performance powder coatings for aluminum chassis components to meet CO2 reduction targets.
- REACH substance authorization:The European Chemicals Agency's restriction protocols are accelerating substitution of per- and polyfluoroalkyl substances with bio-based barrier coatings in food packaging.
- Bean-to-bar processing control:Confectionery manufacturers are securing captive cocoa butter supplies through backward integration into origin sourcing to guarantee coating fat consistency.
Market Restraints
- Palm oil price volatility:Coating fat formulations depend on Southeast Asian oleochemical supply chains exposed to El Niño-driven harvest disruptions and export duty fluctuations.
- Titanium dioxide supply concentration:Five Chinese producers control over 60% of global chloride-process TiO2 capacity, creating single-source risk for white pigment-dependent architectural coatings.
- Migration testing bottlenecks:FDA food-contact notification reviews for novel filling stabilizers currently average 18-24 months, freezing formulation pipelines.
Strategic Opportunities
- India PLI scheme leverage:The Production Linked Incentive scheme for specialty chemicals offers 10-20% output-linked benefits for domestic coating intermediate manufacturing.
- UV-cured powder convergence:Near-infrared curing technology is merging with low-temperature powder systems to enable heat-sensitive substrate coating in automotive interiors.
- Direct technical partnerships:Consolidated bakery groups are bypassing distributors to co-develop functional coatings with embedded active ingredients.
Industry Challenges
- Rheology control expertise scarcity:Formulation chemists capable of tuning 500-15,000 centipoise viscosity windows for dual-phase coating-filling systems command premium compensation and limited availability.
- Legacy equipment retrofit costs:Confectionery lines built for solvent-based enrobing require capital-intensive conversion to water-borne or powder coating handling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coatings and Fillings Market |
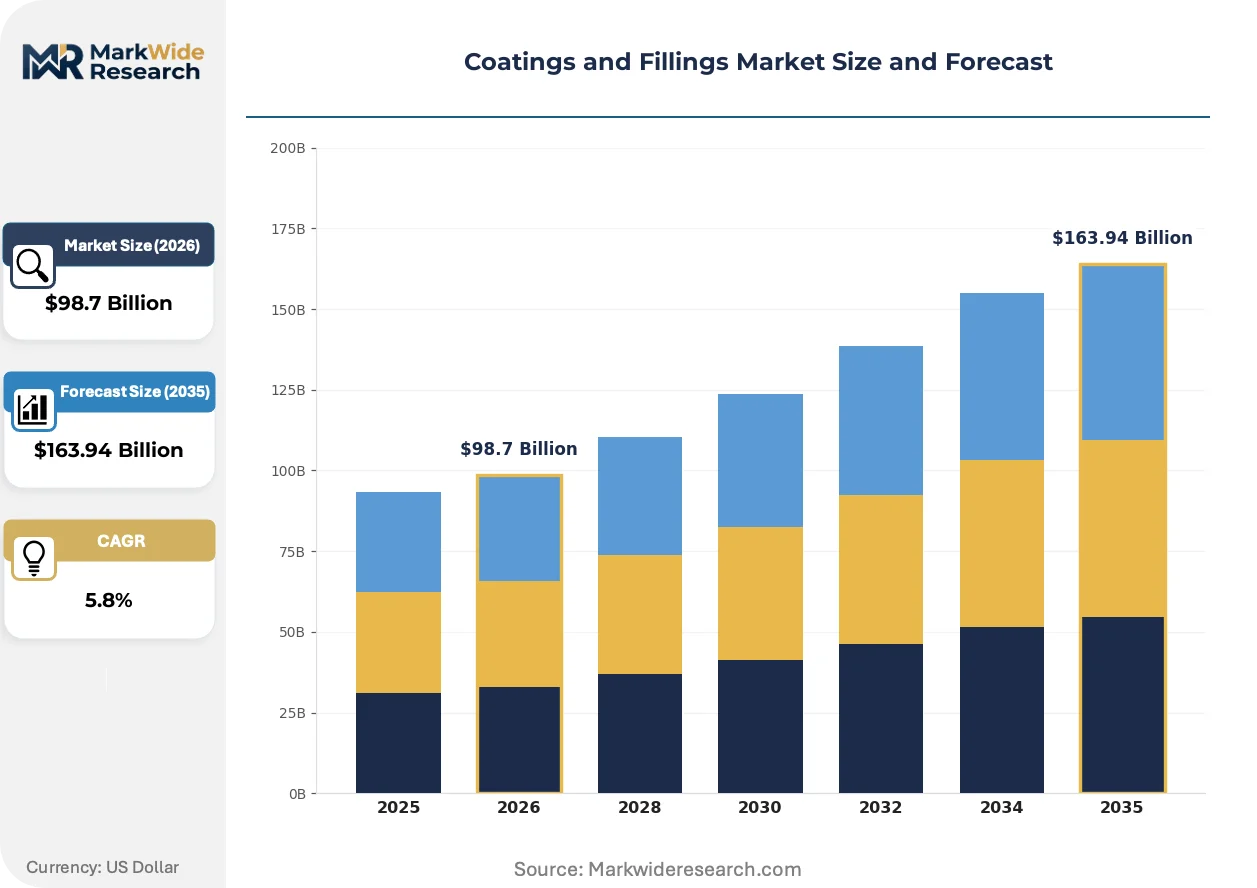
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $163.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Polyester Application: Automotive, Aerospace, Marine, Industrial Form: Liquid, Powder, Paste, Gel End User: Manufacturers, Contractors, DIY Users, Retailers |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Barry Callebaut AG, Tate & Lyle PLC, Ingredion Incorporated, Olam International Limited, AAK AB, Kerry Group plc, Puratos Group NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coatings and Fillings Market Emerging Trajectories
Formulation science is converging with process engineering as coating viscosity control and thermal stability parameters become inseparable from application equipment design and end-use performance validation.
Water-borne acrylic-urethane hybrid systems are hybridizing protective coating categories by combining UV resistance with abrasion tolerance in single-layer automotive refinish applications. Tier 1 suppliers to German OEMs are qualifying these formulations for bumper-to-bumper coverage. The technology is hybridizing procurement decisions as buyers consolidate specification lists and reduce approved vendor counts.
ECHA's restriction roadmap for per- and polyfluoroalkyl substances is eliminating fluoropolymer-based non-stick coatings from food-contact applications across EU member states. Industrial bakeries in Germany and France are accelerating trials of ceramic-reinforced silicone alternatives. The regulation is compressing reformulation cycles from typical 36-month windows to 18-month deadlines.
Consolidated food manufacturers are unbundling technical service from commodity supply contracts and paying premium fees for embedded R&D partnerships. Mid-sized coating ingredient distributors in the Rhine corridor are losing share to direct supplier-manufacturer relationships. This restructuring is most visible in chocolate confectionery, where Barry Callebaut and Cargill field dedicated customer innovation centers.
Coatings and Fillings Market Segmentation
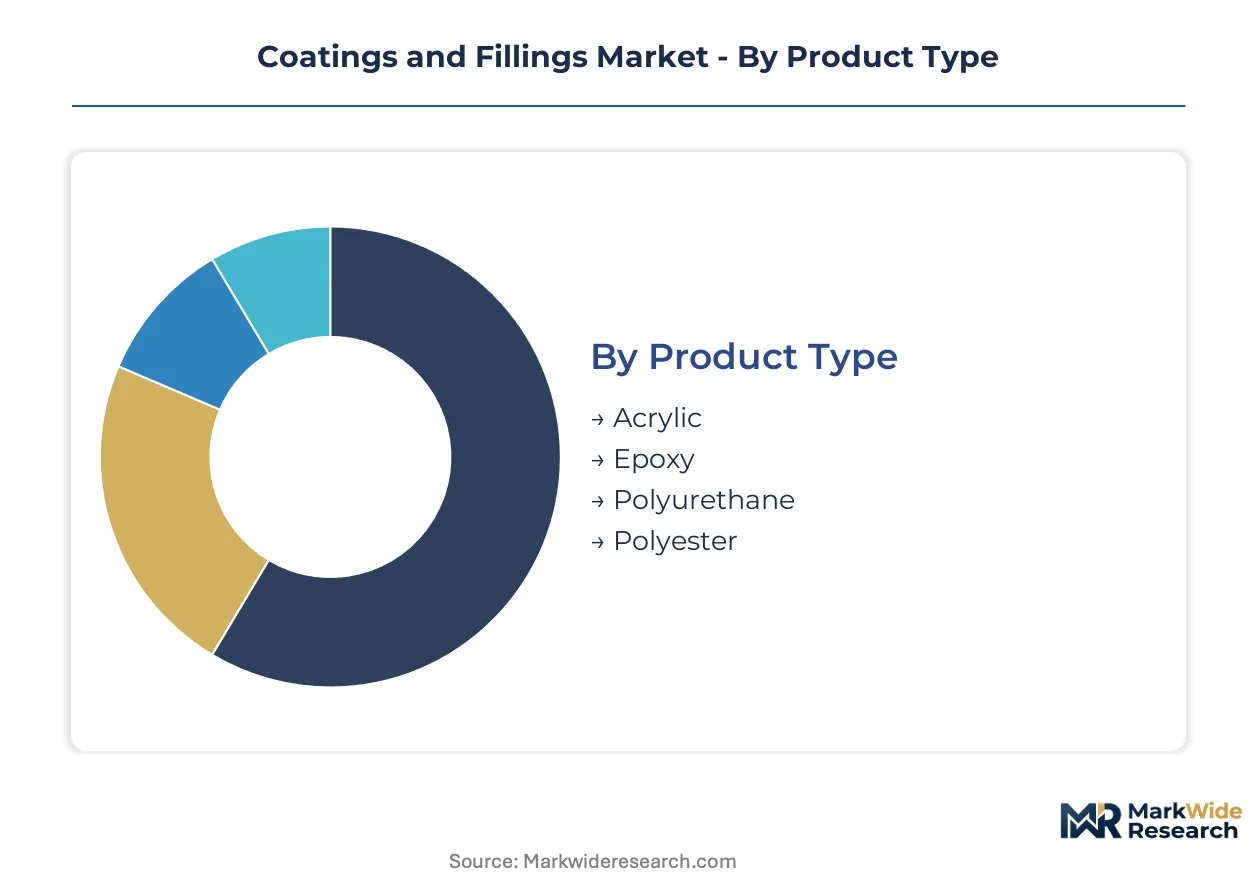
Coatings and fillings demand fragments across incompatible specification regimes—automotive OEMs enforce millimeter-level thickness tolerance while food manufacturers prioritize migration-compliant barrier layers. Segmentation clarity determines whether suppliers configure for high-volume commodity production or precision-engineered specialty batches.
Product Type:
Cost tier stratification separates architectural commodity formulations from specification-critical industrial systems demanding certified batch consistency.
- Acrylic:Water-borne emulsions dominate decorative architectural applications with UV-stable polymer backbones formulated for exterior durability. German housing renovators specify these for masonry protection along the Rhine corridor, though REACH-driven VOC limits are compressing solvent-borne variants out of specification lists.
- Polyurethane:Two-component aliphatic systems command premium positioning in automotive refinish and aerospace maintenance due to abrasion resistance and chemical tolerance. Boeing and Airbus maintenance facilities in Toulouse and Hamburg specify these for flight-critical surface protection where re-coat intervals directly impact fleet availability.
- Epoxy:Amine-cured systems anchor industrial protective coatings for chemical processing equipment and marine ballast tanks.
- Polyester:Saturated formulations serve powder coating applications where TGIC-free alternatives are gaining specification share under ECHA substance scrutiny.
Polyester holds installed capacity. Polyurethane is rotating up the share rankings.
Application:
Application focus determines whether formulation priorities center on corrosion inhibition, aesthetic finish, or regulatory compliance for food contact.
- Automotive:OEM specification hierarchies separate bumper-grade flexible coatings from chassis rigid systems, with German manufacturers along the Rhine corridor driving powder adoption for aluminum lightweighting. BMW and Mercedes-Benz paint shops enforce color-matching tolerances tighter than Delta E 1.0, forcing suppliers to maintain dedicated production lines.
- Industrial:Petrochemical facilities and power generation infrastructure demand intumescent fire-protection coatings with certified hourly ratings. French nuclear maintenance contractors specify these for containment vessel refurbishment where regulatory requalification cycles extend 15-20 years.
- Aerospace:MRO facilities prioritize chromate-free pretreatments and low-VOC topcoats under REACH authorization pressures.
- Marine:Antifouling systems face biocide restriction under EU BPR, accelerating silicone-based foul-release coating trials in Mediterranean and North Sea fleets.
Industrial maintains specification depth. Automotive is climbing the fastest.
Form:
Volume economics favor powder and liquid for automated application, while paste and gel formats serve repair and manual touch-up niches.
- Powder:Thermoset formulations eliminate solvent handling and VOC compliance costs while enabling near-zero overspray recovery. German automotive Tier 1 suppliers are converting liquid lines to powder for aluminum component coating, driven by CO2 reduction mandates and energy-efficient curing cycles.
- Liquid:Solvent-borne and water-borne systems retain dominance in field-applied maintenance coatings and complex geometry substrates where powder film build uniformity proves challenging. Italian yacht builders in Viareggio specify high-solids polyurethane liquids for superyacht superstructure finishing.
- Paste:High-viscosity compounds serve gap-filling and seam-sealing applications in marine and industrial maintenance.
- Gel:Thixotropic formulations enable vertical surface application without sag in structural repair scenarios.
Liquid retains volume leadership. Powder is gaining share fastest.
End User:
Customer type determines service intensity—manufacturers demand embedded technical partnership while retail channels prioritize shelf-ready packaging and color-matching simplicity.
- Manufacturers:Integrated production facilities specify coatings as process inputs rather than finished goods, requiring supplier quality systems certified to IATF 16949 and AS9100. Barry Callebaut and Cargill field dedicated innovation centers for confectionery manufacturers developing functional barrier coatings with embedded active ingredients.
- Contractors:Application specialists prioritize predictable pot life, sprayability, and touch-up compatibility over raw material cost minimization. French industrial painting contractors in Lyon cluster around automotive and aerospace sub-tier suppliers, demanding just-in-time delivery synchronized with production schedules.
- DIY Users:Home improvement retailers stock pre-tinted, single-component systems with application guidance printed on packaging.
- Retailers:Distribution channels consolidate procurement around fewer suppliers with private-label capability and regional logistics coverage.
Manufacturers anchor value capture. Contractors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs command premium pricing for specification-critical powder coatings, while Indian commodity producers compete on volume for architectural emulsions, creating a transcontinental price-power asymmetry that shapes supplier investment priorities.
Germany
Rhine corridor automotive OEMs and industrial bakeries drive dual-demand streams for high-performance powder coatings and food-contact barrier systems. ECHA REACH substance authorization protocols force 18-month reformulation cycles for per- and polyfluoroalkyl substance replacement. Stuttgart-based paint shops enforce Delta E 1.0 color tolerances for BMW and Mercedes-Benz chassis programs.
United States
Food manufacturers prioritize FDA-compliant filling stabilizers for baked goods while aerospace MRO facilities demand chromate-free pretreatments. FDA food-contact notification reviews average 18-24 months for novel coating ingredients. Chicago-area industrial bakeries cluster around commodity fat suppliers seeking technical partnership models.
China
Five domestic producers control over 60% of global chloride-process titanium dioxide capacity for white architectural coatings. MEE environmental enforcement and dual carbon goals accelerate water-borne acrylic substitution in coastal manufacturing zones. Shandong Peninsula chemical parks concentrate coating intermediate production for export markets.
India
Production Linked Incentive schemes offer 10-20% output-linked benefits for domestic specialty chemical manufacturing. FSSAI food safety standards govern confectionery coating formulations for domestic consumption and export qualification. Maharashtra and Gujarat industrial corridors attract coating intermediate investments from multinational suppliers.
France
Nuclear maintenance contractors specify intumescent fire-protection coatings with 15-20 year requalification cycles for containment vessel refurbishment. ANSM and CNIL frameworks shape pharmaceutical packaging coating compliance requirements. Toulouse aerospace clusters demand REACH-compliant low-VOC topcoats for Airbus MRO operations.
Coatings and Fillings Market Vendor Landscape
Integrated agricultural processors and specialized confectionery ingredient houses split the market between captive supply security and technical partnership depth. Consolidation pressure concentrates around three tiers: global oilseed processors with backward integration into coating fats, cocoa-origin specialists controlling bean-to-bar supply chains, and taste-science platforms embedding nutrition expertise into customer co-development. Dominant competitive moves include direct technical partnership formation and geographic production footprint expansion.
Within the integrated processor tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify agricultural commodity leverage applied to coating fat security, while Barry Callebaut AG anchors the cocoa-origin specialist position through bean-to-bar processing control. Kerry Group plc occupies the taste-science platform archetype, embedding formulation expertise into manufacturer innovation pipelines.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Barry Callebaut AG |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Olam International Limited |
| AAK AB |
| Kerry Group plc |
| Puratos Group NV |
| Others |
Supply Flow & Price Mechanics
Rhine corridor freight corridors connecting Rotterdam to Stuttgart carry coating intermediates and specialty fats through tariff-sensitive nodes where logistics cost volatility amplifies price spreads between configured-to-order industrial systems and commodity architectural emulsions. German automotive OEMs absorb premium pricing for powder coating specifications while Indian architectural producers compete on volume, creating asymmetric margin structures that reward supply chain control.
Pricing Analysis
Customization-premium spreads separate configured-to-order powder coatings for German automotive OEMs from standard architectural emulsions sold through retail channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation with REACH-compliant formulations commanding substantial premiums over commodity alternatives. Cost compression in standard architectural tiers is intensifying because Chinese titanium dioxide producers are expanding chloride-process capacity. DIY retailers and small contractors exhibit highest price sensitivity while integrated manufacturers prioritize technical partnership value over unit cost minimization.
Supply Chain Analysis
Tariff exposure between Southeast Asian oleochemical producers and European compounders dominates supply chain risk assessment for coating fat formulations. Production gravity centers on China for titanium dioxide intermediates, Germany for automotive-grade powder systems, and India for PLI-supported specialty chemical manufacturing. Raw material flows draw from Malaysian and Indonesian palm oil estates, Chinese chloride-process pigment plants, and Rhine corridor petrochemical complexes. Single-source vulnerability concentrates in titanium dioxide where five Chinese producers anchor global supply. Distribution runs through direct technical partnerships for manufacturers and consolidated distributor networks for contractor and retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as bio-based barrier coatings displace fluoropolymer systems under ECHA restriction protocols and ceramic-reinforced silicone alternatives capture food-contact applications.
For Market Incumbents: Build formulation moats around REACH-compliant replacement chemistries before 18-month regulatory deadlines compress. Secure captive supply of cocoa butter and coating fats through backward integration into origin sourcing to defend against oleochemical price volatility. Invest in dedicated innovation centers for direct technical partnerships with consolidated bakery and confectionery manufacturers. For New Entrants and Emerging Players: Build out UV-cured powder convergence capabilities targeting heat-sensitive automotive interior substrates where incumbent liquid systems face conversion costs. Target Indian PLI-supported manufacturing corridors for coating intermediate production with 10-20% output-linked benefits. Enter through technical co-development contracts with mid-sized industrial bakeries bypassing distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from agricultural processors seeking to divest non-core coating fat operations amid palm oil sustainability pressures. Long-term viability hinges on regulatory compliance infrastructure and direct manufacturer relationships rather than commodity volume scale. Watch ECHA substance authorization timelines as inflection indicators for reformulation-driven consolidation waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cocoa Sourcing | Bean-to-bar processing control guarantees coating fat consistency for confectionery manufacturers facing supply volatility. |
| REACH-Compliant Formulation Repositioning | ECHA authorization protocols force 18-month substitution cycles for per- and polyfluoroalkyl substance replacement. |
| Direct Technical Partnership Formation | Consolidated food manufacturers bypass distributors for embedded R&D partnerships with premium fee structures. |
| UV-Cured Powder System Development | Near-infrared curing technology enables heat-sensitive substrate coating in automotive interior applications. |
| PLI Scheme Manufacturing Footprint | Indian Production Linked Incentive benefits attract coating intermediate investments from multinational suppliers. |
Methodological Framework
Initial hypotheses were tested against primary input from coating formulation chemists, automotive OEM procurement leads, industrial bakery technical directors, and confectionery R&D heads and refined through secondary validation against ECHA substance authorization databases, FDA food-contact notification filings, SEC 10-K disclosures from integrated agricultural processors, and customs trade data for oleochemical flows. Bottom-up volume modeling across application segments triangulated with top-down value estimates from identified producer revenue disclosures.
Demand-supply-balance framing anchored the analytical framework across the analysis window with segmentation dimensions spanning product type, application focus, form factor, and end-user category. CAGRs were derived from fitted growth curves calibrated to historical volume trajectories and adjusted for regulatory-driven substitution timelines. Forecast inputs incorporated ECHA restriction roadmap milestones, automotive lightweighting mandate compliance schedules, and PLI scheme incentive phase structures.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese titanium dioxide producers or accelerated ECHA authorization deadlines would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Polyaspartic Coatings Market
Coatings
Global Abrasion Resistant Coatings Market
Coatings
Glazes Market
Coatings
South Africa Protective Coatings Market
Coatings
Global Fusion Bonded Epoxy Coatings Market
Coatings
Wood Preservative Coatings Market
Coatings
Polyester Coatings Market
Coatings
Marine Nanocoating Market
Coatings
Global Fireproofing Coatings for Wood Market
Coatings
Antimicrobial Coil Coating Market
Coatings
China Marine Coatings Market
Coatings
Global Cellulosic Fire Protection Intumescent Coatings Market
Coatings
Asia-Pacific Coil Coatings Market
Coatings
Metallic Powder Coating Market
Coatings
Leisure Boat Marine Coatings Market
Coatings
Global Powder Coating Market