
 Glacial Acrylic Acid (GAA) Market | 2026-2036
Glacial Acrylic Acid (GAA) Market Size, Share, and Industry Trends Forecast 2026-2036
Glacial Acrylic Acid (GAA) Market Foresight
China is narrowing its cost advantage in glacial acrylic acid through propylene oxidation capacity additions along the Yangtze River corridor. BASF SE leverages backward integration into propylene feedstock to sustain margin stability across European supply chains. NIPPON SHOKUBAI CO., LTD. anchors high-purity polymer-grade output for superabsorbent polymer makers in Japan and Southeast Asia.
Glacial acrylic acid is a purified form of acrylic acid containing less than 0.3% water, produced via two-stage catalytic oxidation of propylene and subsequently crystallized or azeotropically distilled to achieve polymer-grade purity. Manufacturers use this monomer primarily to synthesize acrylate esters, superabsorbent polymers, and water-soluble thickeners where residual moisture would disrupt chain-growth kinetics. Polymer-grade GAA commands premium positioning as superabsorbent polymer producers require sub-500 ppm impurity thresholds for hygiene product certification. Water treatment applications compete on volume scale rather than purity premiums, with municipal and industrial flocculant buyers sourcing standard-grade material through distributor networks.
EPA oversight of acrylamide residuals in potable water treatment chemicals shapes North American product formulation requirements, while REACH registration mandates in Europe compel full supply-chain disclosure of acrylic acid hazard classifications. China's MEE enforces volatile organic compound emission limits at oxidation plant perimeters, elevating capital costs for new propylene-to-GAA units. Stakeholders must monitor feedstock propylene spread volatility and regional carbon border adjustment mechanisms before committing to greenfield capacity.
Market Dynamics
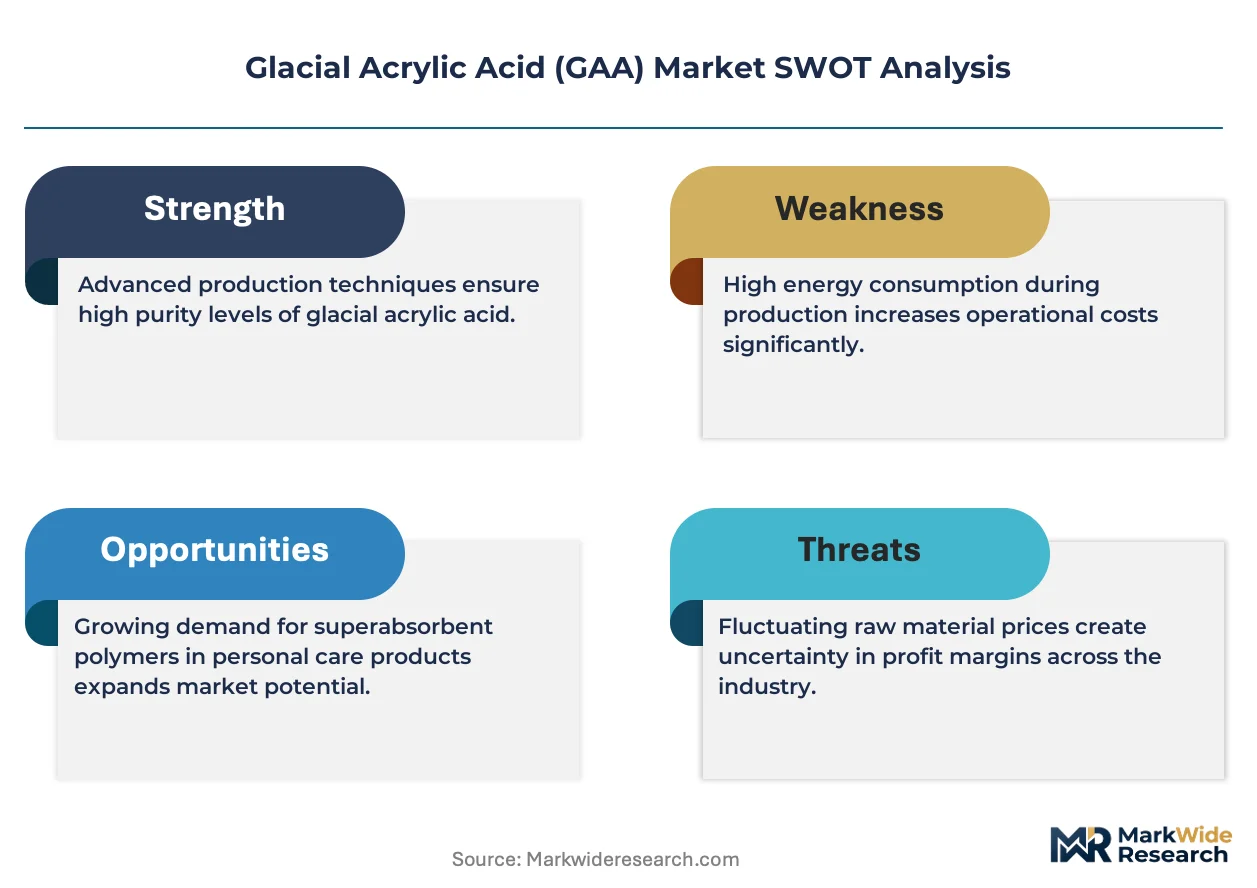
Propylene feedstock volatility and polymer-grade purity mandates are compressing margin structures across glacial acrylic acid supply chains, forcing producers to choose between backward integration investments or specialty-grade premium positioning.
Growth Catalysts
- Superabsorbent polymer expansion:Hygiene product manufacturers in Southeast Asia are scaling diaper and adult incontinence output, driving polymer-grade GAA consumption for sub-500 ppm impurity specifications.
- REACH registration mandates:ECHA disclosure requirements for acrylic acid hazard classifications are consolidating supply toward registered producers with full toxicological dossiers, advantaging compliant incumbents.
- Water treatment polymer demand:Municipal flocculant programs across the Yangtze River corridor are expanding standard-grade GAA offtake for acrylamide copolymer synthesis.
Market Restraints
- Propylene price volatility:Naphtha-cracker feedstock swings and refinery operating rate fluctuations transmit directly into GAA production economics, destabilizing margin forecasts.
- Emission control capital intensity:China's MEE volatile organic compound limits at oxidation plant perimeters require scrubber and thermal oxidizer investments that extend new entrant payback periods.
- Acrylamide residual scrutiny:EPA oversight of potable water treatment chemicals constrains formulation flexibility for North American municipal buyers, limiting supplier pool expansion.
Strategic Opportunities
- Biobased propylene pathways:Bio-naphtha and renewable feedstock cracking advances could decouple GAA production from fossil propylene exposure, appealing to brand-owner sustainability commitments.
- Carbon border adjustment positioning:EU CBAM implementation creates first-mover advantage for producers with verified low-carbon oxidation processes and renewable energy offtake contracts.
- Specialty ester derivative expansion:2-ethylhexyl acrylate and hydroxyethyl acrylate demand for coatings and adhesives applications offers premium pricing escape from commodity acrylic ester competition.
Industry Challenges
- Crystallization operator expertise:Polymer-grade GAA production requires precise temperature control and seed crystal management that experienced technicians command premium compensation to execute.
- Multi-jurisdiction registration synchronization:Maintaining concurrent REACH, EPA TSCA, and China MEE chemical inventory compliance demands dedicated regulatory affairs capacity that mid-scale producers struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glacial Acrylic Acid (GAA) Market |
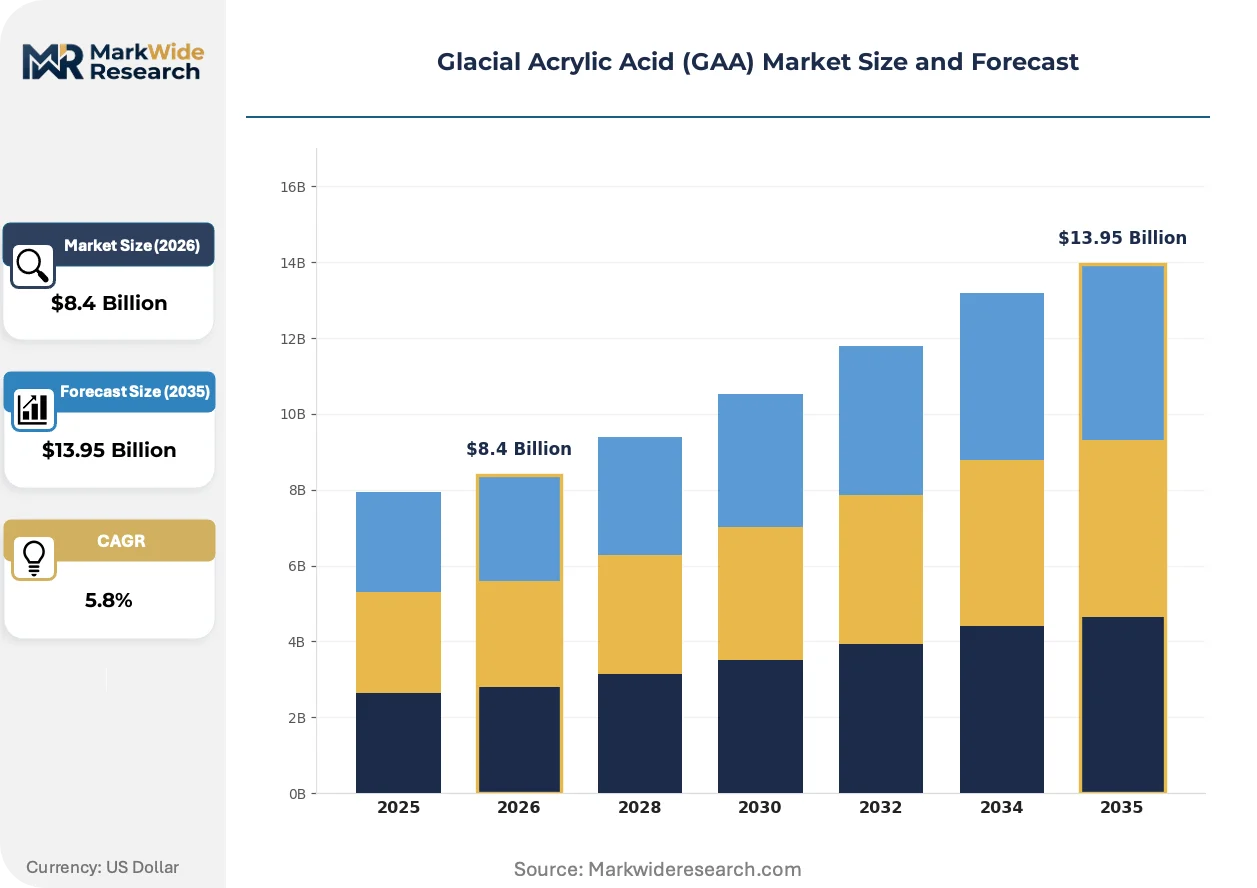
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.95 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Grade, Polymer Grade, High Purity, Technical Grade Application: Adhesives & Sealants, Water Treatment, Coatings, Plastics, Detergents, Textiles End User Industry: Pulp & Paper, Personal Care Products, Paints & Inks, Agriculture Chemicals, Oilfield Chemicals Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Wholesale Suppliers |
| Companies Covered | The Dow Chemical Company, Arkema, BASF SE, Sasol, Tasnee, NIPPON SHOKUBAI CO., LTD., Mitsubishi Chemical Corporation, Formosa Plastics Corporation, HAITUNG CHEMICALS CO., LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glacial Acrylic Acid (GAA) Market Shifts & Advancements
Process intensification and digital control systems are redefining operational boundaries in glacial acrylic acid manufacturing, while regulatory transparency mandates and buyer consolidation reshape commercial relationships.
Membrane-assisted vapor permeation dehydration technology is rendering obsolete conventional azeotropic distillation trains for polymer-grade GAA finishing. Superabsorbent polymer producers in Japan and South Korea are adopting membrane systems to achieve sub-300 ppm water specifications without entrainer chemicals. This shift is compressing energy consumption per ton by eliminating benzene or cyclohexane recovery loops.
REACH Article 33 supply chain communication obligations now require downstream polymer processors to document acrylic acid monomer concentrations in imported articles. European diaper and hygiene product manufacturers are demanding batch-specific certificates of analysis with full impurity profiling. This transparency mandate is segmenting the supplier base between dossier-complete registrants and non-compliant traders facing market exclusion.
Consolidated procurement by multinational hygiene product corporations is compressing supplier negotiation cycles from annual to quarterly frameworks. Buyers are unbundling logistics and technical service components from base chemical pricing, forcing GAA producers to compete on delivered cost and formulation support separately. This disaggregation is most visible in Germany and the Netherlands where centralized purchasing functions serve pan-European manufacturing networks.
Glacial Acrylic Acid (GAA) Market Segmentation
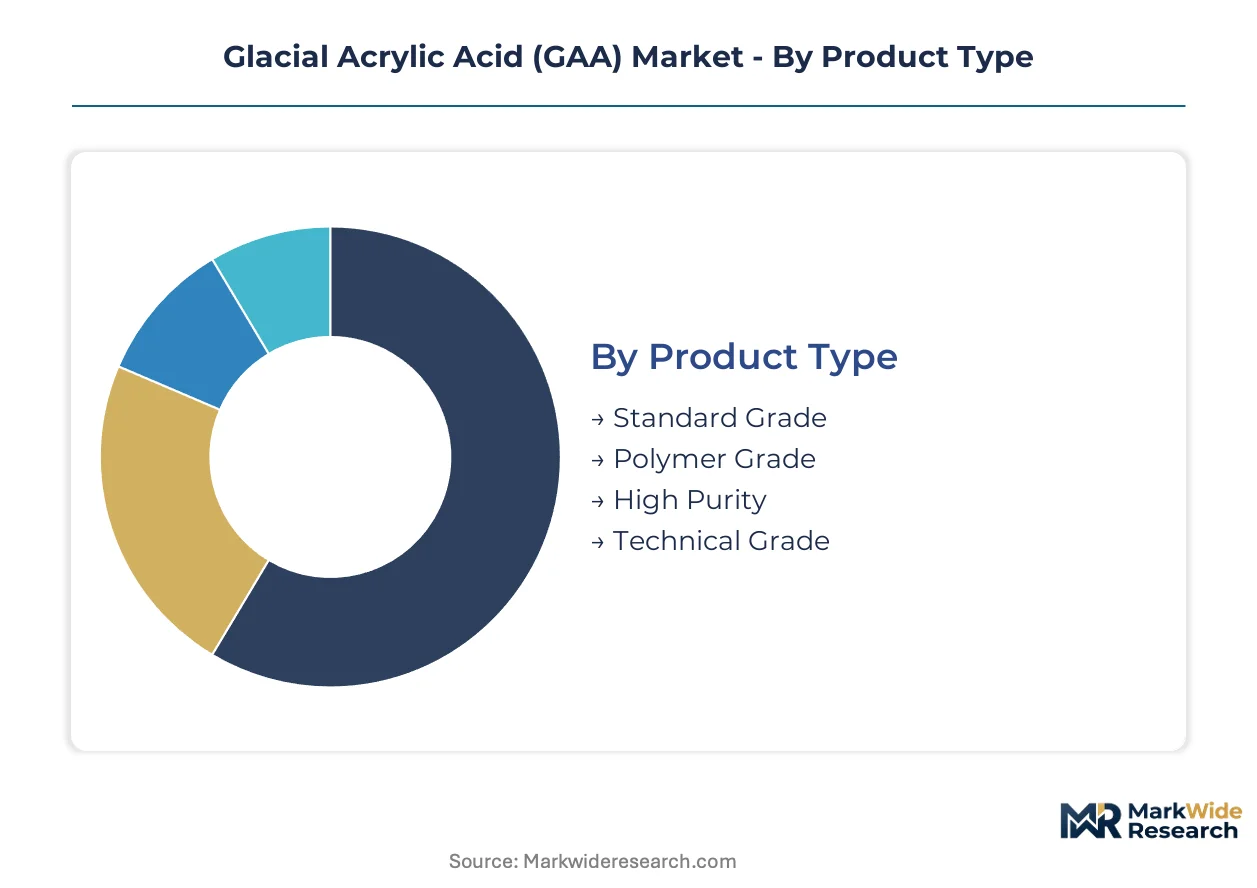
Segmentation in glacial acrylic acid reveals how purity specifications, application chemistry, and procurement channels create distinct margin pools. Producers must align crystallization capacity with the technical service intensity each tier demands.
Product Type:
After-sales service intensity escalates with purity grade, as polymer-grade buyers require batch-specific certificates of analysis and formulation troubleshooting.
- Polymer Grade:Sub-500 ppm impurity thresholds define this specification for superabsorbent polymer synthesis. Hygiene product manufacturers in Japan and South Korea source exclusively from membrane-dehydrated output to achieve sub-300 ppm water content for diaper and adult incontinence applications.
- High Purity:Ultra-low trace metal specifications serve electronic coatings and specialty acrylate derivatives where residual ions disrupt polymerization kinetics. Demand concentrates in German and Dutch coatings clusters where REACH Article 33 disclosure mandates require full impurity profiling.
- Standard Grade:Municipal water treatment flocculant producers accept higher moisture content for acrylamide copolymer feedstock.
- Technical Grade:Industrial adhesive formulators utilize this tier for non-critical bonding applications with less stringent chain-growth requirements.
By volume, Standard Grade leads. By growth pace, Polymer Grade is ahead.
Application:
Cost tier stratification separates commodity volume plays from specialty premium positioning across end-use chemistry.
- Water Treatment:Municipal and industrial flocculant programs drive the largest volume offtake for acrylamide copolymer synthesis. China's Yangtze River corridor expansion and EPA acrylamide residual oversight in US potable systems shape procurement specifications.
- Adhesives & Sealants:Pressure-sensitive adhesive manufacturers require precise viscosity control and low-color specifications for tape and label applications. Demand concentrates in automotive assembly plants across Germany and Mexico where bonding performance standards are stringent.
- Coatings:Architectural and industrial paint formulators source standard-grade material for latex emulsion production.
- Plastics:Acrylic sheet and molding compound producers utilize GAA as comonomer feedstock for impact modification.
- Detergents:Surfactant manufacturers incorporate acrylic acid derivatives as builder and anti-redeposition agents.
- Textiles:Sizing and finishing chemical producers apply GAA-based polymers for yarn lubrication and fabric hand modification.
Water Treatment commands the largest share of volume. Adhesives & Sealants delivers the steepest expansion trajectory.
End User Industry:
Customer type diversity spans from consolidated multinational hygiene corporations to fragmented agricultural chemical blenders.
- Personal Care Products:Superabsorbent polymer makers for diaper and adult incontinence manufacturers represent the most demanding customer segment. Japanese and Southeast Asian hygiene product corporations consolidate procurement through quarterly framework agreements with unbundled logistics and technical service pricing.
- Pulp & Paper:Retention and drainage aid formulators drive standard-grade consumption for microparticle flocculation systems. Nordic integrated mills and Chinese packaging paper producers anchor regional demand clusters.
- Paints & Inks:Decorative and industrial coatings manufacturers source polymer-grade material for high-gloss latex emulsions.
- Agriculture Chemicals:Pesticide and fertilizer coating applications utilize technical-grade GAA for controlled-release polymer matrices.
- Oilfield Chemicals:Enhanced oil recovery polymer and drilling fluid additive producers require high-purity specifications for downhole stability.
Personal Care Products generates the highest purity premiums. Pulp & Paper moves the greatest tonnage.
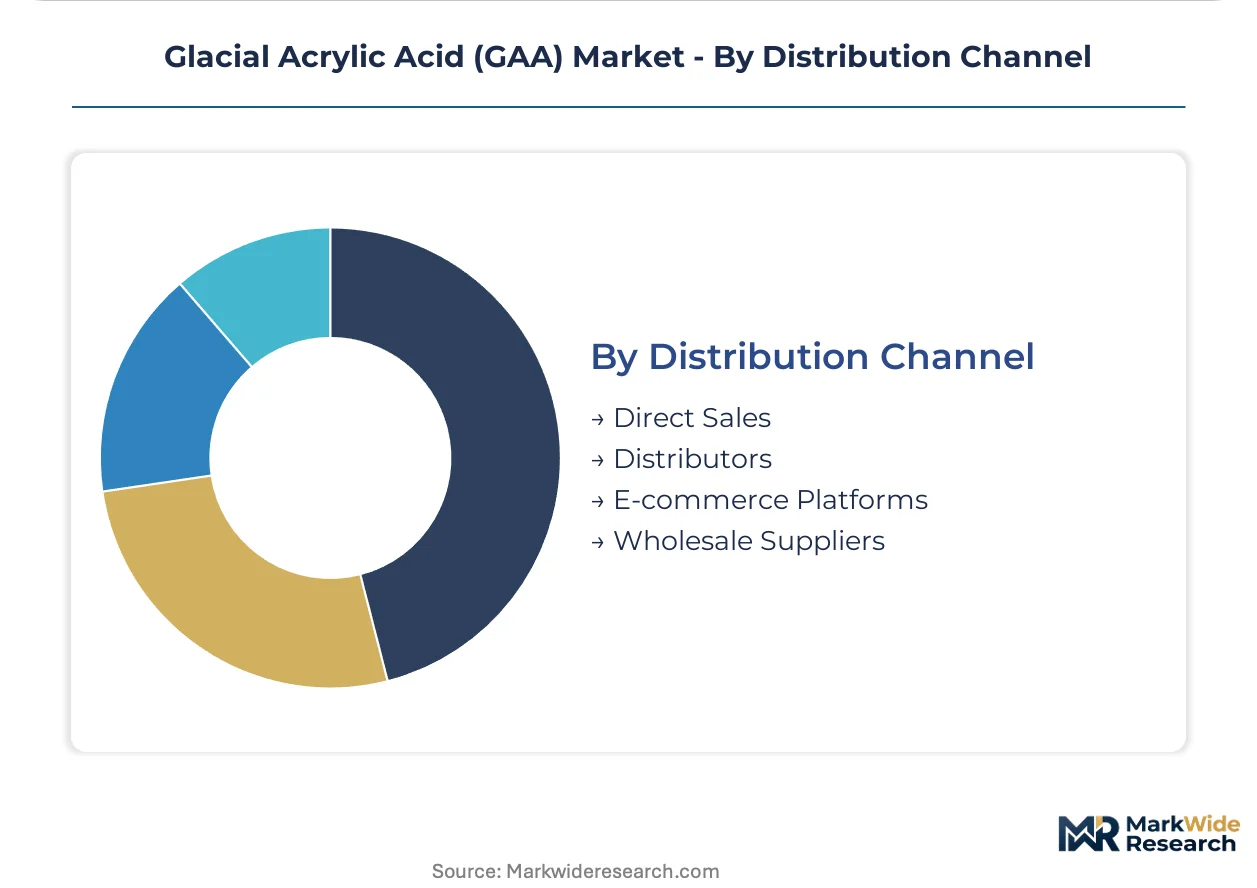
Distribution Channel:
Supply concentration determines channel leverage, with direct relationships dominating polymer-grade while distributors capture standard-grade fragmentation.
- Direct Sales:Polymer-grade GAA producers maintain dedicated account management for superabsorbent polymer and coatings manufacturers. BASF SE and NIPPON SHOKUBAI CO., LTD. deploy technical service teams for formulation support and batch certification.
- Distributors:Regional chemical distributors capture standard-grade water treatment and industrial adhesive volume through stocking locations in China's Yangtze River corridor and Germany's Rhine-Ruhr industrial zone.
- E-commerce Platforms:Small-volume buyers and research laboratories source technical-grade material through specialized chemical marketplaces with certificate of analysis documentation.
- Wholesale Suppliers:Bulk terminal operators and tank farm networks serve spot market demand for standard-grade material in North American and European port locations.
Direct Sales captures the highest margin per ton. Distributors reach the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors the dominant geography through volatile organic compound emission limits that elevate capital costs for new propylene oxidation capacity. Germany's ECHA REACH mandates consolidate supply toward registered producers with full toxicological dossiers. Japan's METI standards drive sub-300 ppm water specifications for superabsorbent polymer feedstock.
China
Propylene oxidation capacity additions along the Yangtze River corridor narrow the country's cost advantage in glacial acrylic acid production. The MEE enforces volatile organic compound emission limits at oxidation plant perimeters, extending payback periods for greenfield investments. Shanghai and Nanjing host expanding acrylic ester derivative clusters serving Southeast Asian hygiene product manufacturers.
Germany
REACH Article 33 supply chain communication obligations require downstream polymer processors to document acrylic acid monomer concentrations in imported articles. ECHA disclosure requirements for hazard classifications advantage compliant incumbents with full toxicological dossiers. The Rhine-Ruhr industrial zone concentrates coatings manufacturers demanding batch-specific certificates of analysis with complete impurity profiling.
United States
EPA oversight of acrylamide residuals in potable water treatment chemicals constrains formulation flexibility for municipal buyers. The agency's monitoring protocols limit supplier pool expansion for standard-grade material used in flocculant synthesis. Texas Gulf Coast petrochemical corridors anchor propylene feedstock supply for integrated GAA producers serving North American water treatment markets.
Japan
Superabsorbent polymer producers adopt membrane-assisted vapor permeation dehydration to achieve sub-300 ppm water specifications without entrainer chemicals. METI standards for polymer-grade purity sustain premium positioning for domestic output serving diaper and adult incontinence applications. Osaka and Kobe host technical service-intensive supply relationships with quarterly framework procurement cycles.
Saudi Arabia
Propylene feedstock availability from associated gas cracking supports cost-competitive oxidation capacity serving European and Asian export markets. The country's industrial diversification programs incentivize downstream acrylic ester derivative investments. Jubail industrial city concentrates petrochemical infrastructure with access to Red Sea shipping lanes for polymer-grade cargo distribution.
Glacial Acrylic Acid (GAA) Market Competitive Landscape
Capability concentration sits with the polymer-grade purification tier; scale advantage sits with integrated propylene oxidation operators. The market structure separates membrane-dehydration specialists serving sub-300 ppm specifications from standard-grade volume players competing on delivered cost. Three archetypes dominate: backward-integrated petrochemical majors, high-purity polymer-grade specialists, and regional propylene oxidation operators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing renewable energy offtake contracts for carbon border adjustment positioning.
Among Germany-based chemical conglomerates, BASF SE exemplifies the backward-integrated archetype with captive propylene feedstock control. NIPPON SHOKUBAI CO., LTD. occupies a position within the high-purity specialist tier, anchoring polymer-grade output for superabsorbent polymer certification requirements. Arkema represents European specialty chemical positioning with regulatory dossier completeness under REACH mandates.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| Arkema |
| BASF SE |
| Sasol |
| Tasnee |
| NIPPON SHOKUBAI CO., LTD. |
| Mitsubishi Chemical Corporation |
| Formosa Plastics Corporation |
| HAITUNG CHEMICALS CO., LTD. |
| Others |
Supply & Pricing Matrix
Overcapacity signals from China's Yangtze River corridor oxidation plants are compressing spot pricing for standard-grade material while tightening polymer-grade premiums. Utilization differentials between membrane-dehydrated polymer-grade lines and conventional azeotropic units are driving supplier behavior toward specialty-grade positioning and pricing posture segmentation.
Pricing Analysis
Asia-Pacific to Europe price spreads for polymer-grade cargo reflect freight differentials and REACH registration premiums. Three-tier pricing structure across polymer-grade, high-purity, and standard levels tracks impurity thresholds and certification intensity. Cost compression in standard-grade water treatment tiers is intensifying because China's MEE emission controls elevate fixed costs for new entrants. Municipal flocculant buyers exhibit highest price sensitivity; superabsorbent polymer manufacturers for hygiene products show least sensitivity due to sub-500 ppm certification requirements.
Supply Chain Analysis
Contract manufacturing concentration resides with NIPPON SHOKUBAI CO., LTD., Arkema, and BASF SE for polymer-grade membrane dehydration capacity. Supply concentrates in China, Germany, and Japan for oxidation and finishing operations. Feedstock propylene and catalytic oxidation technology rest on naphtha-cracker economics and licensed reactor designs. Single-source vulnerability from propylene supply concentration in Gulf Coast and Middle Eastern cracking complexes threatens margin stability. Distribution runs through direct account management for polymer-grade buyers and regional distributors for standard-grade water treatment volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against biobased propylene pathways that could decouple acrylic acid from fossil feedstock economics. Incumbents must navigate sustainability-driven brand-owner commitments that threaten conventional oxidation capacity valuations.
For Market Incumbents: Insulate polymer-grade positioning through captive membrane dehydration capacity and METI-compliant sub-300 ppm certification. Deepen backward integration into propylene feedstock to stabilize margin exposure to naphtha-cracker volatility. Prioritize REACH dossier completeness to consolidate supply toward registered producers as ECHA transparency mandates tighten.
For New Entrants and Emerging Players: India's underpenetrated hygiene product manufacturing base offers white-space expansion for polymer-grade supply with technical service intensity. Target Southeast Asian diaper and adult incontinence producers scaling output without established GAA relationships. Pursue carbon border adjustment positioning through renewable energy offtake contracts for EU market access.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among membrane-dehydration specialists serving quarterly framework agreements with multinational hygiene corporations. Five-to-ten year viability favors producers with verified low-carbon oxidation processes and full toxicological dossiers under REACH. Monitor biobased propylene commercialization milestones as inflection indicator for fossil-dependent capacity valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene | BASF SE's captive feedstock control sustains margin stability across European supply chains. |
| Membrane Dehydration Capacity Addition | Japan and South Korea producers achieve sub-300 ppm specifications without benzene recovery loops. |
| REACH Dossier Completion | ECHA compliance consolidates supply toward registered producers with full toxicological documentation. |
| Renewable Energy Offtake Contracts | EU CBAM positioning creates first-mover advantage for low-carbon oxidation process verification. |
| Specialty Ester Derivative Expansion | 2-ethylhexyl acrylate demand for coatings offers premium pricing escape from commodity competition. |
Research Methodology
Cross-validation between primary interviews with oxidation plant managers, superabsorbent polymer procurement leads, and water treatment chemical distributors anchors the qualitative findings. Secondary validation draws from customs trade data, Cefic chemical industry reports, SEC 10-K filings, and MEE emission disclosure records. Bottom-up capacity modeling triangulates against top-down consumption estimates from acrylate ester derivative production statistics.
Calibration against historical propylene spread volatility and REACH registration timelines shapes the analytical framework across the analysis window. Segmentation dimensions include purity grade tier, end-use industry chemistry, and regional production hub clustering. CAGRs derive from elasticity modeling of superabsorbent polymer demand and water treatment flocculant program expansion. Forecast inputs incorporate MEE emission control capital intensity and biobased propylene pathway commercialization trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-affiliated petrochemical majors would shift outcomes. Propylene price volatility, carbon border adjustment implementation timing, and biobased feedstock cost parity represent specific risk factors requiring revision. Quarterly review of membrane dehydration technology adoption rates and REACH enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
Global Sodium Borohydride Market
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Refined Wax Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Global Potassium Metabisulfite Market
Bulk Chemicals
Europe Calcium Carbonate Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
Global Vinyl Chloride Monomer Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
North America Acetic Acid Market
Bulk Chemicals
Alkali Metal Hydroxides Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Oman Sodium Hydroxide Market
Bulk Chemicals
Potassium Cryolite Market