
 Polyisoprene Elastomers Market | 2026-2036
Polyisoprene Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Polyisoprene Elastomers Market Intelligence
Buyer consolidation among tire manufacturers is realigning procurement leverage across the polyisoprene elastomers value chain. ExxonMobil Chemical leverages integrated feedstock access to sustain cost competitiveness in synthetic grades. Nizhnekamskneftekhim anchors regional supply security through captive butadiene capacity. Kraton Corporation differentiates via specialized styrenic block copolymer architectures for medical and industrial niches.
Polyisoprene elastomers comprise high-cis-1,4-polyisoprene polymers derived from either Hevea brasiliensis latex or Ziegler-Natta catalyzed solution polymerization, exhibiting Shore A hardness values from 30 to 90 and tensile strengths exceeding 20 MPa for demanding mechanical applications. Synthetic polyisoprene dominates volume flows to tire producers seeking consistent viscosity and minimal protein content. Medical device applications represent the fastest-expanding end-use segment, driven by latex-allergy mitigation and stringent biocompatibility protocols. Thermoplastic elastomers capture premium positioning through injection-molding compatibility and recycling advantages in consumer goods.
EPA emissions standards and OSHA workplace exposure limits shape manufacturing site selection and process chemistry investments in U.S. production facilities. EMA biocompatibility frameworks and REACH substance restrictions govern market access for European medical and consumer applications. Stakeholders must monitor evolving ISO 10993 testing protocols and polymer traceability mandates to secure long-term supply contracts with regulated end-users.
Market Dynamics
Tire manufacturers are consolidating procurement volumes while medical device makers fragment into specialized grades, creating divergent margin pressures across synthetic and natural polyisoprene supply tiers. REACH substance restrictions and evolving ISO 10993 biocompatibility protocols are forcing dual-track certification investments.
Growth Catalysts
- Automotive lightweighting mandates:OEMs in Germany specify high-cis polyisoprene for fuel-efficiency-driven tire reformulations.
- Latex-allergy mitigation protocols:FDA guidance on protein-content thresholds accelerates synthetic substitution in surgical glove manufacturing.
- Solution polymerization advances:Ziegler-Natta catalyst refinements deliver viscosity consistency that natural rubber cannot match.
Market Restraints
- Butadiene feedstock volatility:Synthetic polyisoprene producers face margin compression from naphtha-cracker output fluctuations.
- Hevea plantation concentration:Natural rubber supply security depends on Southeast Asian climatic conditions and labor availability.
- REACH authorization bottlenecks:ECHA substance evaluations delay market access for novel curative packages in European medical applications.
Strategic Opportunities
- India medical device manufacturing:CDSCO regulatory harmonization with ISO 13485 creates export-platform potential for latex-free elastomer suppliers.
- Thermoplastic elastomer hybridization:Styrenic block copolymer architectures enable injection-molding compatibility in consumer electronics housings.
- EU Green Deal circularity incentives:Chemical recycling pathways for crosslinked elastomurs attract green bond financing.
Industry Challenges
- ISO 10993-5 cytotoxicity testing capacity:Contract laboratory queues extend medical-grade qualification timelines.
- Legacy mixing equipment retrofit costs:Batch consistency requirements for medical grades demand precision temperature control investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyisoprene Elastomers Market |
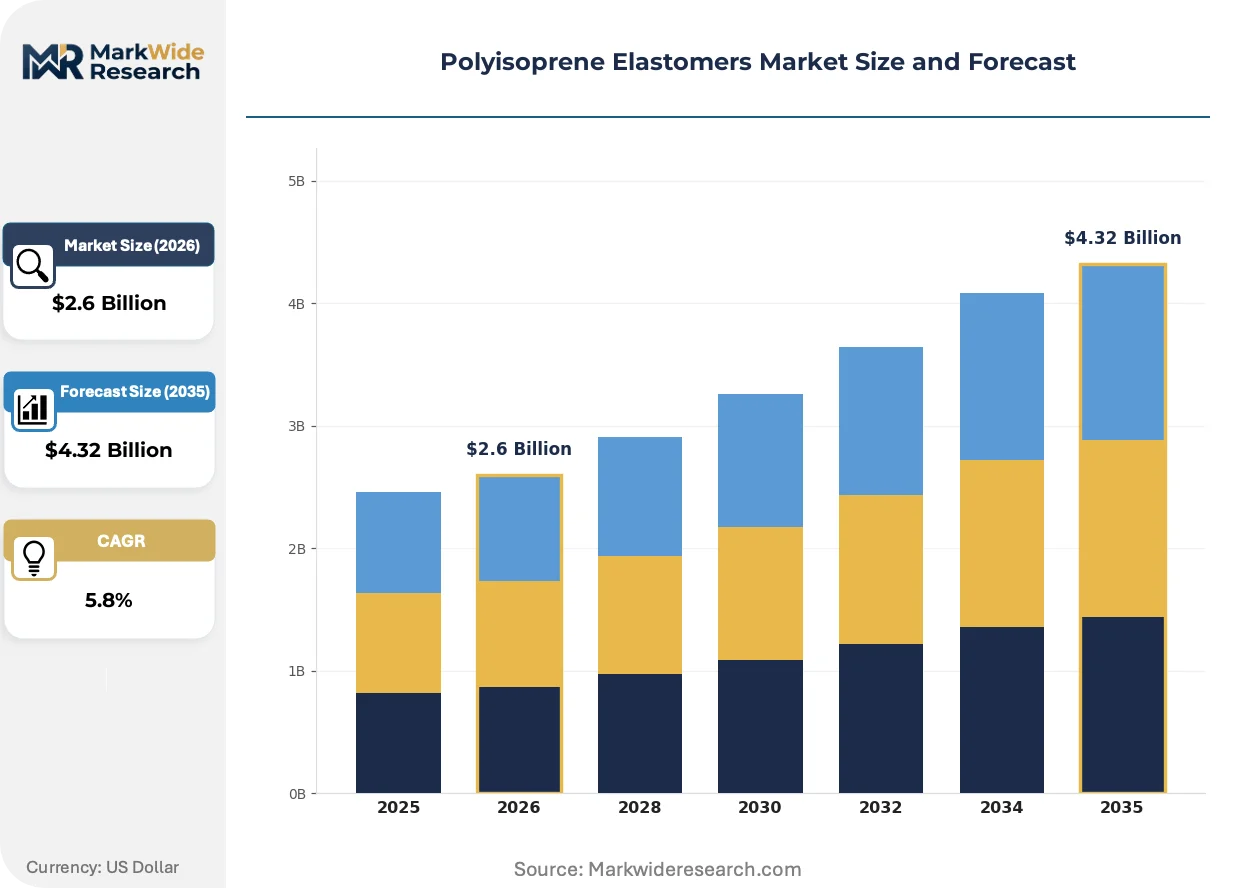
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.32 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Polyisoprene, Synthetic Polyisoprene, Thermoplastic Elastomers, Softening Agents End User: Automotive, Consumer Goods, Healthcare, Industrial Applications Application: Adhesives, Sealants, Medical Devices, Protective Equipment Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Outlets |
| Companies Covered | Sibur Holding, ExxonMobil Chemical, Nizhnekamskneftekhim, Zeon Corporation, The Goodyear Tire & Rubber Company, Cariflex, JSR Corporation, LG Chem Ltd., Kraton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyisoprene Elastomers Market Strategic Shifts & Innovations
Material science convergence with digital process control is compressing development cycles for application-specific elastomer formulations. Regulatory fragmentation between biocompatibility frameworks is simultaneously creating certification complexity and premium-grade segmentation opportunities.
Advanced Ziegler-Natta catalyst systems with controlled stereospecificity are integrating into continuous solution polymerization lines. Tire producers in Germany and Japan adopt these systems to achieve batch-to-batch viscosity stability below 5% variation. This integration is compressing compound development timelines from months to weeks for OEM qualification programs.
REACH Annex XIV authorization requirements for certain phthalate plasticizers are forcing reformulation of medical-grade compounds across European supply chains. Compounders must validate alternative curative packages without compromising Shore A hardness specifications. Surgical device manufacturers in Germany and France are responding by consolidating supplier bases to those with pre-validated alternative portfolios.
Specification-driven procurement now dominates medical elastomer sourcing, displacing price-first tendering. Device OEMs in the United States and Germany now require polymer traceability to monomer batch and catalyst lot. This behavioral shift concentrates volumes with compounders offering blockchain-anchored certificate-of-analysis systems.
Polyisoprene Elastomers Market Segmentation
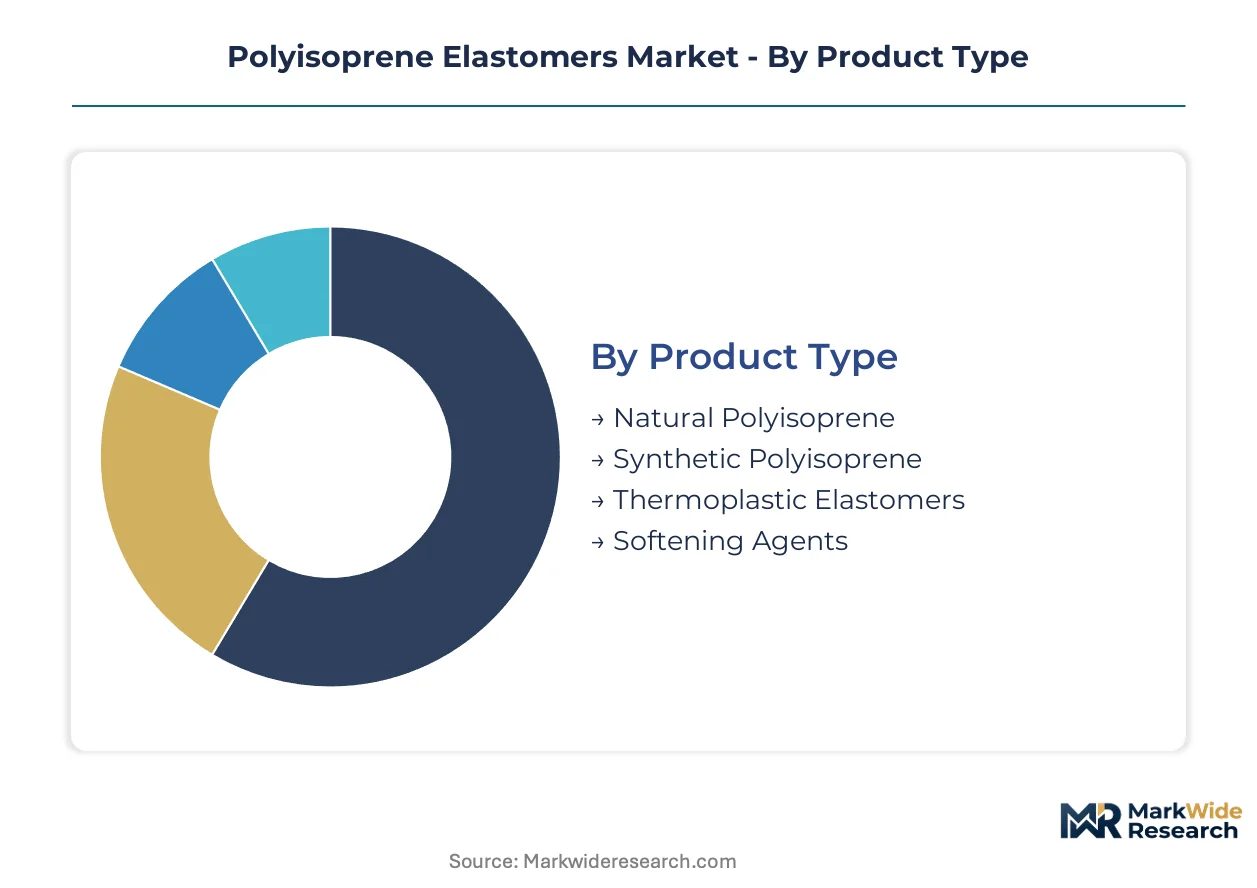
Polyisoprene elastomer procurement divides sharply between specification-driven medical grades and commodity tire formulations. Certification requirements fragment the supplier base across ISO 10993, REACH, and FDA pathways, creating tiered margin structures that reward pre-validated compounders.
Product Type:
ISO 10993-5 cytotoxicity testing and REACH Annex XIV substance restrictions impose divergent compliance burdens across polymer chemistries, with medical grades demanding batch-level traceability that commodity tiers escape.
- Synthetic Polyisoprene:Ziegler-Natta catalyzed solution polymers deliver viscosity consistency below 5% batch-to-batch variation. Tire manufacturers in Germany specify these grades for OEM qualification programs where natural rubber protein content creates rejection risk.
- Natural Polyisoprene:Hevea brasiliensis latex derivatives retain cost advantage in non-medical applications. Supply security depends on Southeast Asian plantation output and labor availability, with climatic volatility forcing automotive buyers toward synthetic alternatives.
- Thermoplastic Elastomers:Styrenic block copolymer architectures enable injection-molding compatibility in consumer electronics housings.
- Softening Agents:Phthalate alternatives dominate reformulation activity as REACH authorization bottlenecks delay legacy plasticizer market access.
Synthetic polyisoprene sits at the top of the volume ranking, with thermoplastic elastomers climbing the fastest.
End User:
Customer procurement maturity separates specification-heavy medical device makers from price-sensitive automotive compounders, with industrial buyers occupying a hybrid middle tier.
- Healthcare:Surgical glove manufacturers accelerate synthetic substitution under FDA protein-content thresholds. Device OEMs now require blockchain-anchored certificate-of-analysis systems, consolidating volumes with pre-validated suppliers.
- Automotive:OEM lightweighting mandates in Germany specify high-cis polyisoprene for fuel-efficiency-driven tire reformulations. Procurement consolidation among tire manufacturers realigns leverage toward compounders with integrated feedstock access.
- Consumer Goods:Recycling advantages and injection-molding compatibility drive thermoplastic elastomer penetration in electronics housings.
- Industrial Applications:Batch consistency requirements demand precision temperature control investments that legacy mixing equipment often cannot satisfy.
Automotive absorbs the largest share of tonnage, while healthcare expands most quickly.
Application:
Functional performance requirements stratify the market across Shore A hardness specifications, with medical devices demanding 30-90 range precision that adhesives and sealants rarely require.
- Medical Devices:Latex-allergy mitigation protocols accelerate synthetic polyisoprene adoption in surgical gloves and catheters. ISO 10993 testing capacity constraints extend qualification timelines, creating backlog advantages for compounders with in-house biocompatibility laboratories.
- Protective Equipment:Industrial glove manufacturers balance cost against protein-content thresholds, with synthetic grades gaining share in regulated European markets.
- Adhesives:Viscosity stability requirements favor synthetic grades in high-performance bonding applications.
- Sealants:Shore A hardness specifications vary widely by end-use, with automotive applications demanding higher mechanical strength.
Medical devices command the steepest expansion trajectory, with adhesives holding steady volume.
Distribution Channel:
Channel selection reflects customer scale and specification complexity, with direct relationships dominating medical grades and distributors serving fragmented industrial accounts.
- Direct Sales:Medical device OEMs in Germany and the United States require polymer traceability to monomer batch and catalyst lot. Direct relationships enable blockchain-anchored certificate-of-analysis systems that specification-driven procurement now mandates.
- Distributors:Regional stockholding reduces lead time risk for automotive compounders managing butadiene feedstock volatility. European distributors face REACH authorization complexity that favors specialized chemical handlers.
- Online Sales:Standard-grade synthetic polyisoprene sees transactional purchasing through digital platforms.
- Retail Outlets:Small-volume industrial buyers access softening agents and compounding additives through localized trade channels.
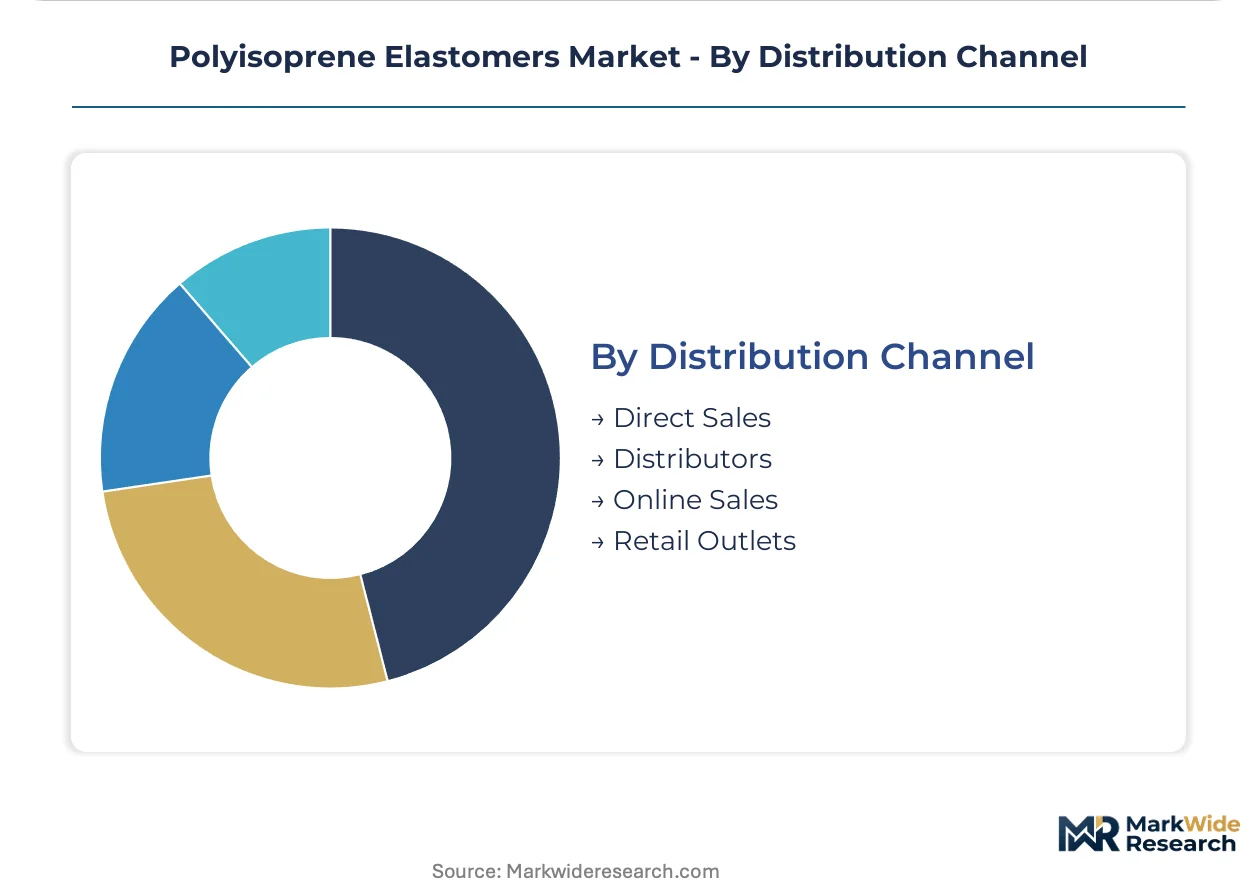
Direct sales captures the highest-value transactions, with distributor volumes expanding in automotive supply tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates specialized elastomer procurement for automotive and medical clusters, while the United States drives synthetic substitution through FDA protein-content thresholds. Japan maintains catalyst technology leadership. India and China expand domestic compounding capacity for export-platform manufacturing.
Germany
Automotive OEMs in Stuttgart and Munich specify high-cis polyisoprene for fuel-efficiency tire programs. REACH Annex XIV authorization requirements force reformulation of medical-grade compounds across Bavarian and Baden-Württemberg production sites. The Rhine-Ruhr industrial corridor anchors continental supply security for synthetic elastomer feedstocks.
United States
FDA guidance on biocompatibility accelerates synthetic polyisoprene adoption in surgical glove manufacturing. EPA emissions standards and OSHA workplace exposure limits shape process chemistry investments at Gulf Coast production facilities. Houston and Baton Rouge host integrated petrochemical complexes serving tire compounders with captive butadiene access.
Japan
Advanced Ziegler-Natta catalyst systems from Nagoya-area chemical engineering firms deliver viscosity consistency below 5% batch-to-batch variation. METI industrial standards govern medical elastomer qualification protocols for export markets. The Kansai region maintains specialized styrenic block copolymer research capacity for electronics applications.
India
CDSCO regulatory harmonization with ISO 13485 creates export-platform potential for latex-free elastomer suppliers in Maharashtra and Gujarat. The country's national pharmaceutical regulator tightens traceability mandates for surgical device materials. Chennai and Hyderabad medical device clusters source compounded grades from domestic toll manufacturers.
China
Solution polymerization capacity expansion in the Yangtze River Delta serves tire manufacturers seeking consistent viscosity alternatives to natural rubber. MIIT industrial policies favor domestic catalyst technology development for specialty elastomer grades. Qingdao and Shanghai host compounding operations supplying automotive OEMs with REACH-compliant export formulations.
Polyisoprene Elastomers Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across synthetic and natural polyisoprene supply tiers. The market structure concentrates volume among integrated petrochemical operators while fragmenting specialty grades across regional compounders. Three archetypes dominate: integrated feedstock players with backward naphtha-cracker control, catalyst technology licensors with process IP advantages, and medical-grade compounders with ISO 10993 pre-validation. Competitive moves center on captive butadiene capacity expansion and blockchain-anchored certificate-of-analysis systems for traceability-demanding medical accounts.
Within the integrated petrochemical tier, Sibur Holding and Nizhnekamskneftekhim exemplify players with regional supply security through captive monomer production. Kraton Corporation occupies a position among specialized architecture developers serving medical and industrial niches requiring styrenic block copolymer formulations. These three entities represent distinct strategic postures: Eurasian feedstock integration, Russian regional market anchoring, and US-based specialty polymer differentiation.
| Leading Market Players |
|---|
| Sibur Holding |
| ExxonMobil Chemical |
| Nizhnekamskneftekhim |
| Zeon Corporation |
| The Goodyear Tire & Rubber Company |
| Cariflex |
| JSR Corporation |
| LG Chem Ltd. |
| Kraton Corporation |
| Others |
Cost & Logistics Intelligence
Catalyst chemists concentrated in Japan's Nagoya industrial corridor command wage premiums that translate into 15-20 point spreads between medical-grade synthetic polyisoprene and commodity tire formulations. This labor-cost differential reinforces tiered pricing structures where Ziegler-Natta catalyst expertise anchors premium positioning.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-grade synthetic polyisoprene. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-validated medical batches from automotive commodity tiers. Cost compression in tire-grade synthetic polyisoprene is intensifying because naphtha-cracker output fluctuations feed butadiene volatility. Automotive compounders exhibit highest price sensitivity, while surgical glove manufacturers accept premium positioning for protein-free certification.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore form hub-and-spoke patterns serving medical device clusters. Supply concentrates in Germany, Japan, and China for Ziegler-Natta catalyst systems and solution polymerization output. Raw material flows draw from naphtha-cracker butadiene, Hevea brasiliensis latex, and specialized curative packages. Single-source vulnerability around Southeast Asian natural rubber plantations forces automotive buyers toward synthetic alternatives. Distribution runs through direct sales for medical grades and specialized chemical distributors for industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in polyisoprene elastomers rests on catalyst efficiency gains compressing production costs and medical-grade certification premiums widening. Ziegler-Natta process improvements and ISO 10993 pre-validation investments simultaneously drive cost-down and premium-tier capture.
For Market Incumbents: Cement feedstock security through captive butadiene capacity or long-term naphtha-cracker offtake agreements. Defend against emerging Chinese solution polymerization entrants by accelerating blockchain-anchored certificate-of-analysis deployment for medical accounts. Prioritize catalyst R&D partnerships with Nagoya-area engineering firms to sustain viscosity consistency advantages. For New Entrants and Emerging Players: Mid-sized Indian surgical device manufacturers represent an underserved buyer archetype seeking latex-free elastomer suppliers with CDSCO-aligned traceability. Capture share in Maharashtra and Gujarat medical device clusters by offering toll-compounding services with pre-validated ISO 10993-5 cytotoxicity documentation. Lead with regulatory harmonization expertise rather than price positioning. For Investors and Strategic Acquirers: Integrated petrochemical conglomerates are the most active acquirer in this space, seeking specialty elastomer capabilities to diversify from commodity polymer exposure. Five-to-ten year viability favors compounders with dual-track medical and automotive certification infrastructure. Watch for REACH Annex XIV authorization bottlenecks triggering consolidation among European medical-grade compounders lacking alternative curative portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Catalyst Technology Licensing | Japanese engineering firms monetize Ziegler-Natta stereospecificity IP across German tire qualification programs. |
| Backward Integration into Butadiene | Sibur Holding and Nizhnekamskneftekhim anchor margin defense through captive naphtha-cracker output. |
| Medical-Grade Pre-Validation Investment | ISO 10993-5 in-house testing capacity compresses qualification timelines for FDA protein-threshold compliance. |
| Blockchain Traceability Deployment | Certificate-of-analysis systems satisfy German device OEM requirements for monomer batch and catalyst lot tracking. |
| Green Chemistry Reformulation | Phthalate alternative curative packages secure REACH Annex XIV compliance for European surgical device supply chains. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged polymer plant managers, procurement leads at German automotive OEMs, distribution channel partners in Rotterdam and Singapore, technical R&D directors at catalyst licensors, and biomedical engineers at surgical glove manufacturers. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical conglomerates, and ECHA REACH authorization databases. Bottom-up volume modeling and top-down market sizing triangulated across these sources.
Historical reference periods anchored the projection horizon to established growth trajectories in synthetic rubber substitution and medical device material migration. Segmentation dimensions modeled include grade tier (medical-certified versus automotive commodity), end-use industry (healthcare, automotive, consumer goods, industrial), and regional production hub (Germany, United States, Japan, China, India). CAGRs derived from elasticity-adjusted demand curves incorporating tire OEM lightweighting mandates and FDA protein-content threshold enforcement. Industry-specific inputs encompassed Ziegler-Natta catalyst efficiency curves and ISO 10993 testing capacity expansion rates.
Underlying measurement precision varies by segment; medical-grade synthetic polyisoprene carries tighter precision than natural rubber commodity flows due to consolidated supplier bases and traceability mandates. Forecasts reflect documented assumptions around REACH authorization timelines, naphtha-cracker operating rates, and Southeast Asian plantation labor availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
Asia-Pacific Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Polyurethane Elastomers Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
Global Elastomeric Coating Market
Elastomeric Membrane
Polysulfide Elastomers Market
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Elastomeric Polyolefins Market
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Stretchable Conductive Material Market