
 Stretchable Conductive Material Market | 2026-2036
Stretchable Conductive Material Market Size, Share, and Industry Trends Forecast 2026-2036
Stretchable Conductive Material Market Intelligence
Buyer concentration in the wearable electronics sector is hardening as Apple, Samsung, and Garmin-scale OEMs consolidate supplier relationships around qualified stretchable conductor vendors. 3M leverages its adhesive-conductor hybrid platforms to anchor medical patch applications where skin-contact reliability commands premium positioning. DuPont competes through polyimide-silver composite films that sustain high-cycle flex performance in automotive interior sensors.
Stretchable conductive materials are electrically functional composites engineered to maintain conductivity beyond 20% tensile strain, typically incorporating silver nanowires, carbon nanotubes, or graphene networks within elastomeric matrices such as PDMS or PU. These materials enable circuit integration on curved, moving, or soft surfaces where conventional rigid conductors fracture. Silver nanowires dominate current commercial supply due to established coating compatibility and low percolation thresholds, while graphene formulations represent the fastest-growing technology segment as production costs decline and batch consistency improves. Inkjet printing occupies the leading manufacturing method for prototyping and small-series medical devices, whereas screen printing sustains cost advantages in high-volume smart textile production.
The EPA regulates silver nanomaterial discharge under TSCA Section 5 premanufacture notification requirements, while REACH in Europe mandates full substance registration for imported conductive inks above one-tonne annual thresholds. FDA device regulations for skin-contact electrodes additionally shape biomedical sensor market access through biocompatibility testing protocols. Stakeholders must monitor evolving nanomaterial classification debates at OECD and national environmental agencies that could reclassify production waste streams and trigger new compliance investments.
Market Dynamics
Silver nanowire supply concentration in South Korean and Chinese chemical clusters is forcing wearable OEMs to diversify qualified material sources as geopolitical friction disrupts just-in-time conductor procurement.
Growth Catalysts
- EU Green Deal material mandates:REACH compliance deadlines are accelerating substitution of conventional tin-lead conductors in medical patches toward silver-elastomer composites.
- Health monitoring wearables:Continuous glucose monitor manufacturers are expanding stretchable electrode procurement for skin-conformable biosensors.
- Graphene production scale-up:CVD synthesis cost reductions below $50 per gram are unlocking textile-integrated heating applications previously blocked by nanowire pricing.
Market Restraints
- Silver price volatility:Spot metal fluctuations above 20% annually compress conductor gross margins and deter long-term supply contracts.
- Nanomaterial registration thresholds:ECHA REACH one-tonne substance registration requirements create compliance cliffs for specialty ink formulators serving European medical device clients.
- Percolation threshold physics:Carbon nanotube networks require 3-5x filler loading versus silver nanowires to achieve equivalent conductivity, inflating elastomer matrix costs.
Strategic Opportunities
- Soft robotics actuation:Stretchable strain sensors for pneumatic artificial muscles in warehouse automation represent an underpenetrated demand vertical outside consumer electronics.
- India PLI scheme incentives:Electronics manufacturing clusters in Tamil Nadu and Karnataka offer capital subsidies for conductive material localization serving domestic wearable assembly.
- Automotive interior sensing:Pressure-mapping seat sensors and steering-wheel health monitors are emerging as high-specification outlets for cyclic-flex-rated conductor films.
Industry Challenges
- Biocompatibility certification timelines:FDA 510(k) pathways for skin-contact electrodes average 14-18 months, delaying revenue recognition for novel material formulations.
- Cross-functional talent scarcity:Hybrid electrochemist-polymer engineers capable of optimizing nanofiller dispersion in PDMS matrices command 40% salary premiums over conventional materials scientists.
- Legacy screen-printing asset stranding:Textile manufacturers face capital write-downs as inkjet and aerosol jet methods displace rotary screens for fine-feature stretchable circuits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stretchable Conductive Material Market |
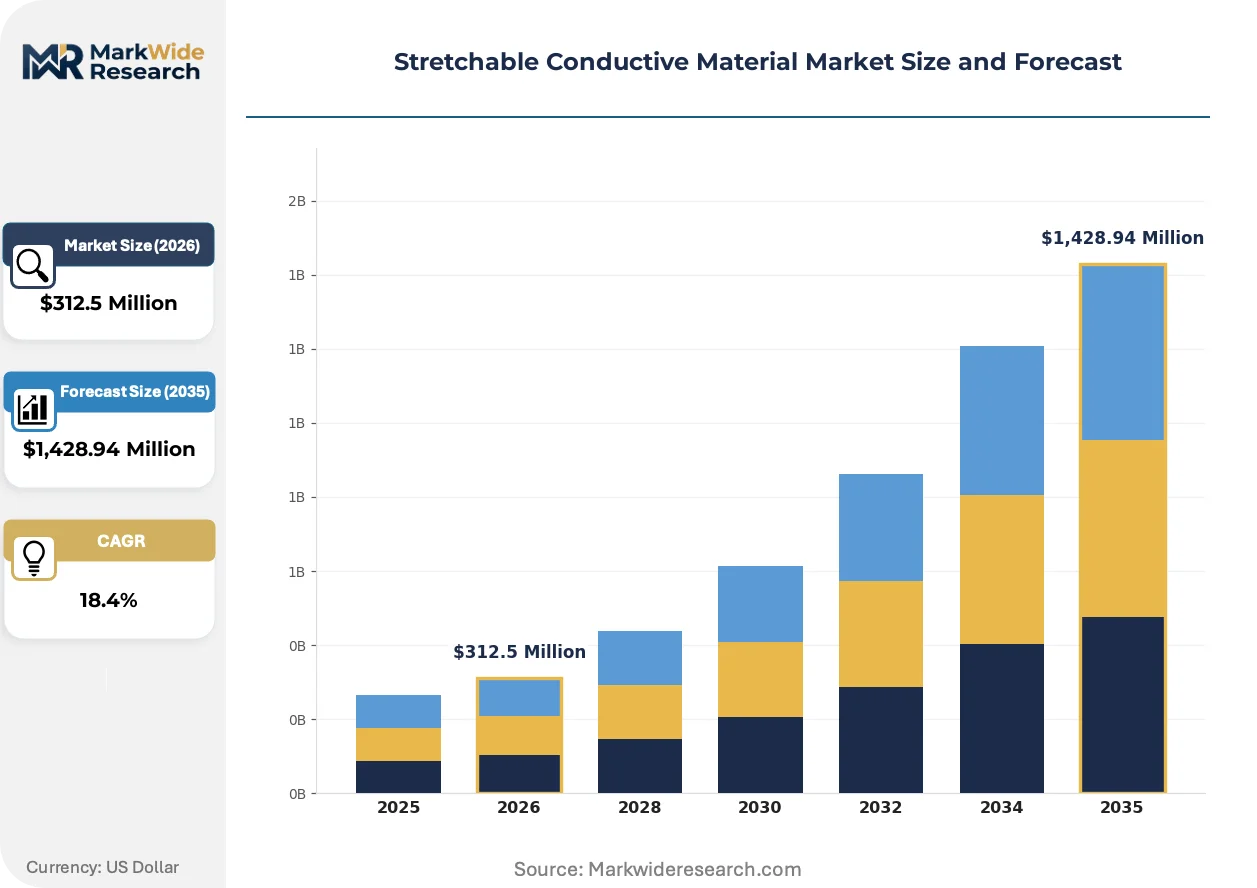
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,428.94 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver Nanowires, Carbon Nanotubes, Conductive Polymers, Graphene Application: Wearable Devices, Flexible Displays, Biomedical Sensors, Smart Textiles Technology: Screen Printing, Inkjet Printing, Spray Coating, 3D Printing End User: Electronics, Healthcare, Automotive, Aerospace |
| Companies Covered | 3M, DuPont, ANP Corporation, Applied Nanotech, Toyobo Co., Indium Corporation, CHASM, Vorbeck Materials, Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stretchable Conductive Material Market Strategic Shifts & Innovations
Manufacturing process innovation is compressing prototyping cycles while regulatory frameworks and procurement patterns are restructuring how conductive materials reach end-use applications.
Aerosol jet printing is decentralizing stretchable circuit production by enabling direct-write metallization onto 3D elastomer surfaces without photomask tooling. Medical device startups in Boston and Berlin are adopting tabletop systems for rapid electrode iteration, collapsing traditional 12-week tooling cycles to 72-hour turnaround. This capability is fragmenting the supplier base as in-house prototyping displaces centralized foundry relationships.
REACH Annex XVII restrictions on nickel release are tightening specifications for skin-contact conductive textiles across European markets. The regulation is forcing textile finishers to abandon nickel-carbon coatings in favor of silver-polyurethane composites, triggering reformulation costs exceeding €200,000 per product line. German automotive seat suppliers and Italian smart apparel manufacturers are accelerating qualification timelines to meet 2026 enforcement windows.
Contract manufacturers are consolidating purchase orders into annual volume commitments to secure allocation from qualified nanowire suppliers. Tier-one EMS providers in Shenzhen and Guadalajara are displacing spot-market spot buying with master service agreements indexed to silver London Metal Exchange pricing. This shift is visible most acutely in continuous glucose monitor production, where FDA-registered material lots require 18-month supply continuity guarantees.
Stretchable Conductive Material Market Segmentation
Stretchable conductive materials serve divergent performance requirements across medical patches, automotive sensors, and consumer wearables. Segmentation reveals how silver nanowire formulations dominate skin-contact applications while graphene climbs fastest in textile heating. Manufacturing method selection—screen versus inkjet versus aerosol jet—determines which material systems achieve commercial scale.
Product Type:
Conductivity mechanisms and strain tolerance separate these four material platforms, with filler geometry and matrix compatibility driving procurement decisions.
- Silver Nanowires:These metallic nanostructures achieve percolation at low filler loadings within PDMS or polyurethane matrices, enabling transparent conductors for touch-sensitive medical patches. Demand concentrates in continuous glucose monitor electrodes where FDA-registered biocompatibility commands premium sourcing from South Korean chemical clusters.
- Graphene:CVD-synthesized graphene networks deliver exceptional thermal conductivity for textile-integrated heating elements, though batch consistency remains variable. Expansion concentrates in German automotive seat warming applications where REACH nickel-release restrictions have eliminated legacy metal-carbon coatings.
- Carbon Nanotubes:These cylindrical carbon structures require elevated filler fractions to match silver nanowire conductivity, limiting adoption to cost-tolerant aerospace strain sensing.
- Conductive Polymers:PEDOT:PSS formulations offer intrinsic stretchability without nanofiller dispersion challenges, finding niche use in disposable electrocardiogram patches.
Mature deployment sits with silver nanowires. Newer deployment is concentrated in graphene.
Application:
End-use environments dictate material specifications, with cyclic flex requirements and skin-contact certification creating divergent qualification barriers.
- Wearable Devices:Smartwatch bands and fitness trackers integrate stretchable interconnects to maintain signal integrity during wrist flexion. Apple and Samsung-scale OEMs consolidate procurement around qualified silver-elastomer suppliers capable of 18-month supply continuity guarantees.
- Biomedical Sensors:Skin-conformable electrodes for cardiac monitoring and glucose detection require ISO 10993 biocompatibility certification. FDA 510(k) timelines averaging 14-18 months delay revenue recognition for novel formulations.
- Flexible Displays:Foldable smartphone hinge circuits demand conductors surviving 200,000+ bend cycles, a specification straining carbon nanotube durability.
- Smart Textiles:Conductive yarns for heated apparel and capacitive touch fabrics integrate silver-polyurethane composites to satisfy ECHA nickel-release restrictions.
Volume concentration rests in wearable devices. Steepest expansion trajectory belongs to biomedical sensors.
Technology:
Deposition precision and tooling amortization separate these manufacturing approaches, with feature resolution requirements determining method selection.
- Screen Printing:Rotary screen systems sustain cost advantages in high-volume smart textile production, though minimum feature sizes limit circuit density. Italian apparel manufacturers and German automotive seat suppliers rely on this method for nickel-free conductive patterning.
- Inkjet Printing:Drop-on-demand systems enable rapid prototyping without photomask tooling, collapsing iteration cycles from 12 weeks to 72 hours. Boston and Berlin medical device startups deploy tabletop systems for electrode development.
- Spray Coating:Airbrush-deposited nanowire networks conform to 3D elastomer surfaces for pneumatic soft robotics actuation.
- 3D Printing:Direct-write extrusion of conductive composites enables embedded circuit architectures for structural electronics.
Production scale favors screen printing. Capability investment is shifting toward inkjet.
End User:
Industry-specific certification regimes and performance specifications fragment demand across these four verticals.
- Electronics:Consumer wearable OEMs drive the largest procurement volumes, with tier-one EMS providers in Shenzhen consolidating annual purchase commitments indexed to London Metal Exchange silver pricing.
- Healthcare:Skin-contact electrode manufacturers face FDA biocompatibility and ECHA REACH substance registration requirements, creating compliance cliffs above one-tonne annual import thresholds.
- Automotive:Pressure-mapping seat sensors and steering-wheel health monitors demand cyclic-flex-rated conductors surviving temperature extremes from NHTSA safety validation.
- Aerospace:Structural health monitoring applications tolerate elevated costs for carbon nanotube strain sensors in wing deformation detection.
Procurement volume concentrates in electronics. Regulatory complexity peaks in healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wearable OEM procurement concentrates in three electronics manufacturing clusters where qualified conductor suppliers maintain FDA-registered production lines. Germany, South Korea, and the United States anchor commercial demand through biomedical research hubs and consumer electronics assembly ecosystems.
United States
Continuous glucose monitor manufacturers in the Greater Boston corridor drive silver-elastomer electrode procurement for FDA-cleared skin-contact biosensors. EPA TSCA Section 5 premanufacture notification requirements govern silver nanomaterial import volumes above specified thresholds. Stanford and MIT research partnerships in California and Massachusetts accelerate aerosol jet printing adoption for rapid medical device prototyping.
Germany
Automotive seat suppliers in Baden-Württemberg integrate graphene-based heating elements to satisfy REACH Annex XVII nickel-release restrictions. ECHA substance registration mandates above one-tonne annual thresholds shape conductive ink formulation strategies for European medical device clients. The Stuttgart electronics cluster hosts qualification programs for cyclic-flex-rated conductor films in pressure-mapping sensor applications.
South Korea
Samsung-scale OEMs consolidate supplier relationships around qualified silver nanowire vendors capable of 18-month supply continuity guarantees. MFDS biocompatibility protocols align with FDA standards for exported medical patch components. Seoul Capital Area chemical clusters dominate global silver nanowire production capacity, forcing wearable manufacturers to diversify qualified material sources amid geopolitical procurement friction.
China
Shenzhen EMS providers displace spot-market purchasing with master service agreements indexed to London Metal Exchange silver pricing. MIIT standards for flexible electronic components intersect with GB nanomaterial safety classifications for domestic wearable assembly. Yangtze River Delta textile manufacturers face capital write-downs as inkjet methods displace rotary screens for fine-feature stretchable circuits.
India
Electronics manufacturing clusters in Tamil Nadu and Karnataka attract PLI scheme capital subsidies for conductive material localization serving domestic wearable assembly. CDSCO medical device regulations create parallel compliance pathways for skin-contact electrode imports. Bangalore biomedical startups pilot PEDOT:PSS formulations in disposable cardiac monitoring applications.
Stretchable Conductive Material Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue graphene scale-up and aerosol jet printing capabilities. The supplier base organizes around three archetypes: diversified materials conglomerates with adhesive-conductor hybrid platforms, nanomaterial specialists controlling silver nanowire synthesis, and regional chemical companies serving qualified foundry relationships. Competitive moves center on backward integration into nanowire production and geographic expansion through qualified material registration in multiple regulatory jurisdictions.
Within the diversified conglomerate tier, 3M and DuPont exemplify positioning through adhesive-conductor hybrid platforms and polyimide-silver composite films respectively. ANP Corporation anchors the nanomaterial specialist archetype with South Korean chemical cluster origins. These three occupy positions spanning medical patch reliability specifications and automotive cyclic-flex requirements without overlapping core technology claims.
| Leading Market Players |
|---|
| 3M |
| DuPont |
| ANP Corporation |
| Applied Nanotech |
| Toyobo Co. |
| Indium Corporation |
| CHASM |
| Vorbeck Materials |
| Henkel |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between FDA-registered biocompatibility tiers and commodity conductive inks manifests in both pricing power concentration and supply chain qualification barriers. Premium silver-elastomer formulations for skin-contact medical patches command sustained margin premiums through 18-month supply continuity guarantees, while unregistered inkjet formulations compete on spot-market silver pricing with minimal buyer loyalty.
Pricing Analysis
Volume-margin splits sharply across the value stack: high-volume smart textile production runs on contract-indexed silver pricing with thin conversion margins, while low-volume medical patch electrodes sustain premium positioning through ISO 10993 certification tiers. Price differentiation rests on FDA registration status and REACH substance registration completion, with unregistered formulators facing 40% price discounts against qualified competitors. Cost compression in the textile tier intensifies as rotary screen manufacturers absorb capital write-downs from inkjet displacement. Electronics OEMs in Shenzhen exhibit highest price sensitivity through consolidated annual purchase commitments, whereas Boston medical device startups accept 25-30% premiums for rapid-turn aerosol jet prototyping services.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Chinese silver nanowire chemical clusters, where three producers control qualified material flows for FDA-registered medical applications. Raw material dependencies span silver bullion from London Metal Exchange contracts, PDMS elastomer precursors from German chemical suppliers, and graphene feedstock from CVD synthesis facilities in Germany and the United States. Tariff exposure on Chinese nanomaterial imports is forcing wearable OEMs to dual-source from emerging Indian PLI-subsidized clusters in Tamil Nadu. Distribution runs through tier-one EMS providers in Shenzhen and Guadalajara that consolidate purchase orders into master service agreements with 12-month volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around qualified material registration, with REACH one-tonne substance thresholds and FDA 510(k) timelines forcing specialty ink formulators without certification depth toward distressed exit.
For Market Incumbents: Hedge silver price volatility through backward integration into nanowire synthesis or captive long-term offtake agreements indexed to London Metal Exchange pricing. Defend medical patch positioning by accelerating biocompatibility certification for next-generation glucose monitor electrodes before emerging graphene suppliers achieve batch consistency breakthroughs. Capacity addition in Indian PLI-subsidized clusters offers geographic diversification against geopolitical procurement friction. For New Entrants and Emerging Players: Aerosol jet printing capability for rapid medical device prototyping represents the most penetrable white-space target, with Boston and Berlin startups demanding 72-hour electrode iteration cycles that centralized foundries cannot match. Soft robotics actuation for warehouse automation strain sensors offers a second underpenetrated vertical outside consumer electronics saturation. Go-to-market execution should anchor on tabletop system leasing with technical training bundles rather than capital equipment sales. For Investors and Strategic Acquirers: Re-rating potential sits with nanomaterial specialists controlling captive silver nanowire synthesis given EU Green Deal substitution mandates accelerating tin-lead conductor displacement. Long-term viability across the analysis window favors qualified suppliers with multi-jurisdiction registration footprints spanning FDA, ECHA REACH, and MFDS protocols. Watch for aerosol jet printing adoption inflection in medical device startup clusters as signal of decentralized production tipping point.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nanowire Synthesis | Captive silver nanowire production insulates margin compression from London Metal Exchange spot volatility. |
| FDA 510(k) Parallel Track Submission | Dual glucose monitor and cardiac electrode pathways accelerate revenue recognition for novel elastomer formulations. |
| Indian PLI Localization Partnership | Tamil Nadu cluster subsidies reduce tariff exposure on Chinese nanomaterial imports for domestic wearable assembly. |
| Aerosol Jet Printing Capability Acquisition | Direct-write metallization systems collapse medical device prototyping cycles from 12 weeks to 72 hours. |
| REACH Annex XVII Nickel-Free Reformulation | Silver-polyurethane composites satisfy 2026 enforcement windows for German automotive seat suppliers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with nanomaterial synthesis plant managers, procurement leads at wearable OEMs, biomedical engineers at continuous glucose monitor manufacturers, and distribution channel partners serving qualified foundry relationships. FDA 510(k) databases, ECHA REACH registration portals, SEC 10-K disclosures from diversified materials conglomerates, and MIIT flexible electronics standards provided cross-referenced validation points. Bottom-up demand modeling across silver nanowire, graphene, carbon nanotube, and conductive polymer product tiers triangulated against top-down electronics and healthcare spending projections.
Data-stream reconciliation between volume-based production capacity assessments and value-based procurement contract analysis informed the analytical framework across the analysis window. Segmentation dimensions spanned filler material chemistry, deposition technology method, end-use application requirements, and regional regulatory cluster intensity. CAGRs derived from weighted average of historical capacity expansion rates and forward-looking OEM procurement commitment visibility. Industry-specific forecast inputs incorporated silver price volatility bands and REACH registration timeline probability distributions.
Several conditions sit outside the modeled scope, including potential OECD nanomaterial reclassification of production waste streams and unannounced FDA guidance revisions for skin-contact electrode biocompatibility protocols. Forecasts reflect documented assumptions regarding sustained EU Green Deal enforcement momentum and continued South Korean chemical cluster production stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Hot Cast Elastomers Market
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
North America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Butyl Elastomers Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
South America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
North America Performance Elastomer Market
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Global Flexible Elastomeric Foam Market
Elastomeric Membrane
Elastic Laminates Market
Elastomeric Membrane
Modified Silicone Fluids Market
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market