
 High Viscosity Mixer Market | 2026-2036
High Viscosity Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
High Viscosity Mixer Market Insights
Pharmaceutical manufacturing is hardening its position as the dominant demand vertical for high viscosity mixers, overtaking traditional paints and coatings buyers who now face margin compression from raw material volatility. Charles Ross & Son leverages its planetary mixer specialization to anchor the North American pharmaceutical equipment segment. EKATO Holding dominates European reactor-mixer integration through its process engineering heritage. Silverson Machines competes aggressively in inline high-shear applications where batch time reduction commands premium positioning.
High viscosity mixers are industrial machines engineered to blend materials with dynamic viscosities exceeding 10,000 centipoise, employing intermeshing blades, planetary motion, or static elements to overcome laminar flow limitations and achieve homogeneous dispersion in non-Newtonian fluids. Planetary mixers lead the product type landscape due to their dual-axis motion handling highly filled adhesives and dental compounds, while sigma blade mixers sustain entrenched positions in chewing gum base and heavy rubber processing where trough-style kneading remains irreplaceable. Dual shaft mixer adoption is accelerating in cosmetics formulation as emulsion stability requirements tighten and batch flexibility becomes a structural priority for contract manufacturers serving multiple beauty brands.
FDA process validation guidelines and OSHA combustible dust standards shape equipment design mandates in the United States, forcing mixer vendors to integrate explosion-proof motors and validated cleaning protocols. The EU Machinery Directive and ATEX certification requirements impose parallel conformity burdens on European suppliers, while China's GB standards for food-contact equipment create divergent testing obligations for multinational manufacturers. Stakeholders must monitor how biologics pipeline expansion and green chemistry regulatory pushes in multiple jurisdictions will reshape equipment specifications before the next replacement cycle consolidates.
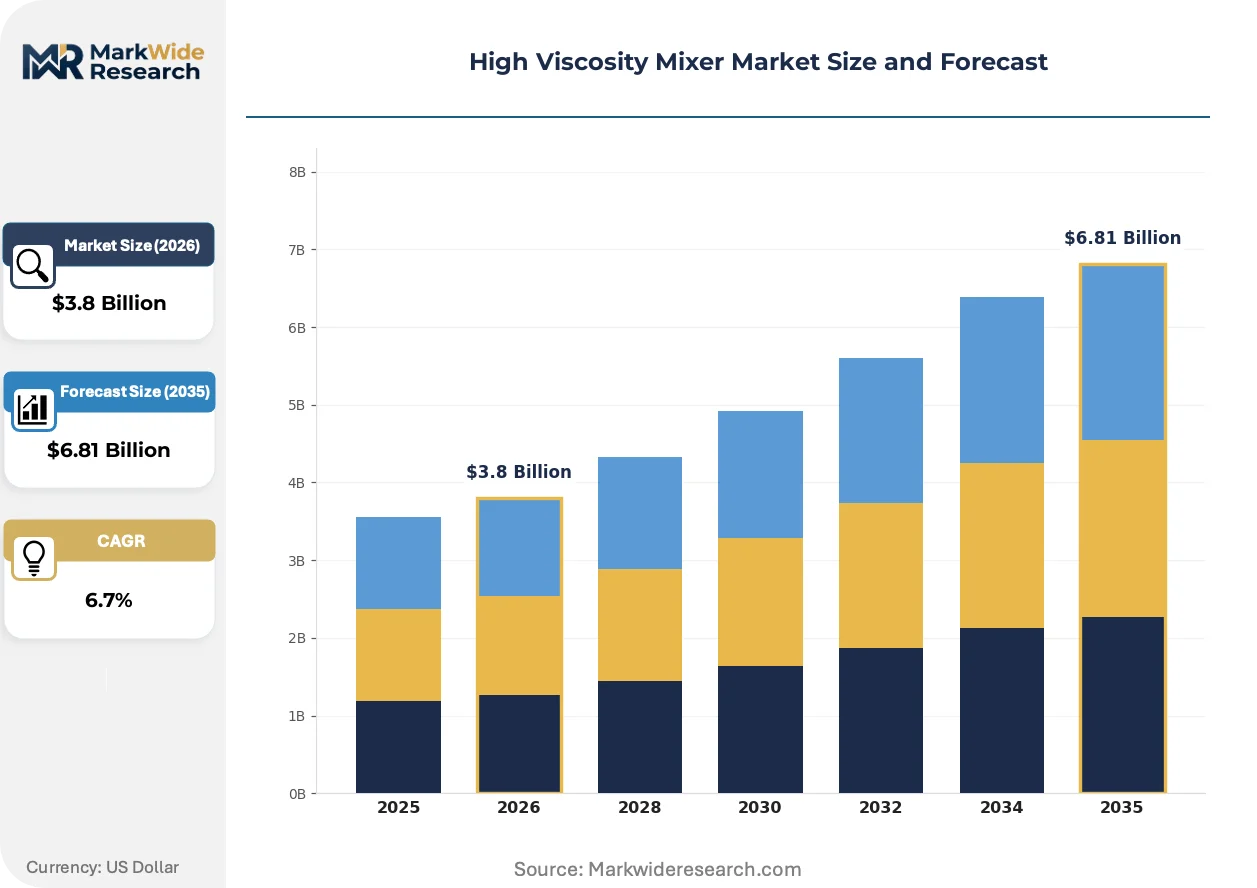
Market Dynamics
Biologics formulation complexity is forcing pharmaceutical manufacturers to replace legacy batch equipment with precision planetary mixers capable of handling shear-sensitive monoclonal antibody suspensions and lipid nanoparticle emulsions. This equipment upgrade cycle is compressing replacement timelines from ten-year intervals to five-to-seven-year cycles as FDA process validation standards tighten traceability requirements.
Growth Catalysts
- REACH compliance deadlines:European chemical manufacturers are retrofitting sigma blade systems with sealed trough designs and vapor recovery to meet ECHA emissions thresholds for volatile organic compounds in adhesive production.
- Biologics pipeline expansion:Contract development and manufacturing organizations are adding dual-shaft mixers with jacketed vessels to handle temperature-critical cell culture media preparation for gene therapy vectors.
- Chewing gum base processing:Concentrated demand from Wrigley and Mondelez suppliers in the US Midwest is sustaining replacement orders for heavy-duty sigma blade kneaders with enhanced torque transmission.
Market Restraints
- Stainless steel price volatility:Input cost swings for 316L and 304-grade alloys are compressing margins for custom-fabricated planetary mixer vessels, particularly affecting small-batch pharmaceutical equipment builders.
- Specialized gearbox supply concentration:Precision planetary drive systems rely on German and Japanese precision gear manufacturers, creating vulnerability to extended lead times during automotive sector demand spikes.
- Clean-in-place validation burden:FDA guidance on residual active pharmaceutical ingredient limits is extending commissioning timelines for new installations, delaying revenue recognition for equipment vendors.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's accelerated approval pathways for biosimilars are attracting greenfield investments in Hyderabad and Ahmedabad, creating demand for explosion-proof planetary mixers with ASME-certified pressure vessels.
- Green chemistry solvent transitions:EU Green Deal mandates on bio-based raw materials are forcing coatings formulators to retool sigma blade systems for higher-viscosity alkyd and polyurethane dispersions.
- Remote monitoring convergence:Integration of IoT vibration sensors with legacy mixer motors is enabling predictive maintenance contracts that capture recurring revenue from chemical plant operators.
Industry Challenges
- ATEX certification bottlenecks:Third-party notified body backlogs for explosion-proof motor certifications are extending delivery schedules for European pharmaceutical projects by four to six months.
- Legacy DCS integration complexity:Brownfield chemical plants require custom protocol bridges to connect modern mixer variable frequency drives with aging distributed control systems from the 1990s.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Viscosity Mixer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Planetary Mixer, Static Mixer, Dual Shaft Mixer, Sigma Blade Mixer, Ribbon Mixer Technology: Mechanical Agitation, Hydraulic Mixing, Pneumatic Mixing, Electromagnetic Mixing Application: Adhesives Production, Chemical Processing, Cosmetics Formulation, Food Processing, Polymer Blending End User Industry: Chemical Manufacturing, Cosmetics & Personal Care, Food & Beverage, Paints & Coatings |
| Companies Covered | Charles Ross & Son, IKA, NETZSCH, FlackTek, Silverson Machines, EKATO Holding, SPX FLOW, GEA Group, Bühler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Viscosity Mixer Market Trends and Innovations
Equipment intelligence and modular vessel architecture are converging to reshape how high viscosity mixers are specified, commissioned, and operated across pharmaceutical and specialty chemical installations. These shifts are compressing the traditional boundaries between mechanical design, process control, and regulatory compliance.
Continuous processing technology is overtaking conventional batch planetary mixers in monoclonal antibody formulation suites. Twin-screw extruder-mixer hybrids from pharma-focused equipment builders are capturing new installations at Merck and Bristol-Myers Squibb facilities, enabling real-time quality release and reducing hold times from days to hours. This architecture is compressing facility footprints and displacing multiple discrete unit operations.
REACH authorization requirements for chromium trioxide in surface treatments are forcing European mixer manufacturers to transition to laser-clad vessel coatings and electropolished finishes. The industrial consequence is a 15-20% cost premium on pharmaceutical-grade equipment that must demonstrate zero metallic ion leaching. German and Swiss suppliers are responding fastest, leveraging existing relationships with BASF and Lonza to validate alternative surface engineering.
Contract manufacturers are unbundling after-sales service from equipment purchase contracts, opting instead for third-party maintenance providers with multi-vendor capabilities. This procurement pattern is disrupting the traditional captive service model of established mixer builders, particularly visible in the US Northeast where independent validation specialists now handle IQ/OQ protocols for multiple pharmaceutical CDMOs. Equipment vendors are responding with remote diagnostics subscriptions to retain customer touchpoints.
High Viscosity Mixer Market Segmentation
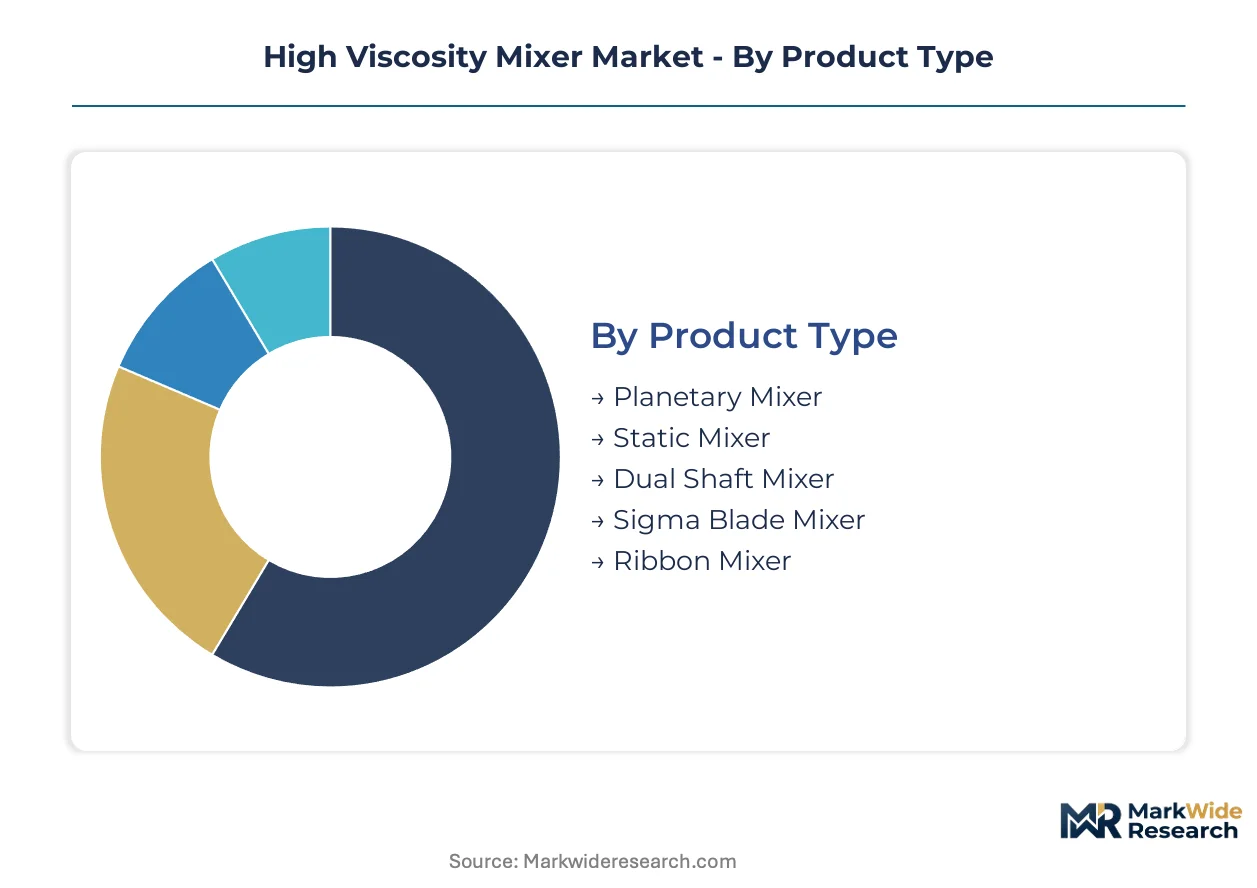
High viscosity mixer procurement patterns diverge sharply between standalone batch installations and integrated continuous processing lines. Equipment specification decisions cascade from product rheology requirements through regulatory compliance burdens to total cost of ownership calculations across multi-year replacement cycles.
Product Type:
Integration depth varies substantially across mixer architectures, with some designs functioning as isolated batch units while others embed within automated production trains.
- Planetary Mixer:Dual-axis orbital motion generates complex flow patterns essential for highly filled adhesives and dental compounds with viscosities exceeding 100,000 centipoise. Pharmaceutical manufacturers in Germany and Switzerland specify these for monoclonal antibody suspensions where shear control prevents protein denaturation. FDA process validation requirements are compressing replacement intervals from ten years to five-to-seven years as traceability mandates tighten.
- Sigma Blade Mixer:Intermeshing Z-shaped blades in trough-style vessels deliver intensive kneading action irreplaceable for chewing gum base and heavy rubber processing. Concentrated demand from Wrigley and Mondelez suppliers in the US Midwest sustains replacement orders for enhanced torque transmission systems. REACH compliance deadlines are forcing sealed trough retrofits with vapor recovery for ECHA emissions thresholds.
- Static Mixer:Fixed geometric elements within pipeline housings enable continuous blending without moving parts, suited for inline polymer compounding where space constraints dominate.
- Dual Shaft Mixer:Independent high-speed disperser and low-speed anchor configurations optimize emulsion stability in cosmetics contract manufacturing serving multiple beauty brands.
- Ribbon Mixer:Helical ribbon agitators on single shafts handle moderate-viscosity dry-to-paste transitions in food seasoning and bakery premix applications.
Volume placements concentrate in sigma blade systems for established rubber and confectionery processing; the faster expansion belongs to planetary mixers capturing biologics formulation demand.
Technology:
Cost tier stratification separates premium precision drive systems from commodity motor configurations, with price spreads reflecting torque density and control sophistication.
- Mechanical Agitation:Gear-driven shaft rotation dominates installed base economics through proven reliability in 24/7 chemical plant operation. German and Japanese precision gear manufacturers supply planetary drive systems where automotive sector demand spikes create extended lead time vulnerabilities. Stainless steel price volatility for 316L and 304-grade alloys compresses margins for custom-fabricated vessels.
- Hydraulic Mixing:Fluid power transmission delivers variable torque at constant speed for heavy-duty sigma blade kneaders processing viscoelastic materials. Paints and coatings manufacturers facing raw material margin compression prioritize these systems for alkyd and polyurethane dispersion flexibility under EU Green Deal mandates.
- Pneumatic Mixing:Compressed air-driven agitation serves explosion-critical environments in solvent-based adhesive production requiring ATEX certification.
- Electromagnetic Mixing:Contactless magnetic coupling eliminates seal wear in sterile pharmaceutical applications demanding zero metallic ion leaching validation.
Premium positioning clusters around electromagnetic and hydraulic configurations; mechanical agitation retains volume dominance through replacement parts economics.
Application:
Customer type fragmentation separates multinational formulators with centralized engineering standards from regional contract manufacturers prioritizing batch flexibility.
- Adhesives Production:Hot-melt and reactive adhesive compounding requires precise temperature control through jacketed vessels handling viscosity transitions from 500 to 500,000 centipoise. Specialty chemical clusters around Ludwigshafen and Leverkusen drive replacement cycles for industrial-grade planetary and sigma blade systems. REACH authorization requirements for chromium trioxide surface treatments force transitions to laser-clad vessel coatings with 15-20% cost premiums.
- Cosmetics Formulation:Emulsion stability requirements for skincare and color cosmetics tighten as clean beauty claims proliferate. Contract manufacturers unbundle after-sales service from equipment purchase contracts, opting for third-party maintenance providers with multi-vendor capabilities across the US Northeast.
- Chemical Processing:Specialty chemical and agrochemical intermediate production integrates mixers within reactor-mixer hybrid systems for complex multi-step syntheses.
- Food Processing:Chocolate conching, nut butter grinding, and dough development require hygienic design certifications with CIP validation protocols.
- Polymer Blending:Masterbatch compounding and reactive extrusion favor twin-screw extruder-mixer hybrids displacing conventional batch equipment.
Established volume concentrates in adhesives and chemical processing; cosmetics formulation gains share fastest through CDMO facility expansion.
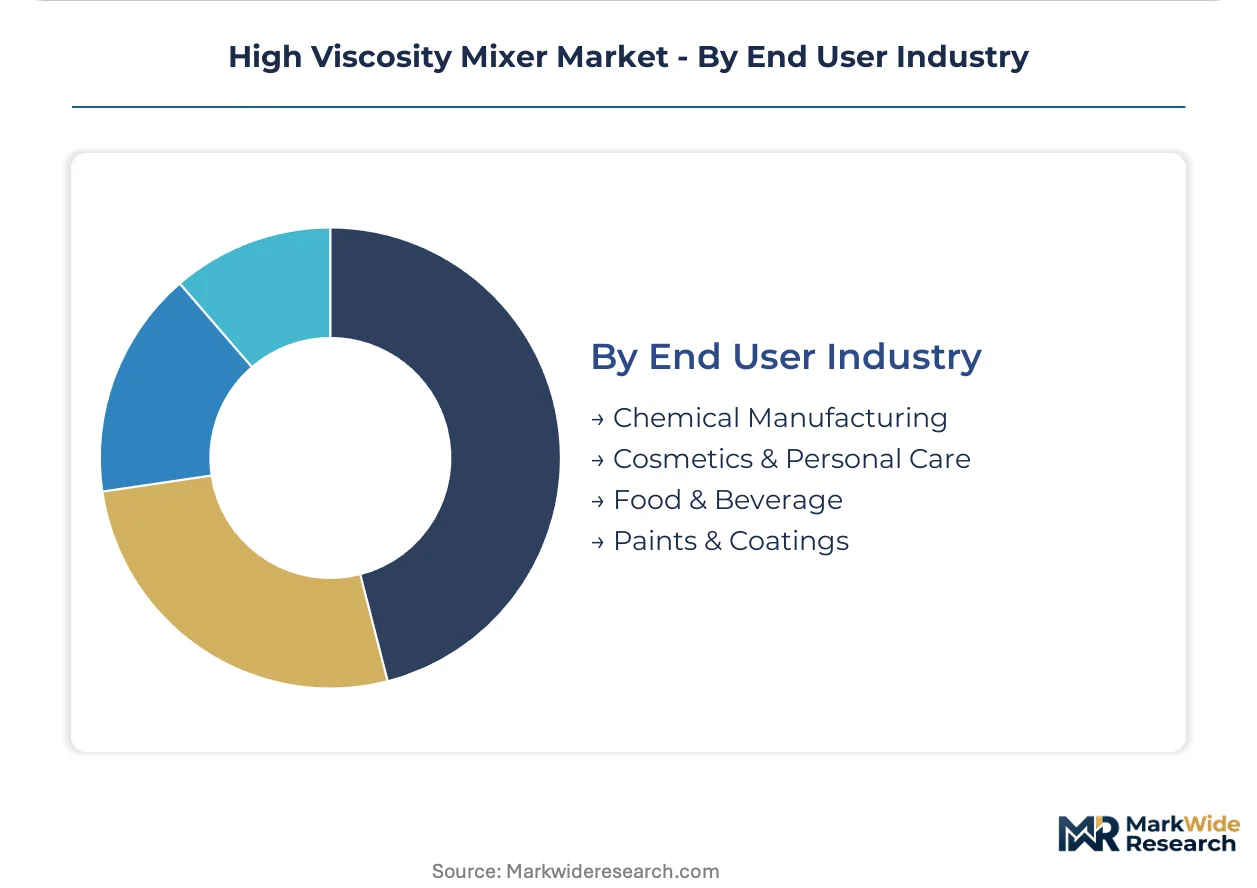
End User Industry:
Maturity differentiation separates regulated pharmaceutical-adjacent sectors with validation burdens from commodity industrial applications competing on throughput metrics.
- Chemical Manufacturing:Specialty and commodity chemical producers specify explosion-proof motors and validated cleaning protocols under OSHA combustible dust standards and FDA guidance on residual active pharmaceutical ingredient limits. Brownfield plants require custom protocol bridges connecting modern variable frequency drives with aging distributed control systems from the 1990s.
- Cosmetics & Personal Care:Clean beauty and sustainability claims drive equipment upgrades for bio-based raw material processing. EU Green Deal mandates on solvent transitions force sigma blade system retooling for higher-viscosity alkyd and polyurethane dispersions.
- Food & Beverage:China's GB standards for food-contact equipment create divergent testing obligations for multinational manufacturers supplying confectionery and sauce processing lines.
- Paints & Coatings:Raw material volatility compresses margins for traditional buyers now prioritizing equipment utilization rates over specification upgrades.
Replacement cycle stability characterizes chemical manufacturing; cosmetics and personal care demonstrates the steepest expansion trajectory through formulation outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates high viscosity mixer production capacity through precision engineering heritage, while the United States and China absorb disproportionate demand from pharmaceutical and chemical manufacturing expansion. This production-consumption divide shapes regional equipment specification standards and regulatory compliance burdens.
Germany
Specialty chemical clusters around Ludwigshafen and Leverkusen drive replacement cycles for industrial-grade planetary and sigma blade systems. REACH authorization requirements for chromium trioxide surface treatments force transitions to laser-clad vessel coatings with 15-20% cost premiums. German precision gear manufacturers supply planetary drive systems where automotive sector demand spikes create extended lead time vulnerabilities.
United States
Contract development and manufacturing organizations add dual-shaft mixers with jacketed vessels for temperature-critical cell culture media preparation. FDA process validation guidelines and OSHA combustible dust standards force mixer vendors to integrate explosion-proof motors and validated cleaning protocols. Concentrated demand from Wrigley and Mondelez suppliers in the US Midwest sustains replacement orders for heavy-duty sigma blade kneaders.
China
GB standards for food-contact equipment create divergent testing obligations for multinational manufacturers supplying confectionery and sauce processing lines. Domestic pharmaceutical equipment demand concentrates in Yangtze River Delta biomanufacturing hubs. Local fabricators compete on cost for standard mechanical agitation systems while imported precision planetary mixers serve biologics formulation.
India
CDSCO's accelerated approval pathways for biosimilars attract greenfield investments in Hyderabad and Ahmedabad. These facilities create demand for explosion-proof planetary mixers with ASME-certified pressure vessels. Contract manufacturers unbundle after-sales service from equipment purchase contracts, opting for third-party maintenance providers with multi-vendor capabilities.
Switzerland
Swissmedic pharmaceutical manufacturing standards drive specification for zero metallic ion leaching validation. Swiss suppliers leverage existing relationships with Lonza and other contract manufacturers to validate alternative surface engineering. Precision equipment exports from Basel-region fabricators serve German and French pharmaceutical installations.
High Viscosity Mixer Market Competitive Landscape
Top-tier vendors anchor the precision pharmaceutical equipment segment, while mid-scale fabricators compete on customization speed and regional service proximity. The vendor base stratifies across three tiers: multinational process engineering conglomerates with reactor-mixer integration capabilities, specialized mechanical equipment builders with planetary mixer heritage, and regional fabricators serving commodity chemical applications. Two dominant competitive moves are reshaping positioning: vertical integration into precision gearbox manufacturing to secure supply chains, and unbundling of after-sales service into standalone recurring revenue streams.
Among European-headquartered process engineering specialists, EKATO Holding and NETZSCH occupy positions exemplifying reactor-mixer integration heritage. Charles Ross & Son represents the specialized mechanical equipment archetype with planetary mixer focus. These three companies illustrate how geographic origin and corporate structure signal distinct strategic postures—German GmbH/AG entities emphasize process engineering integration, while the US-based Inc. structure enables specialized equipment focus.
| Leading Market Players |
|---|
| Charles Ross & Son |
| IKA |
| NETZSCH |
| FlackTek |
| Silverson Machines |
| EKATO Holding |
| SPX FLOW |
| GEA Group |
| Bühler Group |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal mandates on bio-based raw materials gate qualified supply access for coatings-grade sigma blade systems, with compliant surface engineering certifications commanding 15-20% price premiums over standard equipment tiers. REACH authorization requirements for chromium trioxide in vessel treatments restrict premium-tier pricing power to German and Swiss fabricators with validated laser-clad coating capabilities.
Pricing Analysis
Cost-down pressure on pharmaceutical-grade planetary mixers accelerates because stainless steel price volatility for 316L and 304-grade alloys compresses margins for custom-fabricated vessels. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated equipment with IQ/OQ protocols from commodity mechanical agitation systems. Price differentiation traces to ATEX certification grade and clean-in-place validation depth. Contract manufacturers serving multiple beauty brands exhibit highest price sensitivity; biologics CDMOs prioritize traceability over unit cost.
Supply Chain Analysis
Freight cost escalation for precision planetary drive systems from Germany and Japan extends lead time vulnerabilities during automotive sector demand spikes. Supply concentrates in German precision gear manufacturers, Japanese motor specialists, and Chinese standard fabrication hubs. Raw material dependencies center on 316L stainless steel alloys, specialized gearbox castings, and explosion-proof motor windings. Single-source vulnerability for precision planetary drives creates procurement risk. Distribution runs through OEM direct sales for pharmaceutical validation protocols and regional distributor networks for commodity chemical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA process validation guidelines function as a cost-of-compliance moat, consolidating procurement authority around equipment vendors with proven IQ/OQ protocol execution capabilities and validated cleaning documentation.
For Market Incumbents: Deepen backward integration into precision gearbox manufacturing to secure supply chains against automotive sector demand spikes. Anchor service revenue through remote diagnostics subscriptions as contract manufacturers unbundle after-sales support to third-party validation specialists. Prioritize captive supply of planetary drive systems to defend margin position against lead time volatility. For New Entrants and Emerging Players: Regional cosmetics contract manufacturers in the US Northeast represent the most penetrable buyer archetype, with multi-vendor maintenance capabilities replacing traditional captive service models. Target explosion-proof planetary mixer demand from CDSCO-accelerated biosimilar facilities in Hyderabad and Ahmedabad. Lead with third-party IQ/OQ protocol execution as the go-to-market wedge against established OEM service bundling. For Investors and Strategic Acquirers: Extended ATEX certification timelines from notified body backlogs is the leading indicator that compliance infrastructure scarcity will concentrate margin capture among pre-certified equipment portfolios. Frame long-term viability around 5-10 year replacement cycle compression in pharmaceutical applications. Target precision surface engineering specialists with validated laser-clad coating capabilities. Monitor REACH authorization expansion for additional restricted substances as the inflection signal for coating technology obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Gear Manufacturing | Secures planetary drive supply against German and Japanese automotive demand spikes. |
| Remote Diagnostics Subscription Launch | Retains customer touchpoints as CDMOs unbundle service to third-party validation specialists. |
| Laser-Clad Coating Validation Investment | Captures REACH-compliant pharmaceutical equipment premiums as chromium trioxide authorization tightens. |
| Explosion-Proof Planetary Mixer Capacity Addition | Positions for CDSCO-accelerated biosimilar facility investments in Hyderabad and Ahmedabad. |
| Third-Party IQ/OQ Protocol Service Expansion | Exploits procurement pattern shift among US Northeast contract manufacturers toward multi-vendor maintenance. |
Research Methodology
Multi-period observation of equipment replacement intervals, regulatory certification timelines, and raw material input costs anchored the trend analysis, supplemented by interviews with plant engineers at specialty chemical manufacturers, procurement leads at pharmaceutical CDMOs, aftermarket service heads, and technical R&D directors at precision gear suppliers. Secondary validation drew from ECHA REACH authorization databases, FDA 510(k) equipment filings, SEC 10-K disclosures from process engineering conglomerates, and customs trade data for stainless steel alloy imports. Bottom-up triangulation across installation databases and top-down reconciliation against chemical industry capital expenditure surveys ensured cross-verification.
The input-output matrix framed volume and value projections across the analysis window, modeling segmentation dimensions including mixer architecture type, drive technology tier, end-use application, and regional regulatory cluster. CAGRs were derived from replacement cycle compression patterns and biologics pipeline expansion trajectories. Forecast inputs incorporated stainless steel price volatility indices and ATEX certification backlog durations from notified body reporting.
Revisions become necessary when REACH authorization lists expand to additional surface treatment substances, FDA process validation guidelines tighten residual API limits, or precision gear supply concentration shifts through automotive sector demand displacement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Specialty Oils Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Propylene Oxide Market
Industrial Chemicals
Swimming Pool Salt Chlorinator Market
Industrial Chemicals
India Precipitated Silica Market
Industrial Chemicals
Hydrogenated Bisphenol a Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Fischer-Tropsch (FT) Wax Market
Industrial Chemicals
Anhydrous Ammonia Storage Tank Market
Industrial Chemicals
VOC Concentrator Market
Industrial Chemicals
North America Biocides Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Metalworking Treating Fluid Market
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
Global Refrigerants Market
Industrial Chemicals
1,4-Dioxane Market