
 Middle East Engineering Plastics Market | 2026-2036
Middle East Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Engineering Plastics Market Insights
Saudi Arabia's petrochemical complex expansion is rebalancing regional supply availability for engineering-grade polymers. SABIC leverages its integrated cracker-to-compound operations across Jubail and Yanbu to dominate domestic polycarbonate output. Petro Rabigh anchors Red Sea distribution networks with specialized acrylonitrile butadiene styrene grades for automotive Tier-1 suppliers. Borouge differentiates through bimodal polyethylene technologies that extend into modified polyamide formulations for electrical insulation applications.
Engineering plastics in the Middle East comprise thermoplastic polymers with mechanical strength exceeding 40 MPa tensile modulus, thermal stability above 120°C continuous service temperature, and dimensional precision suitable for metal replacement in structural components. These materials serve primarily as lightweight substitutes for aluminum and zinc die castings in powertrain housings, connector bodies, and industrial gear systems. Polycarbonate and nylon currently occupy the largest volume positions, with polycarbonate leading optical-grade and glazing applications while nylon captures the majority of under-the-hood automotive load-bearing parts. Polyethylene terephthalate injection molding grades represent the fastest-expanding structural segment, driven by electrical insulation demand from Saudi and UAE electronics manufacturers seeking halogen-free flame-retardant certifications.
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations and UAE's Emirates Authority for Standardization and Metrology (ESMA) product conformity schemes govern engineering plastics certification for construction and electrical applications across Gulf Cooperation Council markets. The EU REACH regulation exerts extraterritorial pull on export-oriented compounders, particularly for phthalate-free plasticizer formulations and restricted substance declarations in automotive supply chains. Stakeholders must monitor evolving Gulf harmonized standards for recycled content mandates, as Saudi Arabia and the UAE advance circular economy frameworks that will reshape feedstock qualification criteria for virgin and reprocessed engineering resins.
Market Dynamics
Saudi Arabia's integrated petrochemical corridor is concentrating engineering plastics supply within a 200-kilometer radius of Jubail, compressing feedstock logistics and reshaping competitive access for compounders serving automotive and electrical export markets.
Growth Catalysts
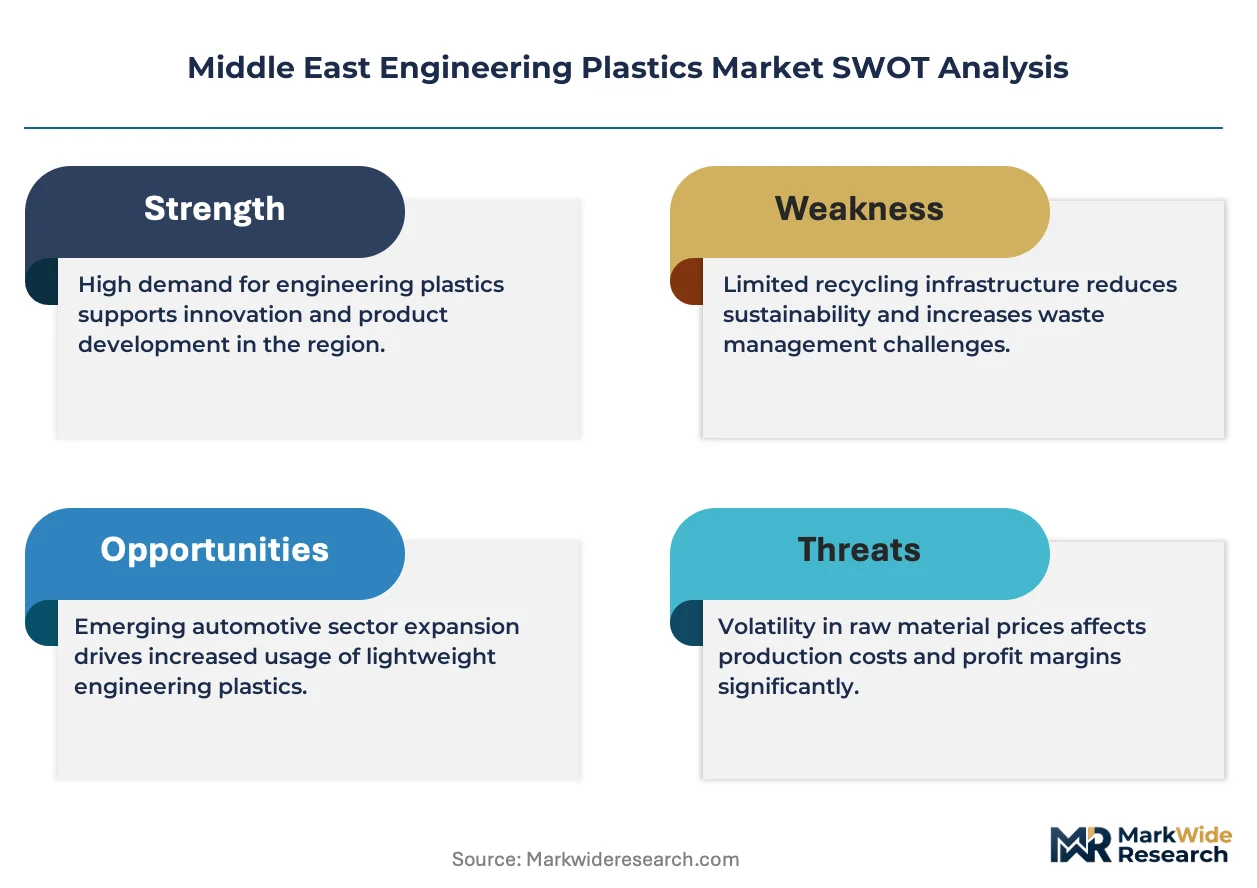
- Automotive lightweighting mandates:Saudi Arabia and the UAE are enforcing stricter fuel efficiency standards that accelerate metal-to-plastic substitution in powertrain housings and structural brackets.
- REACH-aligned export certification:Gulf-based compounders are upgrading phthalate-free formulation capabilities to maintain European automotive supply chain access under ECHA substance restrictions.
- Electrical insulation demand:Electronics manufacturers in Dubai and Riyadh are specifying halogen-free flame-retardant polyamide grades for transformer and connector applications.
Market Restraints
- Crude-linked feedstock volatility:Benzene and caprolactam input costs fluctuate with oil price swings, compressing margin predictability for polycarbonate and nylon producers.
- Supply concentration risk:Over 70 percent of regional compounding capacity sits within Saudi Arabia's Eastern Province, creating single-geography exposure for buyers.
- Technical substitution ceiling:Engineering plastics face persistent performance gaps against aluminum die castings in continuous-service temperatures above 150°C for turbocharger housings.
Strategic Opportunities
- UAE circular economy frameworks:Dubai's advancing recycled content mandates for construction-grade polymers will reshape qualification criteria for reprocessed engineering resins.
- Red Sea logistics corridor:Yanbu and Jeddah port expansions enable direct containerized export to East African electrical equipment markets with shorter lead times than Asian suppliers.
- 5G infrastructure deployment:Low-dielectric polypropylene and PBT compounds are penetrating base station antenna housings as Gulf telecom operators accelerate network rollout.
Industry Challenges
- Compounding technician scarcity:Gulf labor markets lack sufficient polymer rheology specialists to operate twin-screw extrusion lines at specification tolerances required for automotive Tier-1 contracts.
- SASO certification timelines:Saudi Standards, Metrology and Quality Organization electrical safety approvals for new flame-retardant grades extend 14-18 months, delaying product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Engineering Plastics Market |
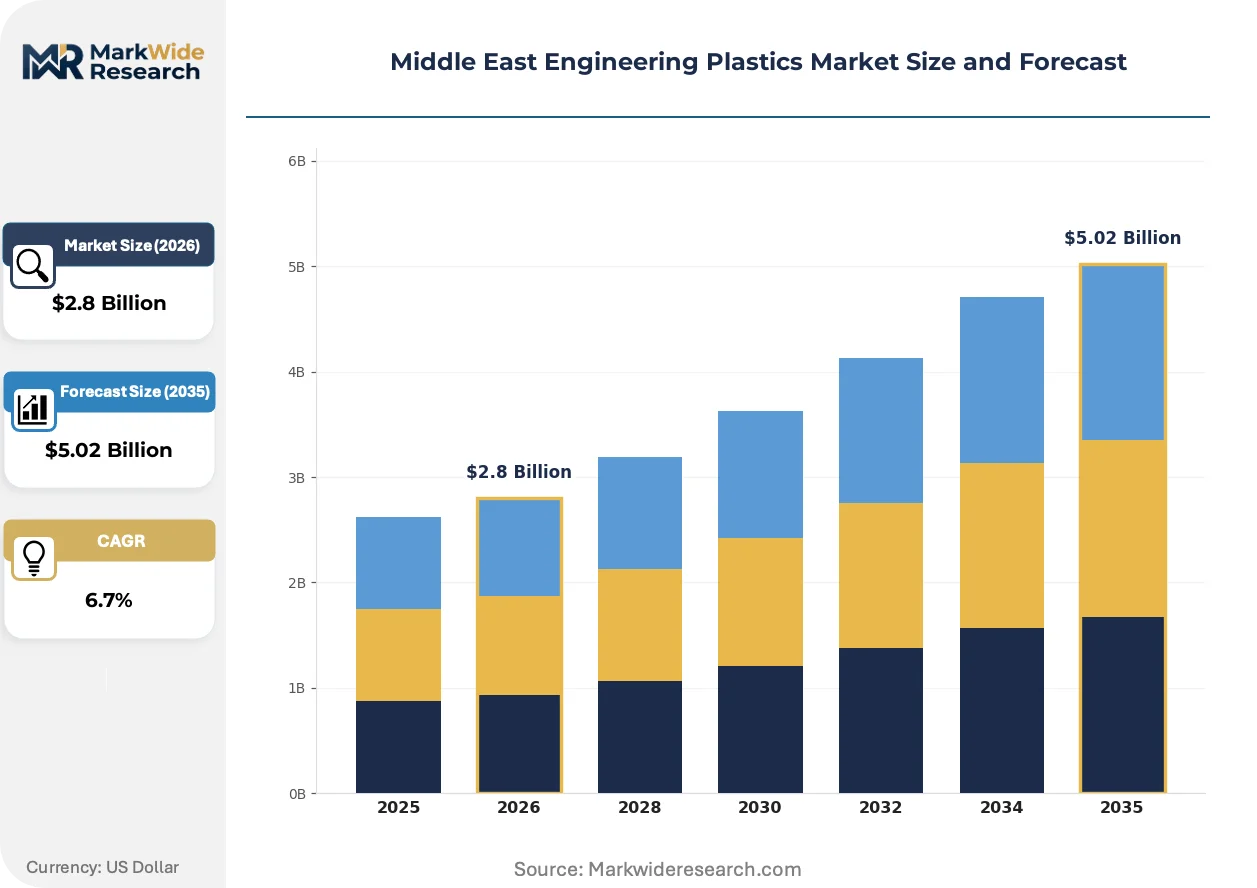
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Acrylonitrile Butadiene Styrene, Nylon, Polyethylene Terephthalate Application: Automotive Components, Electrical Insulation, Consumer Goods, Industrial Equipment End User: OEMs, Tier-1 Suppliers, Electronics Manufacturers, Construction Firms Processing Method: Injection Molding, Extrusion, Blow Molding, Thermoforming |
| Companies Covered | SABIC, Petro Rabigh, Sipchem Company, Celanese Corporation, BASF, Borouge, IVL Dhunseri Petrochem Industries Private Limited, Alfa S.A.B. de C.V., Shahid Tondgooyan Petrochemical Company, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Engineering Plastics Market Trends and Innovations
Material science convergence with digital manufacturing is redefining how engineering plastics are specified, processed, and qualified across Middle Eastern industrial supply chains.
Long-fiber thermoplastic injection molding is expanding into structural automotive components previously reserved for short-fiber or metal solutions. Tier-1 suppliers in Sharjah and Jeddah are adopting 40-50 percent glass-filled polypropylene for front-end modules and bumper beams. This technology is compressing part consolidation timelines and reducing assembly step counts for OEMs targeting 2027 model-year platforms.
SASO and ESMA are harmonizing construction-product certification schemes with EU REACH substance disclosure requirements. Compounders must now submit full material composition datasets for electrical conduit and cable management systems. Saudi exporters to European automotive markets face the steepest compliance burden, with some reformulating entire product lines to eliminate restricted brominated flame retardants.
Buyers are consolidating supplier relationships around compounders offering integrated material testing and part-design support. Tier-2 electrical manufacturers in the UAE are shifting from spot purchasing to multi-year framework agreements with technical service commitments. This pattern is most visible in Dubai's free zone industrial clusters, where procurement teams prioritize suppliers with in-house CAE simulation capabilities for mold-flow analysis.
Middle East Engineering Plastics Market Segmentation
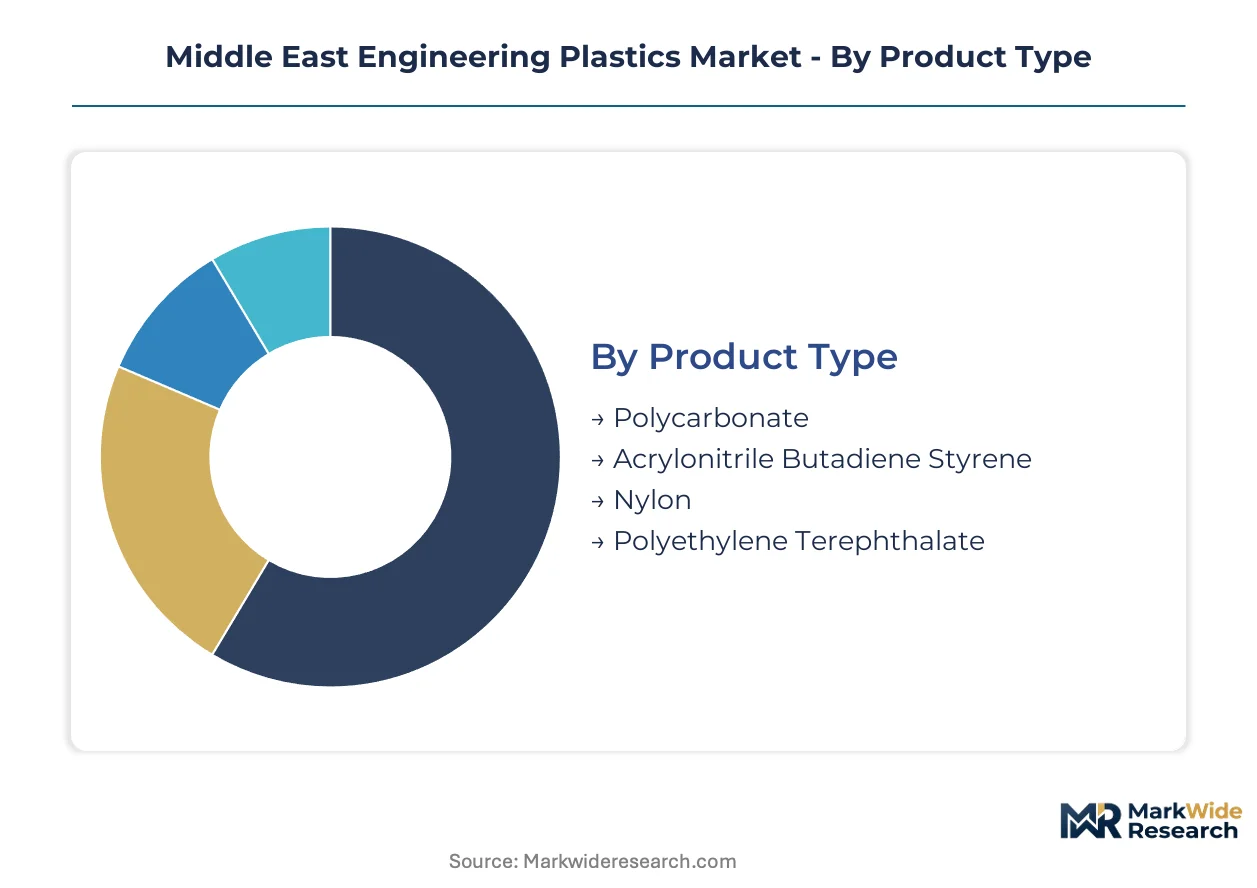
Engineering plastics specification varies sharply across end-use thermal and mechanical requirements. Material selection cascades through processing constraints, cost thresholds, and regulatory compliance layers that differ by application.
Product Type:
Thermal performance boundaries and optical clarity specifications define material selection hierarchies.
- Polycarbonate:Amorphous thermoplastic delivering 145°C heat deflection temperature and 90% light transmission. Saudi automotive glazing and LED housing manufacturers in Jubail Industrial City specify optical grades for headlamp lenses and instrument cluster covers.
- Nylon:Semicrystalline polyamide family spanning PA6 and PA66 variants with 40-50% glass reinforcement options. Under-the-hood applications across Eastern Province assembly plants dominate consumption, driven by metal replacement in engine covers and intake manifolds.
- Acrylonitrile Butadiene Styrene:Terpolymer balancing impact resistance with processability for interior automotive trim and appliance housings.
- Polyethylene Terephthalate:Injection-molding grades with halogen-free flame-retardant formulations for electrical connector bodies.
Polycarbonate leads on scale; Polyethylene Terephthalate leads on momentum.
Application:
End-use performance thresholds segment material qualification pathways and supplier certification requirements.
- Automotive Components:Structural and cosmetic parts subject to OEM material approvals and long-term thermal aging protocols. Saudi fuel efficiency mandates accelerate metal-to-plastic substitution in powertrain housings.
- Electrical Insulation:Transformer housings, connector bodies, and cable management systems requiring SASO electrical safety certification and halogen-free flame-retardant compliance.
- Consumer Goods:Appliance housings and personal electronics chassis prioritizing surface aesthetics and cost-efficient cycle times.
- Industrial Equipment:Gear systems, pump housings, and conveyor components demanding abrasion resistance and dimensional stability under mechanical load.
Automotive Components commands the largest volume position; Electrical Insulation posts the steepest expansion trajectory.
End User:
Procurement sophistication and technical service requirements stratify the customer base.
- OEMs:Vehicle assemblers and white-goods manufacturers with direct material specifications, long-term framework agreements, and in-house polymer laboratories for incoming quality verification.
- Tier-1 Suppliers:Component integrators serving automotive and electrical OEMs with compounder-managed inventory programs and collaborative part-design support.
- Electronics Manufacturers:Dubai and Riyadh-based producers of transformers, switchgear, and consumer devices specifying halogen-free grades for export market access.
- Construction Firms:Infrastructure contractors procuring conduit and cable management systems under ESMA and SASO construction-product certification schemes.
OEMs anchor procurement volumes; Tier-1 Suppliers drive formulation co-development activity.
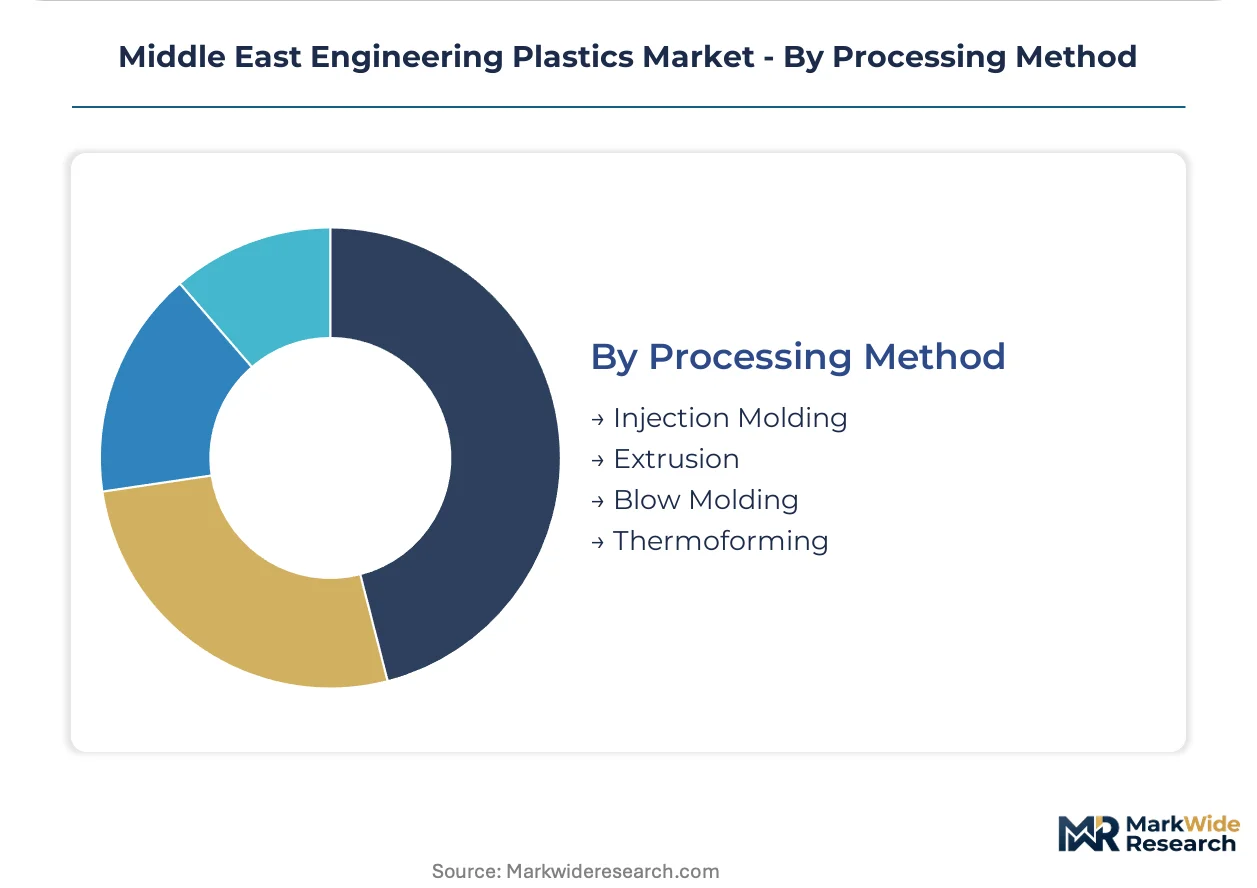
Processing Method:
Equipment capital intensity and cycle economics shape regional processing capacity distribution.
- Injection Molding:Dominant method for complex geometries requiring tight dimensional tolerances, with twin-screw compounding feeding high-cavitation tools for automotive and electrical serial production.
- Extrusion:Continuous profile production for electrical conduit, rod, and sheet applications across Jubail and Yanbu compounding corridors.
- Blow Molding:Hollow part formation for fluid reservoirs and ducting components with limited regional installed capacity.
- Thermoforming:Sheet conversion for packaging and equipment housings with lower capital barriers but narrower engineering-grade adoption.
Injection Molding concentrates equipment investment; Extrusion maintains steady feedstock throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with streamlined chemical safety approvals and lower compliance overhead, concentrating engineering plastics compounding in Gulf petrochemical corridors where integrated feedstock access offsets regulatory arbitrage costs.
Saudi Arabia
Automotive lightweighting mandates and electrical infrastructure expansion drive resin consumption across Eastern Province industrial cities. SASO technical regulations govern flame-retardant certification timelines for construction and electrical applications. Jubail Industrial City hosts integrated cracker-to-compound operations where SABIC and Petro Rabigh anchor polycarbonate and ABS output for export markets.
United Arab Emirates
Dubai-based electronics manufacturers specify halogen-free polyamide grades for transformer housings and connector bodies serving regional power grid modernization. ESMA product conformity schemes align with EU REACH substance disclosure requirements for export-oriented compounders. Jebel Ali free zone clusters concentrate procurement teams demanding suppliers with in-house CAE simulation and mold-flow analysis capabilities.
Qatar
Industrial diversification programs accelerate demand for high-performance polymers in oilfield equipment and petrochemical processing infrastructure. The country's national standards body enforces construction-product certification harmonized with Gulf technical regulations. Ras Laffan Industrial City supports specialized compounding operations feeding downstream manufacturing in electrical insulation and industrial gear applications.
Kuwait
Power generation and water desalination infrastructure renewal creates demand for heat-resistant thermoplastics in pump housings and valve components. National quality and metrology regulations govern material imports for critical infrastructure applications. Shuaiba Industrial Area maintains limited but strategic compounding capacity focused on polyamide formulations for regional electrical equipment suppliers.
Oman
Port and logistics infrastructure investments position Sohar and Salalah as alternative distribution nodes for East African electrical equipment markets. The country's standards and metrology organization implements Gulf harmonized technical regulations for imported engineering plastics. Duqm Special Economic Zone attracts compounders seeking Red Sea logistics access with shorter lead times than Asian supplier alternatives.
Middle East Engineering Plastics Market Competitive Landscape
Saudi producers anchor the integrated feedstock tier; European and Asian specialists hold formulation technology positions. Market structure concentrates around three to five vertically integrated petrochemical operators controlling upstream monomer supply, while mid-scale compounders compete on technical service and certification speed. Strategic archetypes include cracker-integrated resin producers, automotive-focused formulation specialists, and electrical-grade certification experts. Capacity expansion and backward integration into specialized additive masterbatches constitute the dominant competitive moves.
Within the integrated petrochemical tier, SABIC exemplifies the cracker-to-compound archetype through its Jubail and Yanbu manufacturing positions. Petro Rabigh occupies a specialist role in Red Sea distribution networks. Borouge represents the bimodal technology extension strategy into modified polyamide formulations. These three anchors illustrate how feedstock proximity and logistics corridor access determine competitive positioning in Gulf engineering plastics supply.
| Leading Market Players |
|---|
| SABIC |
| Petro Rabigh |
| Sipchem Company |
| Celanese Corporation |
| BASF |
| Borouge |
| IVL Dhunseri Petrochem Industries Private Limited |
| Alfa S.A.B. de C.V. |
| Shahid Tondgooyan Petrochemical Company |
| Others |
Pricing and Supply Chain Analysis
Long-fiber thermoplastic injection molding adoption across Sharjah and Jeddah Tier-1 suppliers simultaneously compresses per-part processing economics and concentrates compounding capacity around integrated petrochemical corridors with captive glass fiber supply.
Pricing Analysis
Distributor margins on engineering-grade polycarbonate and polyamide compounds typically run 8-12 percent above direct OEM contract pricing. Three-tier pricing structure across premium optical grades, standard automotive formulations, and economy electrical conduit materials reflects certification burden and volume scale. Price differentiation hinges on SASO flame-retardant certification status and halogen-free formulation complexity. Cost compression in standard-grade polyamide is intensifying because benzene and caprolactam feedstock volatility transmits directly to compounder margins. Electronics manufacturers in Dubai's free zones exhibit highest price sensitivity due to thin assembly margins, while automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from European automotive OEMs mandate Gulf compounders qualify secondary feedstock channels for critical polyamide and polycarbonate grades. Geographic supply concentration centers on Saudi Arabia's Eastern Province, the UAE's Jebel Ali corridor, and Qatar's Ras Laffan Industrial City. Raw material dependencies draw from benzene derivatives, caprolactam monomer, and specialized flame-retardant additive packages. Single-source vulnerability persists where over 70 percent of regional compounding capacity sits within Jubail's 200-kilometer radius. Distribution runs through integrated petrochemical operators with captive logistics networks serving Red Sea and East African electrical equipment markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where SASO and ESMA certification harmonization with EU REACH substance disclosure requirements creates structural demand for reformulated halogen-free grades.
For Market Incumbents: Cement feedstock security through backward integration into specialized additive masterbatches and flame-retardant packages. Expand compounding capacity in Yanbu to capture Red Sea logistics advantages for East African electrical equipment markets. Defend against Asian import substitution by accelerating SASO certification timelines through pre-submission technical consultations with Saudi Standards, Metrology and Quality Organization. For New Entrants and Emerging Players: The premium-to-economy price gap in electrical-grade polyamide compounds offers white-space entry for mid-tier compounders with technical service capabilities. Target UAE-based transformer manufacturers seeking alternatives to established Saudi suppliers. Penetrate through mold-flow analysis and CAE simulation services bundled with material supply, mirroring procurement patterns visible in Dubai's free zone industrial clusters. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale compounders lacking integrated cracker access but holding ESMA certification speed advantages and electrical-grade formulation libraries. Long-term viability hinges on circular economy positioning as recycled content mandates advance across Gulf Cooperation Council markets. Watch for inflection where Dubai's recycled polymer qualification criteria reshape feedstock sourcing economics for virgin resin compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Masterbatches | Captive supply of flame-retardant packages insulates margins from specialty chemical import volatility. |
| ESMA Pre-Certification Investment | Accelerated product launch cycles capture Dubai electronics manufacturer procurement shifts. |
| Red Sea Distribution Footprint Expansion | Yanbu and Jeddah port access shortens lead times to East African electrical equipment markets. |
| Recycled Content Qualification Capability | UAE circular economy frameworks will reshape feedstock criteria for construction-grade polymers. |
| Technical Service Co-Development Programs | CAE simulation capabilities secure multi-year framework agreements with Tier-2 electrical manufacturers. |
Research Methodology
Coverage spans Saudi Arabia, United Arab Emirates, Qatar, Kuwait, and Oman, with primary inputs from each Gulf Cooperation Council jurisdiction. Primary interviews engaged compounding plant managers, automotive Tier-1 procurement leads, electrical equipment technical directors, and petrochemical distribution channel partners. Secondary validation drew from SASO technical regulation filings, ESMA product conformity databases, customs and trade flow data, and SEC disclosures from listed petrochemical operators. Bottom-up resin consumption estimates triangulated against top-down petrochemical production capacity data.
Rate-of-change decomposition structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry, processing method, and regional production hub clustering. CAGRs derived from historical consumption pattern analysis adjusted for regulatory milestone impacts and feedstock capacity expansion timelines. Industry-specific forecast inputs incorporated automotive lightweighting mandate compliance schedules and 5G infrastructure deployment trajectories for low-dielectric compound demand.
Caveats apply where crude-linked benzene and caprolactam price volatility, SASO certification timeline extensions, or REACH substance restriction amendments could materially shift the outlook. Deviation in Gulf harmonized standards for recycled content mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle East Polymer Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Poly Alpha Olefin (PAO) Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Polycide Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
EVA Foam Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Metallocene Polyethylene Market
Polymers & Resins
Global Chromatography Resin Market
Polymers & Resins
Polymers for Electric Vehicle (EV) Market
Polymers & Resins
Polyamide Precursors Market
Polymers & Resins
Plastic Calendering Resins Market
Polymers & Resins
Polylysine Market
Polymers & Resins
TPEE in Automotive Industry Market
Polymers & Resins
Scleroglucan Market