
 Polyurethane Elastomers Market | 2026-2036
Polyurethane Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane Elastomers Market Intelligence
The shift toward bio-based polyols and isocyanates is fragmenting the traditional petrochemical-based supply chain for polyurethane elastomers. This innovation creates new competitive dynamics where firms like Covestro AG invest in sustainable material science. Wanhua Chemical Group leverages its massive scale in conventional isocyanate production to maintain cost leadership. BASF SE differentiates through a broad portfolio of specialized formulations for high-performance applications.
Polyurethane elastomers are polymers resulting from the reaction of diisocyanates with polyols, forming materials with exceptional abrasion resistance, tear strength, and elasticity. Their primary function is to bridge the performance gap between flexible rubber and rigid plastics. Within end-use industries, the automotive sector remains the dominant consumer for applications like gaskets, seals, and bushings. The footwear segment, however, represents the fastest-growing opportunity, particularly for high-resilience foams in athletic shoe midsoles.
Regulatory frameworks such as the EU's REACH directive and EPA regulations in the United States govern the use of specific isocyanates and blowing agents, impacting product composition. In China, national GB standards for volatile organic compound (VOC) emissions are pushing manufacturers toward water-based or low-VOC formulations. Navigating these divergent regional environmental standards while managing raw material volatility will be the central challenge for producers.
Market Dynamics
The central dynamic in the polyurethane elastomers market is the competitive friction between incumbent, large-scale petrochemical production and the innovation-driven, fragmented supply chain for emerging bio-based materials. This creates a strategic divergence between cost leadership and sustainable differentiation.
Growth Catalysts
- Automotive Lightweighting:Demand from electric vehicle manufacturers for lightweight components to extend battery range drives adoption of PU elastomers in bushings, engine mounts, and suspension parts.
- Footwear Innovation:The athletic footwear segment's pursuit of higher energy return and durability fuels consumption of high-resilience PU foams for midsoles, particularly in manufacturing centers across Southeast Asia.
- Sustainability Mandates:Corporate ESG goals and consumer preferences for sustainable products are accelerating the development and specification of elastomers derived from bio-based polyols and isocyanates.
Market Restraints
- Raw Material Volatility:The market's performance is tied to the price fluctuations of petrochemical feedstocks like MDI and TDI, creating margin pressure and forecasting uncertainty for producers.
- Substitution from Thermoplastics:Thermoplastic elastomers (TPEs) present a persistent substitution threat in less demanding applications due to their easier processing and recyclability, limiting PU's penetration.
- Regulatory Fragmentation:Divergent chemical regulations, such as the EU's REACH framework and China's GB standards for VOCs, increase the complexity and cost of developing globally compliant formulations.
Strategic Opportunities
- Additive Manufacturing:The development of liquid PU resins for 3D printing creates an opportunity to produce customized, complex-geometry parts for prototyping, medical devices, and low-volume industrial applications.
- Medical Grade Materials:Expanding healthcare sectors in developing economies offer a growth avenue for biocompatible PU elastomers in applications like catheters, tubing, and medical device seals.
- Circular Economy Integration:Innovations in chemical recycling that can break down post-consumer PU elastomers back into polyols and isocyanates present a long-term opportunity to create closed-loop supply chains.
Industry Challenges
- Bio-Based Supply Chain Development:Establishing reliable, scalable, and cost-effective supply chains for bio-based feedstocks like vegetable oils or sugars remains a significant operational hurdle for manufacturers.
- VOC Emission Compliance:Implementing the process controls and capital equipment needed to meet increasingly strict VOC emission limits, particularly in China, poses a substantial challenge for coating and adhesive producers.
- Formulation Expertise Scarcity:A talent gap exists for chemical engineers and technicians skilled in reformulating products to meet new regulatory constraints or incorporate novel bio-materials without sacrificing performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane Elastomers Market |
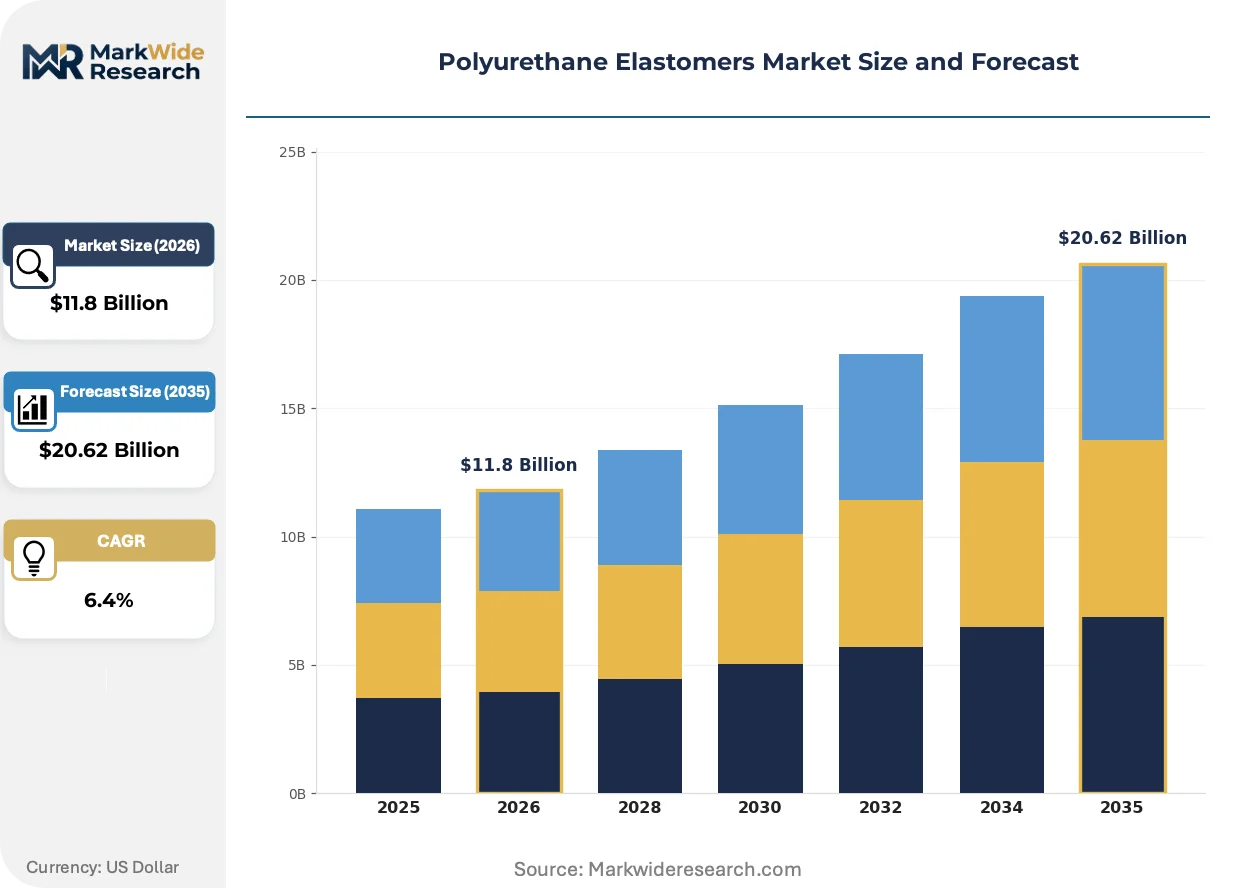
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
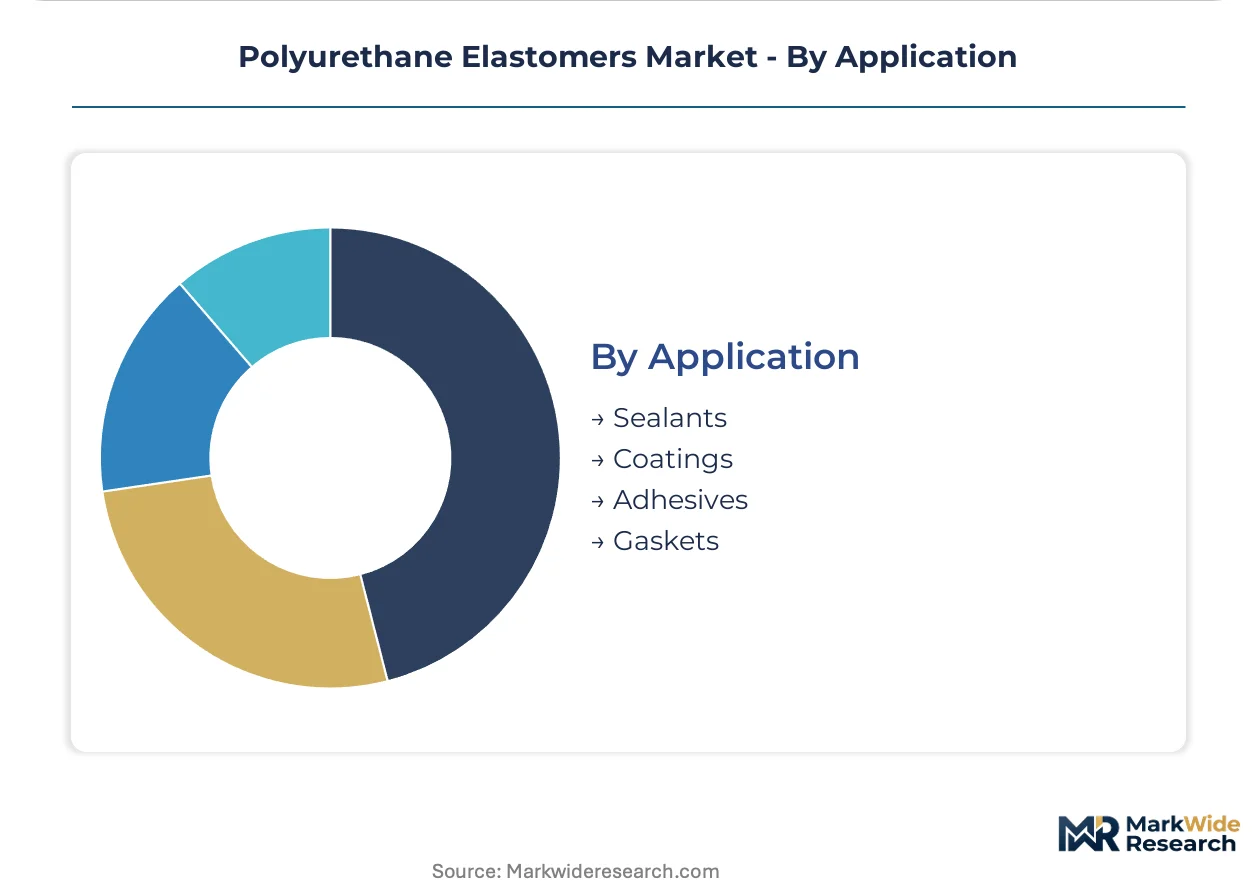
| Segmentation | Product Type: Flexible, Rigid, High Resilience, Thermoplastic End Use Industry: Automotive, Construction, Footwear, Furniture Form: Spray, Sheet, Liquid, Molded Application: Sealants, Coatings, Adhesives, Gaskets |
| Companies Covered | Huntsman International LLC, Wanhua Chemical Group, Covestro AG, Mitsui Chemicals, Inc., LANXESS, BASF SE, The Lubrizol Corporation, Tosoh Corporation, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane Elastomers Market Strategic Shifts & Innovations
The market's evolution is defined by a necessary pivot from pure performance optimization toward a balanced equation of material efficiency, sustainability, and regulatory compliance. This shift is altering product development, material sourcing, and end-user specification criteria across all major applications.
Digital material simulation software allows formulators to predict the physical properties of new elastomer formulations. R&D teams in the automotive and aerospace industries are adopting these tools to shorten development cycles for specialized components. This advanced modeling capability is virtualizing the time-intensive and resource-heavy process of physical prototyping and testing, compressing the path from concept to commercialization.
The European Union's REACH directive imposes stringent controls on the use of certain diisocyanates, citing occupational health risks. This regulation compels manufacturers serving the European market to invest in reformulation efforts. The coatings, adhesives, and sealants sectors are most directly impacted, accelerating their transition toward low-monomer or water-based polyurethane systems to ensure compliance.
A notable shift in buying behavior involves the prioritization of materials with documented sustainability credentials. This change disrupts procurement decisions based solely on technical performance and price, favoring suppliers who can provide certified low-VOC, bio-based content, or recyclable elastomers. This trend is most pronounced in consumer-facing industries like furniture and footwear within North American and European markets.
Polyurethane Elastomers Market Segmentation
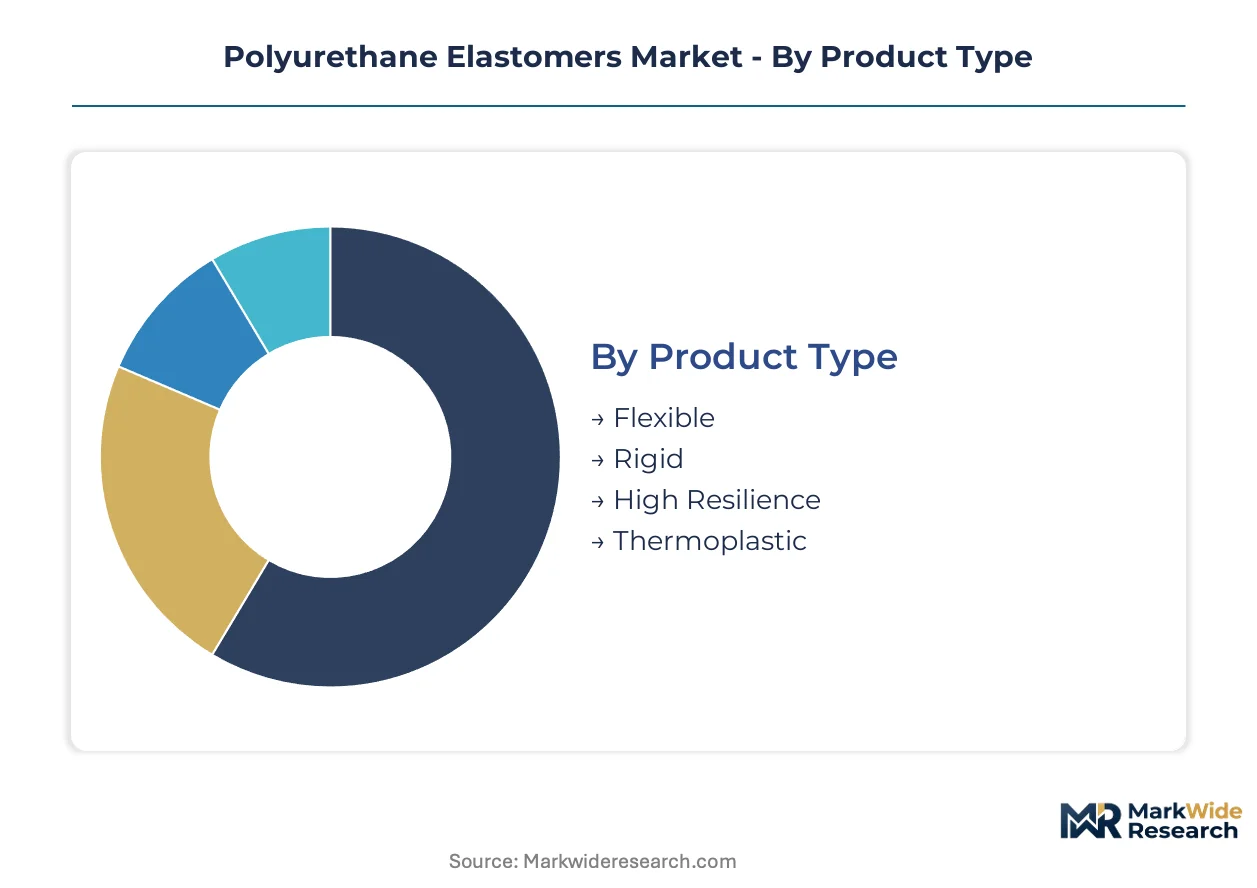
The polyurethane elastomers market is disaggregated across diverse product types, end-use applications, and material forms, each reflecting distinct performance requirements and value propositions. Understanding these segments provides clarity on demand drivers and the specific technological innovations shaping competitive dynamics. Each category reveals unique growth trajectories and regulatory influences.
Product Type:
The maturity spectrum within product types varies significantly, with established formulations coexisting alongside rapidly evolving advanced materials. This divergence influences investment in R&D and manufacturing capabilities across the industry.
- High Resilience:These elastomers exhibit superior elastic recovery and energy absorption, making them ideal for demanding applications requiring shock absorption and comfort. Demand for high-resilience foams is accelerating within the athletic footwear segment, particularly for advanced midsole designs in Vietnam and China.
- Thermoplastic:Thermoplastic polyurethanes (TPUs) offer melt-processability and recyclability, combining rubber-like elasticity with plastic's manufacturing ease. Their adoption is expanding in consumer electronics and medical devices, driven by increasing focus on circular economy principles and efficient production cycles.
- Flexible:Characterized by high elongation and softness, flexible polyurethane elastomers find extensive use in furniture cushioning and automotive interior components. They offer comfort and vibration dampening for consumer and industrial goods.
- Rigid:Rigid polyurethane elastomers provide high compressive strength and dimensional stability, commonly specified for structural components and insulation panels. They find application in construction and refrigeration, valued for durability and thermal efficiency.
Flexible polyurethane elastomers handle the majority of throughput; High Resilience is the fastest mover on share.
End Use Industry:
Application demands from distinct end-use industries dictate the specific performance characteristics required from polyurethane elastomers. Each sector exhibits unique consumption patterns and material specification criteria.
- Automotive:The automotive sector utilizes polyurethane elastomers for lightweighting components, vibration damping, and interior aesthetics, including seals, gaskets, and seating foams. Demand is concentrated in Germany and China, driven by electric vehicle production and stringent comfort requirements.
- Footwear:Polyurethane elastomers are critical for midsoles, outsoles, and insoles in footwear, providing cushioning, energy return, and durability. The athletic footwear segment in Southeast Asia, particularly Vietnam and Indonesia, is a primary growth engine due to ongoing innovation in shoe performance.
- Construction:Polyurethane elastomers are applied in construction for insulation, sealants, and coatings, offering thermal efficiency and weather resistance. They contribute to energy-efficient building envelopes and durable infrastructure.
- Furniture:In the furniture industry, polyurethane elastomers form the core of cushioning, upholstery, and structural components due to their comfort and resilience. They are integral to both residential and commercial seating.
The automotive industry remains the largest consumer of polyurethane elastomers; Footwear is expanding most quickly due to innovation in athletic shoe designs.
Form:
The form in which polyurethane elastomers are supplied influences processing methods and application versatility. Supply concentration varies, with some forms requiring specialized equipment for application.
- Liquid:Liquid polyurethane resins are precursors for molded parts, coatings, and adhesives, offering high versatility in processing and final product properties. Their use is expanding in 3D printing for rapid prototyping and custom medical devices in the United States and Japan.
- Molded:Molded polyurethane elastomers are produced through casting or injection molding, creating finished components like gaskets, wheels, and rollers. This form dominates industrial applications requiring precise shapes and high mechanical performance in manufacturing hubs like China and South Korea.
- Spray:Spray polyurethane elastomers are applied as coatings or insulation, forming seamless, protective layers with excellent adhesion. They are commonly used in roofing, flooring, and protective linings.
- Sheet:Polyurethane elastomers in sheet form are utilized for membranes, seals, and diaphragms, offering consistent thickness and uniform properties. These sheets are often fabricated into components through cutting or thermoforming.
Molded forms represent a substantial volume of consumption; Liquid forms are gaining significant traction, driven by advancements in additive manufacturing.
Application:
The application of polyurethane elastomers often aligns with specific cost tiers, reflecting performance requirements and regulatory compliance. Each application addresses distinct functional needs across various industries.
- Gaskets:Polyurethane gaskets provide sealing solutions with excellent compression set resistance, abrasion resistance, and chemical compatibility in demanding environments. They are widely used in automotive engines and industrial machinery to prevent leaks and ensure operational integrity.
- Coatings:Polyurethane coatings offer superior abrasion resistance, chemical protection, and aesthetic appeal, extending the lifespan of substrates. Their demand is rising in construction and automotive refinishing, driven by stringent VOC regulations in Europe and China pushing for water-based systems.
- Sealants:Polyurethane sealants offer strong adhesion, flexibility, and weather resistance, crucial for bonding and sealing joints in buildings and vehicles. They prevent moisture ingress and provide structural integrity in construction and automotive assemblies.
- Adhesives:Polyurethane adhesives provide robust bonding strength and flexibility, used in assembly processes across automotive, construction, and electronics sectors. They enable lightweight designs and offer superior performance.
Gaskets remain a foundational application for polyurethane elastomers; Coatings and adhesives are experiencing strong growth due to regulatory shifts and product innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyurethane elastomers demand concentrates where major end-use industries like automotive and footwear manufacturing are robust. These regional clusters drive material innovation and consumption patterns. Regulatory environments also significantly shape product development and material sourcing within these key geographies.
China
China's automotive sector, particularly electric vehicle production, creates substantial demand for lightweight PU components. The country's GB standards for VOC emissions push manufacturers toward low-VOC and water-based formulations. Manufacturing hubs in the Yangtze River Delta and Pearl River Delta lead in both production and consumption of these advanced materials.
Germany
Germany's sophisticated automotive industry requires high-performance polyurethane elastomers for seals, gaskets, and vibration dampening. The EU's REACH framework dictates material selection, driving innovation in sustainable and safer chemistries. Chemical companies in the Rhine-Ruhr region actively develop specialized formulations for global markets.
United States
The United States' expanding healthcare sector and additive manufacturing capabilities drive demand for medical-grade and specialized liquid PU resins. EPA regulations influence material composition, particularly for blowing agents and VOCs. Silicon Valley and Boston-area innovation clusters are exploring new applications for 3D-printed elastomers.
Vietnam
Vietnam's footwear industry, a major global manufacturing hub, requires high-resilience PU foams for athletic shoe midsoles. This segment benefits from ongoing design innovation focused on energy return and durability. Production facilities in Ho Chi Minh City and Hanoi are key centers for this specialized PU consumption.
Japan
Japanese consumer electronics and automotive industries require advanced polyurethane elastomers for durable, flexible components. METI initiatives support R&D into novel materials and processing techniques. Industrial zones around Tokyo and Nagoya are centers for precision manufacturing and material science development.
Polyurethane Elastomers Market Key Industry Players
Channel-controlling players compete with product-specialist players across the polyurethane elastomers market. The industry structure shows a tiered consolidation, with large chemical conglomerates offering broad portfolios alongside niche players specializing in specific formulations. Key strategic archetypes include cost leaders, sustainable innovators, and high-performance specialists. Dominant competitive moves involve portfolio diversification into bio-based materials and strategic partnerships for supply chain resilience.
At the scale-driven end, Wanhua Chemical Group leverages its massive production capacity for conventional isocyanates to maintain cost leadership. Covestro AG exemplifies sustainable innovation, investing significantly in bio-based polyols and isocyanates to meet evolving environmental mandates. BASF SE occupies a position as a high-performance specialist, differentiating through a broad portfolio of specialized formulations for demanding applications across various end-use industries.
| Leading Market Players |
|---|
| Huntsman International LLC |
| Wanhua Chemical Group |
| Covestro AG |
| Mitsui Chemicals, Inc. |
| LANXESS |
| BASF SE |
| The Lubrizol Corporation |
| Tosoh Corporation |
| Dow |
| Others |
Cost & Logistics Intelligence
Underutilized production capacity in conventional isocyanate manufacturing in China drives down spot market prices for base polyurethane elastomer feedstocks, influencing global contract negotiations. This oversupply encourages suppliers to offer more flexible terms to maintain volume, impacting overall market margins.
Pricing Analysis
Cost-plus contracts, often indexed to MDI and TDI prices, dominate long-term supply agreements for polyurethane elastomers. Price differentiation stems from specialized formulation complexity, such as high-resilience grades, and the level of regulatory compliance certifications like REACH. Pricing pressure stems from intense competition among large-scale producers and the availability of lower-cost alternatives from Asian manufacturers. Automotive OEMs, purchasing in high volumes, exhibit the highest price sensitivity, while medical device manufacturers prioritize performance and certification over cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities help manage working capital for both upstream chemical producers and downstream formulators. Geographic supply concentration for key raw materials like isocyanates and polyols centers on China and Germany, with significant production also in the United States and Japan. The supply chain relies heavily on petrochemical feedstocks, making it susceptible to commodity price volatility. Distribution runs through a mix of direct sales to large industrial customers and a network of specialized distributors serving smaller formulators and regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyurethane elastomers market is experiencing a shift in buyer power, driven by the increasing consolidation of large automotive and footwear manufacturers globally. These consolidated buyers leverage their scale to demand more competitive pricing and stringent sustainability credentials.
For Market Incumbents:Pre-empt competitive threats from bio-based material innovators by accelerating investments in sustainable R&D. Develop comprehensive portfolios of low-VOC and bio-based polyols to meet evolving regulatory frameworks like the EU's REACH directive. Deepen vertical integration into specialized polyol production to secure critical inputs and differentiate offerings. Focus on high-performance applications where established expertise and brand reputation command a premium, mitigating margin pressure from commodity grades.
For New Entrants and Emerging Players:Establish a beachhead in niche applications requiring advanced material properties or specific sustainability profiles. Target the additive manufacturing segment with specialized liquid PU resins for 3D printing, leveraging customization and rapid prototyping needs. The medical grade materials segment, particularly for biocompatible elastomers in emerging economies, offers a penetrable market due to its high-value, low-volume nature. A go-to-market angle focusing on certified sustainable or novel processing solutions will resonate with forward-thinking end-users.
For Investors and Strategic Acquirers:Capital is best deployed toward mid-sized companies possessing proprietary bio-based polyol technologies or advanced chemical recycling capabilities. These firms offer long-term viability by addressing both sustainability mandates and raw material volatility. Target acquisition profiles include companies with established intellectual property in water-based or low-monomer systems, or those with strong regional distribution networks in high-growth areas like Southeast Asia's footwear industry. The signal to watch is the increasing adoption rate of chemically recycled PU content by major consumer brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Bio-based Polyol Production | Reduces reliance on petrochemicals and meets growing demand for sustainable products. |
| Invest in Chemical Recycling Technologies | Enables closed-loop material flow, enhancing circular economy integration and resource efficiency. |
| Develop Low-VOC Formulations | Ensures compliance with stringent environmental regulations, particularly in China and Europe. |
| Form Strategic Partnerships for Additive Manufacturing | Accelerates market penetration into customized, high-value 3D printing applications. |
| Acquire Medical Grade Material Specialists | Captures growth opportunities in the expanding healthcare sector with specialized, biocompatible elastomers. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation from published sources. This involved conversations with plant managers, procurement leads at automotive OEMs, R&D directors in chemical companies, and footwear designers across various geographies. Secondary data sources included customs and trade statistics, company financial filings, and regulatory reports from the EPA and ECHA.
Forecast inputs being considered included material flow analysis across the modeling period, segmenting the market by product type, end-use industry, material form, and application, alongside regional production hubs. Compound annual growth rates were derived from historical data trends and projected demand from key end-use sectors. Industry-specific forecast inputs included electric vehicle production forecasts and bio-based polyol adoption rates in consumer goods.
Stress conditions across raw material volatility, regulatory shifts, and technological advancements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding economic stability and continued industrial growth across major regions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
North America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Global Elastomeric Coating Market
Elastomeric Membrane
Elastic Laminates Market
Elastomeric Membrane
Ethylene Propylene Elastomers Market
Elastomeric Membrane
Polyolefin Elastomer Market
Elastomeric Membrane
High Temperature Elastomers Market
Elastomeric Membrane
Global Acrylic Elastomers Market
Elastomeric Membrane
Polysulfide Elastomers Market
Elastomeric Membrane
Hot Cast Elastomers Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Stretchable Conductive Material Market