
 UV Stabilized Thermoplastic Elastomer for Automotive Market | 2026-2036
UV Stabilized Thermoplastic Elastomer for Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
UV Stabilized Thermoplastic Elastomer for Automotive Market Intelligence
China's expanding polymer compounding capacity is reshaping regional supply dynamics for automotive TPE grades. ExxonMobil leverages its integrated olefin feedstock position to sustain cost-competitive polyolefin elastomer output. Covestro AG differentiates through aliphatic polyurethane chemistry leadership for exterior applications requiring superior UV resistance. Arkema S.A. specializes in bio-based Pebax elastomers that target premium OEM sustainability specifications.
UV stabilized thermoplastic elastomers comprise block copolymer or polyolefin matrices blended with hindered amine light stabilizers and UV absorbers, typically processed at melt temperatures between 180°C and 220°C to preserve additive integrity while achieving Shore A hardness ranges of 60-90 for flexible automotive components. Interior trim applications dominate current volume consumption due to extensive dashboard and door panel deployments, though bumper fascia segments represent the fastest-growing application as Class A surface requirements tighten. Injection molding occupies the largest processing share for complex geometries, while extrusion commands premium positioning in continuous sealing profiles where lot-to-lot color stability is critical.
EPA fuel economy standards and NHTSA safety regulations in the United States compel lighter-weight sealing solutions, while REACH restrictions on phthalate plasticizers in Europe redirect formulation strategies toward non-migrating stabilizer packages. China's GB standards for interior air quality and MIIT new energy vehicle mandates collectively expand addressable demand for low-VOC, UV-stable TPE grades. Stakeholders must monitor evolving stabilizer chemistries and regional certification timelines to align capacity investments with shifting OEM qualification protocols.
Market Dynamics
Automotive OEMs are consolidating supplier bases for UV-stabilized TPEs around compounders capable of certifying lot-to-lot weathering performance under multiple regional protocols simultaneously, compressing qualification timelines from 18 months to under 12 months.
Growth Catalysts
- ECE R43 weathering durability mandates:European exterior sealing specifications now require 5,000-hour xenon arc exposure testing, forcing adoption of hindered amine-stabilized TPE grades.
- China MIIT new energy vehicle production quotas:Domestic OEMs in the Yangtze River Delta specify low-VOC UV-stable TPEs for interior air quality compliance under GB/T 27630.
- Polyolefin elastomer process innovation:Advances in reactive extrusion compounding allow inline UV stabilizer dispersion at 200°C melt temperatures without thermal degradation.
Market Restraints
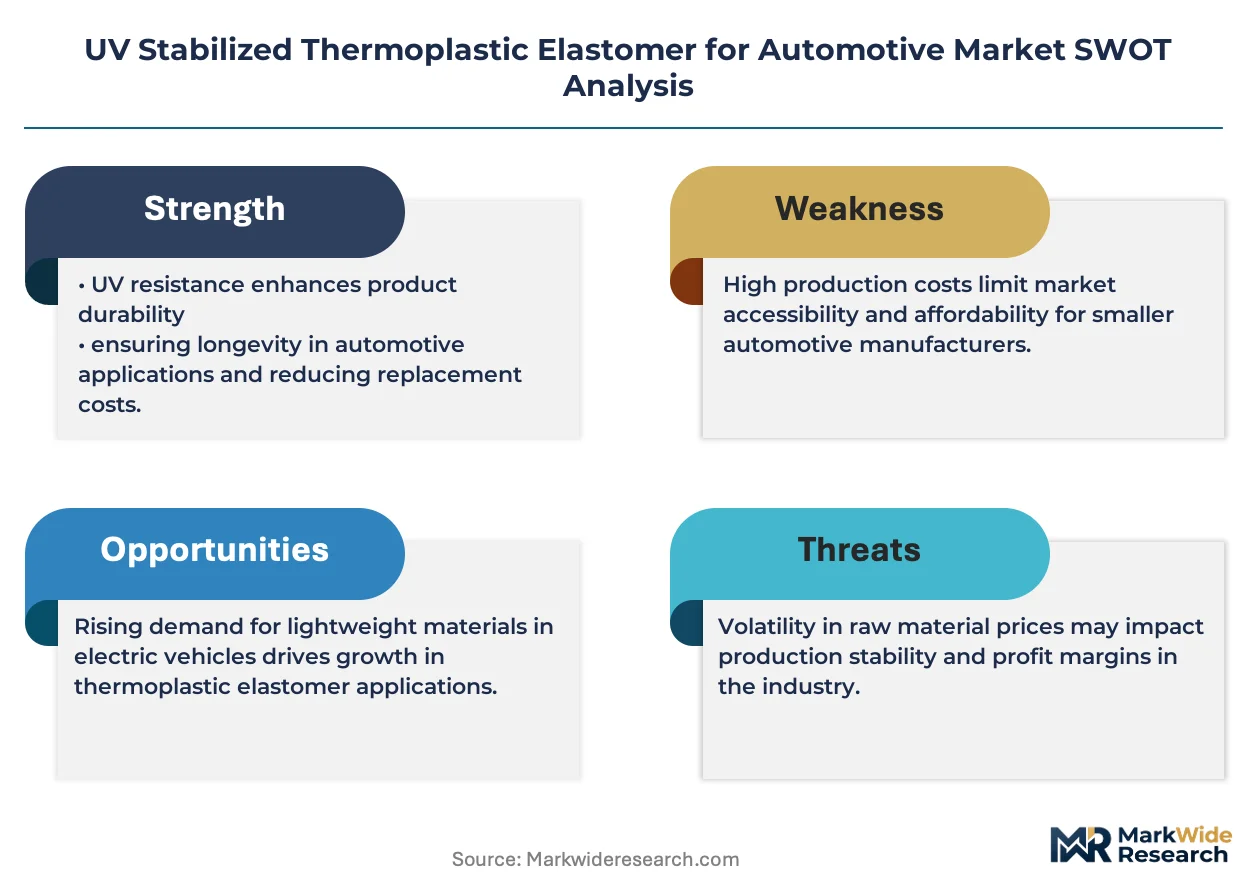
- Hindered amine light stabilizer cost volatility:Raw material dependence on petrochemical-derived piperidine intermediates creates margin pressure during crude price swings.
- Specialized compounding concentration:Automotive-grade UV-TPE production clusters heavily in Germany's Ruhr industrial region and China's Jiangsu province, creating geographic supply risk.
- Aliphatic polyurethane TPE substitution:Covestro's Desmopan grades capture premium exterior applications where color stability exceeds 10 years, limiting polyolefin elastomer pricing power.
Strategic Opportunities
- India automotive component localization:PLI scheme incentives for domestic manufacturing create first-mover advantage for compounders establishing Bengaluru or Pune technical centers.
- Overmolded sensor housing applications:ADAS camera and radar enclosures require UV-stable TPEs with electromagnetic shielding compatibility, an emerging specification gap.
- EU Green Deal circular economy requirements:Recyclable mono-material TPE systems qualify for extended producer responsibility credits, differentiating sustainable formulations.
Industry Challenges
- Accelerated weathering technician shortage:Qualified personnel capable of interpreting ASTM G154 and ISO 4892 correlation data remain scarce across third-party testing laboratories.
- Multi-protocol certification complexity:Simultaneous SAE J1885, JIS D 0205, and PV 3929 qualification creates 14-16 month approval cycles that strain R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Stabilized Thermoplastic Elastomer for Automotive Market |
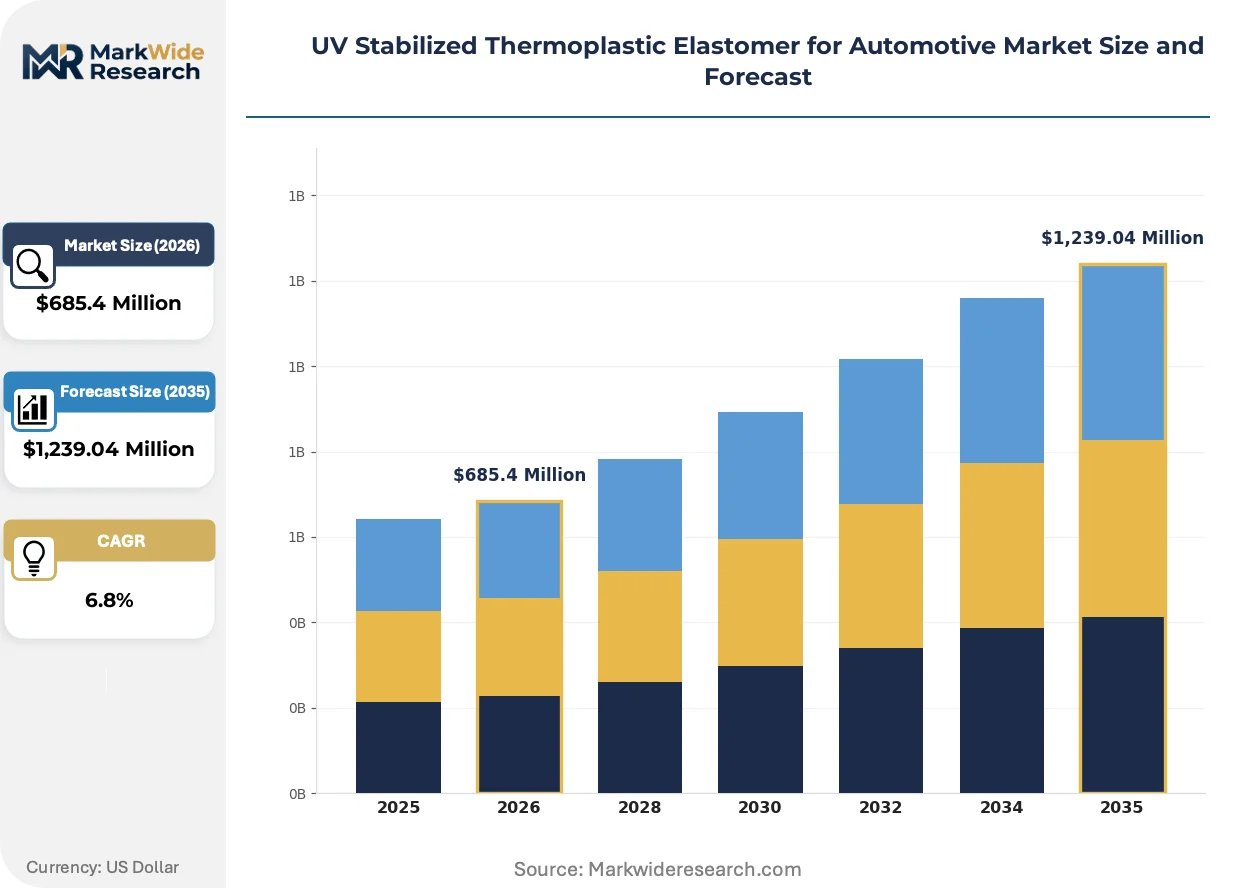
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Interior Trim, Bumpers, Seals, Gaskets End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Material Type: Polyurethane, Styrenic Block Copolymer, Polyolefin, Thermoplastic Polyurethane Processing Method: Injection Molding, Extrusion, Blow Molding, Thermoforming |
| Companies Covered | DuPont de Nemours, Inc., ExxonMobil, SABIC, Covestro AG, Arkema S.A., BASF SE, Kraton Corporation, LG Chem, Kraiburg TPE GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Stabilized Thermoplastic Elastomer for Automotive Market Strategic Shifts & Innovations
Formulation science is converging with digital color matching and predictive weathering analytics to compress development cycles. Three developments are restructuring how UV-stabilized TPEs reach automotive production lines.
Reactive processing technology is hybridizing conventional polyolefin elastomers with in-situ grafted stabilizer architectures. Tier 1 seal manufacturers in Stuttgart and Nagoya are piloting these systems for bumper fascia with Class A surface requirements. The approach collapses compounding and part production into integrated cells, reducing stabilizer migration risks.
REACH Annex XVII restrictions on microplastic release are compelling reformulation of exterior TPEs with enhanced surface durability. Compounders must demonstrate 15-year UV resistance without surface cracking that generates particulate shedding. German KBA type approval processes now incorporate accelerated wash-down testing that favors denser, cross-linked elastomer structures.
Automotive procurement teams are consolidating specification authority at platform engineering centers rather than regional purchasing offices. This centralization forces compounders to maintain technical sales presence in Wolfsburg, Toyota City, and Shanghai simultaneously. The shift rewards suppliers with global laboratory networks capable of local weathering validation.
UV Stabilized Thermoplastic Elastomer for Automotive Market Segmentation
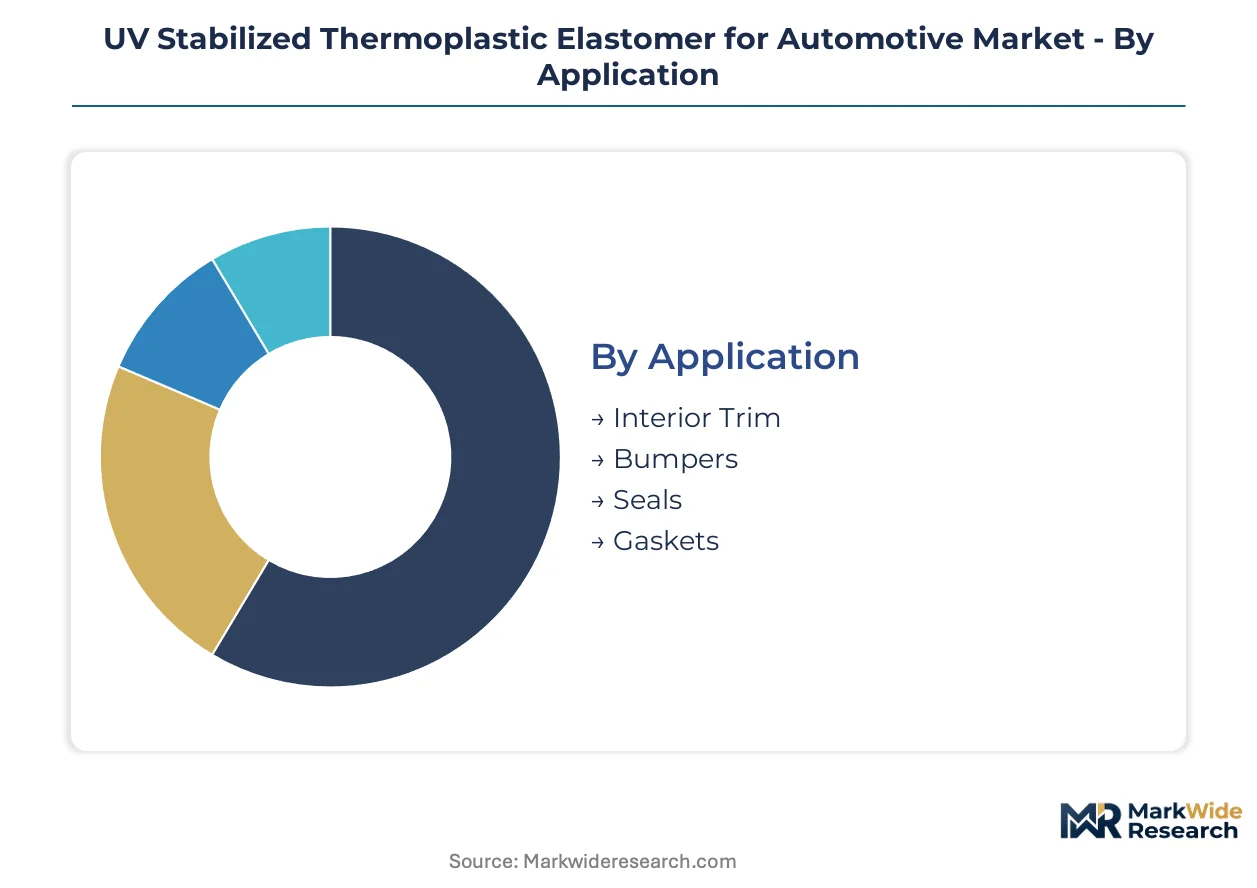
UV-stabilized TPE specification pathways diverge sharply across automotive subsystems, with material chemistry and processing constraints dictating viable segment combinations. Procurement teams map these intersections against regional weathering certification requirements and platform volume commitments.
Application:
Mature exterior sealing applications coexist with emerging ADAS enclosure specifications, creating divergent performance tiers across the automotive body-in-white.
- Interior Trim:Dashboard skins, door panels, and console surfaces utilize Shore A 60-85 TPE grades with hindered amine stabilizer packages formulated for GB/T 27630 low-VOC compliance. Yangtze River Delta OEMs specify these materials most intensively as domestic brands upgrade cabin air quality credentials.
- Bumpers:Class A fascia surfaces demand aliphatic polyurethane or advanced polyolefin matrices with 10-year color stability under ECE R43 xenon arc protocols. Reactive extrusion compounding is displacing conventional batch processes for these high-visibility components.
- Seals:Continuous extrusion profiles for door and glass run channels.
- Gaskets:Static compression seals for HVAC and powertrain interfaces.
Interior Trim handles the majority of throughput; Bumpers is the fastest mover on share.
End User:
Specification authority concentrates at platform engineering centers, compressing traditional multi-tier procurement hierarchies.
- OEMs:Volkswagen, Toyota, and BYD centralize material qualification at Wolfsburg, Toyota City, and Shenzhen technical centers. Direct compounder relationships now bypass traditional Tier-1 intermediaries for strategic TPE grades.
- Tier-1 Suppliers:Continental, Faurecia, and Yanfeng execute production contracts with locked formulation specifications. These suppliers absorb inventory risk while OEMs retain intellectual property over proprietary stabilizer blends.
- Aftermarket Providers:Independent distributors serving collision repair channels.
- Dealerships:Captive retail networks for OEM-certified replacement components.
OEMs dominate specification authority; Tier-1 Suppliers capture the steepest expansion trajectory as outsourcing accelerates.
Material Type:
Cost-performance positioning separates commodity polyolefin grades from premium polyurethane systems serving distinct warranty exposure profiles.
- Polyurethane:Aliphatic grades from Covestro's Desmopan range command exterior applications where hydrolysis resistance and color stability justify 40-60% price premiums over polyolefin alternatives. KBA type approval processes favor these materials for 15-year durability commitments.
- Styrenic Block Copolymer:SEBS and SIS matrices dominate interior soft-touch applications with Shore A ranges of 30-70. Cost efficiency and established recycling streams support volume deployment in mass-market vehicle platforms.
- Polyolefin:EPDM/PP dynamic vulcanizates for cost-sensitive sealing systems.
- Thermoplastic Polyurethane:Aromatic grades for abrasion-resistant underhood components.
Styrenic Block Copolymer handles the majority of throughput; Polyurethane is climbing the fastest on specification intensity.
Processing Method:
Equipment utilization rates and cycle time economics determine viable segment entry points for compounders.
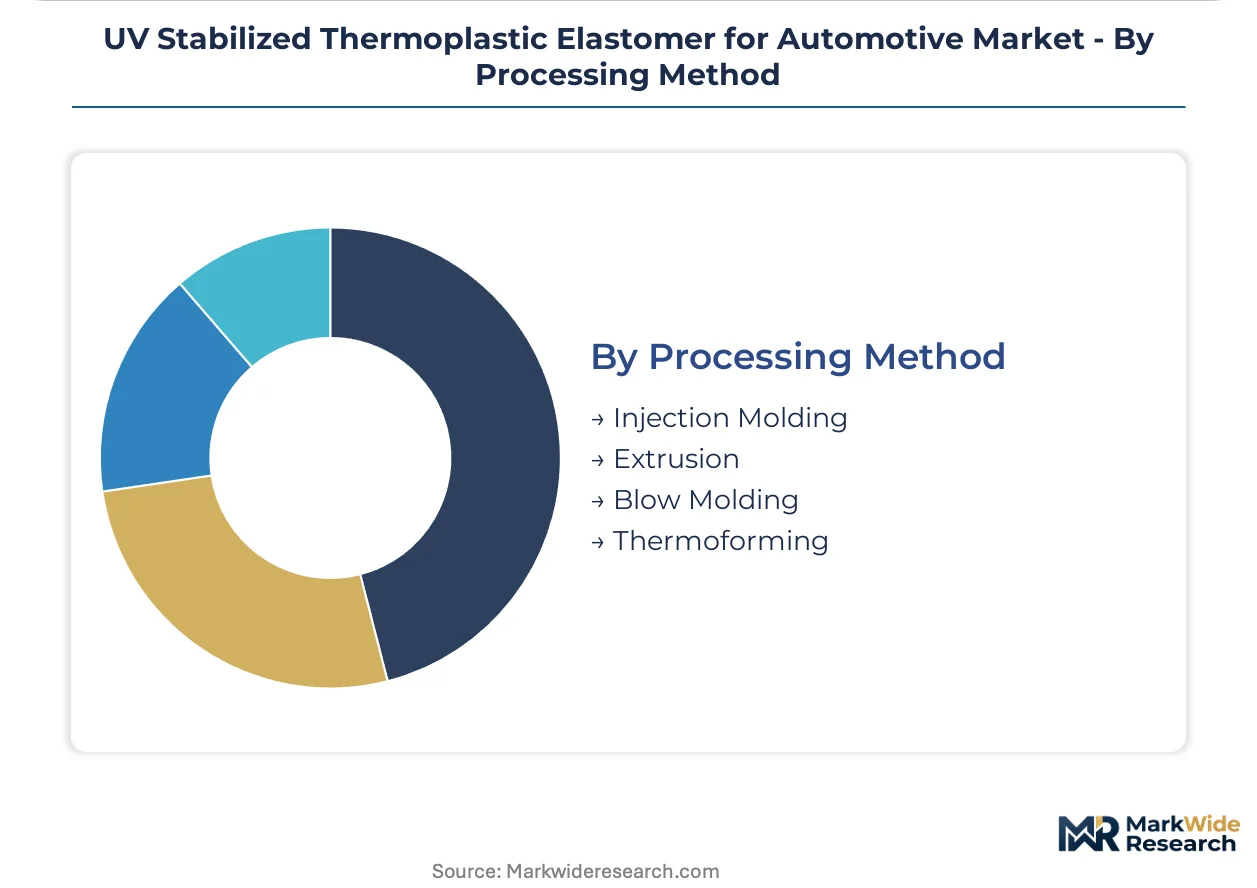
- Injection Molding:Complex geometries including bumper fascia, sensor housings, and interior handles utilize multi-cavity tooling with 60-90 second cycle times. Stuttgart-based seal manufacturers pilot reactive processing cells that integrate compounding and part production.
- Extrusion:Continuous profiles for door seals and glass run channels demand lot-to-lot color stability within Delta E 1.0 tolerances. Jiangsu province compounders specialize in these applications for German and Japanese OEM export programs.
- Blow Molding:Hollow ducting and reservoir components.
- Thermoforming:Large-format interior panels with textured surfaces.
Injection Molding handles the majority of throughput; Extrusion is gaining share fastest on sealing system content expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major automotive manufacturing bases. German OEMs prioritize exterior durability under ECE protocols, while Chinese producers optimize for interior air quality compliance. Japanese manufacturers balance both requirements through dual-certification strategies.
Germany
Exterior sealing systems drive specification intensity for UV-stabilized TPE grades. KBA type approval processes now mandate 15-year weathering performance without surface degradation. The Ruhr industrial region concentrates specialized compounding capacity serving Volkswagen and BMW platform engineering centers in Wolfsburg and Munich.
China
Domestic OEMs and joint ventures in the Yangtze River Delta specify low-VOC grades for dashboard and bumper fascia applications. MIIT new energy vehicle production quotas accelerate material qualification timelines under GB/T 27630 interior air quality standards. Jiangsu province compounders dominate export supply chains for German and Japanese automotive programs.
United States
EPA fuel economy standards and NHTSA safety regulations compel lighter-weight sealing solutions across Detroit Three platforms. Sealing profile manufacturers in Michigan and Ohio absorb inventory risk while OEMs retain proprietary stabilizer blend intellectual property. Direct compounder relationships now bypass traditional Tier-1 intermediaries for strategic grades.
Japan
Toyota City and Nagoya technical centers centralize material qualification authority for global platform deployment. JIS D 0205 weathering protocols intersect with ECE R43 requirements, creating dual-certification burdens for compounders. Reactive processing technology pilots are restructuring bumper fascia supply chains around integrated compounding-to-part production cells.
India
PLI scheme incentives for domestic automotive component manufacturing attract first-mover compounders establishing Bengaluru and Pune technical centers. BIS certification requirements for automotive materials create qualification bottlenecks that favor early entrants with established testing relationships. Domestic OEMs specify cost-sensitive sealing grades while premium import platforms demand polyurethane-based exterior solutions.
UV Stabilized Thermoplastic Elastomer for Automotive Market Key Industry Players
Capability concentration sits with specialized polyurethane and advanced polyolefin compounders; scale advantage sits with integrated petrochemical producers. The vendor base organizes around three strategic archetypes: integrated olefin feedstock operators, aliphatic polyurethane chemistry specialists, and bio-based elastomer innovators. M&A activity targets reactive processing technology assets, while capacity expansion concentrates in China's Jiangsu province and Germany's Ruhr region.
Within the integrated petrochemical tier, ExxonMobil and SABIC anchor cost-competitive polyolefin elastomer supply through captive feedstock positions. Covestro AG occupies the premium polyurethane vector with aliphatic Desmopan grades. Arkema S.A. represents the sustainability-focused archetype through bio-based Pebax elastomer positioning. These three company types exemplify how raw material access, chemistry specialization, and sustainability credentials stratify competitive positioning across exterior and interior automotive applications.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| ExxonMobil |
| SABIC |
| Covestro AG |
| Arkema S.A. |
| BASF SE |
| Kraton Corporation |
| LG Chem |
| Kraiburg TPE GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Hindered amine light stabilizer cost volatility on petrochemical-derived piperidine intermediates compresses both pricing tier spreads and supply chain configuration across automotive TPE compounders. Crude price swings force simultaneous margin pressure on standard polyolefin grades and premium polyurethane systems, reshaping procurement strategies toward captive stabilizer production or long-term offtake contracts.
Pricing Analysis
Geographic price spreads between Germany's Ruhr region and China's Jiangsu province reach 25-35% for equivalent UV-stabilized TPE grades due to divergent energy and regulatory compliance costs. Three-tier pricing structure across premium aliphatic polyurethane, standard hindered amine-stabilized polyolefin, and economy EPDM/PP grades reflects certification intensity under ECE R43 and GB/T 27630 protocols. Pricing pressure stems from Covestro's Desmopan capturing exterior fascia share with 10-year color stability warranties. Aftermarket distributors exhibit highest price sensitivity; OEM platform engineering centers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk as specialized compounding capacity concentrates in these two manufacturing clusters. Raw material flows draw from Saudi olefin feedstock, Japanese stabilizer additive packages, and Korean polyolefin elastomer intermediates. Single-source vulnerability on hindered amine light stabilizers from petrochemical-derived piperidine creates chokepoint exposure during crude volatility cycles. Distribution runs through Tier-1 seal manufacturers who absorb inventory risk while OEMs retain proprietary formulation intellectual property.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for weathering validation and lot-to-lot certification support are expanding faster than base material sales, creating recurring revenue pools that compound with automotive platform lifecycles. Compounders who attach predictive analytics and digital color matching services capture margin expansion unavailable to commodity resin suppliers.
For Market Incumbents: Build regulatory certification moats by securing simultaneous ECE R43, JIS D 0205, and GB/T 27630 qualifications at single technical centers. Pursue backward integration into hindered amine stabilizer production to deflect petrochemical price volatility. Expand compounding capacity in India's Bengaluru corridor ahead of PLI scheme maturation to preempt emerging entrant land grabs. For New Entrants and Emerging Players: Pursue ADAS sensor housing applications where electromagnetic shielding compatibility specifications remain undefined and incumbent qualification cycles lag. Target India's domestic OEM sealing programs where BIS certification bottlenecks favor early technical center establishment. Lead with reactive processing technology pilots that collapse compounding-to-part production timelines below 12 months. For Investors and Strategic Acquirers: EU Green Deal circular economy requirements reshape the acquisition landscape toward recyclable mono-material TPE systems qualifying for extended producer responsibility credits. Five-to-ten-year viability favors compounders with reactive extrusion technology assets and multi-protocol certification capabilities. Monitor KBA type approval timeline acceleration as the signal indicating consolidation pressure on non-integrated regional players.| Strategic Initiative | Industry Significance |
|---|---|
| Reactive Extrusion Technology Deployment | Integrates compounding and part production for Stuttgart and Nagoya bumper fascia programs. |
| Multi-Protocol Certification Investment | Compresses OEM qualification timelines from 18 months to under 12 months simultaneously. |
| Backward Integration into Stabilizers | Captures margin on hindered amine packages exposed to crude-derived piperidine volatility. |
| India Technical Center Establishment | Secures PLI scheme positioning ahead of BIS certification bottleneck formation. |
| Digital Color Matching Service Launch | Attaches recurring revenue to lot-to-lot Delta E 1.0 stability guarantees for extrusion profiles. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, and third-party weathering laboratory technicians; and secondary validation through customs trade databases, SEC 10-K chemical segment disclosures, and automotive production registration data. Bottom-up volume estimates from application-level content-per-vehicle assumptions were triangulated against top-down polymer compounding capacity utilization data across Germany's Ruhr region and China's Jiangsu province.
Forecast inputs span vehicle class segmentation, propulsion architecture mix shifts, and regional OEM platform engineering center concentration. Modeled dimensions include interior trim versus exterior sealing content intensity, polyolefin versus polyurethane chemistry share trajectories, and injection molding versus extrusion processing splits. CAGRs were derived from correlated regression against automotive production volume forecasts and regulatory mandate implementation timelines, with specific sensitivity to MIIT new energy vehicle quota acceleration and REACH Annex XVII microplastic restriction enforcement.
Sensitivities concentrate around crude price volatility on stabilizer input costs, KBA and SAMR regulatory timeline acceleration, and reactive processing technology adoption rates by major seal manufacturers. Forecasts reflect documented assumptions on OEM platform standardization trends and regional trade flow stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
Rigid Spray Polyurethane Foam Market
Polymers & Resins
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Polyamide 12 Market
Polymers & Resins
Vinyl Acetate Ethylene Copolymer Powder Market
Polymers & Resins
Polyisobutene Market
Polymers & Resins
Cellulosic Polymers Market
Polymers & Resins
Polymer Filler Market
Polymers & Resins
Polyimides Market
Polymers & Resins
Latent Curing Agents for Epoxy Resin Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market
Polymers & Resins
Polyether Polyols Market
Polymers & Resins
Polyamide-Imide (PAI) Market
Polymers & Resins
Global Thermoset Resin Market
Polymers & Resins
Liquid Polybutadiene [LPBD] Market