
 Europe Thermoplastic Elastomer (TPE) Market | 2026-2036
Europe Thermoplastic Elastomer (TPE) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Thermoplastic Elastomer (TPE) Market Foresight
Market Context
Germany's Rhineland chemical corridor is reshaping TPE supply dynamics as producers expand compounding capacity to serve just-in-time automotive sequences. BASF SE leverages its Ludwigshafen integrated site to sustain captive supply of polyether polyols for thermoplastic polyurethane grades. Arkema anchors specialty TPE production through its Pebax polyamide elastomer platform, while LANXESS competes in high-performance automotive sealing applications with its Bond-Laminates subsidiary.
Technical Definition and Segment Structure
Thermoplastic elastomers combine rubber-like elasticity at service temperatures with thermoplastic processability, typically exhibiting Shore A hardness ranging from 20 to 95 and melt flow indices enabling injection cycle times under 30 seconds. These materials serve as drop-in replacements for thermoset rubber and flexible PVC in applications requiring overmolding adhesion to engineering plastics and colorability without post-cure painting. Styrenic block copolymers occupy the volume leadership position in consumer goods and footwear due to established supply chains and formulation familiarity, while thermoplastic vulcanizates capture expanding share in under-the-hood automotive hoses and cable jacketing where heat aging resistance to 150°C defines specification compliance. Thermoplastic polyurethanes concentrate margin pools in medical device tubing and film laminates where USP Class VI biocompatibility and clarity requirements create qualification barriers.
Regulatory Framework and Outlook
REACH registration obligations administered by ECHA govern monomer and additive disclosure thresholds, while the EU Green Deal's packaging and automotive sector recycled content targets are forcing reformulation roadmaps. The F-Gas Regulation indirectly shapes TPE selection in HVAC and refrigeration gaskets as fluorocarbon elastomer alternatives face supply constraints. Stakeholders must monitor ECHA's SVHC candidate list expansion for plasticizer chemistries and calibrate R&D budgets between bio-based feedstock validation and mechanical recycling stream qualification.
Market Dynamics
REACH chemical compliance and the EU Green Deal's recycled content mandates are redirecting formulation strategies across Europe's TPE compounding base, forcing producers to validate bio-based feedstocks and mechanical recycling streams under tightening disclosure thresholds.
Growth Catalysts
- Automotive lightweighting:Germany and France specify TPE grades for instrument panels, airbag covers, and HVAC ducts, displacing conventional rubber and PVC in sealing systems and interior skins.
- ECHA SVHC expansion:The candidate list's growth for plasticizer chemistries accelerates reformulation toward safer alternatives, opening specification windows for compliant TPE families.
- Just-in-time automotive sequencing:Rhineland corridor producers expand compounding capacity to serve OEM supplier networks, tightening supply chain integration with tier-1 manufacturers.
Market Restraints
- Polyether polyol supply concentration:Captive production at Ludwigshafen-scale integrated sites limits independent compounder access to TPU feedstock, compressing margin pools for non-integrated players.
- F-Gas Regulation constraints:HVAC and refrigeration gasket specifications face fluorocarbon elastomer supply disruptions, yet TPE alternatives require costly heat-aging validation to 150°C.
- Mechanical recycling stream inconsistency:Post-consumer TPE feedstock exhibits batch-to-batch property variation, blocking qualification for medical device tubing and film laminate applications.
Strategic Opportunities
- Poland automotive supplier corridor:Volkswagen Group and Stellantis assembly expansion near Poznań and Gliwice creates unserved demand for localized TPE compounding and technical service.
- CSRD disclosure mandates:Corporate sustainability reporting requirements favor suppliers with verified bio-based content and carbon footprint transparency, rewarding early feedstock transition investments.
- 3D printing filament convergence:Fused deposition modeling adoption in prototyping and low-volume automotive tooling opens specification paths for flexible TPE filaments with Shore A 85-95 hardness.
Industry Challenges
- Biocompatibility certification timelines:USP Class VI validation for medical-grade TPU tubing requires 18-24 month qualification cycles, blocking fast-follower market entry.
- Compounding technician scarcity:Rheology optimization and twin-screw extrusion expertise concentrates among aging workforce cohorts in Germany's chemical corridor, constraining capacity expansion.
- Overmolding adhesion IP:Proprietary tie-layer chemistries for TPE-to-engineering-plastic bonding remain locked under exclusive licensing, fragmenting formulation freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Thermoplastic Elastomer (TPE) Market |
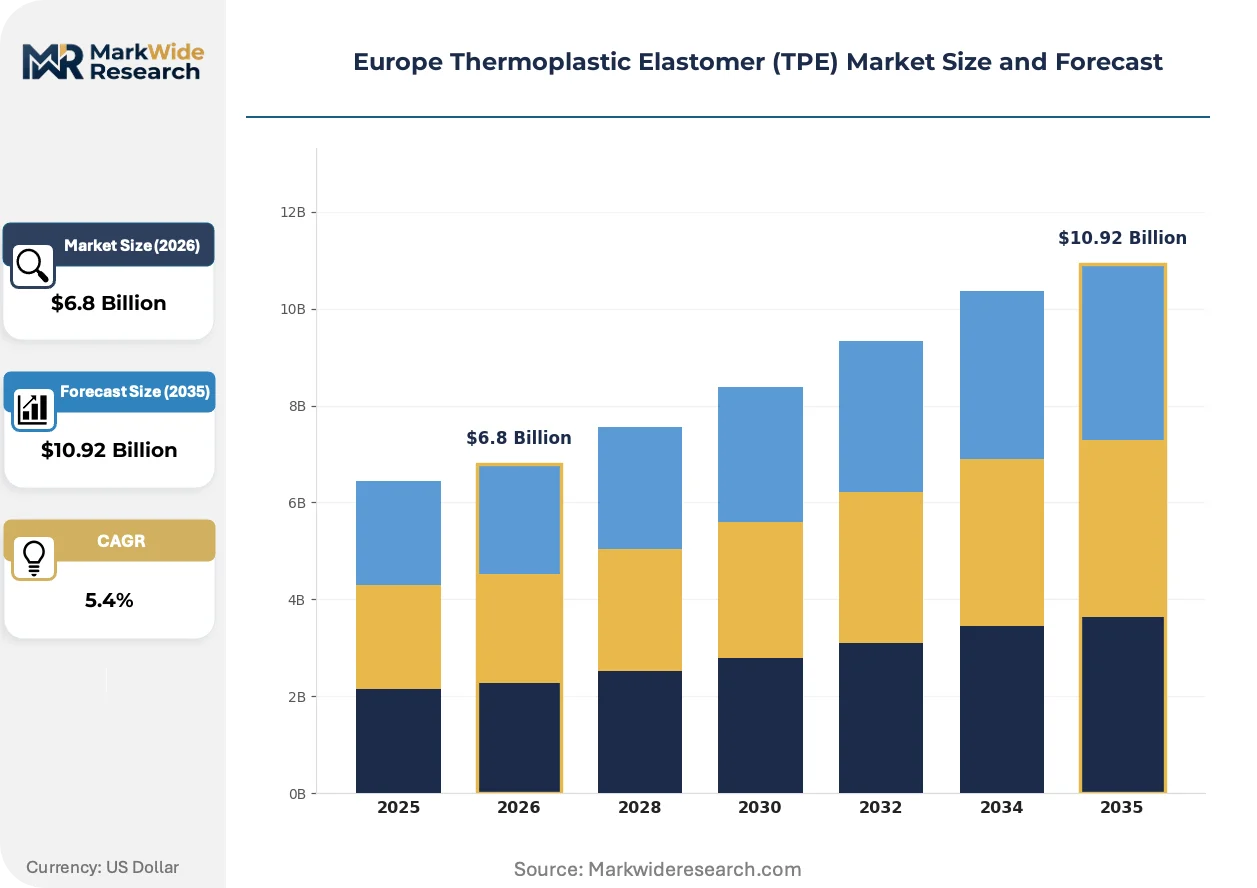
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrenic Block Copolymers, Thermoplastic Polyurethanes, Thermoplastic Polyolefins, Thermoplastic Vulcanizates Application: Automotive Interiors, Medical Devices, Consumer Products, Adhesives End User: Healthcare, Automotive, Electronics, Footwear Technology: Injection Molding, Blow Molding, Extrusion, 3D Printing |
| Companies Covered | KRATON CORPORATION, Arkema, BASF SE, Evonik Industries AG, LANXESS, Covestro AG, SABIC, LyondellBasell Industries Holdings BV, DuPont, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Thermoplastic Elastomer (TPE) Market Shifts & Advancements
Formulation science and regulatory chemistry are converging to redefine competitive advantage, as producers race to qualify sustainable feedstocks while maintaining performance parity with incumbent petrochemical grades.
Dynamic vulcanization technology is hybridizing with continuous compounding architectures to produce thermoplastic vulcanizates with improved compression set and fluid resistance. Tier-1 automotive suppliers in Stuttgart and Munich are adopting these grades for under-the-hood hose applications at accelerated validation cycles. This hybridization is compressing the performance gap between TPVs and thermoset EPDM, enabling specification capture in engine bay environments previously closed to thermoplastics.
REACH registration obligations administered by ECHA are tightening monomer and additive disclosure thresholds, forcing compounders to document full supply chain chemistry. Industrial consequence includes reformulation of legacy plasticizer packages and antioxidant systems to maintain registration compliance. Medical device and food contact segments are responding fastest, with Pebax and TPU grades leading qualification for reduced-substance-concern portfolios.
Specification-driven procurement is consolidating vendor panels as OEMs reduce approved material lists to streamline compliance auditing. Tier-2 and tier-3 compounders face exclusion from automotive qualification programs, replaced by integrated suppliers with captive analytical and regulatory affairs capabilities. France's medical device cluster around Lyon and Germany's automotive engineering centers exhibit the most pronounced supplier base consolidation.
Europe Thermoplastic Elastomer (TPE) Market Segmentation
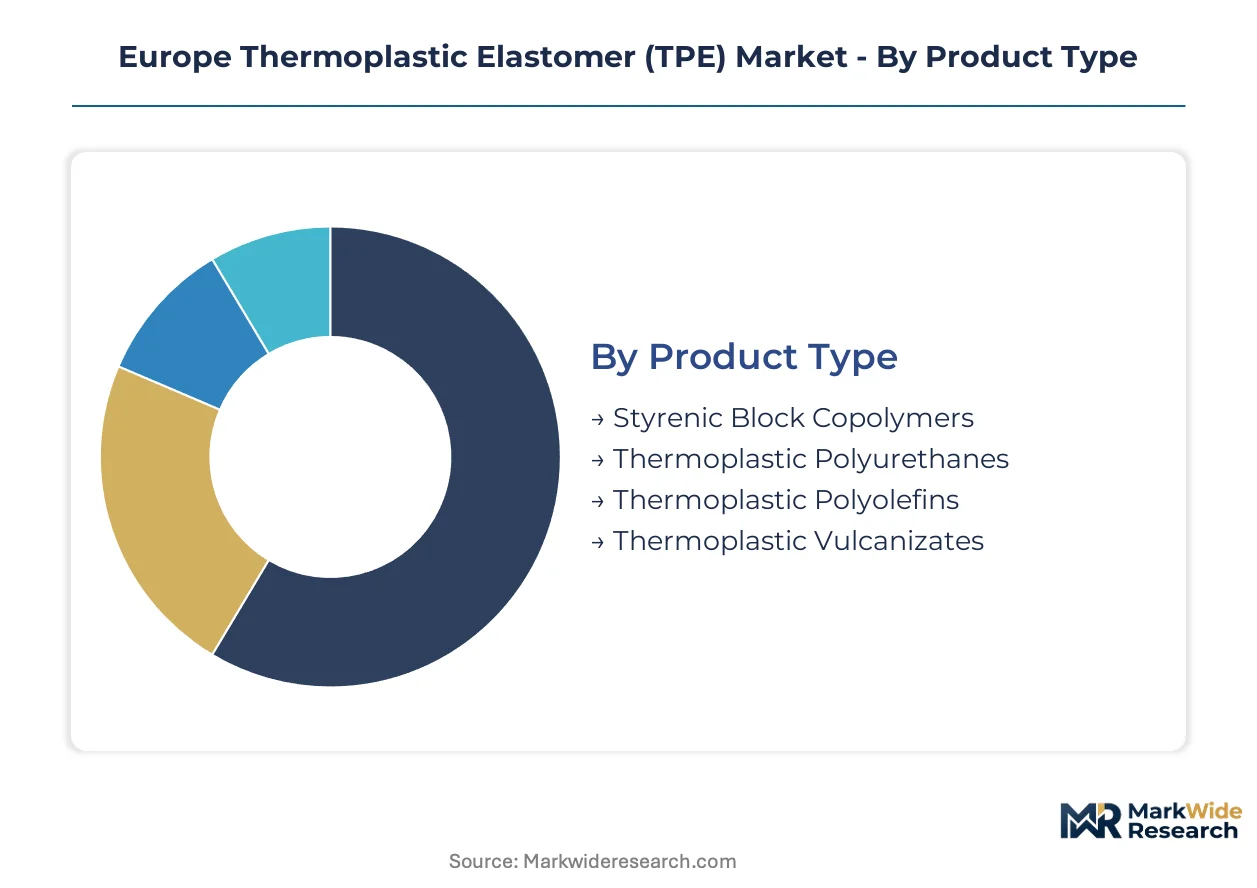
Product chemistry and processing technology create distinct margin pools across Europe's TPE landscape, with automotive qualification requirements and medical biocompatibility standards fragmenting specification tiers. Understanding how these dimensions intersect reveals where compounders can defend premium positioning versus commodity exposure.
Product Type:
Cost tier separation defines competitive dynamics, with feedstock integration and formulation complexity determining margin capture.
- Styrenic Block Copolymers:Hydrogenated mid-block architectures deliver Shore A 20-95 hardness ranges with rapid injection molding cycle times. Germany's consumer goods manufacturers and footwear producers in Portugal concentrate procurement around established SBC supply chains, though ECHA plasticizer scrutiny is forcing migration toward oil-extended hydrogenated grades.
- Thermoplastic Polyurethanes:Polyether and polyester backbone variants exhibit superior abrasion resistance and load-bearing capacity. Medical device tubing specifications in France's Lyon cluster and automotive film laminates across Bavaria drive demand for USP Class VI and FDA-compliant TPU grades, with polyether polyol supply concentration at integrated sites creating entry barriers.
- Thermoplastic Polyolefins:Polypropylene-based elastomer blends offer cost positioning against conventional EPDM rubber.
- Thermoplastic Vulcanizates:Dynamic vulcanization produces rubber particle dispersions in thermoplastic matrices with compression set performance approaching thermosets.
Styrenic block copolymers command the established base. The steepest expansion runs through thermoplastic vulcanizates.
Application:
Application-driven specification intensity separates medical and automotive segments from consumer goods on compliance burden and qualification timeline.
- Automotive Interiors:Overmolding adhesion to ABS and PC/ABS substrates enables soft-touch instrument panels and airbag covers without secondary painting. Volkswagen Group and Stellantis specifications across Germany, France, and Poland are displacing PVC skins and thermoset rubber seals with TPE alternatives that reduce part mass and enable recycling.
- Medical Devices:USP Class VI and ISO 10993 biocompatibility requirements govern tubing, catheters, and drug delivery components. France's medical device cluster around Lyon and Germany's precision tubing manufacturers concentrate demand for Pebax and medical-grade TPU, with 18-24 month validation cycles blocking fast-follower entry.
- Consumer Products:Toothbrush grips, tool handles, and sporting goods leverage TPE overmolding for ergonomic enhancement.
- Adhesives:Hot-melt and pressure-sensitive formulations exploit TPE block copolymer tack and cohesion balance.
Automotive interiors anchor volume concentration. Medical devices follow the steepest value-per-kilogram trajectory.
End User:
Customer type determines technical service intensity and formulation co-development depth, with automotive and healthcare demanding captive regulatory affairs support.
- Healthcare:Sterilization resistance and extractables testing requirements dominate material selection. German and French medical device OEMs specify reduced-substance-concern portfolios ahead of ECHA SVHC expansions, with compounders investing in dedicated cleanroom compounding and batch documentation systems.
- Automotive:Just-in-time sequencing and PPAP submission protocols favor suppliers with Rhineland corridor proximity. Tier-1 seating and interior module manufacturers in Stuttgart, Munich, and Paris specify TPE grades for dual-hardness injection molding and in-mold decoration compatibility.
- Electronics:Cable jacketing and connector seals require flame retardancy and electrical insulation balance.
- Footwear:Midsole cushioning and outsole traction components in Portugal and Italy's footwear districts exploit TPU and TPO rebound resilience.
Automotive procurement commands the largest absolute offtake. Healthcare end users are climbing the fastest on specification premium capture.
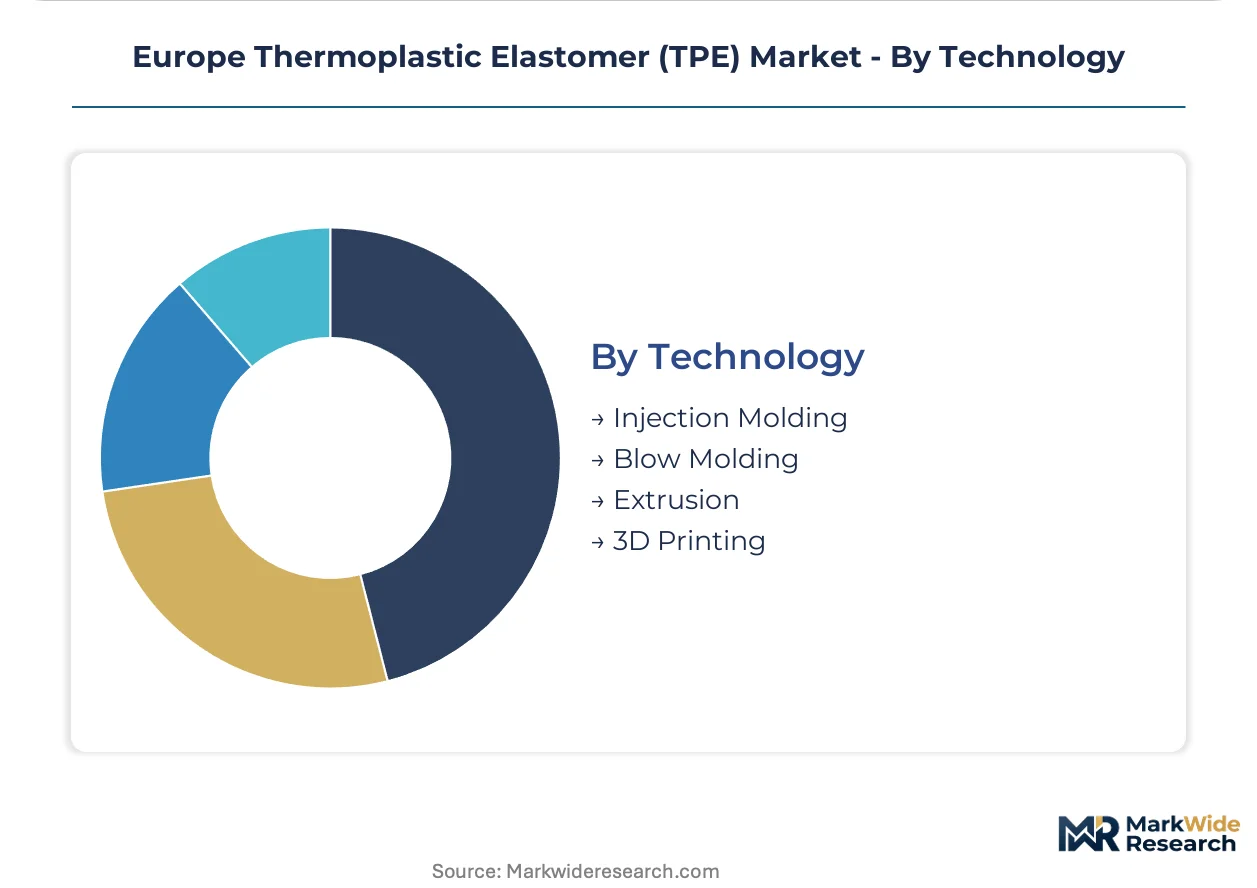
Technology:
Processing method selection ties directly to part geometry complexity, cycle economics, and post-processing elimination.
- Injection Molding:Multi-shot and overmolding configurations enable integrated soft-touch surfaces with engineering plastic substrates. Bavarian automotive suppliers and Lyon medical device molders dominate European installed capacity, with electric machine retrofits reducing energy intensity per part.
- Extrusion:Profile and sheet production serves weatherseals, gaskets, and film laminates with continuous output economics. German window profile manufacturers and HVAC duct suppliers specify TPE extrusion grades with calibrated melt strength for complex die geometries.
- Blow Molding:Hollow part production for ducts, bottles, and reservoirs exploits TPE flexibility and impact resistance.
- 3D Printing:Fused deposition modeling filament formulations enable prototyping and low-volume tooling applications.
Injection molding anchors the technology base. 3D printing filament demand is expanding most quickly from prototyping into production tooling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH registration obligations anchor Germany's regulatory dominance across Europe's TPE compounding base, with the EU Green Deal's recycled content mandates forcing feedstock transitions from the Rhineland corridor to Poland's emerging automotive supplier belt.
Germany
Volkswagen Group and Stellantis specify TPE grades for instrument panels and airbag covers across Stuttgart and Munich manufacturing centers. REACH SVHC candidate list expansions for plasticizer chemistries accelerate reformulation toward compliant hydrogenated styrenic block copolymers. BASF SE's Ludwigshafen integrated site sustains captive polyether polyol supply for thermoplastic polyurethane grades serving Bavarian automotive suppliers.
France
Medical device tubing demand concentrates around Lyon's precision healthcare cluster, where USP Class VI biocompatibility requirements govern Pebax and TPU grade selection. ANSM sterilization standards and ECHA substance disclosure obligations push compounders toward reduced-substance-concern portfolios. Renault and Stellantis specifications for soft-touch interior skins displace PVC across Paris-region assembly plants.
Poland
Volkswagen Group Poznań and Stellantis Gliwice assembly expansion creates unserved demand for localized TPE compounding capacity. EU Green Deal automotive sector recycled content targets redirect formulation strategies toward mechanically recycled feedstock validation. Poznań's supplier corridor attracts technical service investments from Rhineland compounders seeking just-in-time sequencing proximity.
Italy
Footwear midsole and outsole producers in Veneto exploit TPU rebound resilience for athletic and luxury shoe applications. ECHA disclosure thresholds for monomer chemistry reshape antioxidant and plasticizer package selection across Lombardy compounding operations. Milan-region automotive seating suppliers specify TPE overmolding grades for dual-hardness injection molding compatibility.
Netherlands
Rotterdam chemical logistics infrastructure supports polyether polyol import and distribution for independent TPU compounders lacking captive feedstock. CSRD disclosure mandates favor suppliers with verified bio-based content transparency across Randstad industrial procurement. Covestro AG's Dutch operations exemplify integrated supply chain positioning for European film laminate applications.
Europe Thermoplastic Elastomer (TPE) Market Competitive Landscape
Capability concentration sits with integrated petrochemical majors possessing captive feedstock and regulatory affairs infrastructure; scale advantage sits with diversified material science conglomerates serving multiple polymer families. The vendor base stratifies across three tiers: integrated producers with Ludwigshafen-scale polyol production, specialty compounders with medical-grade cleanroom capacity, and regional distributors with formulation technical service. Dominant competitive moves include backward integration into bio-based feedstock cultivation and strategic partnerships with automotive tier-1 suppliers for just-in-time sequencing contracts.
Within the integrated producer tier, BASF SE and Covestro AG exemplify petrochemical majors with captive supply chain control over critical TPU intermediates. Arkema occupies a distinct position among specialty material architects through its Pebax polyamide elastomer platform. These three companies represent divergent strategic postures: BASF SE anchors volume supply through Ludwigshafen integration, Covestro AG leverages Rotterdam logistics for polyether polyol distribution, and Arkema concentrates margin capture in medical and high-performance automotive specifications.
| Leading Market Players |
|---|
| KRATON CORPORATION |
| Arkema |
| BASF SE |
| Evonik Industries AG |
| LANXESS |
| Covestro AG |
| SABIC |
| LyondellBasell Industries Holdings BV |
| DuPont |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors transmit polyether polyol cost volatility directly into TPU grade pricing spreads, compressing margin pools for non-integrated compounders while rewarding Ludwigshafen-scale producers with captive feedstock leverage across premium specification tiers.
Pricing Analysis
Geographic price spreads between Rhineland corridor producers and Polish independent compounders reflect polyether polyol supply concentration. Three-tier pricing structure across medical-grade, automotive-qualified, and standard industrial levels separates USP Class VI certified TPU from uncertified commodity grades. Cost compression in standard industrial tiers stems from SBC oversupply in footwear applications. Consumer goods manufacturers exhibit highest price sensitivity; medical device OEMs accept premium positioning for validated biocompatibility documentation.
Supply Chain Analysis
Extended payment terms from Volkswagen Group and Stellantis tier-1 suppliers strain working capital for independent compounders lacking supply-chain finance facilities. Feedstock sourcing concentrates in Germany, Belgium, and the Netherlands for polyether polyol production; mechanical recycling feedstock draws from France and Italy post-consumer collection streams. Single-source vulnerability sits with Ludwigshafen-scale polyol production. Distribution runs through just-in-time sequencing hubs serving Stuttgart, Munich, and Poznań automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rheology optimization expertise and twin-screw extrusion technician scarcity concentrates among aging workforce cohorts in Germany's chemical corridor, constraining capacity expansion and fragmenting competitive response speed across formulation tiers.
For Market Incumbents: Pre-empt qualification displacement by accelerating bio-based feedstock validation ahead of EU Green Deal recycled content mandates. Capture just-in-time sequencing contracts with Poznań automotive suppliers before Rhineland corridor proximity advantages erode. Consolidate regulatory affairs capabilities to defend vendor panel positions against integrated petrochemical majors.
For New Entrants and Emerging Players: Pursue medical-grade cleanroom compounding capacity in France's Lyon cluster where USP Class VI validation timelines block fast-follower entry. Target Poland automotive supplier corridor for localized technical service investments. Differentiate through CSRD-compliant carbon footprint transparency to capture sustainability-driven procurement.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking portfolio simplification; specialty TPE divisions with captive medical certification offer defensive positioning. Five-to-ten year viability hinges on bio-based feedstock transition completion. Signal to watch: ECHA SVHC candidate list expansion pace for plasticizer chemistry disqualification.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstock | Arkema's Pebax platform validates castor-oil derived polyamide elastomer supply security ahead of REACH disclosure tightening. |
| Medical-Grade Cleanroom Capacity Expansion | LANXESS Bond-Laminates subsidiary captures Lyon cluster tubing demand through ISO 13485 certified compounding infrastructure. |
| Just-in-Time Sequencing Proximity Investment | Poznań corridor localization enables Volkswagen Group Poznań assembly plant specification capture against Rhineland incumbents. |
| Dynamic Vulcanization Technology Licensing | TPV hybrid architectures compress performance gap with thermoset EPDM for under-the-hood Stuttgart supplier adoption. |
| CSRD Disclosure Infrastructure Buildout | Verified bio-based content transparency rewards early feedstock transition investments across Randstad industrial procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA registration databases, Cefic polymer trade statistics, and automotive OEM specification sheets. Plant managers at Rhineland compounding facilities, procurement leads at Stuttgart tier-1 suppliers, and regulatory affairs directors at medical device OEMs provided operational validation. Bottom-up volume estimates from grade-level production data triangulate against top-down demand aggregation across automotive, medical, and consumer end-use segments.
Forecast inputs incorporate REACH SVHC expansion scenarios, EU Green Deal recycled content mandate implementation trajectories, and automotive lightweighting program specifications across the projection horizon. Segmentation dimensions model product chemistry tier, application specification intensity, end-user compliance burden, and regional production cluster proximity. CAGRs derive from elasticity-adjusted demand curves calibrated to OEM qualification cycle timelines and compounding capacity expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, polyether polyol feedstock costs, or euro-zone industrial energy pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation pace and substitution elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
Polyolefin Elastomer Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
Cold Cast Elastomers Market
Elastomeric Membrane
Styrene Ethylene Butylene Styrene (SEBS) Market
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Global Thermoplastic Elastomers (TPE) Market