
 Thermoplastic Polyester Elastomer Market | 2026-2036
Thermoplastic Polyester Elastomer Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Polyester Elastomer Market Intelligence
REACH is decoupling European market access from legacy formulation practices, forcing reformulation investments that favor incumbents with dedicated compliance infrastructure. DuPont leverages its polymer science depth to sustain premium positioning in medical-grade TPE grades. BASF SE anchors supply security through backward integration into petrochemical feedstocks. Celanese Corporation competes on manufacturing scale, operating large-volume reactors that reduce unit costs for automotive tier suppliers.
Thermoplastic polyester elastomer is a segmented copolyester combining hard crystalline polybutylene terephthalate blocks with soft amorphous polyether or polyester segments, delivering Shore D hardness ranging from 32 to 82 alongside resistance to oils, fuels, and elevated temperatures up to 150°C; this composition enables replacement of vulcanized rubber and flexible PVC in dynamic sealing, hose, and cable jacket applications. Automotive Components dominates application demand as OEMs specify these materials for airbag systems and constant velocity joint boots, while Medical Devices represents the fastest-expanding segment where USP Class VI compliance commands substantial margin premiums over industrial grades. TPC product types occupy the technical high ground in powertrain applications, whereas TPE formulations penetrate consumer goods through cost-optimized injection molding cycles.
FDA material master files and EU MDR biocompatibility requirements govern medical device applications, while EPA fuel permeation standards drive automotive formulation chemistry. ISO 10993 testing protocols create a harmonized baseline for healthcare market entry, though national deviations in cytotoxicity thresholds fragment certification pathways. Stakeholders must monitor regulatory divergence between FDA and EMA guidance documents as dual-track approval strategies become essential for capturing medical-grade margin pools.
Market Dynamics
Automotive OEMs are consolidating supplier bases for under-the-hood components while simultaneously fragmenting specification requirements across regional regulatory regimes. This dual pressure compresses margins for compounders lacking dedicated compliance infrastructure or captive feedstock supply.
Growth Catalysts
- EPA fuel permeation standards:Stringent evaporative emission limits in the United States are mandating advanced elastomer formulations for fuel system components, forcing material upgrades across supplier tiers.
- China's automotive cluster expansion:OEM localization in Jiangsu and Zhejiang provinces is generating concentrated demand for high-temperature-resistant sealing solutions in powertrain assemblies.
- Biocompatible grade proliferation:USP Class VI and ISO 10993 certification pipelines are opening margin-rich pathways into surgical instrument housings and drug delivery device components.
Market Restraints
- Petrochemical feedstock volatility:Butanediol and dimethyl terephthalate price swings compress compounder margins unpredictably, particularly for non-integrated producers.
- German supply concentration:A disproportionate share of medical-grade certification expertise and specialized compounding capacity resides with incumbent European suppliers, creating entry barriers.
- Technical ceiling in extreme temperatures:Performance degradation above 150°C limits penetration into next-generation electric vehicle battery thermal management systems where silicone elastomers dominate.
Strategic Opportunities
- India's medical device PLI scheme:Production-linked incentives for domestic manufacturing of critical care equipment are creating localized demand for certified TPE compounds.
- Overmolding convergence with metal inserts:Hybrid metal-polymer structural components in lightweight automotive assemblies represent unexploited specification territory.
- Direct-to-device-maker distribution:Bypassing traditional distributor networks through qualified supplier programs at major hospital purchasing consortia captures margin otherwise lost to intermediaries.
Industry Challenges
- Dual-track FDA-EMA certification timelines:Divergent biocompatibility testing protocols between agencies extend product launch cycles and duplicate validation expenditure for medical-grade entrants.
- Legacy injection molding equipment retrofit costs:Processing TPE-E materials requires precise temperature control and drying systems that many tier-two automotive suppliers lack, creating adoption friction.
- Specialized polymer engineering talent scarcity:Formulation chemists with copolyester block architecture expertise command premium compensation and concentrate at established compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Polyester Elastomer Market |
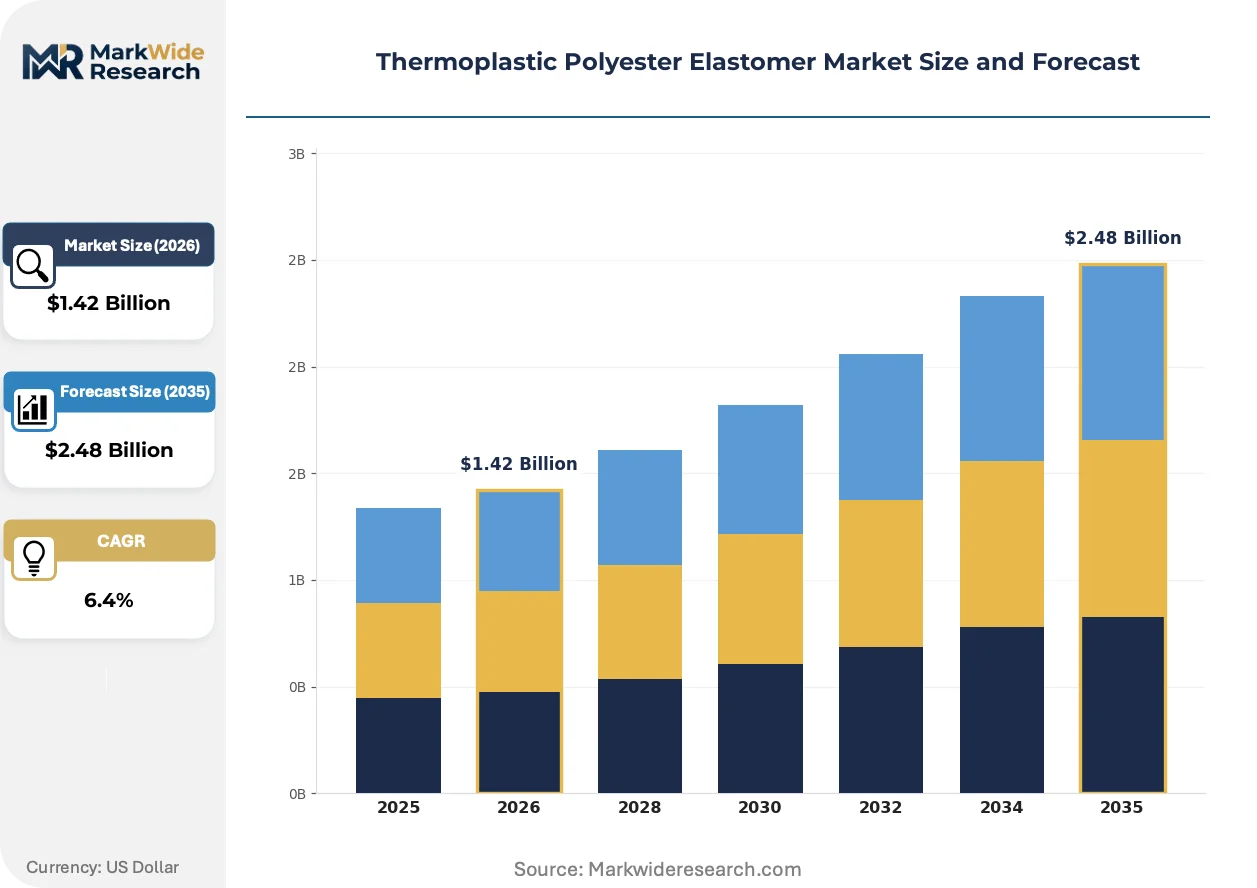
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
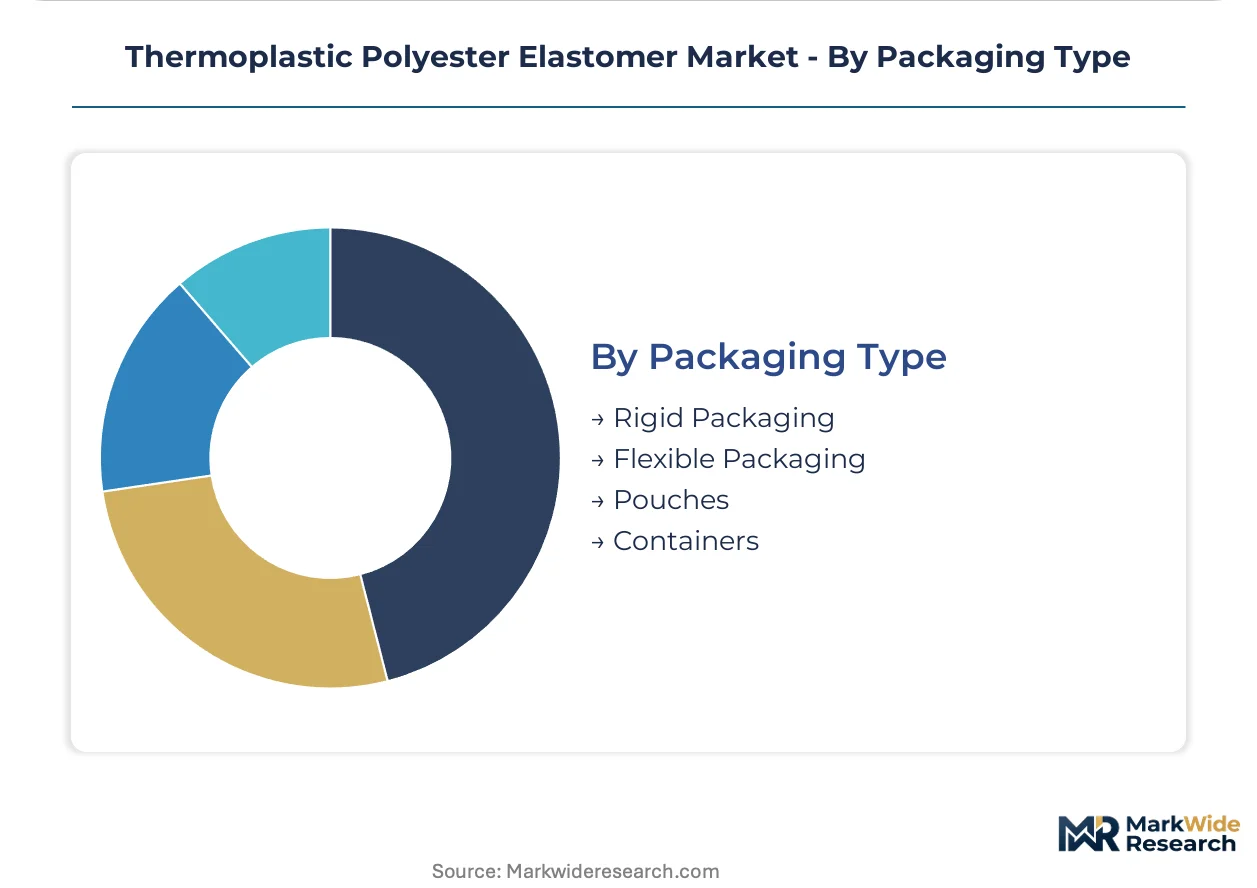
| Segmentation | Product Type: TPU, TPE, TPC, TPA Application: Automotive Components, Consumer Goods, Medical Devices, Industrial Applications End User: Automotive, Healthcare, Footwear, Electronics Packaging Type: Rigid Packaging, Flexible Packaging, Pouches, Containers |
| Companies Covered | DuPont, Celanese Corporation, BASF SE, SABIC, Covestro, LG Chem, Toyobo Co., Ltd., Teijin Plastics, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Polyester Elastomer Market Strategic Shifts & Innovations
Bio-based feedstock integration and closed-loop recycling protocols are redefining material qualification pathways. These developments intersect with tightening regulatory disclosure requirements and OEM sustainability scorecards.
Additive manufacturing-grade TPE-E filament development is decentralizing prototype-to-production workflows for medical device housings. Tier-one suppliers in Minnesota and Baden-Württemberg are qualifying powder-bed fusion and material extrusion processes for short-run surgical instrument grips. This capability compression is collapsing traditional tooling lead times and enabling patient-specific device geometries without mold fabrication.
REACH authorization list expansion is forcing systematic substitution of legacy plasticizers and stabilizers in European-sourced compounds. ECHA's 2024-2025 candidate substance updates are triggering reformulation cycles across automotive interior and under-hood applications. German compounders with dedicated regulatory affairs teams are capturing specification wins from competitors scrambling to maintain market access.
Consolidated procurement at multi-brand automotive groups is compressing supplier lists and demanding systems-level material warranties rather than compound-level specifications. Buyers in Stuttgart and Detroit are shifting risk onto compounders for full-component performance validation. This accountability transfer favors vertically integrated suppliers with in-house testing and simulation capabilities over specialized material-only vendors.
Thermoplastic Polyester Elastomer Market Segmentation
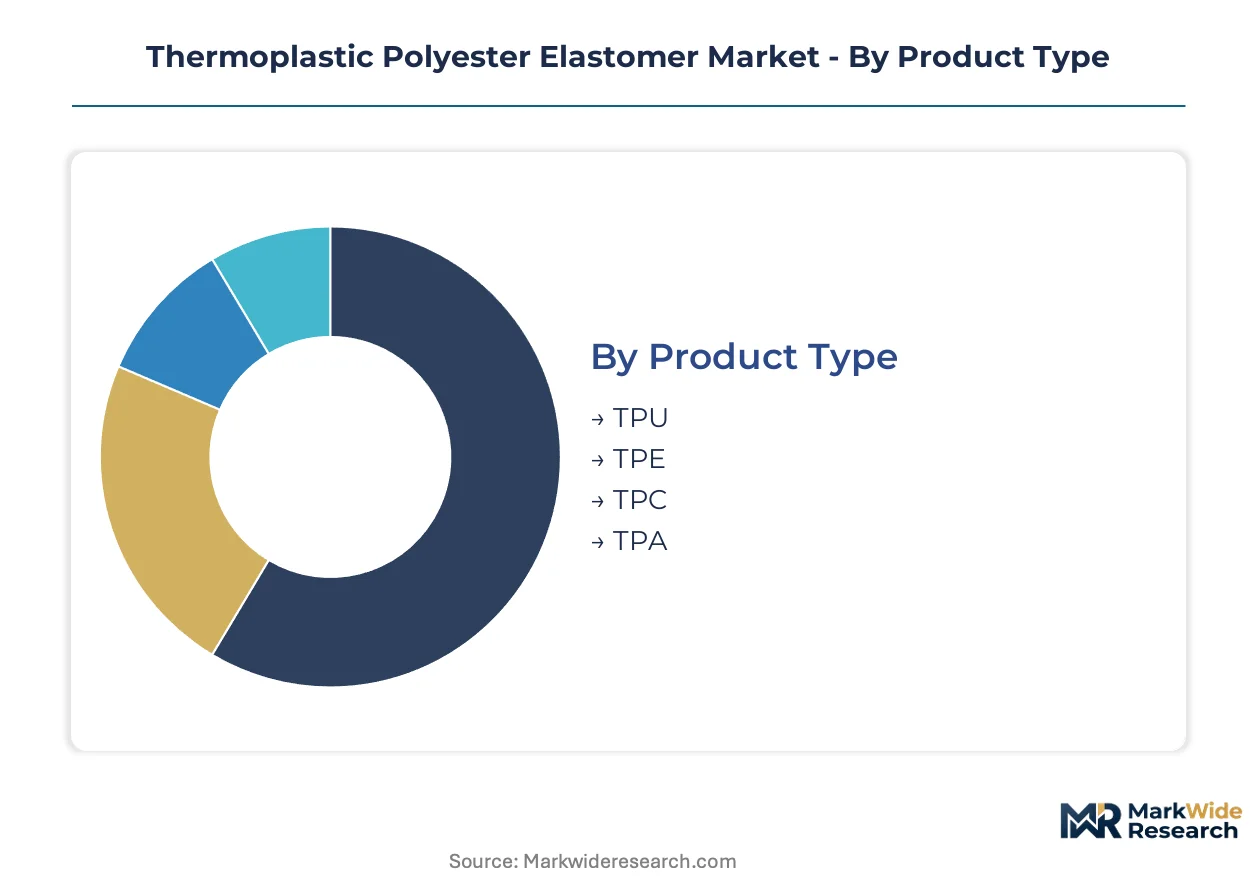
Segmentation in thermoplastic polyester elastomers reveals how material specifications diverge across regulatory regimes and end-use performance requirements. Each category maps distinct upgrade cycles—from automotive powertrain refreshes to medical device recertification timelines—that reshape procurement patterns and margin structures.
Product Type:
Material substitution cycles in automotive sealing and medical tubing are accelerating specification shifts across copolyester grades.
- TPC:Combines hard polybutylene terephthalate crystalline blocks with soft polyether segments, delivering Shore D hardness from 32 to 82 and continuous service temperatures to 150°C. German OEMs specify TPC grades for constant velocity joint boots and airbag deployment systems where resistance to oils, fuels, and hydrolysis is mandatory. REACH authorization pressures are filtering out legacy plasticizers, favoring TPC formulations with dedicated compliance documentation.
- TPE:Cost-optimized copolyester formulations penetrate consumer goods through faster injection molding cycles and lower processing temperatures. Jiangsu and Zhejiang automotive clusters source TPE compounds for interior applications where fuel resistance requirements are less stringent than under-hood specifications. The grade trades off thermal ceiling against unit economics in high-volume exterior trim.
- TPU:Delivers abrasion resistance and load-bearing capacity for industrial belting and power transmission components.
- TPA:Serves niche applications requiring specific flexibility and chemical resistance profiles in specialty film and coating markets.
Volume placements concentrate in TPE; the faster expansion belongs to TPC.
Application:
End-use diversification follows divergent regulatory clock speeds—automotive model cycles versus medical device recertification windows.
- Automotive Components:Dominates consumption through under-hood sealing, hose, and cable jacket applications where replacement of vulcanized rubber and flexible PVC is ongoing. EPA fuel permeation standards mandate material upgrades across supplier tiers, with Detroit and Stuttgart procurement offices consolidating approved compounder lists. Airbag systems and constant velocity joint boots represent specification anchors with multi-year qualification timelines.
- Medical Devices:USP Class VI and ISO 10993 certification pipelines command substantial margin premiums over industrial grades. Surgical instrument housings and drug delivery device components in Minnesota and Baden-Württemberg manufacturing clusters demand biocompatible grades with FDA master file documentation. Dual-track FDA-EMA certification strategies extend launch cycles but unlock higher pricing tiers.
- Consumer Goods:Absorbs cost-optimized formulations through footwear midsoles and ergonomic grips with shorter qualification paths.
- Industrial Applications:Serves power transmission, conveyor systems, and fluid handling equipment requiring abrasion and chemical resistance.
Procurement scale favors Automotive Components; margin expansion concentrates in Medical Devices.
End User:
Customer concentration patterns reflect regional manufacturing cluster development and regulatory proximity.
- Automotive:OEM localization in China's Jiangsu and Zhejiang provinces, Germany's supplier belt, and the US Midwest generates concentrated demand for high-temperature sealing solutions. Tier-one suppliers face consolidated procurement at multi-brand groups demanding systems-level material warranties rather than compound-level specifications.
- Healthcare:Hospital purchasing consortia and device manufacturers in the US and Germany drive certified compound demand with qualified supplier programs bypassing traditional distribution.
- Footwear:Midsole and outsole applications in Asian manufacturing hubs absorb volume grades with rapid color-matching capabilities.
- Electronics:Cable jacket and connector seal applications in consumer device supply chains prioritize halogen-free and flame-retardant formulations.
Contract value aggregates with Automotive; certification intensity peaks with Healthcare.
Packaging Type:
Material handling requirements diverge between bulk industrial shipment and cleanroom medical delivery.
- Flexible Packaging:Dominates medical-grade compound delivery where moisture barrier properties and particulate control are essential for USP Class VI certified materials.
- Rigid Packaging:Serves automotive tier suppliers with drum and pail formats optimized for automated feeding systems.
- Pouches:Supports sample and trial quantities for qualification programs at device manufacturers.
- Containers:Handles bulk industrial shipments with standard handling and storage protocols.
Specification density runs highest through Flexible Packaging; throughput volume flows through Rigid Packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, China, and the United States as OEMs regionalize supply chains and tighten material specifications under divergent regulatory regimes. Each geography presents distinct procurement patterns shaped by automotive cluster development and medical device certification intensity.
Germany
Baden-Württemberg and Stuttgart anchor European demand for under-the-hood TPC grades specified for constant velocity joint boots and airbag deployment systems. REACH authorization pressures filter out legacy plasticizers, favoring compounders with dedicated compliance infrastructure. German suppliers capture specification wins through backward integration into petrochemical feedstocks and in-house regulatory affairs teams.
China
Jiangsu and Zhejiang provinces generate concentrated demand as OEM localization accelerates powertrain sealing procurement. MIIT fuel economy standards and GB automotive emission regulations mandate material upgrades across supplier tiers. Shanghai and Suzhou manufacturing clusters source high-temperature-resistant compounds for localized assembly operations serving domestic and export markets.
United States
EPA fuel permeation standards drive automotive formulation chemistry for evaporative emission controls in Detroit and Midwest automotive corridors. Minnesota medical device manufacturing clusters demand USP Class VI certified grades with FDA master file documentation. Tier-one suppliers face consolidated procurement at multi-brand groups demanding systems-level material warranties.
Japan
METI industrial standards and automotive lightweighting mandates sustain demand for TPC grades in powertrain and chassis applications. Nagoya and Toyota City manufacturing belts specify these elastomers for dynamic sealing in hybrid powertrain assemblies. Domestic compounders maintain supply security through captive polymerization capacity and JIS standard certification pipelines.
India
Maharashtra and Gujarat medical device manufacturing zones absorb certified TPE compounds under the PLI scheme for critical care equipment. CDSCO medical device regulations and BIS material standards create dual-track compliance requirements for entrants. Pune and Ahmedabad clusters localize procurement for surgical instrument housings and drug delivery components.
Thermoplastic Polyester Elastomer Market Key Industry Players
German producers anchor one tier; United States specialists hold premium medical-grade positioning through FDA master file infrastructure. The vendor base fragments across regional compounders serving automotive tier suppliers and consolidated healthcare procurement. Three archetypes dominate: petrochemical-integrated majors with captive feedstock supply, medical-grade specialists commanding certification premiums, and Asian scale players penetrating cost-sensitive consumer goods. Competitive moves concentrate on backward integration into butanediol and dimethyl terephthalate supply, alongside dual-track FDA-EMA certification investments for medical device market access.
Among diversified chemical majors, DuPont, Celanese Corporation, and BASF SE occupy positions exemplifying distinct strategic archetypes. DuPont represents polymer science depth sustaining premium positioning in medical-grade segments. Celanese Corporation exemplifies manufacturing scale through large-volume reactor operations reducing unit costs for automotive procurement. BASF SE anchors supply security through in-house production of petrochemical feedstocks, capturing specification wins from non-integrated competitors facing margin compression from raw material volatility.
| Leading Market Players |
|---|
| DuPont |
| Celanese Corporation |
| BASF SE |
| SABIC |
| Covestro |
| LG Chem |
| Toyobo Co., Ltd. |
| Teijin Plastics |
| Arkema |
| Others |
Cost & Logistics Intelligence
Tier-one automotive procurement offices in Stuttgart and Detroit command contract-based long-term offtake structures that compress spot-market premiums for compounders lacking captive feedstock supply. REACH-driven reformulation cycles and EPA fuel permeation mandates are fragmenting specification requirements, forcing price stratification across certification tiers rather than commodity grades.
Pricing Analysis
Short lead-time premiums for medical-grade USP Class VI compounds with FDA master file documentation command substantial markups over standard industrial grades with longer qualification windows. Three-tier pricing structure across premium, standard, and economy levels separates biocompatible surgical instrument housings from automotive under-hood sealing and consumer goods midsoles. Cost compression in automotive TPE formulations is intensifying because OEM consolidated procurement shifts risk onto compounders for full-component validation. Tier-two automotive suppliers exhibit highest price sensitivity due to legacy injection molding equipment retrofit burdens, while medical device manufacturers absorb premium pricing for dual-track FDA-EMA certification assurance.
Supply Chain Analysis
Specialized polymer engineering talent scarcity in Germany, China, and the United States concentrates formulation expertise at established compounders with captive polymerization capacity. Butanediol and dimethyl terephthalate feedstock supply draws from petrochemical complexes in Ludwigshafen, Nanjing, and the US Gulf Coast. Single-source vulnerability in medical-grade certification expertise creates procurement bottlenecks for entrants lacking Baden-Württemberg regulatory affairs infrastructure. Distribution runs through qualified supplier programs at hospital purchasing consortia for medical grades and automated drum handling systems for automotive tier suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where backward integration into butanediol and dimethyl terephthalate supply separates margin-sustainable incumbents from feedstock-exposed competitors facing petrochemical price volatility.
For Market Incumbents: Cement supply security through captive polymerization capacity additions in Jiangsu and Zhejiang provinces where OEM localization accelerates. Deepen FDA master file infrastructure against emerging Asian compounders seeking USP Class VI certification shortcuts. Prioritize in-house regulatory affairs teams to capture REACH authorization wins as ECHA candidate substance updates trigger systematic substitution cycles.
For New Entrants and Emerging Players: Launch via direct-to-device-maker distribution bypassing traditional medical compound distributors in Minnesota and Baden-Württemberg manufacturing clusters. Target India's PLI scheme medical device zones in Maharashtra and Gujarat where certified TPE compound localization demand outpaces incumbent supply response. Penetrate through overmolding convergence with metal inserts in lightweight automotive assemblies where specification territory remains unexploited.
For Investors and Strategic Acquirers: Distressed-cycle entries favor non-integrated compounders with stranded medical-grade certification pipelines in Germany facing feedstock margin compression. Long-term viability across the analysis window hinges on backward integration completion or niche biocompatible grade defensibility. Watch for ECHA authorization list acceleration as inflection indicator for regulatory-driven consolidation windows favoring compliance-infrastructure-heavy acquirers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | BASF SE's Ludwigshafen complex demonstrates margin insulation against butanediol price swings. |
| Dual-Track FDA-EMA Certification Investment | DuPont's polymer science depth sustains premium positioning in USP Class VI surgical instrument housings. |
| Regional Manufacturing Footprint Expansion | Celanese Corporation's large-volume reactors reduce unit costs for Jiangsu automotive tier suppliers. |
| Long-term Supply Agreement with OEM Procurement | Multi-brand automotive groups in Stuttgart demand systems-level material warranties from compounders. |
| Green Manufacturing Transition | Bio-based feedstock integration intersects with OEM sustainability scorecards and REACH disclosure requirements. |
Research Approach
Multi-period observation of EPA fuel permeation standard evolution, REACH authorization list expansion, and OEM supplier consolidation patterns anchored the trend analysis, supplemented by interviews with polymer formulation chemists, Tier 1 automotive procurement directors, medical device regulatory affairs leads, and hospital GPO contracts managers. Secondary validation drew from ECHA substance databases, FDA 510(k) filing records, SEC 10-K petrochemical segment disclosures, and MIIT fuel economy standard updates. Bottom-up volume modeling across copolyester grades triangulated against top-down automotive production cluster demand estimates.
Segment-weighting approaches distributed value projections across TPC, TPE, TPU, and TPA product types by hardness tier, thermal ceiling, and certification intensity. End-use industry segmentation captured automotive powertrain refresh cycles, medical device recertification windows, and consumer goods injection molding velocity differentials. CAGRs were derived from compound annual growth rate calculation across the projection horizon, incorporating butanediol price elasticity assumptions and regional automotive cluster localization trajectories.
Feedstock price volatility, regulatory timeline acceleration, and OEM procurement consolidation are the dominant revision risks that could compress or extend modeled outcomes. Material deviation in named triggers warrants pause and re-evaluation of volume and value assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market
Elastomeric Membrane
Elastic Laminates Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Water Soluble Elastomers Market
Elastomeric Membrane
Global Thermoplastic Elastomers (TPE) Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
North America Performance Elastomer Market
Elastomeric Membrane
Hot Cast Elastomers Market
Elastomeric Membrane
Rubber Membrane Market
Elastomeric Membrane
Asia-Pacific Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Polyolefin Elastomer Market
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Ethylene Propylene Elastomers Market