
 Global Elastomeric Coating Market | 2026-2036
Global Elastomeric Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Global Elastomeric Coating Market Foresight
Modular coating systems that bundle primer, basecoat, and topcoat into specified assemblies is realigning procurement patterns across commercial construction. BASF SE leverages its integrated acrylic resin production to control raw material quality and supply security for formulated systems. Sherwin-Williams Company anchors North American distribution through its contractor-direct channel, while PPG Industries competes on specification relationships with architectural engineers.
Elastomeric coatings are highly flexible, film-forming materials typically formulated with acrylic, silicone, or polyurethane polymers that cure into rubber-like membranes capable of bridging substrate cracks while maintaining elongation properties exceeding 200 percent; they serve primarily as protective, waterproof barriers for exterior building surfaces and civil infrastructure. Acrylic formulations dominate volume in residential and light commercial roofing due to cost-performance balance and waterborne compliance, while silicone coatings command premium positioning in high-UV climates and ponding-water conditions where thermal stability and moisture resistance justify higher material costs. Polyurethane segments occupy specialized niches in below-grade waterproofing and traffic-bearing surfaces where abrasion resistance and tensile strength exceed acrylic capabilities.
EPA VOC regulations under 40 CFR Part 59 restrict solvent content in architectural coatings, compelling reformulation toward compliant waterborne systems. ECHA REACH requirements govern substance registration and hazard communication for coatings imported into European Union member states, affecting raw material sourcing and labeling obligations. Stakeholders must monitor evolving chemical restriction proposals under both frameworks to anticipate raw material substitution costs and qualification timelines.
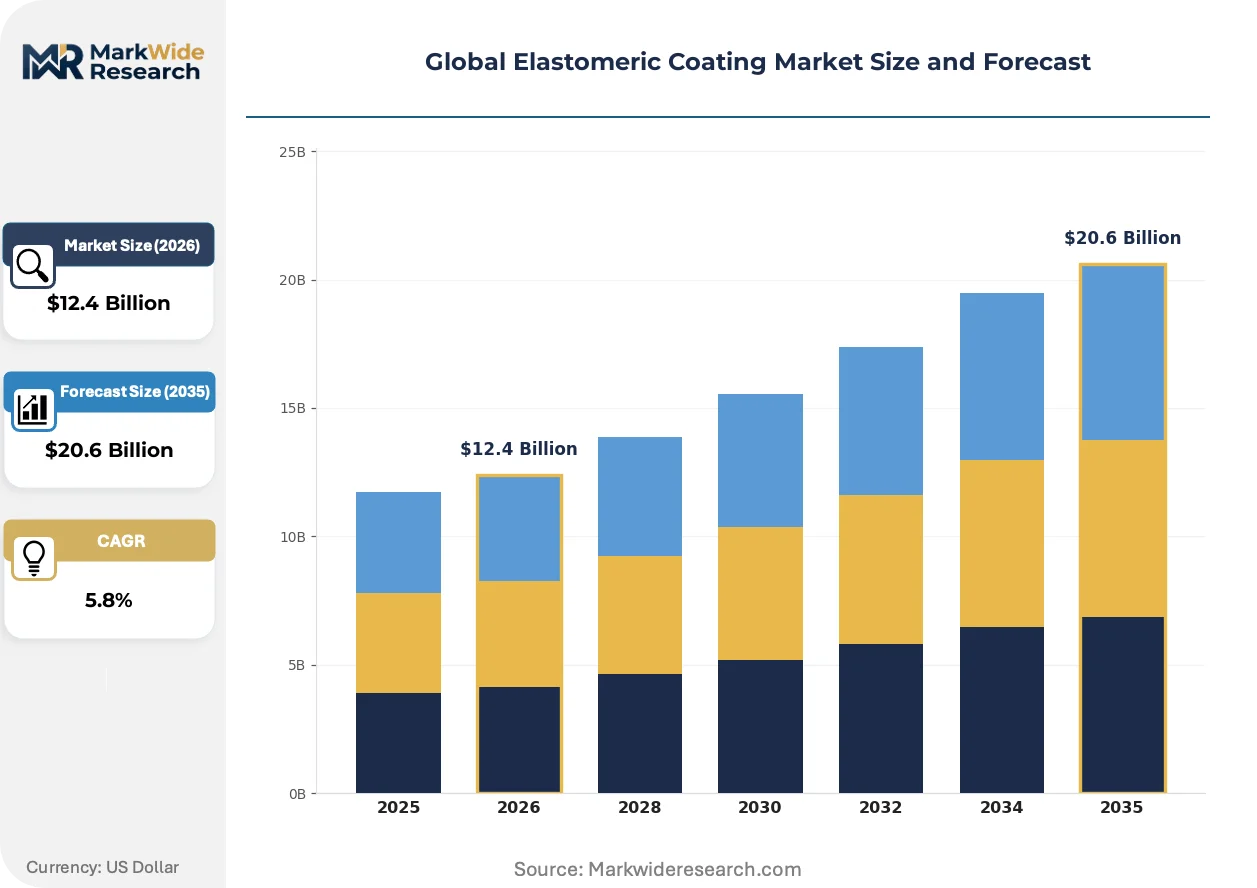
Market Dynamics
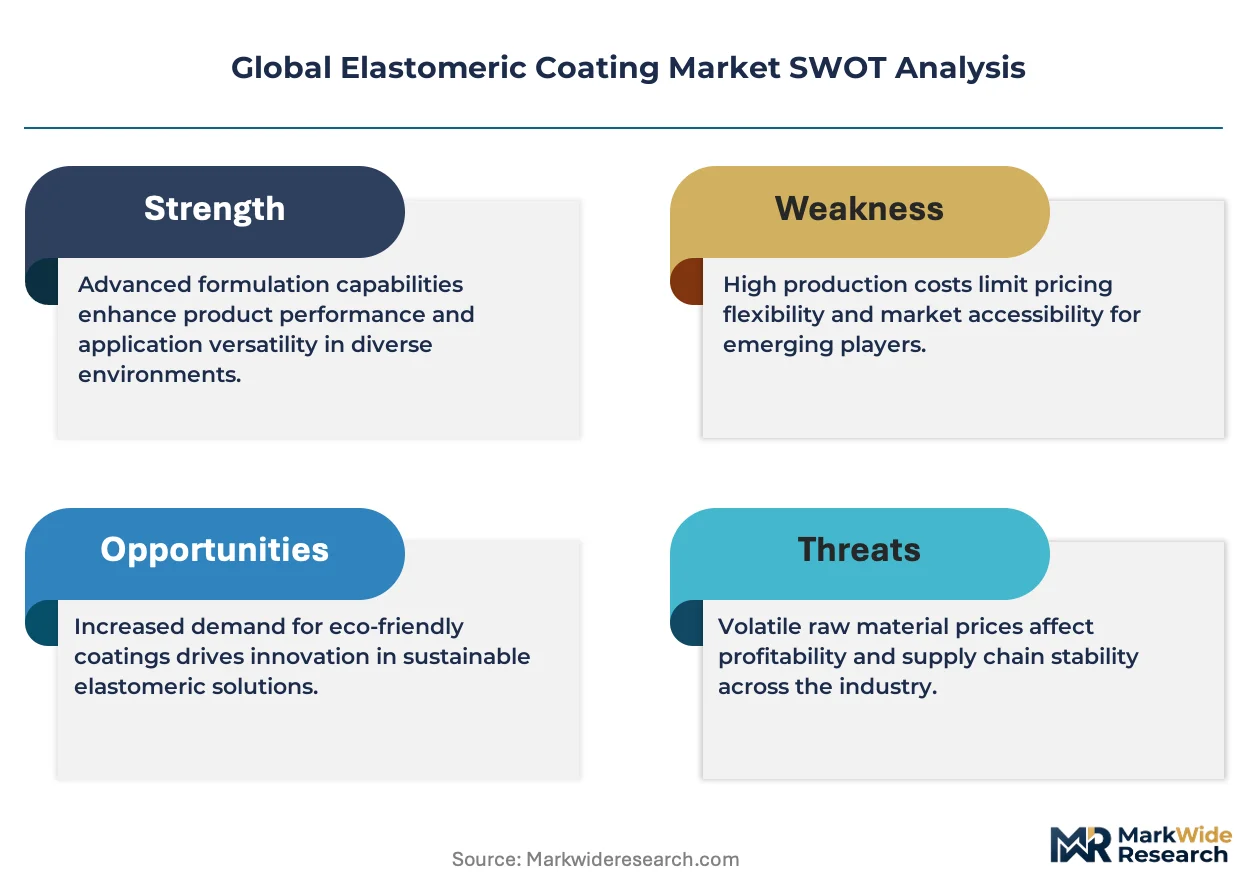
Waterborne acrylic reformulation under EPA 40 CFR Part 59 and ECHA REACH is compressing solventborne capacity while concentrating procurement among integrated resin-coating suppliers. This regulatory compression is reshaping competitive positioning toward captive raw material security and specification-engineering relationships.
Growth Catalysts
- Green building code adoption:LEED and BREEAM certification mandates in the United States, Germany, and China are accelerating specification of cool-roof elastomeric systems with solar reflectance index above 80.
- Infrastructure renewal cycles:Federal and state-level building envelope rehabilitation programs across mature economies are replacing failed single-ply membranes with fluid-applied elastomeric alternatives.
- REACH substance restrictions:ECHA proposals limiting isocyanates in polyurethane coatings are redirecting specification toward compliant silicone and hybrid acrylic-silicone chemistries for high-performance segments.
Market Restraints
- Acrylic monomer supply concentration:Butyl acrylate and methyl methacrylate production clusters in the US Gulf Coast and Northeast Asia create feedstock vulnerability for waterborne formulators.
- Application labor intensity:Elastomeric systems require skilled spray or roller application at specified mil thickness, constraining uptake in cost-driven residential reroofing segments.
- Cure-time limitations:Waterborne acrylics demand 24-48 hour cure windows with temperature above 50°F, excluding cold-climate emergency repair applications.
Strategic Opportunities
- India commercial construction penetration:Green building council adoption and cooling-energy cost pressures in Mumbai, Delhi, and Bangalore are opening specification channels for reflective roof coatings.
- Cool roof mandate expansion:California Title 24 and similar state-level energy codes are extending elastomeric cool-roof requirements from commercial to multi-family residential structures.
- Drone-assisted inspection and coating:UAV-based substrate assessment paired with robotic spray application is automating quality assurance and reducing labor dependency for large-format roofing.
Industry Challenges
- Applicator certification bottlenecks:Manufacturer-specific training programs for warranty-eligible installation are constraining contractor pool expansion in high-growth metro markets.
- Substrate compatibility testing:Legacy built-up roofing, modified bitumen, and single-ply TPO surfaces each demand distinct primer and surface preparation protocols, complicating specification standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Elastomeric Coating Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Silicone, Polyurethane, Bituminous, Fluoropolymer Application: Roofing, Fascia & Soffits, Facades, Bridges, Water Tanks End User Industry: Construction, Marine Engineering, Infrastructure Development, Commercial Complexes, Transportation Facilities Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Retail Stores, Contractors |
| Companies Covered | BASF SE, Sherwin-Williams Company, PPG Industries, The Dow Chemical Company, Nippon Paint Holdings Co., Ltd., Jotun A/S, Axalta Coating Systems, Henry Company, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Elastomeric Coating Market Shifts & Advancements
Digital specification tools and predictive substrate analytics are compressing the design-to-application cycle while elevating performance accountability. These shifts are concentrating influence among coating suppliers capable of delivering validated system warranties.
Self-healing microcapsule technology embedded in silicone elastomeric formulations is automating crack-sealing response to thermal cycling stress. Commercial roofing contractors in the southwestern United States are specifying these systems for high-UV exposure zones. The technology is compressing maintenance callback frequency and extending warranty terms from 10 to 20 years.
REACH authorization requirements for titanium dioxide nanoparticles are compelling reformulation toward alternative opacifiers in reflective roof coatings. European formulators are qualifying calcium carbonate and engineered polymer microspheres to maintain solar reflectance compliance. The regulatory friction is most acute in Germany and France, where architectural specification demands full material disclosure.
Direct-to-contractor digital platforms are disintermediating traditional distribution for specified coating systems. Large commercial roofing contractors in Texas, Florida, and California are procuring complete primer-basecoat-topcoat assemblies through manufacturer portals with embedded application training. This channel shift is most visible in the United States, where contractor consolidation has created procurement scale for direct fulfillment models.
Global Elastomeric Coating Market Segmentation
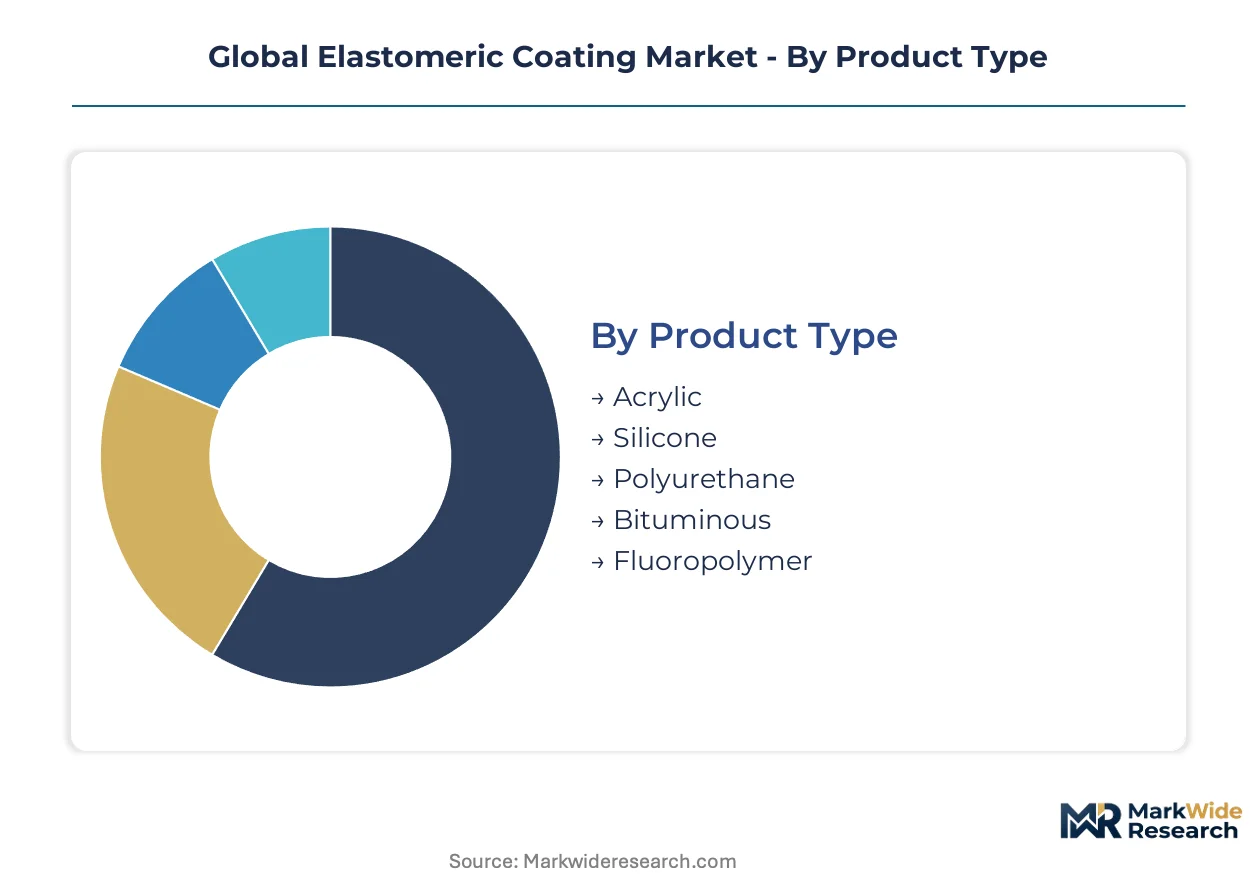
Elastomeric coating procurement splits across technical specifications, application environments, and channel economics. Each segmentation axis carries distinct compliance burdens and margin structures that reshape supplier positioning.
Product Type:
Acrylic formulations require EPA 40 CFR Part 59 compliance for architectural coatings in the United States, while silicone systems face ECHA REACH substance authorization for nanoparticle additives in European markets. Polyurethane segments trigger isocyanate exposure regulations under OSHA and equivalent occupational safety frameworks.
- Acrylic:Waterborne polymer emulsions dominate residential and light commercial roofing specifications due to cost-performance balance and VOC compliance advantages. Demand concentrates in the United States and Germany where green building codes mandate cool-roof solar reflectance above 80. Cold-climate application windows and 24-48 hour cure requirements constrain emergency repair adoption.
- Silicone:Moisture-cure and high-solid formulations command premium positioning in ponding-water and high-UV exposure zones. Specification concentrates in Florida, Texas, and Arizona where thermal stability justifies material cost premiums. Self-healing microcapsule technology is extending warranty terms from 10 to 20 years in southwestern commercial roofing.
- Polyurethane:Two-component systems with superior tensile strength and abrasion resistance serve below-grade waterproofing and traffic-bearing surfaces.
- Bituminous:Solvent-modified asphalt emulsions persist in cost-driven reroofing and damp-proofing applications.
- Fluoropolymer:PVDF and FEVE resin systems deliver maximum UV durability and chemical resistance for high-performance facade specifications.
Leading the category by volume: Acrylic. Growing fastest: Silicone.
Application:
Roofing applications demand mil-thickness certification and substrate-specific primer protocols that fragment contractor qualification requirements. Bridge and water tank segments trigger infrastructure-grade performance warranties and inspection documentation that extend sales cycles.
- Roofing:Fluid-applied membrane systems replace failed single-ply substrates in federal and state-level building envelope rehabilitation programs. Demand concentrates in California, New York, and Illinois where cool-roof mandates extend from commercial to multi-family residential structures. Drone-assisted inspection and robotic spray application are automating quality assurance for large-format commercial projects.
- Facades:Crack-bridging elastomeric finishes protect exterior insulation and finish systems from thermal cycling stress. Specification concentrates in Germany, France, and the United Kingdom where REACH disclosure requirements drive material transparency. Calcium carbonate and engineered polymer microspheres are substituting for titanium dioxide nanoparticles under authorization pressure.
- Fascia & Soffits:Horizontal and vertical trim applications require flexible adhesion to wood, fiber cement, and metal substrates.
- Bridges:Expansion joint sealing and deck waterproofing demand traffic-bearing durability and chloride resistance.
- Water Tanks:Potable water contact approvals and NSF/ANSI 61 certification constrain formulation chemistry for municipal storage.
Roofing commands the largest volume share. Facades are expanding most quickly under green building code acceleration.
End User Industry:
Construction sector procurement runs through specification-engineering relationships with architectural firms, while infrastructure development channels require public bidding compliance and performance bonding.
- Construction:General contractors and specialty roofing trades specify complete primer-basecoat-topcoat assemblies for building envelope protection. Demand concentrates in the United States, China, and Germany where infrastructure renewal and green building codes accelerate membrane replacement cycles. Direct-to-contractor digital platforms are disintermediating traditional distribution in Texas, Florida, and California.
- Infrastructure Development:Federal, state, and municipal agencies procure fluid-applied systems for bridge deck and transportation facility rehabilitation. Specification concentrates in the United Kingdom, Japan, and Australia where public asset management programs prioritize lifecycle cost over first-cost procurement.
- Commercial Complexes:Property management firms and REITs prioritize warranty-backed systems with predictive maintenance analytics.
- Marine Engineering:Offshore platforms and port facilities demand salt spray resistance and immersion-grade adhesion.
- Transportation Facilities:Airport terminals and rail stations specify rapid-cure systems to minimize operational disruption.
Construction generates the highest absolute volume. Infrastructure development shows the steepest expansion trajectory under public spending programs.
Distribution Channel:
Channel selection correlates with project scale, specification complexity, and contractor consolidation patterns across metropolitan markets.
- Direct Sales:Integrated resin-coating suppliers like BASF SE bypass distribution for large commercial roofing contractors with procurement scale. Channel concentration is highest in the United States where contractor consolidation enables manufacturer portal fulfillment with embedded application training.
- Contractors:Specification-grade systems move through certified applicator networks with warranty-eligible installation protocols. Manufacturer-specific training programs constrain contractor pool expansion in Mumbai, Delhi, and Bangalore despite green building council adoption.
- Distributors:Regional coating distributors serve mid-market commercial and residential reroofing segments with inventory availability.
- E-commerce Platforms:Standard-grade acrylic maintenance coatings and DIY repair kits reach residential consumers.
- Retail Stores:Big-box home improvement channels stock limited SKUs for consumer-grade waterproofing applications.
Direct sales and contractor channels together dominate specification-grade volume. E-commerce platforms are gaining share fastest in residential maintenance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in Texas, Florida, and California concentrate elastomeric coating demand through accelerated depreciation incentives for commercial roof rehabilitation. These zones attract property investors pursuing energy-efficient building upgrades under state-level cool-roof mandates.
United States
California Title 24 and similar state energy codes extend cool-roof requirements from commercial to multi-family residential structures. EPA 40 CFR Part 59 restricts solvent content in architectural coatings, compelling waterborne acrylic reformulation. Demand clusters in Houston, Dallas-Fort Worth, and Miami where contractor consolidation enables direct manufacturer portal procurement.
Germany
Green building council adoption and building envelope efficiency standards accelerate specification of reflective facade systems. ECHA REACH authorization requirements for titanium dioxide nanoparticles compel alternative opacifier qualification. Industrial concentration in North Rhine-Westphalia and Bavaria drives formulation innovation for exterior insulation and finish system protection.
China
Infrastructure renewal programs and dual carbon goals prioritize energy-efficient building envelope materials in commercial construction. Ministry of Ecology and Environment standards tighten VOC emissions for architectural coatings. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta supply waterborne acrylic emulsions for domestic and export markets.
India
Green building council adoption in Mumbai, Delhi, and Bangalore opens specification channels for reflective roof coatings amid cooling-energy cost pressures. Bureau of Indian Standards certification requirements govern coating performance for government infrastructure projects. Applicator certification bottlenecks constrain contractor pool expansion despite accelerating commercial construction penetration.
United Arab Emirates
Solar reflectance requirements for building envelopes in Dubai and Abu Dhabi drive specification of high-performance elastomeric systems. MOHAP and municipal regulations govern material safety and environmental compliance for imported coating systems. Mega-project development in NEOM and existing urban core rehabilitation sustain demand for weather-resistant membrane technologies.
Global Elastomeric Coating Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation and distribution vectors. Integrated resin-coating suppliers control captive raw material security while independent formulators rely on external polymer emulsion sourcing. Three archetypes dominate: integrated chemical conglomerates with backward acrylic resin production, specification-grade coating specialists with contractor-direct channels, and regional formulators serving cost-driven maintenance segments. Competitive moves concentrate on M&A for resin capacity control and strategic partnerships for specification-engineering relationships.
Among integrated chemical conglomerates, BASF SE anchors the captive supply archetype through in-house acrylic resin production. Sherwin-Williams Company and PPG Industries occupy positions within the specification-grade tier, with the former exemplifying contractor-direct distribution models and the latter representing architectural engineer relationship strategies. These three entities illustrate the competitive tension between raw material security and channel control.
| Leading Market Players |
|---|
| BASF SE |
| Sherwin-Williams Company |
| PPG Industries |
| The Dow Chemical Company |
| Nippon Paint Holdings Co., Ltd. |
| Jotun A/S |
| Axalta Coating Systems |
| Henry Company |
| Akzo Nobel N.V. |
| Others |
Supply & Pricing Matrix
Consolidated commercial roofing contractors in Texas, Florida, and California command project-based pricing with volume-scale discounts, while fragmented residential applicators face spot-market acrylic pricing with 24-48 hour lead-time premiums. This buyer-concentration asymmetry rewards integrated suppliers with captive resin production and direct portal fulfillment capabilities.
Pricing Analysis
Short lead-time premiums apply to emergency repair specifications where cold-climate cure windows exclude standard waterborne acrylics. Three-tier pricing structure across premium silicone, standard acrylic, and economy bituminous levels tracks certification grade and warranty term differentiation. Price compression runs through residential reroofing segments as big-box retailers push private-label maintenance coatings. Infrastructure procurement offices show lowest price sensitivity due to lifecycle-cost mandates and performance bonding requirements.
Supply Chain Analysis
Regional distribution centers in Houston, Dallas-Fort Worth, and Miami anchor hub-and-spoke fulfillment for contractor-direct channels. Acrylic monomer production clusters in the United States Gulf Coast and Northeast Asia feed waterborne formulation plants. Butyl acrylate and methyl methacrylate dependencies create single-source vulnerability during petrochemical turnaround seasons. Distribution runs through manufacturer portals with embedded application training for large commercial contractors, while regional distributors serve mid-market inventory requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Elastomeric Coating Market functions as a vertical-integration race where captive acrylic resin production determines margin sustainability. Players are pursuing backward integration into polymer emulsion supply to secure formulation cost control against feedstock volatility.
For Market Incumbents: Cement specification-engineering relationships with architectural firms through validated system warranties and predictive substrate analytics. Deepen captive resin capacity in the United States Gulf Coast and Yangtze River Delta manufacturing clusters. Defend against drone-assisted application disruptors by embedding UAV inspection protocols into contractor certification programs.
For New Entrants and Emerging Players: Launch via direct-to-contractor digital platforms targeting mid-market commercial roofing contractors in India and the United Arab Emirates. Penetrate green building council adoption corridors in Mumbai, Delhi, and Bangalore where applicator certification bottlenecks constrain incumbent expansion. Position hybrid acrylic-silicone chemistries as REACH-compliant alternatives for European facade specifications facing titanium dioxide nanoparticle restrictions.
For Investors and Strategic Acquirers: The window for entry favors integrated resin-coating suppliers with captive acrylic emulsion production and established specification relationships. Long-term viability hinges on control over waterborne polymer supply chains as EPA and ECHA solvent restrictions tighten. Watch ECHA authorization timelines for isocyanate limitations as the signal for polyurethane segment restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Resin Production | BASF SE exemplifies margin control through captive butyl acrylate supply security. |
| Drone-Assisted Inspection and Application Partnership | Commercial roofing contractors in Texas and Florida automate quality assurance at scale. |
| REACH-Compliant Silicone Formulation Investment | European formulators qualify calcium carbonate opacifiers to replace titanium dioxide nanoparticles. |
| Direct-to-Contractor Digital Platform Launch | Manufacturer portals disintermediate distribution for consolidated contractor procurement in California. |
| Self-Healing Microcapsule Technology Licensing | Southwestern United States commercial roofing extends warranty terms from 10 to 20 years. |
Research Methodology
Multi-period observation of acrylic monomer pricing spreads, contractor certification expansion rates, and cool-roof mandate adoption anchored the trend analysis, supplemented by interviews with formulation chemists at integrated resin suppliers, commercial roofing contractor operations managers, architectural specification engineers, and EPA regional compliance officers. Secondary validation drew from EPA 40 CFR Part 59 regulatory filings, ECHA REACH substance authorization databases, customs trade data for acrylic emulsion imports, and green building council certification registries. Bottom-up volume modeling triangulated against top-down construction spending allocation estimates.
Input-output matrices mapped polymer emulsion supply through formulation capacity to end-use application demand across the projection horizon. Segmentation dimensions included chemistry type, substrate application, end-user industry vertical, and distribution channel structure. CAGRs derived from elasticity-adjusted demand curves incorporating regulatory compliance cost pass-through and substitution effects between silicone and hybrid acrylic-silicone systems.
Feedstock price volatility, ECHA substance restriction timelines, and applicator certification bottlenecks are the dominant revision risks for forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Rubber Membrane Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market
Elastomeric Membrane
Modified Silicone Fluids Market
Elastomeric Membrane
Europe Single-Ply Membrane Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
Global Flexible Elastomeric Foam Market
Elastomeric Membrane
North America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Hot Cast Elastomers Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
Elastomeric Membrane Market