
 Chlorinated Polyethylene Resins and Elastomers (CPE) Market | 2026-2036
Chlorinated Polyethylene Resins and Elastomers (CPE) Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorinated Polyethylene Resins and Elastomers (CPE) Market Outlook
Polyvinyl chloride is broadening its addressable use cases as chlorinated polyethylene displaces conventional impact modifiers and flexible PVC in weather-resistant applications. Dow Chemical Company leverages its integrated chlor-alkali and polyethylene assets to sustain cost-competitive CPE supply across North American wire and cable markets. Shandong Novista Chemicals Co. Ltd anchors its position through deep specialization in chlorinated polymer grades tailored to Chinese construction standards. LG Chem Ltd competes on technology leadership in high-performance elastomer formulations for automotive hose and tubing specifications.
Chlorinated polyethylene resins and elastomers comprise thermoplastic materials produced by chlorinating high-density polyethylene to chlorine contents typically ranging from 25% to 40% by weight, yielding products with rubber-like elasticity combined with polyolefin processability. Manufacturers employ aqueous suspension or solution chlorination processes to control chlorine distribution and molecular architecture for target applications in impact modification, flexible sheeting, and extruded profiles. High-performance CPE commands premium positioning in automotive fuel hose and industrial conveyor belt applications where oil resistance and thermal stability justify elevated pricing. Medium-density CPE occupies the volume core of construction membranes and geomembrane liners where balanced flexibility and tensile strength meet specification requirements at moderate cost.
EPA regulations under the Toxic Substances Control Act govern chlorinated polymer manufacturing emissions and waste handling practices in the United States, while REACH registration obligations in Europe impose substance evaluation and restriction protocols on CPE importers and compounders. China's MEE enforces chlorinated organic emissions standards at Shandong and Jiangsu production hubs where the majority of domestic capacity operates. Stakeholders must monitor evolving halogenated polymer restrictions under EU Green Deal chemical sustainability strategies and assess backward integration into captive polyethylene feedstock as margin protection against ethylene cost volatility.
Market Dynamics
Grid modernization across utility infrastructure is redirecting specification demand toward halogenated elastomer alternatives as legacy plasticizers face phasedown pressures. Chlorinated polyethylene resin producers must balance chlorine content precision against tightening emissions protocols at integrated chlor-alkali sites.
Growth Catalysts
- Wire and cable jacketing specifications:Utilities in the United States and China are specifying CPE for medium-voltage distribution cables requiring weather resistance and flame retardancy. Jacketing compound volumes track directly with transmission infrastructure replacement cycles.
- REACH plasticizer restrictions:ECHA's progressive limitation of phthalate-based additives in European flexible PVC compounds redirects formulation demand toward halogenated elastomer alternatives. Compounders reformulate construction membranes and geomembranes to maintain elasticity compliance.
- Shandong-Jiangsu production clustering:Domestic chlorination capacity concentration alongside PVC compounding hubs in eastern China creates integrated feedstock-to-compound supply advantages. Local producers capture margin through captive polyethylene sourcing and shared logistics infrastructure.
Market Restraints
- Ethylene feedstock volatility:CPE manufacturing margins compress when naphtha-cracker ethylene prices spike, as chlorination costs represent a fixed proportion of total production expense. Producers without backward integration into polyethylene supply face asymmetric margin pressure.
- Chinese supply concentration:Over sixty percent of global chlorinated polyethylene capacity operates within Shandong and Jiangsu provinces, creating geographic risk exposure to regional environmental enforcement actions or energy rationing protocols.
- Thermoplastic polyurethane substitution:TPU compounds with comparable oil resistance and superior abrasion performance capture specification share in automotive fuel hose and industrial conveyor belt segments where premium CPE historically dominated.
Strategic Opportunities
- Indian infrastructure buildout:Central Electricity Authority transmission expansion targets and National Highway Authority waterproofing mandates create specification entry points for impact-modified PVC compounds. Domestic compounding capacity gaps necessitate resin import partnerships.
- Recyclable mono-material construction films:CPE's compatibility with polyethylene recycling streams enables closed-loop geomembrane and agricultural film formulations. Sustainability-driven procurement criteria in German and Dutch civil engineering projects favor halogenated elastomer solutions over multi-layer alternatives.
- Automotive lightweighting convergence:Integration of CPE with thermoplastic olefin blends for under-hood hose and tubing applications addresses mass reduction targets. OEM material approval timelines present first-mover positioning windows for compounders with established fuel permeation test data.
Industry Challenges
- Chlorination process engineering expertise:Aqueous suspension chlorination requires precise control of chlorine distribution and molecular weight degradation. Qualified technical personnel scarcity constrains capacity expansion at mid-scale producers attempting process technology transfers.
- Automotive OEM qualification timelines:Fuel hose and coolant tubing specifications require eighteen-to-thirty-six-month validation cycles including permeation, burst pressure, and thermal aging protocols. Compounders absorb working capital burdens during specification pursuit with uncertain conversion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorinated Polyethylene Resins and Elastomers (CPE) Market |
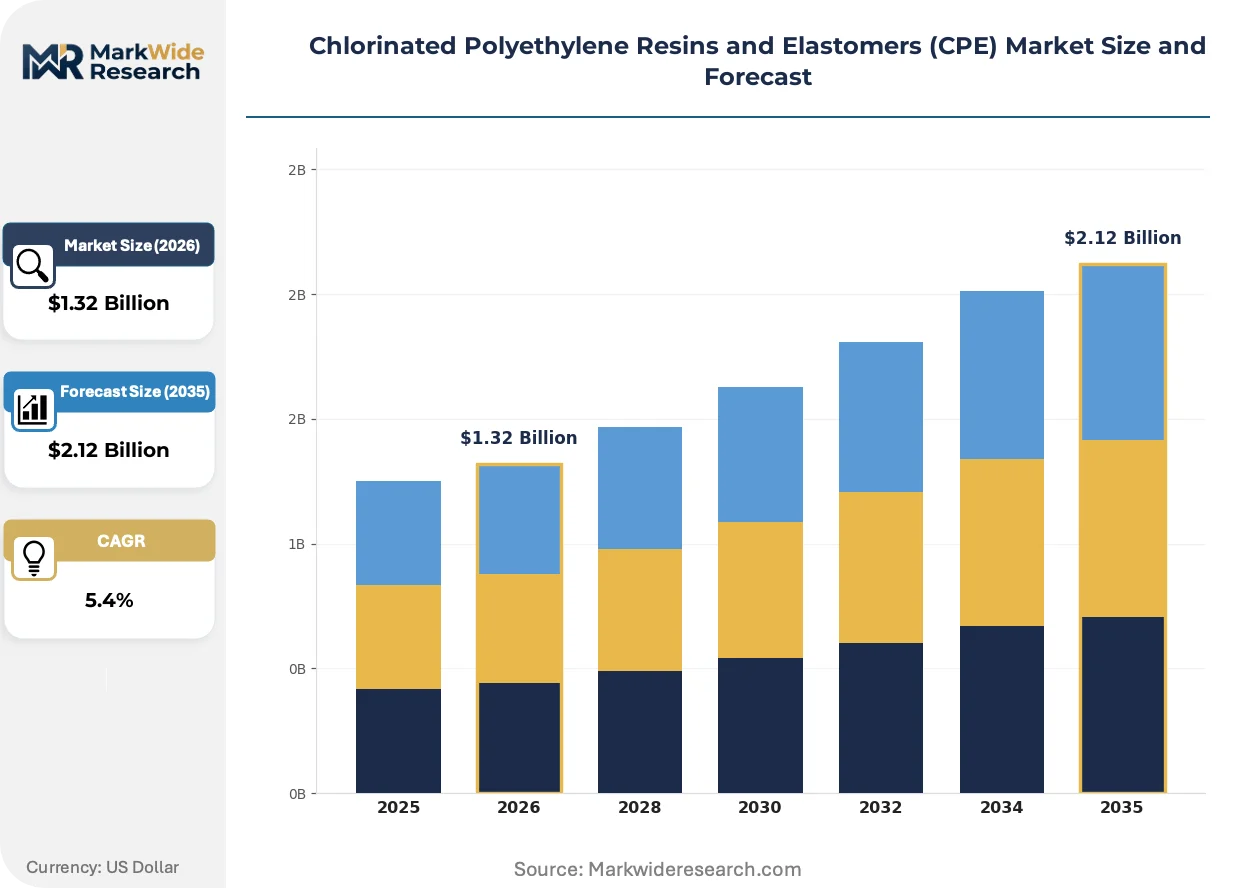
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.12 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Performance CPE, Low-Density CPE, Medium-Density CPE, Specialty CPE Application: Adhesives, Coatings, Sealants, Automotive Parts End Use Industry: Construction, Automotive, Electrical, Consumer Goods Form: Granules, Powder, Pellets, Films |
| Companies Covered | LG Chem Ltd, Jiangsu Tianteng Chemical Industry Co. Ltd, Dow Chemical Company, Hangzhou Keli Chemical Co. Ltd, Weifang Yaxing Chemical Co. Ltd, Sundow Polymers Co. Ltd, Shandong Gaoxin Chemical Co. Ltd, Shandong Novista Chemicals Co. Ltd, Lianda Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorinated Polyethylene Resins and Elastomers (CPE) Market Strategic Shifts
Process intensification and regulatory chemistry are compressing traditional specification boundaries between commodity impact modifiers and performance elastomers. Chlorinated polyethylene compounders must now engineer for circularity credentials alongside mechanical performance.
Aqueous suspension chlorination technology is decentralizing production economics by enabling smaller-scale reactors with precise chlorine distribution control. Regional compounders in the United States and Germany are adopting modular chlorination units to produce niche CPE grades for automotive and wire specifications without integrated chlor-alkali assets. This technology is decentralizing supply concentration away from coastal Chinese mega-sites toward demand-proximate manufacturing.
EU Green Deal chemical sustainability strategies are accelerating substance evaluation protocols for halogenated polymers under REACH authorization review. ECHA's systematic assessment of persistent organic pollutant characteristics threatens long-term CPE import permissions for European compounders. Construction membrane and geomembrane segments are responding by accelerating alternative formulation qualification and engaging in industry consortium defense of chlorinated polymer safety profiles.
Specification-driven procurement is compressing traditional distributor roles as wire and cable OEMs engage resin producers directly for compound customization. Technical service agreements now bundle formulation development with volume commitments, displacing spot-market resin purchases. This pattern is most visible in German automotive supplier networks and Chinese state-grid cable procurement where approved vendor lists consolidate around integrated compounders with in-house chlorination capability.
Chlorinated Polyethylene Resins and Elastomers (CPE) Market Segmentation
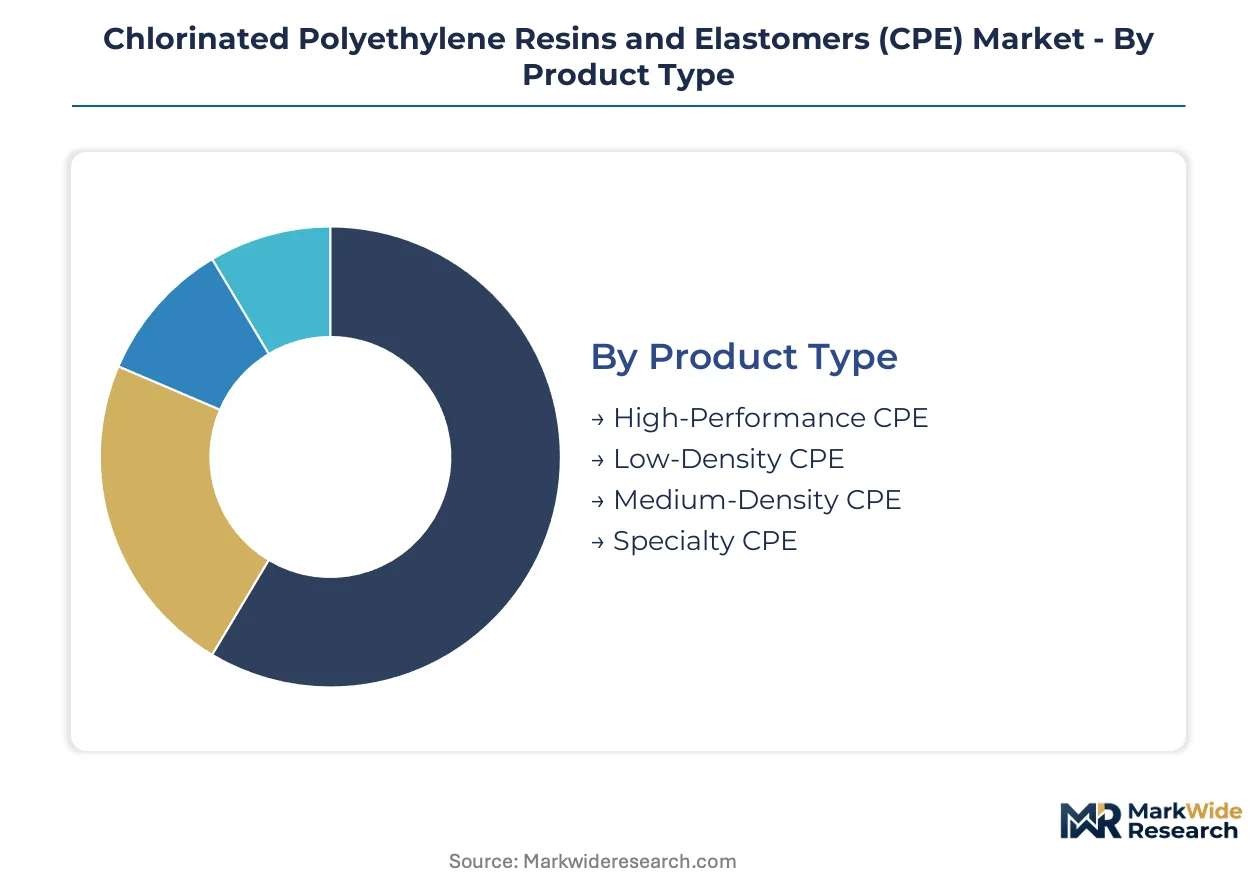
Chlorinated polyethylene formulations diverge sharply across chlorine content and density grades, with specification requirements in wire jacketing and automotive hoses driving premium tier development. Compounders must align product portfolios with end-use certification standards that vary by geography and application severity.
Product Type:
Chlorination capacity concentration in Shandong and Jiangsu provinces shapes global availability of differentiated density grades, with captive polyethylene feedstock determining cost competitiveness across performance tiers.
- High-Performance CPE:Chlorine content exceeding 35% by weight delivers enhanced oil resistance and thermal stability for fuel hose and industrial conveyor specifications. Demand concentrates in German automotive supplier networks where OEM validation cycles favor established compounders with permeation test data archives.
- Medium-Density CPE:Balanced elasticity and tensile strength at 30-35% chlorine content serves construction membrane and geomembrane volume requirements. Chinese state-grid cable procurement specifications absorb the majority of global medium-density output from integrated Shandong producers.
- Low-Density CPE:Impact modification of rigid PVC profiles for window and fencing applications at 25-30% chlorine levels.
- Specialty CPE:Custom molecular architectures for adhesive and sealant formulations requiring specific solubility parameters.
Today's leader: Medium-Density CPE. Tomorrow's challenger: High-Performance CPE.
Application:
Specification intensity varies by application, with automotive and electrical segments demanding compound customization that fragments procurement patterns away from spot-market resin purchases.
- Automotive Parts:Under-hood hose and tubing formulations integrate CPE with thermoplastic olefin blends to address mass reduction targets. OEM approval timelines in the United States and Germany extend eighteen-to-thirty-six months, consolidating supply around compounders with established fuel permeation databases.
- Coatings:Solution-grade CPE resins provide corrosion protection for industrial equipment and marine structures. Demand from Indian infrastructure buildout and National Highway Authority waterproofing mandates is climbing the fastest among application segments.
- Adhesives:Solvent-based systems for flexible packaging lamination and construction panel bonding.
- Sealants:Caulk and gasket compounds requiring weather resistance in building envelope applications.
Automotive Parts commands specification premiums. Coatings is gaining share fastest through infrastructure expansion.
End Use Industry:
Industry verticals impose distinct certification barriers, with electrical and automotive sectors maintaining approved vendor lists that favor backward-integrated compounders.
- Electrical:Wire and cable jacketing specifications for medium-voltage distribution require flame retardancy and weather resistance. Utilities in the United States and China are redirecting demand toward halogenated elastomer alternatives as legacy plasticizers face phasedown pressures under REACH restrictions.
- Construction:Geomembrane liners and waterproofing membranes specify medium-density grades with balanced mechanical properties. German and Dutch civil engineering procurement criteria increasingly favor recyclable mono-material CPE formulations over multi-layer alternatives.
- Automotive:Fuel system components and coolant tubing represent the highest specification intensity vertical.
- Consumer Goods:Flexible sheeting and molded articles for household and recreational products.
Electrical leads volume absorption. Construction offers the steepest expansion trajectory through sustainability-driven specification shifts.
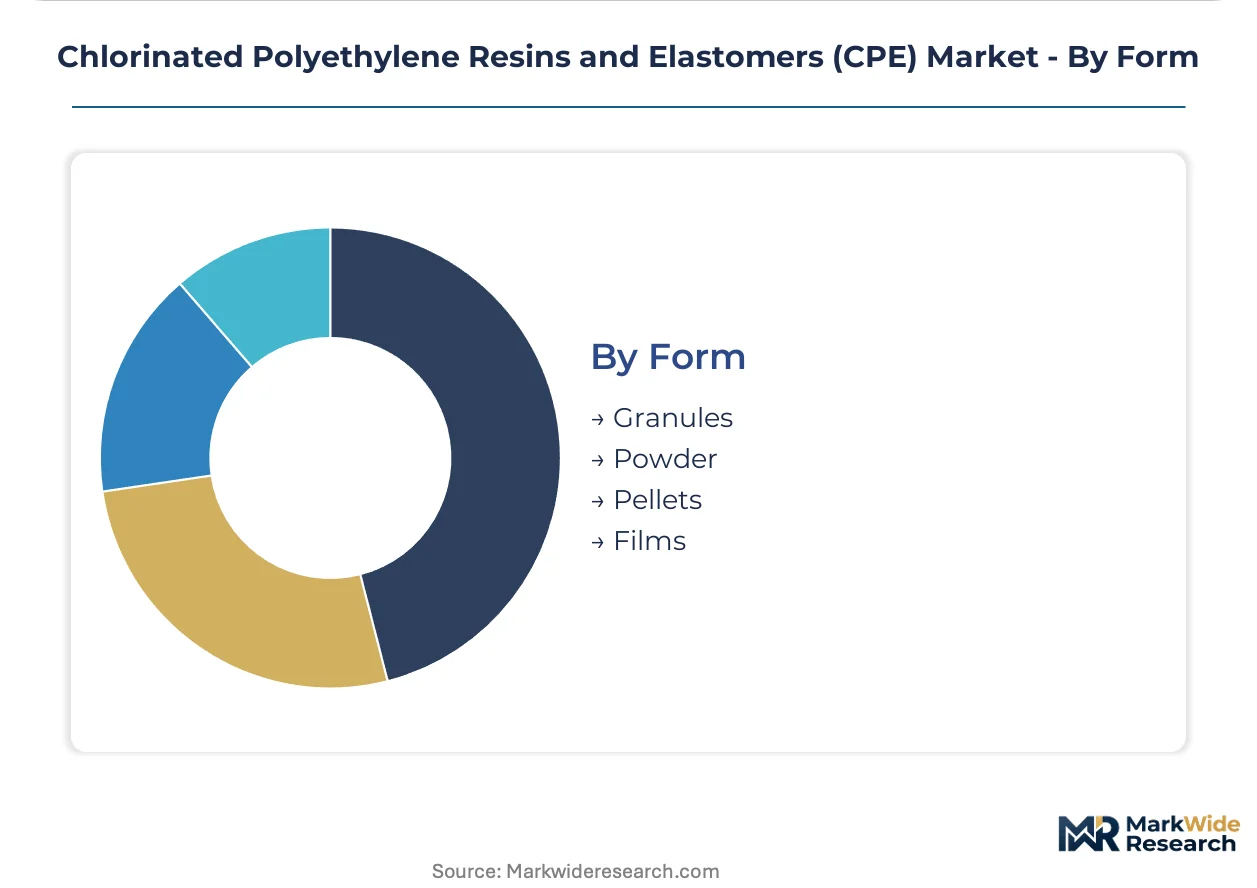
Form:
Physical form selection determines processing economics across extrusion, calendering, and solution application methods, with granule and pellet formats dominating automated compounding operations.
- Granules:Free-flowing particulate form optimized for high-throughput extrusion of wire jacketing and profile applications. Chinese PVC compounding clusters in Shandong and Jiangsu prefer granule delivery for integrated resin-to-compound operations.
- Pellets:Uniform cylindrical form factors enable precise feeding in automotive hose extrusion lines. German and United States compounders specify pelletized grades for tight dimensional tolerance requirements in fuel system components.
- Powder:Fine particle size for solution coating and adhesive formulations requiring rapid dissolution.
- Films:Pre-formed sheet stock for membrane lamination and specialty packaging applications.
Granules dominates current procurement volumes. Pellets is advancing through automotive specification tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong-Jiangsu production clustering commands global chlorinated polyethylene supply, with integrated chlor-alkali and PVC compounding infrastructure concentrating capacity in eastern China. Utility grid modernization and construction membrane specifications drive demand dispersion across North America, Europe, and South Asia.
United States
Medium-voltage distribution cable jacketing specifications from utilities redirect formulation demand toward halogenated elastomer alternatives. EPA regulations under the Toxic Substances Control Act govern manufacturing emissions and waste handling practices at chlorinated polymer production sites. Wire and cable OEMs in the Southeast and Midwest engage resin producers directly for compound customization, displacing traditional distributor roles.
China
State-grid cable procurement and construction waterproofing mandates absorb the majority of global medium-density CPE output. MEE enforces chlorinated organic emissions standards at production hubs where captive polyethylene feedstock creates integrated supply advantages. Shandong and Jiangsu provinces host over sixty percent of global chlorination capacity alongside PVC compounding clusters.
Germany
Automotive fuel hose and coolant tubing specifications require eighteen-to-thirty-six-month validation cycles including permeation and thermal aging protocols. REACH authorization review under EU Green Deal chemical sustainability strategies threatens long-term CPE import permissions for European compounders. German automotive supplier networks consolidate approved vendor lists around integrated compounders with in-house chlorination capability.
India
Central Electricity Authority transmission expansion targets and National Highway Authority waterproofing mandates create specification entry points for impact-modified PVC compounds. BIS certification requirements and DGFT import regulations shape resin partnership structures for domestic compounders. Domestic compounding capacity gaps in Maharashtra and Gujarat necessitate resin import partnerships from Chinese and South Korean producers.
Chlorinated Polyethylene Resins and Elastomers (CPE) Market Competitive Environment
Backward integration into captive polyethylene feedstock dominates the current landscape as margin protection against ethylene cost volatility. The vendor base concentrates around integrated chlor-alkali operators and specialized chlorinated polymer compounders, with mid-scale producers constrained by process engineering expertise scarcity. Three archetypes define competitive positioning: petrochemical majors with integrated polyethylene assets, regional specialists with deep chlorination technology mastery, and automotive-focused compounders with established OEM validation archives. Capacity expansion in modular aqueous suspension units and strategic partnerships for Indian market entry represent the dominant competitive moves.
Among integrated petrochemical operators, Dow Chemical Company exemplifies the archetype of chlor-alkali and polyethylene asset leverage for cost-competitive supply. Shandong Novista Chemicals Co. Ltd and Jiangsu Tianteng Chemical Industry Co. Ltd represent the regional specialist tier with production concentration in eastern China's chlorination corridor. LG Chem Ltd occupies a position exemplifying technology leadership in high-performance elastomer formulations.
| Leading Market Players |
|---|
| LG Chem Ltd |
| Jiangsu Tianteng Chemical Industry Co. Ltd |
| Dow Chemical Company |
| Hangzhou Keli Chemical Co. Ltd |
| Weifang Yaxing Chemical Co. Ltd |
| Sundow Polymers Co. Ltd |
| Shandong Gaoxin Chemical Co. Ltd |
| Shandong Novista Chemicals Co. Ltd |
| Lianda Corporation |
| Others |
Value Chain & Pricing Dynamics
Ethylene feedstock index movements cascade through chlorinated polyethylene manufacturing economics, compressing margins at non-integrated compounders while captive polyethylene producers in Shandong and Jiangsu maintain pricing power through backward integration into chlor-alkali assets. This cost pass-through dynamic stratifies the vendor base across three performance tiers tied to chlorine precision and certification depth.
Pricing Analysis
Input-cost pass-through from naphtha-cracker ethylene volatility governs CPE pricing dynamics, with integrated producers absorbing spikes better than merchant resin buyers. Three-tier pricing structure across premium, standard, and economy levels separates high-performance automotive grades with OEM validation archives from construction membrane volumes and commodity impact modifier tiers. Pricing pressure stems from thermoplastic polyurethane substitution in fuel hose specifications, eroding premium positioning. Construction compounders exhibit highest price sensitivity due to specification fungibility, while automotive Tier 1 suppliers tolerate premiums for validated permeation data.
Supply Chain Analysis
Reverse-logistics flows for geomembrane and agricultural film recovery are emerging as CPE's polyethylene recycling compatibility enables closed-loop collection programs in German and Dutch civil engineering procurement. Manufacturing concentrates in China, South Korea, and the United States, with Shandong-Jiangsu corridor hosting over sixty percent of global chlorination capacity. Feedstock dependencies center on high-density polyethylene resin, chlorine gas from chlor-alkali operations, and suspension-grade process chemicals. Single-source vulnerability runs through Shandong environmental enforcement actions that trigger regional production halts. Distribution runs through direct technical service agreements with wire and cable OEMs, displacing traditional distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
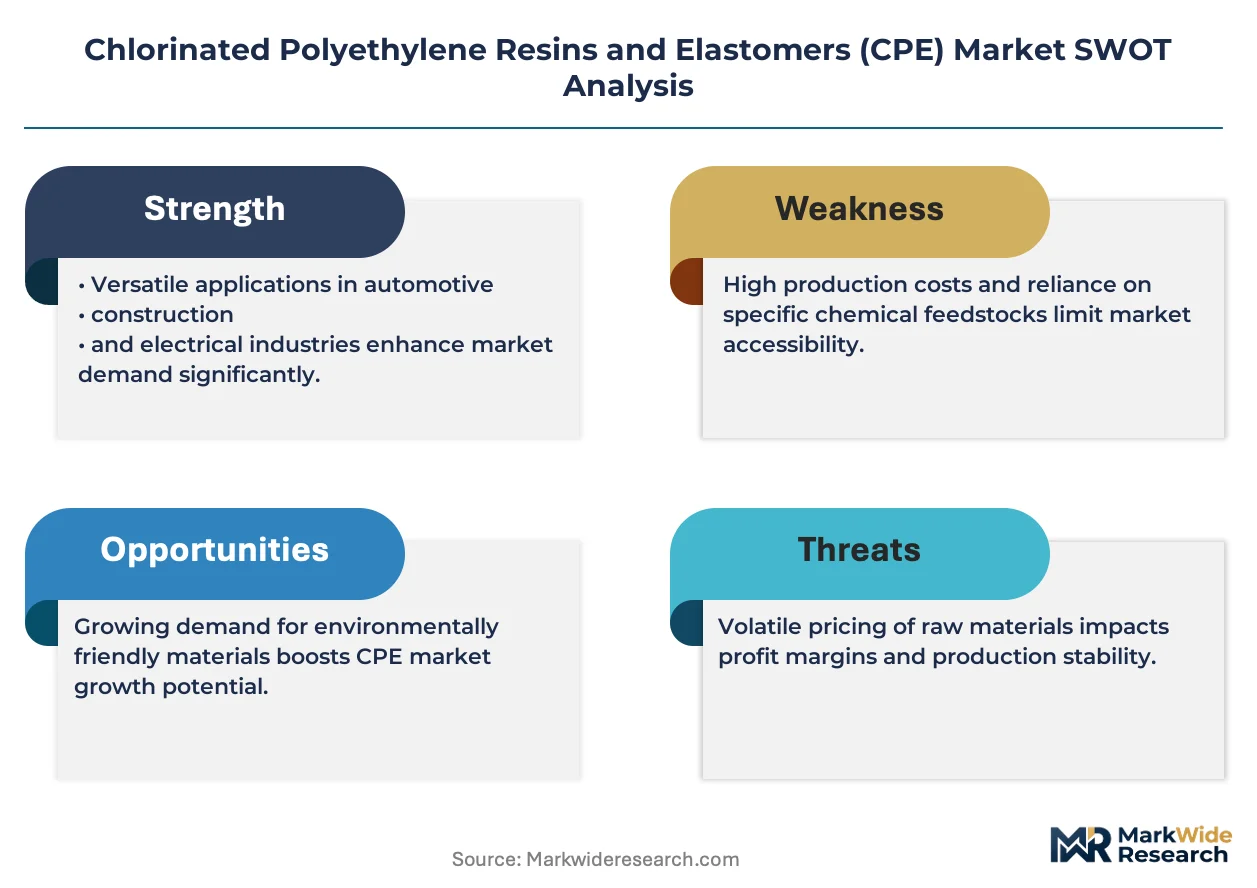
This market functions as a regulatory compounder where REACH plasticizer restrictions and EPA emissions protocols redirect formulation demand toward halogenated elastomer alternatives, creating specification windows for integrated producers with validation data archives.
For Market Incumbents: To counter thermoplastic polyurethane substitution in automotive fuel hose segments, deepen captive polyethylene sourcing through chlor-alkali integration and accelerate permeation test data accumulation for eighteen-to-thirty-six-month OEM qualification cycles. Prioritize certification investment for EU Green Deal chemical sustainability compliance to defend European import permissions against ECHA authorization review threats. For New Entrants and Emerging Players: E-commerce platforms for specialty CPE grades offer direct access to Indian infrastructure compounders lacking domestic chlorination capacity. Target Maharashtra and Gujarat compounding gaps through resin import partnerships with technical service bundling, leveraging BIS certification navigation as the primary go-to-market wedge against established distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale producers lack aqueous suspension chlorination engineering expertise to execute process technology transfers. Five-to-ten-year viability favors integrated compounders with in-house chlorination and established OEM validation archives. Acquisition targets should display captive polyethylene feedstock or modular reactor technology for demand-proximate manufacturing. Monitor ECHA halogenated polymer authorization timelines as the critical inflection signal for European market access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Polyethylene | Shandong producers neutralize ethylene volatility through integrated chlor-alkali assets. |
| Modular Aqueous Suspension Capacity | Regional compounders in Germany and the United States decentralize supply from Chinese mega-sites. |
| Automotive OEM Validation Investment | Eighteen-to-thirty-six-month fuel permeation protocols lock in specification premiums. |
| Indian Market Entry Partnership | Central Electricity Authority transmission targets create resin import demand for integrated compounders. |
| Recyclable Mono-Material Formulation | German civil engineering procurement criteria favor CPE geomembranes over multi-layer alternatives. |
Study Parameters
Bottom-up wire and cable jacketing modeling reconciled against top-down chlorination capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Shandong and Jiangsu production facilities, procurement leads at automotive Tier 1 suppliers, technical R&D directors at German compounders, and distribution channel partners in Maharashtra and Gujarat were validated against secondary sources including customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated petrochemical operators, and EPA emissions disclosures under the Toxic Substances Control Act.
Historical trendline analysis of transmission infrastructure replacement cycles and construction membrane procurement patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include chlorine content grade, end-use industry vertical, physical form factor, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand curves incorporating specification substitution rates and regulatory phase-in timelines. Industry-specific forecast inputs encompassed state-grid cable procurement volumes from China and REACH restriction implementation schedules from ECHA.
Ethylene feedstock price spikes, ECHA authorization review outcomes, and Shandong environmental enforcement actions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about OEM qualification conversion rates and infrastructure spending continuity. Practitioners should monitor chlor-alkali operating rates and EU Green Deal chemical sustainability strategy publications for early signals of supply and demand restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Rubber Membrane Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
Modified Silicone Fluids Market
Elastomeric Membrane
Elastic Laminates Market
Elastomeric Membrane
Elastomeric Polyolefins Market
Elastomeric Membrane
Stretchable Conductive Material Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
Global Elastomeric Foam Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Europe Single-Ply Membrane Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
Middle-East and Africa Fluoroelastomers Market
Elastomeric Membrane
High Temperature Elastomers Market
Elastomeric Membrane
Polyisoprene Elastomers Market