
 North America Polyisoprene Market | 2026-2036
North America Polyisoprene Market Size, Share, and Industry Trends Forecast 2026-2036
North America Polyisoprene Market Intelligence
U.S. synthetic rubber producers is consolidating around larger monomer-to-polymer operations. JSR Corporation leverages its advanced solution polymerization technology to serve medical-grade specifications. ExxonMobil Chemical anchors its position through backward integration into isoprene feedstock and captive catalyst production. Kraton Corporation differentiates via specialized styrenic block copolymer adjacencies that complement core polyisoprene grades.
Polyisoprene is a synthetic or naturally derived elastomer composed primarily of cis-1,4-polyisoprene repeating units, exhibiting high resilience, low hysteresis, and tensile strengths typically ranging from 17 to 24 MPa in vulcanized form. Manufacturers produce it via Ziegler-Natta or anionic polymerization of isoprene monomer for applications requiring latex-like elasticity without allergenic proteins. The medical devices application leads absolute volume due to stringent healthcare material requirements, while liquid polyisoprene represents the fastest-expanding product type as formulators adopt low-viscosity grades for precision molding and adhesive formulations. Solid synthetic grades retain mature, high-volume positions in tire component and industrial belting markets where cost efficiency dominates procurement criteria.
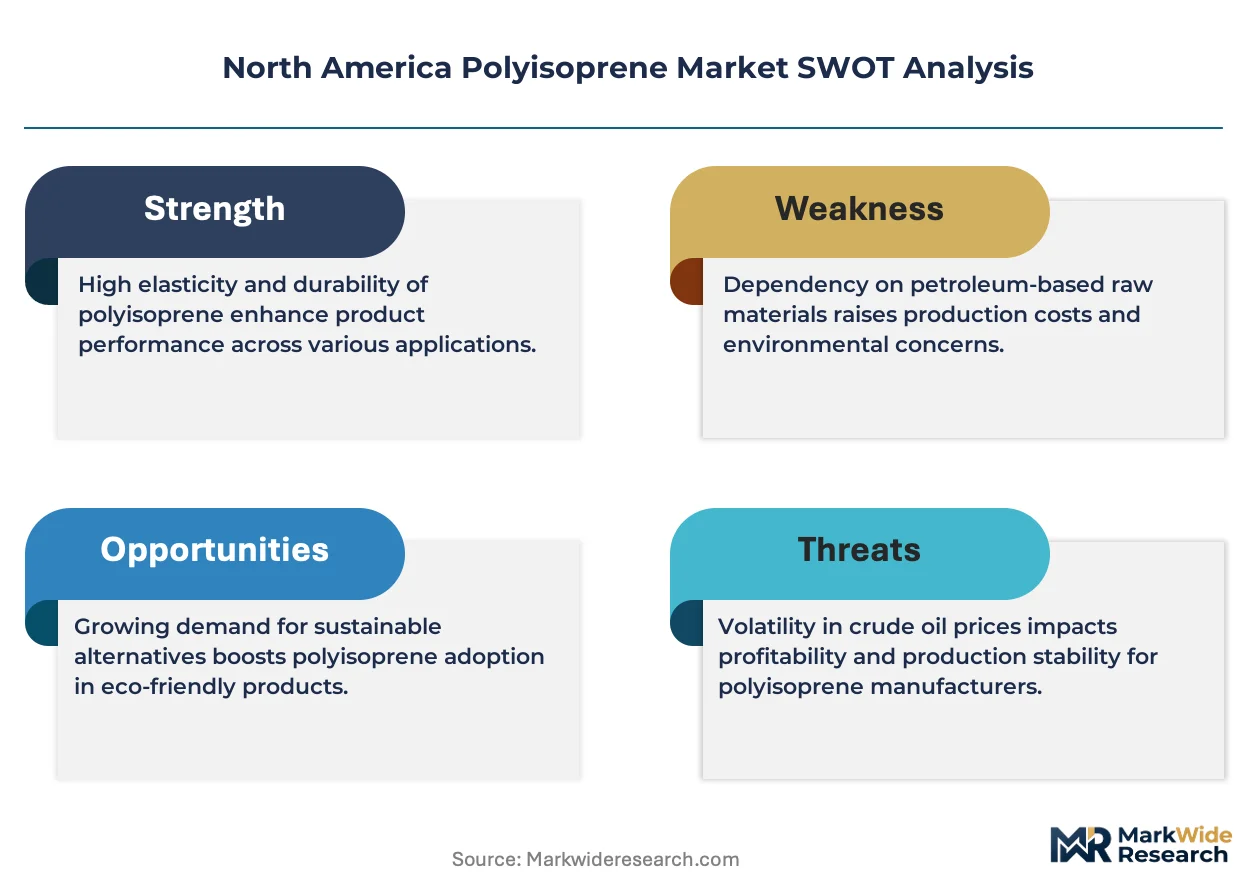
The U.S. FDA regulates polyisoprene in medical applications through biocompatibility standards under ISO 10993, while EPA oversight of isoprene monomer emissions affects plant permitting and operating costs. OSHA workplace exposure limits for isoprene influence plant automation investments and personnel safety protocols. Stakeholders must monitor evolving state-level chemical disclosure laws and healthcare procurement sustainability mandates that increasingly factor into supplier selection beyond unit economics.
Market Dynamics
Medical device manufacturers are consolidating supplier relationships around FDA-registered polyisoprene producers capable of ISO 10993 biocompatibility documentation, compressing qualification timelines and locking out smaller compounders lacking clinical-grade polymerization controls.
Growth Catalysts
- Latex allergy elimination mandates:Healthcare systems across the United States and Canada are phasing out natural rubber latex in surgical environments, redirecting procurement toward synthetic polyisoprene alternatives that eliminate Type I hypersensitivity risks without sacrificing elasticity performance.
- Ziegler-Natta catalyst advances:Enhanced stereospecific polymerization is yielding cis-1,4 content above 96 percent in medical-grade resins, meeting the tensile and recovery specifications previously achievable only with Hevea-derived material.
- Gulf Coast petrochemical integration:Proximity between isoprene monomer crackers and polymerization facilities in Texas and Louisiana is compressing logistics costs and enabling just-in-time supply to domestic medical device molders.
Market Restraints
- Isoprene feedstock volatility:Crude oil price fluctuations and naphtha cracking economics transmit directly to polyisoprene resin costs, squeezing compounder margins when downstream medical OEMs resist renegotiation of multi-year supply agreements.
- Butadiene rubber substitution:Industrial belting and tire component applications are partially reverting to styrene-butadiene copolymers during polyisoprene price spikes, capping volume expansion in non-medical segments.
- EPA emissions permitting:Isoprene monomer is classified as a volatile organic compound, requiring extensive air quality controls and Title V operating permits that extend facility commissioning timelines by 18-24 months in high-growth manufacturing zones.
Strategic Opportunities
- Mexican medical device manufacturing:Tijuana and Guadalajara clusters are attracting catheter and glove producers seeking proximity to U.S. distribution networks with lower labor inputs, creating demand for regional polyisoprene compounding capacity.
- Liquid polyisoprene formulating:Low-viscosity grades are penetrating precision molding applications for micro-catheters and minimally invasive surgical instruments where conventional solid rubber processing limits geometric complexity.
- California sustainable procurement mandates:State-level healthcare purchasing guidelines are prioritizing suppliers with verified bio-based content and closed-loop solvent recovery, rewarding producers with certified environmental management systems.
Industry Challenges
- Polymerization technician scarcity:Solution-phase Ziegler-Natta operations require specialized expertise in anionic chemistry and reactor control that is retiring faster than vocational programs replenish the workforce across the U.S. Gulf Coast.
- FDA 510(k) companion documentation:Medical-grade polyisoprene suppliers must maintain master file submissions that synchronize with device manufacturer regulatory filings, creating administrative overhead that smaller compounders struggle to sustain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Polyisoprene Market |
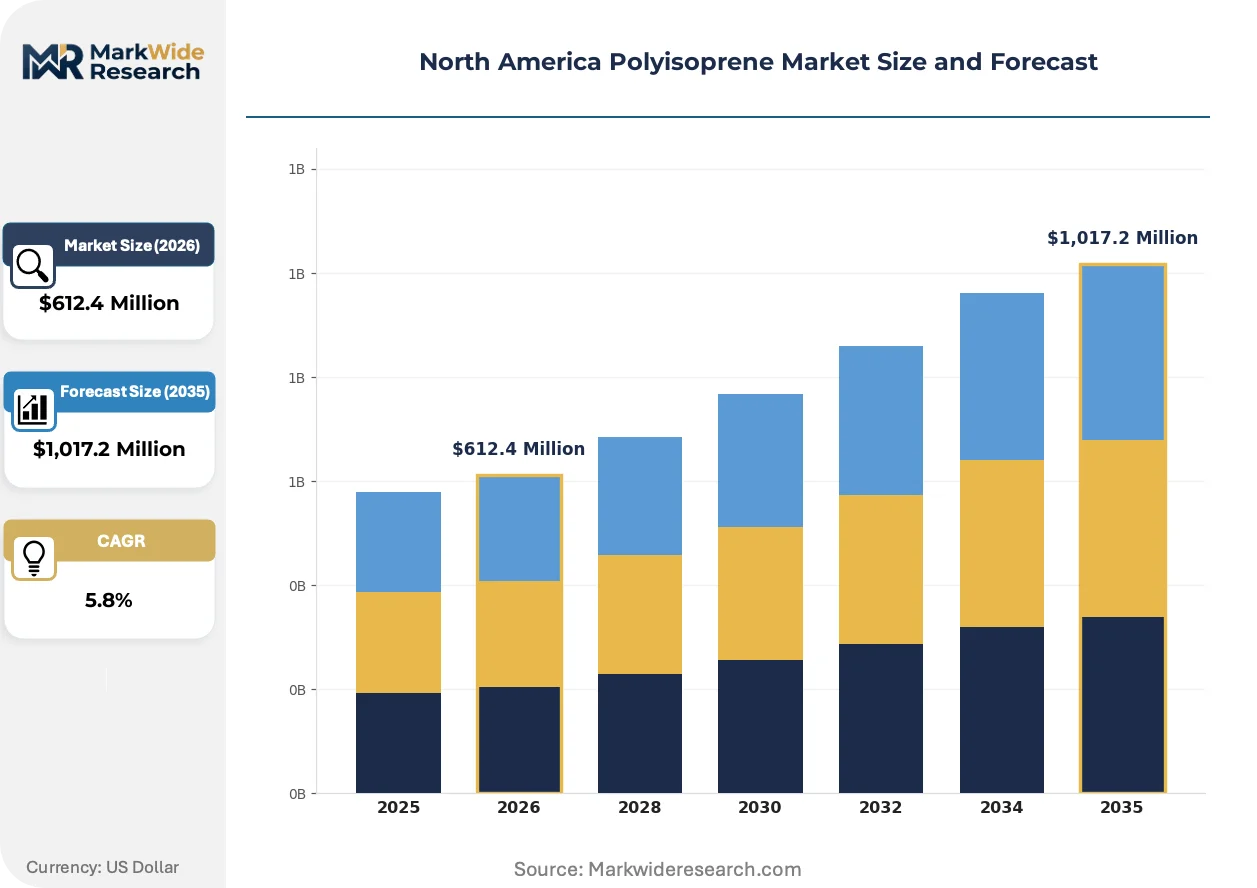
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Liquid, Solid Application: Medical Devices, Automotive Parts, Footwear, Industrial Products End User: Healthcare, Automotive, Consumer Goods, Manufacturing Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | JSR Corporation, ARLANXEO, ExxonMobil Chemical, Kraton Corporation, Lanxess AG, Goodyear Tire & Rubber Company, Kuraray Co Ltd, Lion Elastomers, Zeon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Polyisoprene Market Strategic Shifts & Innovations
Advanced polymerization architectures and regulatory documentation automation are compressing development cycles for clinical-grade elastomers while reshaping competitive qualification requirements.
Solution anionic polymerization with lithium-based initiators is electrifying precision in molecular weight distribution control for medical-grade polyisoprene. Catheter manufacturers in Minnesota and Massachusetts are adopting these resins for micro-extrusion applications requiring sub-millimeter wall thickness consistency. The technology is electrifying entry barriers by concentrating supply relationships around producers with pharmaceutical-grade cleanroom compounding capabilities.
ISO 10993-5 cytotoxicity testing harmonization with FDA biocompatibility guidance is streamlining supplier qualification protocols for implantable device applications. Compounders maintaining current master file submissions are capturing preferred vendor status with major surgical glove and balloon catheter OEMs. The regulatory convergence is most pronounced in cardiovascular device supply chains where dual ISO-FDA documentation is becoming a table-stakes requirement.
Healthcare procurement consolidation through group purchasing organizations is compressing supplier margins while extending contract durations. Integrated delivery networks in Texas and the Midwest are consolidating elastomer purchasing across multiple hospital systems, favoring compounders with national distribution infrastructure and redundant manufacturing sites. The behavioral shift is most visible in surgical glove categories where three-year sole-source agreements are displacing spot-market purchasing.
North America Polyisoprene Market Segmentation
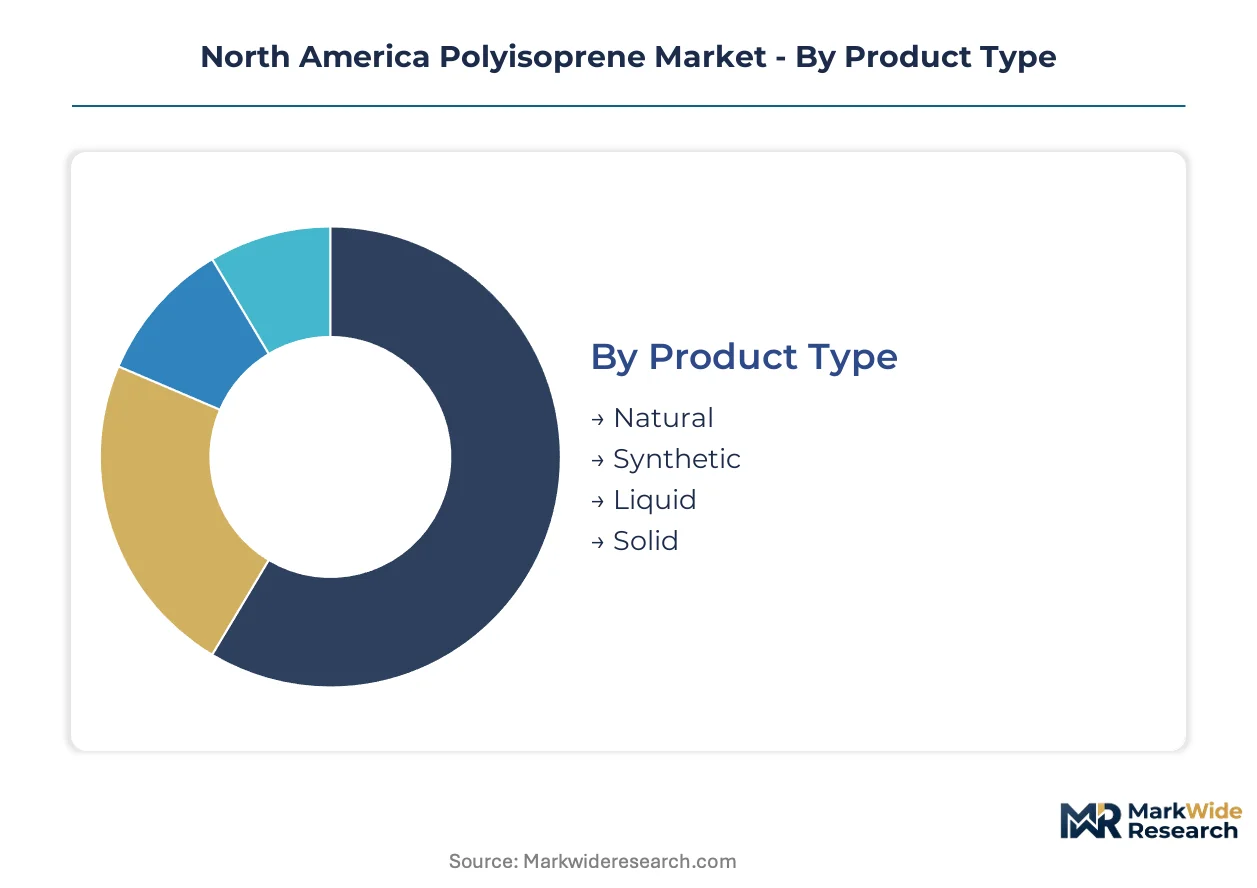
Polyisoprene procurement patterns diverge sharply across product forms and end-use specifications. Medical-grade synthetic grades command qualification-intensive supply relationships, while industrial segments prioritize cost efficiency and volume availability.
Product Type:
Synthetic grades are displacing natural rubber latex in surgical environments where protein allergen elimination drives upgrade cycles.
- Synthetic:Manufactured via Ziegler-Natta or anionic polymerization, these resins achieve cis-1,4 content above 96 percent. Demand concentrates in Minnesota and Massachusetts catheter manufacturing clusters, where FDA biocompatibility documentation requirements lock in supplier relationships with registered compounders.
- Liquid:Low-viscosity grades enable precision molding of micro-catheters and minimally invasive surgical instruments. Adoption is accelerating in Tijuana medical device maquiladoras seeking geometric complexity beyond conventional solid rubber processing limits.
- Natural:Hevea-derived material retains cost-sensitive industrial belting applications in the U.S. Southeast where protein content restrictions do not apply.
- Solid:Mature high-volume grades serve tire component and conveyor belt markets across Texas and Louisiana petrochemical corridors.
Volume placements concentrate in Solid synthetic grades; the faster expansion belongs to Liquid.
Application:
Cost-tier stratification separates qualification-intensive medical applications from price-sensitive industrial segments.
- Medical Devices:Surgical gloves, catheters, and balloon devices require ISO 10993 cytotoxicity documentation and FDA master file synchronization. Procurement consolidates around Gulf Coast compounders with pharmaceutical-grade cleanroom capabilities and redundant manufacturing sites.
- Automotive Parts:Vibration dampers, bushings, and seals utilize medium-grade synthetic polyisoprene. Styrene-butadiene substitution pressure intensifies during feedstock price spikes, capping margin expansion in this tier.
- Footwear:Soling and cushioning applications in Mexico and Central American manufacturing zones favor natural rubber blends for cost containment.
- Industrial Products:Conveyor belts, hoses, and molded goods across Ohio and Illinois manufacturing bases prioritize tensile consistency and lot-to-lot uniformity over clinical-grade specifications.
Medical Devices command the steepest expansion trajectory; Industrial Products anchor absolute volume.
End User:
Customer-type concentration reflects divergent procurement sophistication levels across healthcare and industrial verticals.
- Healthcare:Integrated delivery networks in Texas and the Midwest are consolidating elastomer purchasing across multi-hospital systems. Three-year sole-source agreements with FDA-registered suppliers are displacing spot-market purchasing for surgical gloves and catheters.
- Automotive:Tier-1 suppliers in Michigan and Ohio specify medium-grade synthetic resins with emphasis on lot traceability and just-in-time delivery windows aligned with assembly plant schedules.
- Consumer Goods:Footwear and sporting goods manufacturers in Mexico prioritize volume pricing and flexible minimum order quantities over technical documentation depth.
- Manufacturing:General industrial compounders across the U.S. Southeast and Midwest source standard-grade material through distributor networks with regional warehousing.
Healthcare procurement is climbing the fastest; Manufacturing retains the broadest supplier base.
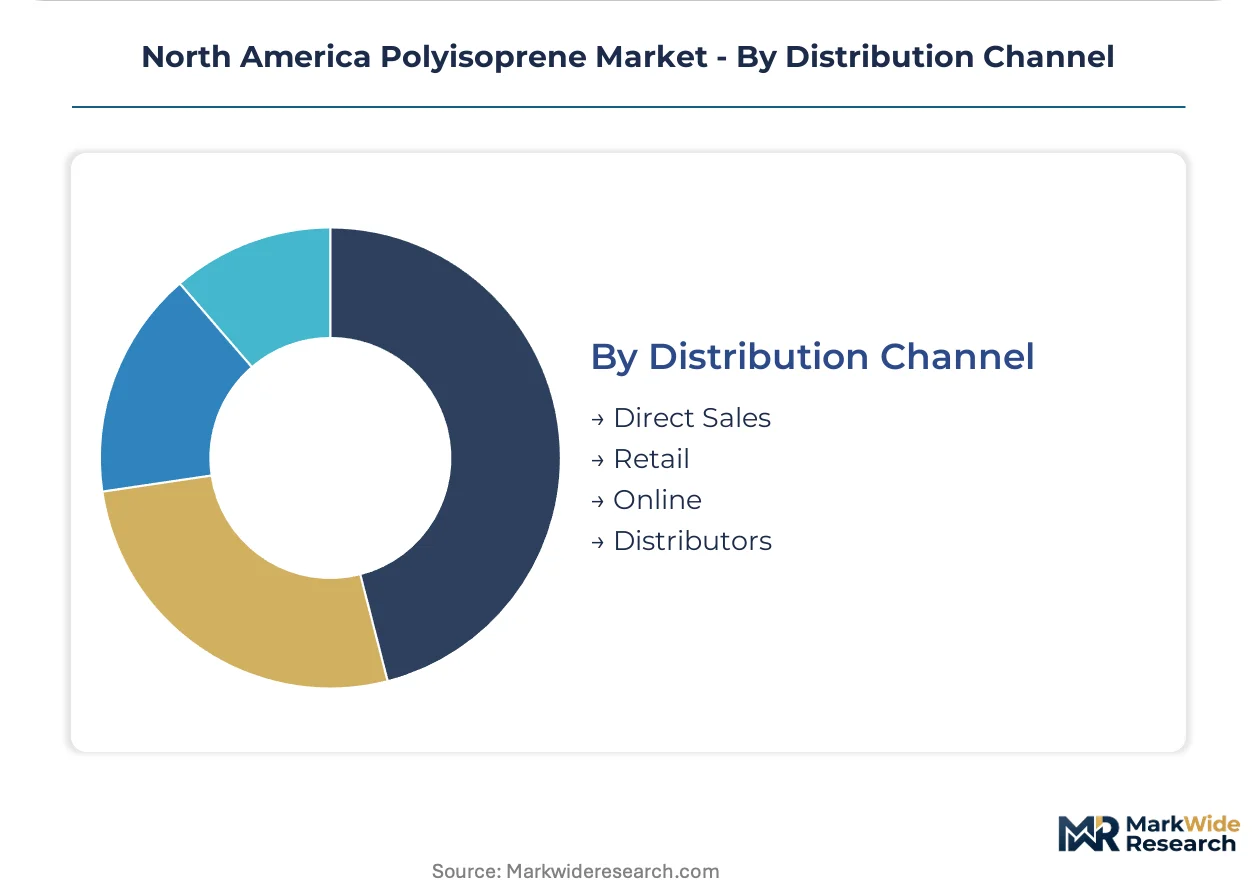
Distribution Channel:
Supply concentration patterns vary between direct mill relationships and intermediary-dependent segments.
- Direct Sales:Medical-grade producers in Texas and Louisiana maintain dedicated account teams for major catheter and glove OEMs. Master file coordination and regulatory synchronization require channel control that distributors cannot replicate.
- Distributors:Industrial belting and automotive compounders in Ohio, Illinois, and Michigan rely on regional chemical distributors for inventory buffering and technical service support.
- Online:Small-batch liquid polyisoprene procurement for R&D and prototype molding is migrating to specialized polymer e-commerce platforms with expedited sampling programs.
- Retail:Limited to hobbyist and small-scale footwear repair segments with minimal commercial significance.
Direct Sales capture the highest-margin placements; Distributors handle the greatest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Isoprene monomer crackers along the Texas and Louisiana Gulf Coast anchor polyisoprene production capacity across the continent. The U.S. Gulf Coast petrochemical corridor generates feedstock proximity advantages that compress logistics costs for domestic medical device molders. Cross-border manufacturing integration between the three countries reshapes supply chain configurations.
United States
Minnesota and Massachusetts catheter manufacturing clusters drive medical-grade polyisoprene consumption for micro-extrusion applications. FDA biocompatibility documentation requirements under ISO 10993 lock in supplier relationships with registered compounders. Texas and Louisiana host integrated synthetic rubber production where proximate isoprene monomer supply enables just-in-time delivery to healthcare OEMs.
Canada
Ontario's automotive parts sector consumes medium-grade synthetic polyisoprene for vibration dampers and seals supplied to Michigan assembly plants. Health Canada aligns medical device material regulations with FDA guidance, streamlining cross-border supplier qualification for surgical glove manufacturers. Quebec chemical distributors buffer inventory for industrial belting compounders serving Ontario and U.S. Midwest markets.
Mexico
Tijuana and Guadalajara medical device maquiladoras attract catheter and glove producers seeking proximity to U.S. distribution networks with lower labor inputs. The country's national pharmaceutical regulator enforces biocompatibility standards that mirror FDA protocols, facilitating integrated North American supply chains. Nuevo León and Jalisco industrial zones are developing regional polyisoprene compounding capacity to serve this demand.
North America Polyisoprene Market Key Industry Players
Global majors compete with regional champions across backward integration depth and medical-grade certification capabilities. The supplier base concentrates around integrated petrochemical operations with captive isoprene feedstock and pharmaceutical-grade cleanroom compounding facilities. Three archetypes dominate: Gulf Coast-integrated producers with monomer-to-polymer control, Japanese and German technology licensors with advanced Ziegler-Natta catalyst systems, and specialized styrenic block copolymer compounders with medical-grade adjacencies. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing long-term supply agreements with FDA-registered medical device OEMs.
Among Japanese chemical conglomerates, JSR Corporation and Zeon Corporation exemplify the technology-licensing archetype with advanced solution polymerization capabilities. ExxonMobil Chemical anchors the integrated producer tier through its position in the U.S. Gulf Coast petrochemical corridor. Kraton Corporation occupies a specialized position within the styrenic block copolymer segment that complements core polyisoprene offerings for medical applications.
| Leading Market Players |
|---|
| JSR Corporation |
| ARLANXEO |
| ExxonMobil Chemical |
| Kraton Corporation |
| Lanxess AG |
| Goodyear Tire & Rubber Company |
| Kuraray Co Ltd |
| Lion Elastomers |
| Zeon Corporation |
| Others |
Cost & Logistics Intelligence
Medical-grade certification tiers bifurcate North American polyisoprene procurement into locked-in premium supply relationships and spot-market commodity sourcing. FDA master file synchronization and ISO 10993 documentation requirements create pricing power for registered Gulf Coast compounders serving catheter OEMs, while industrial belting buyers negotiate volume discounts through distributor networks.
Pricing Analysis
Service bundling separates medical-grade suppliers offering regulatory documentation support from unbundled commodity resin vendors. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade levels reflects certification depth and cleanroom compounding investments. Pricing pressure stems from healthcare procurement consolidation through group purchasing organizations demanding multi-year contract locks. Industrial compounders exhibit highest price sensitivity, reverting to styrene-butadiene substitutes during isoprene feedstock spikes.
Supply Chain Analysis
Isoprene monomer supply rests on naphtha crackers concentrated along the Texas and Louisiana Gulf Coast, with secondary feedstock sourcing from Canadian oil sands operations. Key inputs include Ziegler-Natta catalyst systems, pharmaceutical-grade solvents, and precision polymerization reactor equipment. Tariff exposure on catalyst precursors sourced from German and Japanese technology licensors creates vulnerability in medical-grade production lines. Distribution runs through direct mill relationships for medical OEMs and regional chemical distributors for industrial compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American polyisoprene operates as a cost-of-compliance market where FDA biocompatibility documentation under ISO 10993 erects formidable barriers to entry, entrenching incumbent compounders with synchronized master file submissions and cleanroom capabilities.
For Market Incumbents: To counter styrene-butadiene substitution pressure in automotive tiers, deepen captive isoprene feedstock integration through Gulf Coast cracker partnerships and expand redundant manufacturing sites to satisfy healthcare procurement consolidation requirements for sole-source eligibility. For New Entrants and Emerging Players: Specialized polymer e-commerce platforms offering expedited liquid polyisoprene sampling programs penetrate the R&D prototyping segment underserved by bulk-focused incumbents. Target Tijuana medical device maquiladoras seeking regional compounding partners to compress cross-border logistics timelines for micro-catheter producers. For Investors and Strategic Acquirers: Re-rating potential sits with FDA-registered compounders possessing pharmaceutical-grade cleanroom assets given healthcare procurement consolidation toward three-year sole-source agreements. Monitor California sustainable procurement mandate adoption as an inflection signal for bio-based content certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isoprene Feedstock | Gulf Coast cracker proximity compresses logistics costs for medical device molders in Minnesota and Massachusetts. |
| FDA Master File Synchronization Investment | Regulatory documentation alignment locks in preferred vendor status with major catheter and surgical glove OEMs. |
| Regional Compounding Capacity in Mexico | Tijuana and Guadalajara facilities capture medical device maquiladora demand with lower labor inputs. |
| Liquid Polyisoprene Formulation Expansion | Low-viscosity grades enable precision molding for micro-catheters beyond solid rubber processing limits. |
| Closed-Loop Solvent Recovery Certification | California healthcare procurement mandates reward producers with verified environmental management systems. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving polymerization plant managers, medical device procurement leads at catheter OEMs, FDA regulatory affairs specialists, and Gulf Coast chemical distribution channel partners. Bottom-up resin consumption estimates triangulated against top-down petrochemical capacity assessments.
Data-stream reconciliation across production volume, import-export flows, and end-use consumption patterns shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product form, application tier, end-user vertical, and regional production hub proximity. CAGRs derived from trend extrapolation of medical device demand growth and industrial substitution elasticity, with specific inputs from healthcare procurement consolidation patterns and EPA emissions permitting timelines.
The model holds under stable isoprene feedstock pricing and consistent FDA regulatory enforcement; deviation in crude oil volatility or accelerated state-level chemical disclosure laws would shift volume trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
North America Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Polyester Polyol Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Resins Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Soy Polysaccharides Market
Polymers & Resins
Highly Reactive Polyisobutylene (HR-PIB) Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
Global Polyamide Market
Polymers & Resins
Global UV Curable Resins and Formulated Products Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market
Polymers & Resins
India Automotive Thermoplastic Polymer Composites Market