
 Ultra-Soft Thermoplastic Elastomer Market | 2026-2036
Ultra-Soft Thermoplastic Elastomer Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-Soft Thermoplastic Elastomer Market Analysis
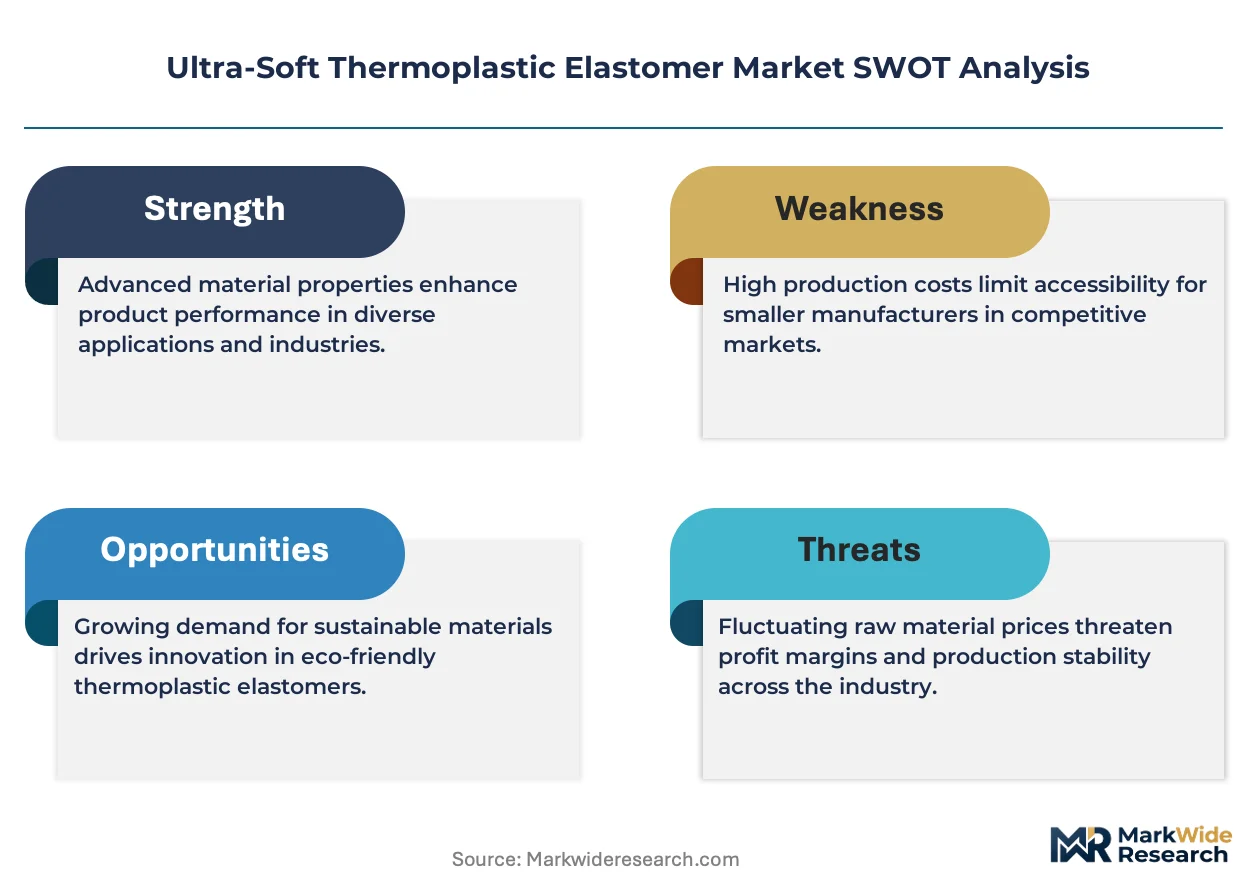
The gap between premium medical-grade formulations and commodity consumer-grade compounds is broadening. Lubrizol Corporation leverages its medical polymer expertise to sustain high-margin positions in implant-contact applications. Kraton Corporation anchors its portfolio with hydrogenated styrenic block copolymers that dominate overmolding segments for automotive soft-touch surfaces.
Ultra-soft thermoplastic elastomers are polymeric materials combining rubber-like elasticity with thermoplastic processability, typically exhibiting Shore A hardness below 30 and melt-processable behavior without vulcanization crosslinking. Their primary purpose centers on replacing silicone and PVC in applications requiring haptic softness, chemical resistance, and design flexibility. Styrenic block copolymers lead volume due to established supply chains and cost efficiency in footwear and consumer goods. Polyurethates capture premium margin pools in medical device tubing where biocompatibility certifications command price premiums.
FDA biocompatibility standards under ISO 10993 and REACH substance restrictions shape material selection and reformulation cycles for compounders serving regulated industries. EPA and OSHA workplace exposure limits further constrain solvent-based processing routes, accelerating waterborne and pellet-dry handling system investments. Stakeholders must monitor evolving EU MDR requirements and state-level chemical disclosure laws in California and Massachusetts as these will determine which formulation platforms retain market access.
Market Dynamics
Medical device OEMs in Germany and the United States are consolidating compound specifications around ISO 10993-certified formulations, compressing supplier qualification timelines and reshaping procurement power toward certified compounders with captive polymerization capacity.
Growth Catalysts
- EU MDR compliance deadlines:European medical device manufacturers are accelerating material requalification cycles ahead of notified body audits, pulling forward demand for pre-certified ultra-soft TPE grades.
- Automotive soft-touch interior mandates:German OEMs are specifying Shore A 10-20 compounds for steering wheel grips and console surfaces, displacing painted ABS in premium vehicle segments.
- Hydrogenated styrenic block copolymer processability:Injection molders are adopting waterborne compounding lines to meet EPA and OSHA solvent exposure limits, expanding addressable capacity for thin-wall medical tubing.
Market Restraints
- Raw material concentration:Hydrogenated styrenic block copolymer feedstock production clusters in Belgium and the Netherlands, exposing compounders to single-source disruption risk.
- Silicone substitution threat:Liquid silicone rubber suppliers are narrowing the processing cost gap through cold-deck molding advances, retaining implant-contact applications.
- REACH authorization timelines:ECHA substance scrutiny is extending plasticizer approval cycles, freezing formulation pipelines for 18-24 months.
Strategic Opportunities
- India medical device manufacturing:CDSCO regulatory harmonization with ISO 13485 is enabling export-oriented catheter and IV set production, creating virgin demand for biocompatible TPE tubing.
- Wearable device skin-contact applications:Fitness tracker and continuous glucose monitor manufacturers are specifying ultra-soft overmolds for 24-hour wear comfort, opening consumer health segments.
- Massachusetts chemical disclosure laws:State-level reporting mandates are advantaging compounders with full material transparency, creating compliance-based supplier selection.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization study queues at contract laboratories are extending product launch timelines.
- Multi-material bonding expertise:Overmolding ultra-soft TPE onto engineering thermoplastics requires process engineers with specialized rheology training, a skill set concentrated at German and Swiss technical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-Soft Thermoplastic Elastomer Market |
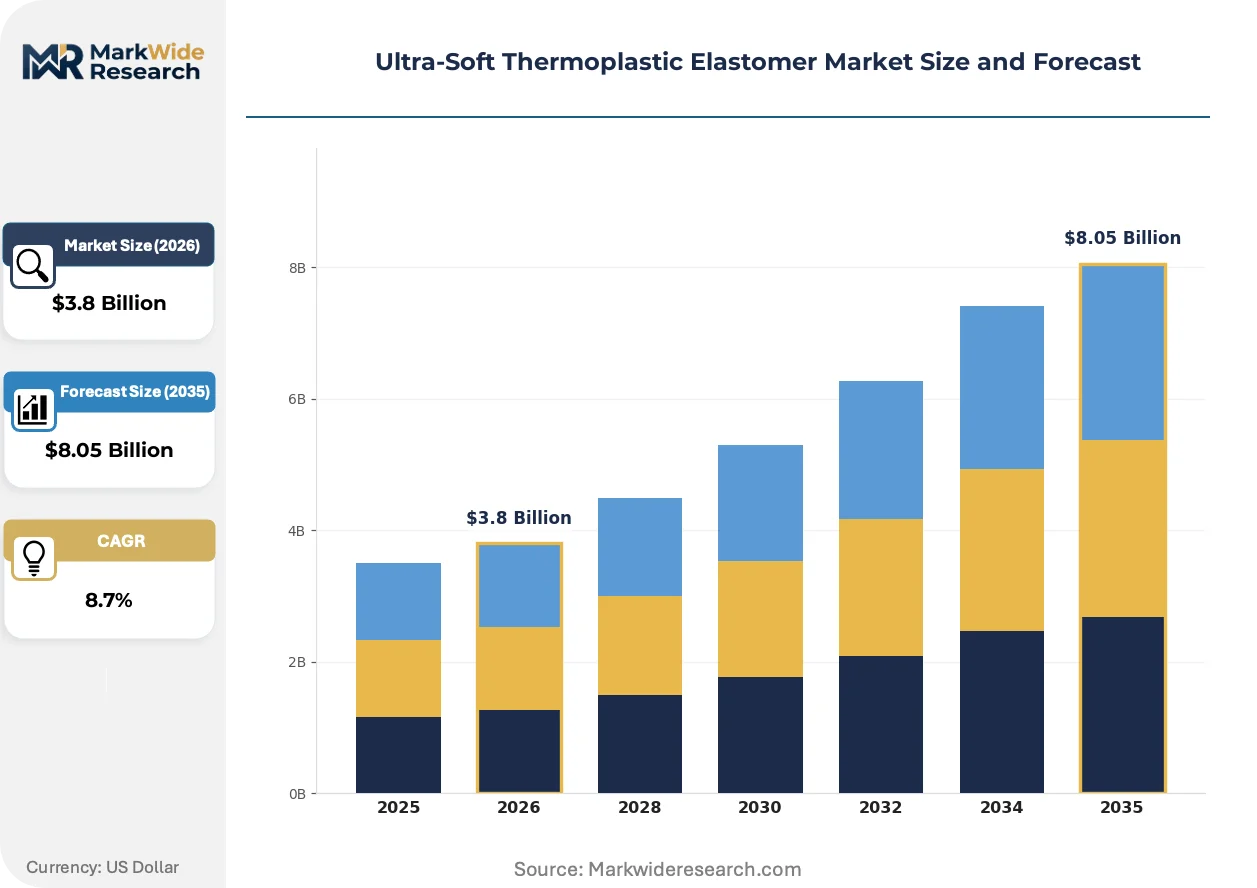
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrenic Block Copolymers, Polyurethanes, Olefinic Elastomers, Thermoplastic Vulcanizates Application: Automotive Interiors, Medical Devices, Footwear, Consumer Goods End User: Manufacturers, Research Institutions, Retailers, Distributors Form: Granules, Sheets, Films, Compounds |
| Companies Covered | Lubrizol Corporation, Asahi Kasei Corporation, Kraton Corporation, Teknor Apex, Franplast, BASF SE, Tosoh Corporation, Dow Chemical Company, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-Soft Thermoplastic Elastomer Market Emerging Trajectories
Compound development is pivoting from hardness-centric specifications toward functional performance matrices that combine haptic targets with chemical resistance and sterilization compatibility. This reorientation is compressing traditional formulation cycles and rewarding integrated R&D operations.
Dynamic vulcanization of silicone-TPV hybrids is electrifying the medical tubing segment by delivering compression set performance comparable to thermoset silicone while retaining thermoplastic reprocessability. Catheter manufacturers in Minnesota and Massachusetts are qualifying these materials for multi-lumen extrusion lines. The technology is compressing the historical silicone-TPE cost premium by eliminating secondary curing steps.
REACH substance restrictions on phthalate plasticizers are forcing reformulation of legacy soft-touch compounds across European automotive supply chains. Tier suppliers in Stuttgart and Wolfsburg are validating bio-based plasticizer alternatives through ECHA pre-registration pathways. The regulatory pressure is most acute in child-contact interior applications, where OEMs are demanding full substance disclosure to 0.1% thresholds.
Specification consolidation among medical device contract manufacturers is concentrating procurement volumes with compounders holding dual FDA master file and EU MDR technical documentation. Original equipment manufacturers in the Research Triangle and Orange County are bypassing distributors for direct mill relationships. This behavioral shift is most visible in Class II device segments, where material traceability requirements have tightened under updated FDA guidance documents.
Ultra-Soft Thermoplastic Elastomer Market Segmentation
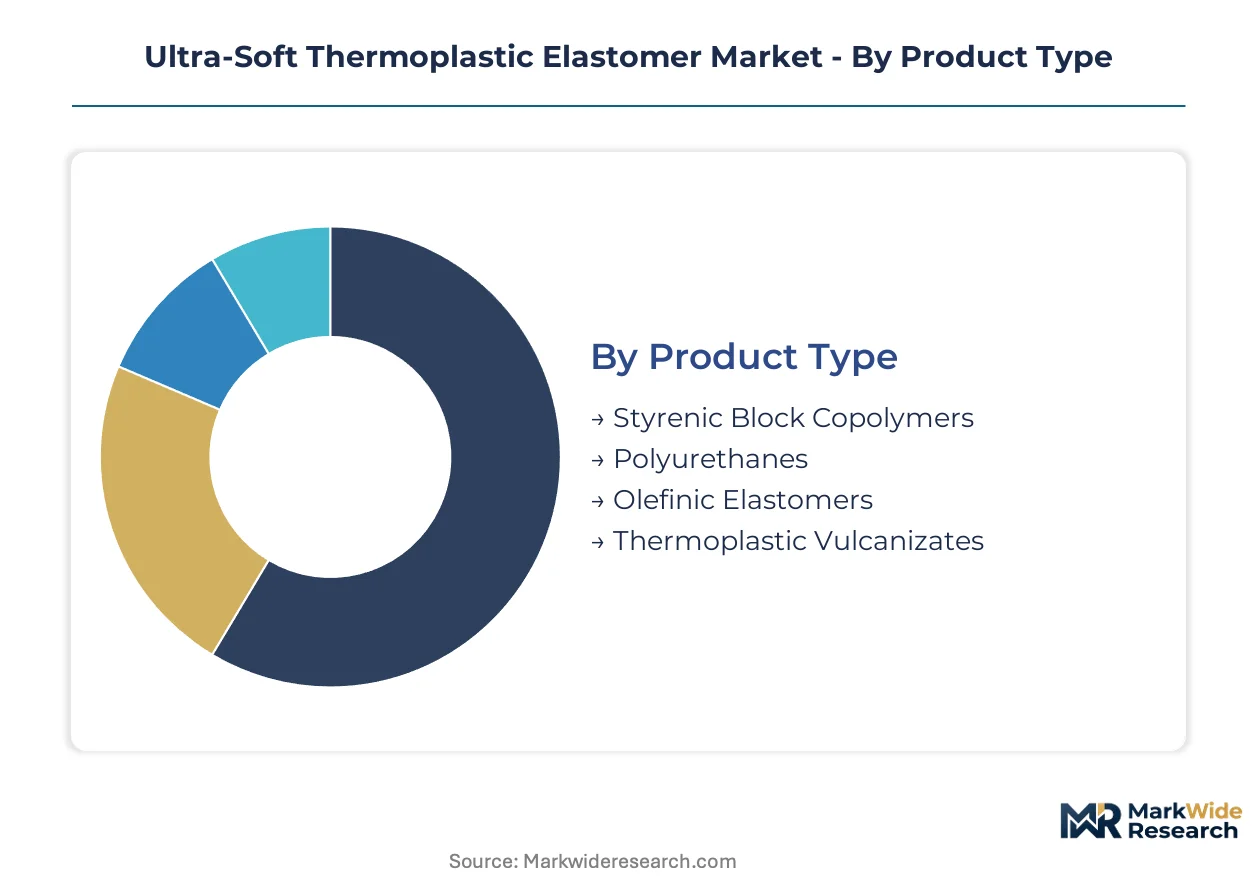
Ultra-soft thermoplastic elastomers fragment across polymer chemistry, physical form, and end-use requirements. Each segmentation axis carries distinct margin profiles and certification burdens that determine supplier positioning.
Product Type:
Feedstock concentration in hydrogenated styrenic block copolymer production clusters shapes competitive access and pricing leverage for compounders.
- Styrenic Block Copolymers:Hydrogenated SEBS and SIS variants dominate volume through established polymerization capacity in Belgium and the Netherlands. German automotive OEMs and footwear manufacturers in Vietnam and Indonesia absorb the majority of global output.
- Polyurethanes:Castable TPU grades command premium positioning in medical device tubing where ISO 10993-5 cytotoxicity certification is mandatory. Minnesota and Massachusetts catheter manufacturers are consolidating procurement around FDA master file holders with captive polymerization.
- Olefinic Elastomers:Metallocene-catalyzed plastomers serve cost-sensitive consumer goods and packaging seals through reactor-grade supply chains concentrated with Saudi and South Korean petrochemical majors.
- Thermoplastic Vulcanizates:Dynamic vulcanization of EPDM-PP blends delivers compression set performance approaching thermoset rubber for automotive underhood and industrial hose applications.
Styrenic block copolymers absorb the bulk of installed capacity; polyurethanes are expanding most quickly on medical certification premiums.
Application:
End-use specifications diverge sharply between regulated medical environments and performance-driven automotive interiors.
- Automotive Interiors:Shore A 10-20 compounds for steering wheel grips, console surfaces, and door seals displace painted ABS in premium German vehicle segments. BMW and Mercedes-Benz specifications now mandate low-VOC emission profiles under VDA 278 testing protocols.
- Medical Devices:Multi-lumen catheter tubing, IV set components, and respiratory masks require ISO 10993-certified formulations with full REACH substance disclosure. Contract manufacturers in the Research Triangle and Orange County are bypassing distributors for direct mill relationships.
- Footwear:Midsole and outsole applications in running and lifestyle categories leverage SBC cost efficiency through established injection molding supply chains in Vietnam and Indonesia.
- Consumer Goods:Toothbrush grips, cosmetic applicators, and kitchen utensil handles prioritize haptic softness and colorability over certification burdens.
Automotive interiors command the highest per-kilogram pricing; medical devices are climbing the fastest on regulatory compliance premiums.
End User:
Procurement sophistication varies dramatically across the value chain, from specification-setting OEMs to price-sensitive distributors.
- Manufacturers:Medical device OEMs and automotive Tier 1 suppliers drive compound development through collaborative R&D programs with certified compounders.
- Research Institutions:Universities and national laboratories in Germany, Switzerland, and the United States pioneer next-generation silicone-TPV hybrids and bio-based plasticizer validation.
- Retailers:Mass-market consumer goods brands prioritize inventory flexibility and color-matching speed over technical performance differentiation.
- Distributors:Regional compound resellers serve molders without direct mill relationships, though medical device consolidation is compressing their relevance in certified grades.
Manufacturers absorb the bulk of technical collaboration investment; research institutions are expanding most quickly on government-funded materials innovation programs.
Form:
Physical presentation determines handling infrastructure requirements and downstream processing flexibility.
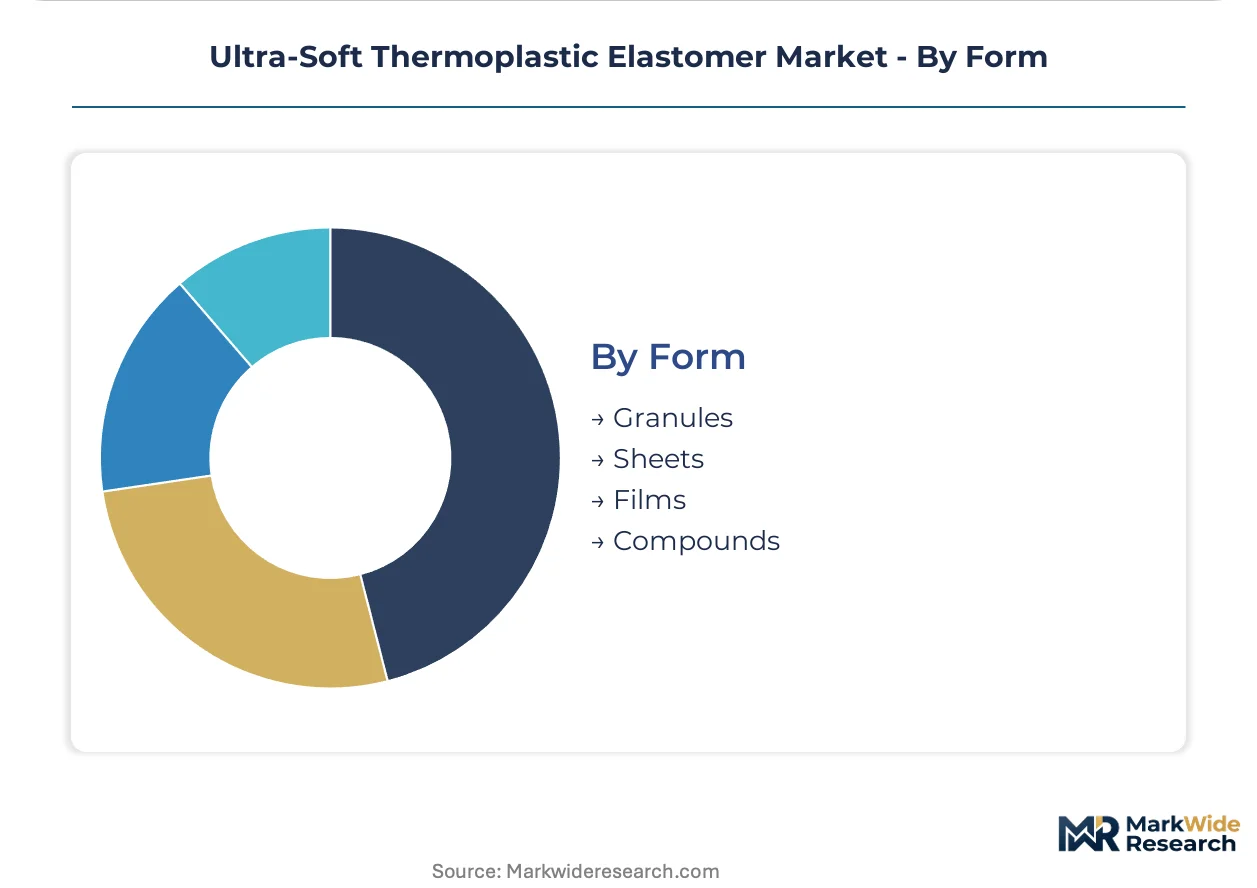
- Granules:Pelletized compounds dominate injection molding and extrusion through automated feeding systems, with medical-grade lots requiring individual bag traceability.
- Sheets:Calendered rolls serve automotive interior lamination and industrial gasket applications where thickness tolerance is critical.
- Films:Cast and blown film grades enable breathable membranes for medical drapes and consumer packaging through multi-layer coextrusion.
- Compounds:Custom-mixed batches with customer-specified color and additive packages support short-run medical device validation and automotive prototype development.
Granules absorb the bulk of volume throughput; films are expanding most quickly on medical packaging and wearable device membrane applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European demand for automotive soft-touch compounds, while medical device clusters in Minnesota and Massachusetts pull certified formulations from specialized compounders. German OEM specifications and FDA master file requirements reshape procurement patterns across both continents.
United States
Medical device OEMs in the Research Triangle and Orange County consolidate procurement around ISO 10993-certified compounders with captive polymerization. FDA biocompatibility requirements under updated guidance documents compress supplier qualification timelines. Minnesota catheter manufacturers are qualifying silicone-TPV hybrids for multi-lumen extrusion lines.
Germany
BMW and Mercedes-Benz specifications mandate Shore A 10-20 compounds for steering wheel grips and console surfaces, displacing painted ABS in premium segments. REACH substance restrictions and VDA 278 low-VOC testing protocols tighten material certification standards. Stuttgart and Wolfsburg clusters validate bio-based plasticizer alternatives through ECHA pre-registration pathways.
Belgium
Hydrogenated styrenic block copolymer feedstock production concentrates near Antwerp, exposing compounders to single-source disruption risk. ECHA authorization timelines extend plasticizer approval cycles, freezing formulation pipelines. The port complex serves as the primary European distribution node for SEBS and SIS variants.
China
Footwear manufacturers in Guangdong and Fujian absorb bulk SBC volume through established injection molding supply chains. NMPA regulatory harmonization with ISO 13485 accelerates medical device compound localization. Yangtze River Delta medical tubing producers are building direct mill relationships with hydrogenated styrenic suppliers.
India
CDSCO regulatory alignment with ISO 13485 enables export-oriented catheter and IV set production for North American and European markets. Maharashtra and Gujarat medical device parks attract compounders seeking biocompatible TPE tubing demand. Government PLI scheme incentives support domestic polymerization capacity investments.
Ultra-Soft Thermoplastic Elastomer Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade stratification, with medical-grade compounders commanding price premiums over consumer-grade suppliers. The vendor base organizes around three strategic archetypes: integrated petrochemical majors with captive hydrogenated SBC production, specialized medical compounders with FDA master file holdings, and regional distributors serving price-sensitive footwear and consumer goods molders. Dominant competitive moves include backward integration into hydrogenation capacity and geographic expansion toward Indian medical device manufacturing zones.
Within the medical-grade tier, Lubrizol Corporation and Kraton Corporation exemplify divergent positioning strategies. Lubrizol leverages polymer expertise to sustain high-margin positions in implant-contact applications requiring ISO 10993-5 cytotoxicity certification. Kraton anchors portfolio positioning with hydrogenated styrenic block copolymers that dominate overmolding segments for automotive soft-touch surfaces. Among diversified chemical majors, BASF SE and Covestro AG occupy positions spanning multiple elastomer chemistries with cross-segment formulation capabilities. Asahi Kasei Corporation represents the Asian integrated producer archetype with regional supply chain density.
| Leading Market Players |
|---|
| Lubrizol Corporation |
| Asahi Kasei Corporation |
| Kraton Corporation |
| Teknor Apex |
| Franplast |
| BASF SE |
| Tosoh Corporation |
| Dow Chemical Company |
| Covestro AG |
| Others |
Supply Flow & Price Mechanics
Medical device OEMs in Minnesota and Massachusetts concentrate procurement volumes with ISO 10993-certified compounders, anchoring a value-based pricing model where biocompatibility certification commands substantial premiums over commodity grades.
Pricing Analysis
ISO 10993-5 cytotoxicity certification anchors value-based pricing, with FDA master file holders capturing premium positioning against uncertified competitors. Price differentiation rests on certification tier and captive polymerization capability. Cost compression in consumer-grade SBC compounds is intensifying because footwear manufacturers in Vietnam and Indonesia exert volume leverage. Distributors serving molders without direct mill relationships exhibit highest price sensitivity; implant-contact compounders with full REACH disclosure face minimal bargaining pressure.
Supply Chain Analysis
Regional distribution centers near Antwerp warehouse hydrogenated styrenic block copolymer feedstock for European compounders, while Singapore and Rotterdam hubs serve Asia-Pacific and North American demand. Hydrogenated SEBS production draws from Belgium, the Netherlands, and South Korea. Raw material dependencies include styrene monomer, butadiene, and hydrogenation catalysts. Single-source vulnerability concentrates in Antwerp polymerization assets. Distribution runs through direct mill relationships for medical-grade lots and regional distributors for consumer-grade volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogenated styrenic block copolymer polymerization capacity concentrates in Belgium and the Netherlands, propping pricing power for certified compounders serving regulated medical device OEMs.
For Market Incumbents: To counter liquid silicone rubber cold-deck molding advances in implant-contact applications, prioritize backward integration into hydrogenation capacity and expand captive polymerization assets in India. CDSCO regulatory harmonization creates first-mover positioning for export-oriented catheter production. For New Entrants and Emerging Players: Wearable device manufacturers specifying 24-hour skin-contact overmolds represent the most penetrable buyer archetype, with fitness tracker and continuous glucose monitor producers underserved by incumbent medical compounders. Massachusetts chemical disclosure laws create compliance-based entry angles for transparent formulation platforms. For Investors and Strategic Acquirers: The window for entry favors compounders with dual FDA master file and EU MDR technical documentation holdings. Long-term viability hinges on regulatory certification moats rather than commodity scale. Watch ECHA substance authorization timelines as inflection indicators for plasticizer-dependent formulation portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogenation Capacity | Captive SEBS polymerization insulates compounders from Antwerp supply disruptions. |
| FDA Master File Investment | Biocompatibility documentation accelerates Minnesota catheter manufacturer qualification timelines. |
| India Manufacturing Footprint Expansion | Maharashtra medical device parks attract CDSCO-aligned compounders for export production. |
| Bio-Based Plasticizer Validation | ECHA pre-registration pathways enable REACH-compliant automotive interior formulations. |
| Direct Mill Relationship Cultivation | Research Triangle OEMs bypass distributors for traceable Class II device material supply. |
Methodological Framework
Document review covered FDA 510(k) filings, ECHA substance registration databases, and EU MDR technical documentation, complemented by interviews with medical device procurement managers, polymerization plant engineers, and automotive Tier 1 supplier technical directors. Secondary validation drew from SEC 10-K disclosures, customs trade data, and ISO certification registries. Bottom-up demand modeling and top-down supply capacity assessments were triangulated to cross-verify volume estimates.
Segmented outputs across polymer chemistry, physical form, Shore hardness tier, and end-use application fed into the projection framework. CAGRs were derived from regression analysis of historical certification-driven price premiums and capacity expansion timelines. Forecast inputs incorporated REACH authorization pipeline status and CDSCO regulatory harmonization progress.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance restrictions and silicone-TPV hybrid adoption rates. Outputs reflect documented assumptions around regulatory timeline adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Cold Cast Elastomers Market
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
Hot Cast Elastomers Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
Styrene Ethylene Butylene Styrene (SEBS) Market
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Global Acrylic Elastomers Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
North America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Middle-East and Africa Fluoroelastomers Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
Europe Single-Ply Membrane Market
Elastomeric Membrane
Stretchable Conductive Material Market
Elastomeric Membrane
Silicone Elastomers Market