
 1,4 Butanediol Derivatives Market | 2026-2036
1,4 Butanediol Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
1,4 Butanediol Derivatives Market Analytics
Chinese petrochemical producers is broadening BDO derivative output through coal-to-chemicals integration. BASF SE leverages its Ludwigshafen Verbund site to sustain captive tetrahydrofuran supply for European engineering plastics customers. Mitsubishi Chemical Group Corporation anchors Asia-Pacific gamma-butyrolactone capacity through its Kurosaki operations. SINOPEC competes on feedstock cost position via its integrated refineries in Ningbo and Shanghai.
1,4 Butanediol derivatives comprise downstream chemicals synthesized through catalytic dehydrogenation, cyclization, or esterification of BDO feedstock, typically requiring polymer-grade purity above 99.5 weight percent for solvent and engineered polymer applications. These compounds serve as essential intermediates for spandex fibers, lithium-ion battery binders, pharmaceutical excipients, and high-performance thermoplastic elastomers. Tetrahydrofuran dominates product type value generation owing to its role as the primary monomer for polytetramethylene ether glycol in spandex production. Polybutylene terephthalate captures expanding margin pools in automotive electronics and connector housings as OEMs substitute metals with engineering thermoplastics. Gamma-butyrolactone maintains steady pharmaceutical solvent demand despite regulatory scrutiny on precursor classification.
REACH registration requirements in the European Union govern chemical safety dossiers for BDO derivative importers, while China's MEE enforces emissions standards on coal-based BDO process operators. The US EPA Toxic Substances Control Act triggers pre-manufacture notifications for novel bio-based tetrahydrofuran entrants seeking domestic market access. Stakeholders must monitor feedstock pathway certification schemes and precursor control list revisions to secure long-term offtake contracts without supply interruption.
Market Dynamics
Coal-to-chemicals integration in China is compressing production costs for BDO derivatives while EU bio-based mandates force European producers toward renewable feedstock pathways, creating a bifurcated global cost structure.
Growth Catalysts
- Spandex fiber expansion:Polytetramethylene ether glycol demand from textile manufacturers in Vietnam and Indonesia pulls tetrahydrofuran consumption upward as regional apparel production scales.
- REACH bio-based quotas:EU chemical safety dossier requirements under ECHA guidance redirect investment toward renewable process routes for gamma-butyrolactone pharmaceutical solvents.
- Lithium-ion battery binders:Electric vehicle cathode manufacturing in South Korea and Japan consumes polyvinylidene fluoride precursors derived from BDO feedstock.
Market Restraints
- Coal price volatility:Chinese producers dependent on coal gasification face margin compression when thermal coal benchmarks spike, undermining cost advantages against naphtha-based competitors.
- Precursor classification scrutiny:Gamma-butyrolactone regulatory friction in multiple jurisdictions restricts solvent distribution channels and adds compliance overhead for pharmaceutical excipient suppliers.
- Acetylene substitution threat:Reppe process operators confront displacement risk from propylene oxide-based BDO routes as petrochemical complexes achieve superior carbon efficiency metrics.
Strategic Opportunities
- Indian specialty chemicals:Underpenetrated domestic production creates white space for gamma-butyrolactone manufacturing serving CDSCO-regulated pharmaceutical formulation growth.
- Polybutylene terephthalate automotive electronics:OEM metal substitution programs in connector housings and sensor modules expand engineering thermoplastic offtake.
- EU Green Deal funding:Renewable tetrahydrofuran process development qualifies for innovation grants under the European Commission's decarbonization incentive frameworks.
Industry Challenges
- Catalysis expertise scarcity:Specialized hydrogenation reactor engineering talent concentrates with legacy acetylene chemistry operators, constraining new entrant process design capabilities.
- Polymer-grade purity certification:Battery binder applications require 99.95 weight percent BDO derivative specifications, extending qualification timelines with cathode material suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1,4 Butanediol Derivatives Market |
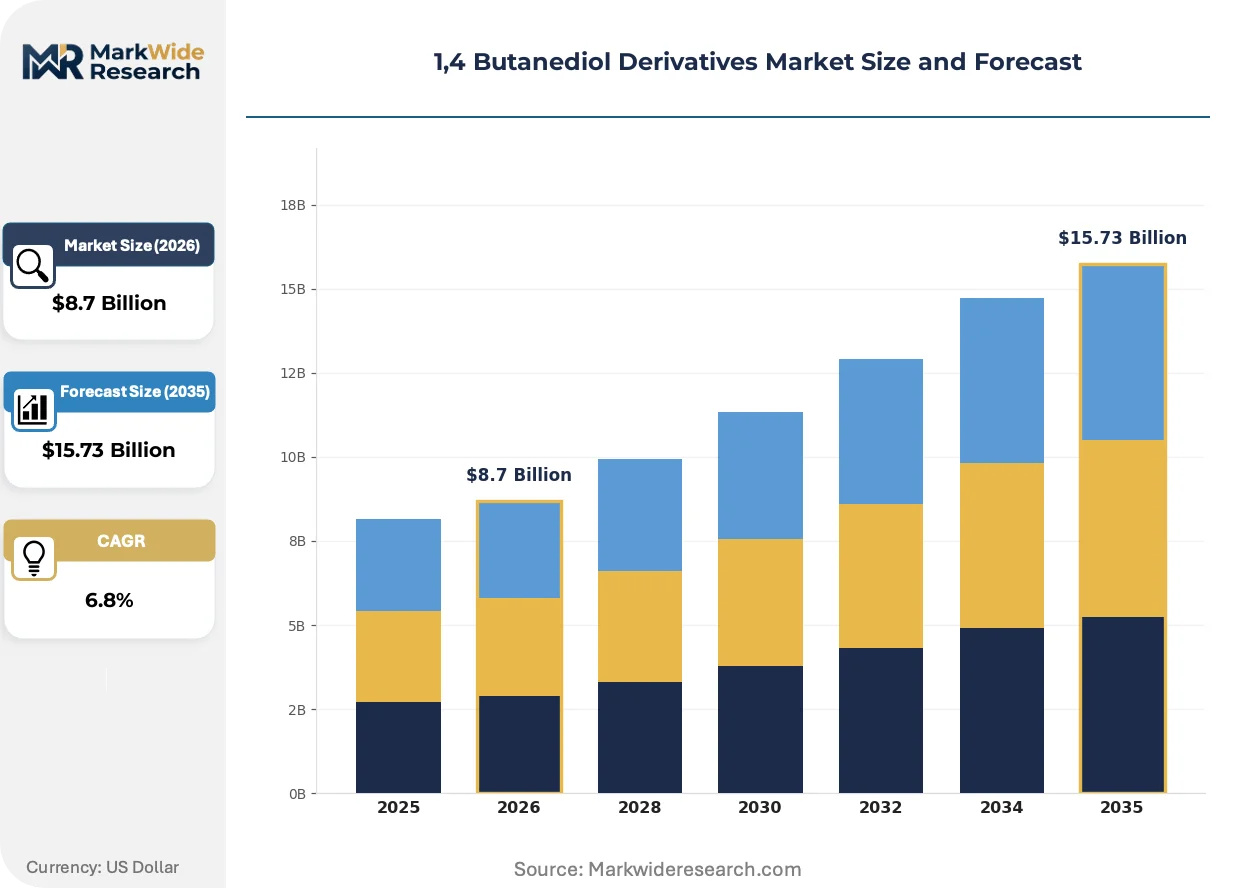
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butyric Acid, Tetrahydrofuran, Polybutylene Terephthalate, Gamma-Butyrolactone End Use Industry: Automotive, Pharmaceuticals, Electronics, Textiles Form: Liquid, Solid, Powder, Granule Application: Solvents, Adhesives, Coatings, Plastics |
| Companies Covered | BASF SE, DCC, Mitsubishi Chemical Group Corporation, LyondellBasell Industries Holdings B.V., Evonik Industries AG, Ashland Global Holdings Inc., SINOPEC, Sipchem Company, Genomatica, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1,4 Butanediol Derivatives Market Evolving Landscape
Electrification of chemical process heating and feedstock pathway diversification are compressing established production economics while opening novel competitive positioning for renewable-integrated operators.
Biomass-derived tetrahydrofuran via furfural hydrogenation is decentralizing supply origin away from petrochemical hub concentration. Specialty chemical distributors in the Netherlands and Germany are qualifying second-source renewable material streams. This technology is decentralizing procurement risk management for spandex manufacturers seeking dual-feedstock security.
ECHA REACH registration requirements for bio-based BDO derivatives are tightening substance volume tracking and safety data documentation obligations. European importers now face expanded dossier obligations for renewable tetrahydrofuran versus fossil-derived equivalents. German and French chemical distributors are restructuring supply agreements to segregate renewable-certified inventory streams.
Automotive OEMs are unbundling material certification from volume contracts, requiring separate documentation for polybutylene terephthalate carbon footprint verification. Tier-1 suppliers in Stuttgart and Munich are establishing direct relationships with bio-based BDO derivative producers to secure Scope 3 emissions data. This pattern is most visible in German automotive electronics procurement where OEM sustainability scorecards now weight feedstock pathway transparency.
1,4 Butanediol Derivatives Market Segmentation
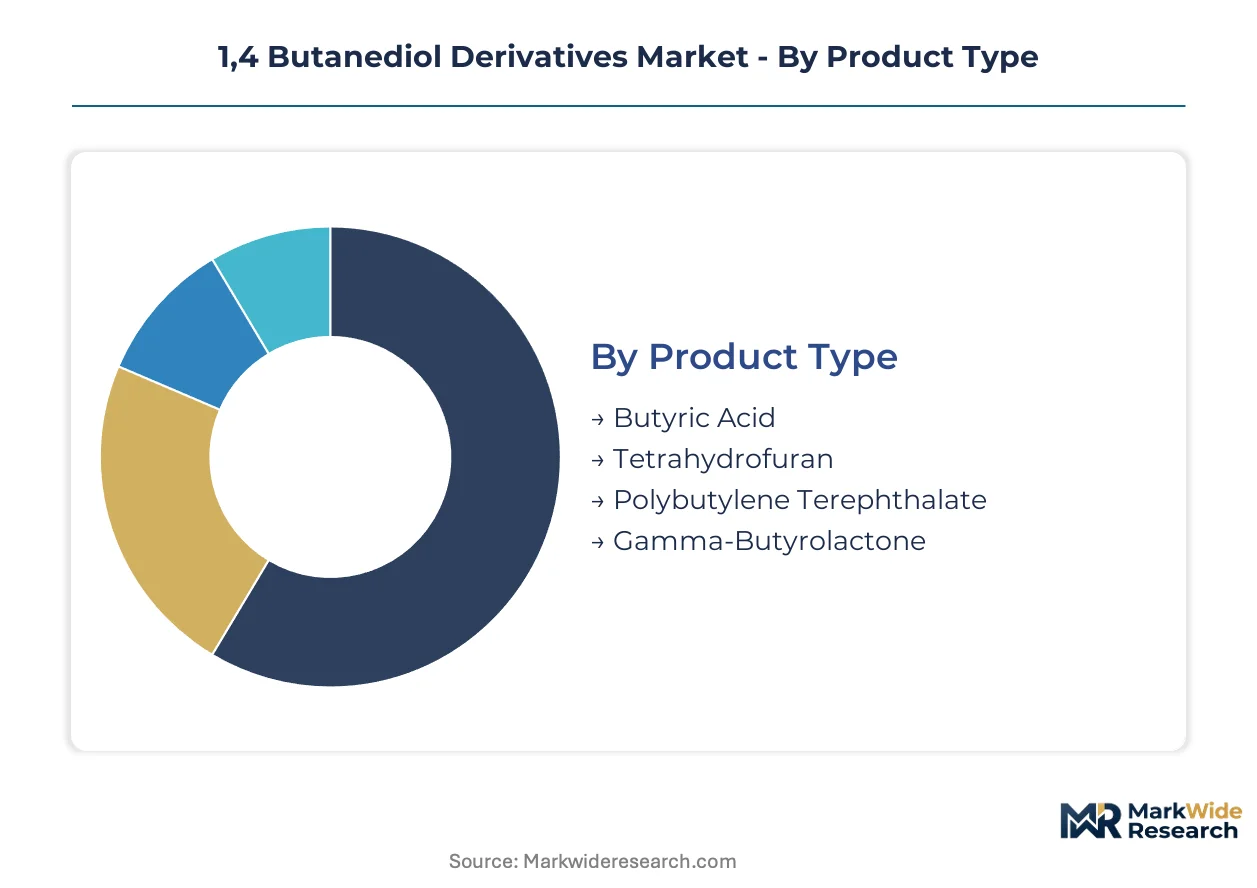
Segmentation in 1,4 Butanediol derivatives reveals how capital deployment, regulatory exposure, and end-use specifications fragment commercial opportunity. Distinct technical requirements across product types and applications create divergent margin profiles that reward specialized positioning.
Product Type:
Tetrahydrofuran and Polybutylene Terephthalate command the heaviest upfront investment due to polymerization infrastructure and purity certification requirements.
- Tetrahydrofuran:Cyclic ether produced via catalytic dehydration of BDO feedstock, requiring hydrogenation reactors and distillation trains rated for 99.95 weight percent purity. Spandex fiber manufacturers in Vietnam and Indonesia pull volumes upward as regional textile production scales, though acetylene-based Reppe process operators face displacement risk from propylene oxide routes.
- Polybutylene Terephthalate:Semi-crystalline thermoplastic polyester synthesized through polycondensation of BDO with terephthalic acid, demanding melt-phase reactor systems and solid-state polymerization for automotive-grade specifications. OEM metal substitution programs in German connector housings and sensor modules expand engineering thermoplastic offtake as sustainability scorecards weight feedstock pathway transparency.
- Gamma-Butyrolactone:Lactone solvent serving pharmaceutical excipient and lithium-ion battery electrolyte applications, subject to precursor classification scrutiny across multiple jurisdictions.
- Butyric Acid:Carboxylic acid derivative with limited commercial scale, primarily consumed in flavor and fragrance formulations.
Most installed capacity flows through Tetrahydrofuran. Expansion is steepest in Polybutylene Terephthalate.
End Use Industry:
Automotive and Electronics segments concentrate the highest value-add applications where material certification commands premium positioning.
- Automotive:Engineering thermoplastics for under-hood components, electrical connectors, and sensor housings, with German OEMs unbundling carbon footprint verification from volume contracts. Tier-1 suppliers in Stuttgart and Munich establish direct relationships with bio-based BDO derivative producers to secure Scope 3 emissions data.
- Electronics:Lithium-ion battery binders and printed circuit board substrates, where South Korean and Japanese cathode manufacturing consumes polyvinylidene fluoride precursors derived from BDO feedstock.
- Pharmaceuticals:Gamma-butyrolactone solvent demand for active pharmaceutical ingredient synthesis, constrained by CDSCO and EMA regulatory friction on precursor distribution channels.
- Textiles:Spandex fiber production via polytetramethylene ether glycol intermediates, concentrated in Vietnamese and Indonesian apparel manufacturing clusters.
Automotive generates the highest per-kilogram margins. Electronics is climbing the fastest as battery chemistry requirements tighten.
Form:
Liquid and Solid forms dominate commercial throughput, with Powder and Granule variants serving niche specification markets.
- Liquid:Bulk solvent and monomer delivery for tetrahydrofuran and gamma-butyrolactone, requiring stainless-steel storage and nitrogen-blanketed transport logistics.
- Solid:Polybutylene terephthalate resin pellets for injection molding and extrusion, with automotive-grade lots demanding lot-traceable viscosity specifications.
- Powder:Specialized adhesive and coating formulations where particle size distribution affects film formation properties.
- Granule:Engineering polymer feedstock for compounding operations, offering reduced dust handling versus powder alternatives.
Liquid form carries the largest volume base. Solid form is gaining share fastest as automotive thermoplastic substitution accelerates.
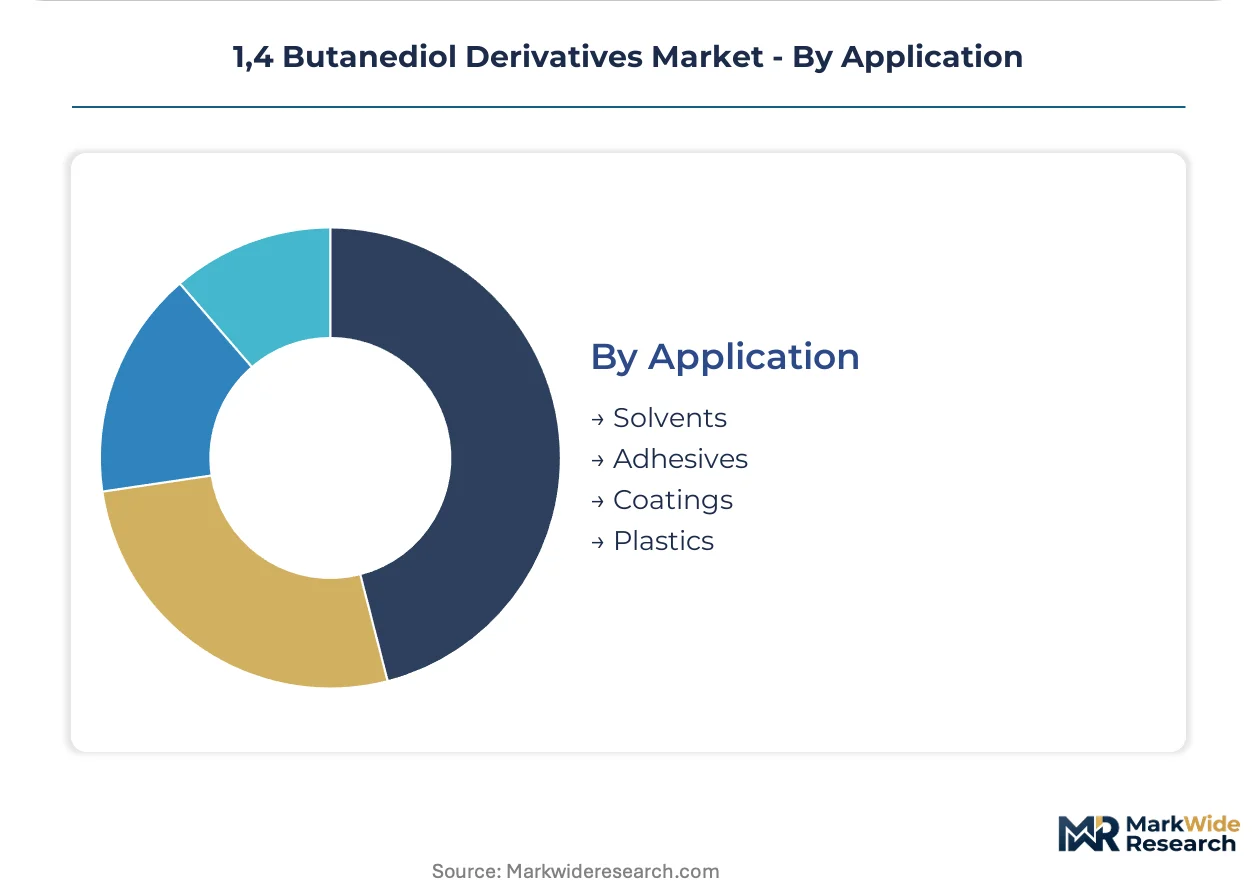
Application:
Solvents and Plastics absorb the majority of derivative output, with Adhesives and Coatings representing specification-driven specialty niches.
- Solvents:Gamma-butyrolactone and tetrahydrofuran for pharmaceutical and polymer processing applications, with REACH bio-based quotas redirecting European investment toward renewable process routes.
- Plastics:Polybutylene terephthalate for automotive electronics and consumer goods, where polymer-grade purity certification extends qualification timelines with cathode material suppliers.
- Adhesives:Reactive hot-melt and polyurethane systems for industrial bonding, leveraging BDO-derived polyols for hydrolysis resistance.
- Coatings:Polyurethane dispersions and polyester resins for protective and decorative finishes, requiring VOC compliance under EPA and MEE emissions standards.
Plastics application anchors the largest installed base. Solvents application shows the steepest expansion trajectory as battery chemistry requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between EU bio-based mandates and China's coal-to-chemicals cost structure is fragmenting production geography. European producers face compliance premiums under REACH and EU Green Deal frameworks. Asian operators exploit feedstock cost advantages through integrated petrochemical complexes.
China
Coal gasification economics anchor BDO derivative supply for tetrahydrofuran and gamma-butyrolactone manufacturers. MEE emissions standards tighten on coal-based process operators, forcing selective capacity upgrades. Ningbo and Shanghai host integrated refinery-petrochemical complexes where SINOPEC compounds feedstock cost advantages.
Germany
Engineering plastics demand from Stuttgart and Munich automotive clusters pulls polybutylene terephthalate consumption upward. ECHA REACH registration requirements govern bio-based derivative dossiers under EU chemical safety frameworks. BASF SE's Ludwigshafen Verbund site sustains captive tetrahydrofuran supply for European customers.
United States
Battery binder applications for electric vehicle cathodes consume polyvinylidene fluoride precursors derived from BDO feedstock. EPA Toxic Substances Control Act triggers pre-manufacture notifications for bio-based tetrahydrofuran entrants. Texas and Louisiana Gulf Coast petrochemical corridors concentrate propylene oxide-based BDO route development.
Japan
Lithium-ion cathode manufacturing in South Korea and Japan drives specialty solvent demand for gamma-butyrolactone pharmaceutical applications. METI industrial policy supports process efficiency improvements in hydrogenation reactor engineering. Kurosaki operations anchor Asia-Pacific gamma-butyrolactone capacity for regional pharmaceutical formulation.
India
Underpenetrated domestic gamma-butyrolactone production creates white space for CDSCO-regulated pharmaceutical formulation growth. BIS quality certification requirements extend qualification timelines for polymer-grade purity specifications. Maharashtra and Gujarat specialty chemical corridors attract investment serving textile and pharmaceutical end-use clusters.
1,4 Butanediol Derivatives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and renewable feedstock pathways. The vendor base stratifies between legacy acetylene-chemistry operators and propylene oxide-based challengers achieving superior carbon efficiency. Three archetypes dominate: integrated petrochemical majors with captive BDO supply, specialty chemical distributors with REACH compliance expertise, and renewable process developers securing EU Green Deal funding. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure long-term offtake contracts.
Within the integrated petrochemical tier, BASF SE and SINOPEC exemplify divergent feedstock strategies. BASF SE anchors European engineering plastics supply through its Ludwigshafen Verbund integration. SINOPEC represents coal-to-chemicals economics through Ningbo and Shanghai refinery integration. Mitsubishi Chemical Group Corporation occupies the Asia-Pacific specialist position with Kurosaki-based gamma-butyrolactone capacity.
| Leading Market Players |
|---|
| BASF SE |
| DCC |
| Mitsubishi Chemical Group Corporation |
| LyondellBasell Industries Holdings B.V. |
| Evonik Industries AG |
| Ashland Global Holdings Inc. |
| SINOPEC |
| Sipchem Company |
| Genomatica, Inc. |
| Others |
Value Network & Pricing Analysis
German automotive OEM procurement clusters anchor pricing power through unbundled carbon footprint verification contracts, forcing feedstock pathway transparency premiums into contract structures for polybutylene terephthalate and renewable tetrahydrofuran grades.
Pricing Analysis
Distributor margin compression runs through European gamma-butyrolactone channels as REACH bio-based quotas force inventory segregation costs onto specialty chemical distributors in Rotterdam and Hamburg. Three-tier pricing structure across renewable-certified, polymer-grade, and industrial-grade specifications separates pharmaceutical excipient premiums from solvent commodity benchmarks. Cost compression in coal-based tetrahydrofuran is intensifying as Chinese producers face MEE emissions upgrade requirements. Battery binder cathode material suppliers exhibit lowest price sensitivity due to 99.95 weight percent purity qualification barriers.
Supply Chain Analysis
Refurbishment flows for hydrogenation reactor catalysts concentrate servicing expertise with legacy acetylene-chemistry operators in Germany and Japan, constraining new entrant process design capabilities. Feedstock supply draws from coal gasification corridors in Ningbo and Shanghai, propylene oxide routes along the Texas and Louisiana Gulf Coast, and emerging furfural hydrogenation pilots in the Netherlands and Germany. Single-source vulnerability sits with specialized hydrogenation reactor engineering talent pools. Distribution runs through stainless-steel bulk liquid logistics for tetrahydrofuran and nitrogen-blanketed solid resin handling for polybutylene terephthalate automotive grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal funding frameworks compound market demand for renewable process routes, with ECHA REACH registration requirements tightening substance volume tracking obligations that redirect investment toward bio-based tetrahydrofuran and gamma-butyrolactone certification.
For Market Incumbents: Deploy captive BDO integration as the primary defensive lever. BASF SE's Ludwigshafen Verbund model demonstrates how upstream control over tetrahydrofuran supply secures European engineering plastics offtake against propylene oxide-based challengers. Capacity addition in coal-to-chemicals corridors faces MEE emissions headwinds, favoring incumbent repositioning toward renewable feedstock pathways with EU innovation grant qualification. For New Entrants and Emerging Players: Digital qualification platforms for polymer-grade purity certification offer the most penetrable route into battery binder supply chains. Underpenetrated gamma-butyrolactone production in Maharashtra and Gujarat specialty chemical corridors presents white space for CDSCO-regulated pharmaceutical formulation growth. Direct engagement with cathode material suppliers in South Korea and Japan bypasses established distributor channel control. For Investors and Strategic Acquirers: Specialty chemical distributors with REACH compliance expertise are the most active acquirer category in this space, consolidating inventory segregation capabilities for renewable-certified streams. Long-term viability hinges on feedstock pathway certification scheme alignment rather than scale economics alone. Monitor ECHA precursor control list revisions for gamma-butyrolactone as an inflection indicator on pharmaceutical solvent distribution channel restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into BDO Feedstock | SINOPEC's Ningbo refinery integration demonstrates how captive coal gasification supply compounds cost position against naphtha-based competitors. |
| Green Manufacturing Transition | Furfural hydrogenation pilots in the Netherlands qualify for European Commission decarbonization innovation grants under EU Green Deal frameworks. |
| Long-term Supply Agreement | Tier-1 suppliers in Stuttgart establish direct relationships with bio-based BDO derivative producers to secure Scope 3 emissions data for OEM sustainability scorecards. |
| Capacity Expansion | Mitsubishi Chemical Group Corporation's Kurosaki operations anchor Asia-Pacific gamma-butyrolactone capacity for regional pharmaceutical formulation demand. |
| Joint Venture | Coal-to-chemicals partnerships in Shanghai integrate MEE emissions compliance upgrades with tetrahydrofuran expansion for Vietnamese and Indonesian spandex fiber pull. |
Research Methodology
Coverage spans China, Germany, the United States, Japan, and India, with primary inputs from each market triangulated against secondary validation. Plant managers at coal gasification and propylene oxide-based facilities, procurement leads at automotive Tier-1 suppliers in Stuttgart and Munich, distribution channel partners in Rotterdam and Hamburg, and technical R&D directors for hydrogenation reactor engineering provided stakeholder perspectives. Secondary sources include customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed petrochemical majors, and ECHA REACH registration dossiers. Bottom-up capacity and consumption estimates were cross-checked against top-down market sizing across the analysis window.
Rate-of-change decomposition structured the analytical framework, with volume and value outputs derived from product type segmentation across tetrahydrofuran, polybutylene terephthalate, and gamma-butyrolactone grades; end-use industry splits across automotive, electronics, pharmaceuticals, and textiles; and regional production hub clustering. CAGRs were synthesized from segment-level growth differentials and feedstock pathway cost evolution assumptions. Industry-specific forecast inputs incorporated spandex fiber capacity buildouts in Vietnam and Indonesia, lithium-ion cathode manufacturing expansion in South Korea and Japan, and EU bio-based mandate compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for propylene oxide-based BDO routes displacing acetylene chemistry would alter the outlook for incumbent cost positions and regional supply concentration. Forecasts reflect assumptions on coal price stability, REACH registration enforcement intensity, and precursor classification stability for gamma-butyrolactone. Practitioners should monitor MEE emissions standard revisions, ECHA substance volume tracking obligations, and OEM sustainability scorecard weighting changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Thallium Acetate Market
Additives
India Feed Additives Market
Additives
Dishwashing Additives Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Polysaccharides and Oligosaccharides Market
Additives
Glacial Acetic Acid Market
Additives
Gluconic Acid and Derivatives Market
Additives
Potting Mix Additives Market
Additives
Global Hindered Amine Light Stabilizers Market
Additives
Global Matting Agents Market
Additives
Nucleating and Clarifying Agents Market
Additives
Asia-Pacific Water Enhancer Market
Additives
Anti-Foaming Agent Market
Additives
Sodium Benzoate Market
Additives
Global Anti-Fog Additives Market
Additives
Low VOC Coating Additives Market