
 Specialty Elastomer Market | 2026-2036
Specialty Elastomer Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Elastomer Market Outlook
German chemical producers is restructuring specialty elastomer supply chains to secure captive access to silicone intermediates and polyurethane precursors. BASF SE leverages its Ludwigshafen integrated site to sustain differentiated thermoplastic elastomer grades for automotive OEMs. DuPont de Nemours, Inc. anchors its position through fluoropolymer elastomer technology leadership in semiconductor fabrication seals. Dow competes on scale in North American silicone elastomer production, while Wacker Chemie AG specializes in high-purity silicone formulations for medical and electronics applications.
Specialty elastomers are high-performance polymeric materials engineered to deliver elastic recovery under repeated stress cycles, typically operating across temperature ranges from minus sixty degrees Celsius to over two hundred degrees Celsius depending on backbone chemistry and crosslink density. These materials combine rubber-like elasticity with thermoplastic processability or thermoset durability to serve critical sealing, damping, and insulation functions in harsh industrial environments. Thermoplastic elastomers command the largest volume share due to injection molding compatibility and recyclability advantages in automotive lightweighting programs. Silicone elastomers generate premium margin pools from medical device and electronics applications where biocompatibility and dielectric stability justify higher formulation costs. Polyurethane elastomers occupy the fastest-expanding niche in industrial roller and mining equipment segments demanding abrasion resistance.
EPA regulations on volatile organic compound emissions from sealant and coating applications are redirecting formulation investments toward solvent-free curing systems in the United States. REACH substance restrictions and the EU F-Gas Regulation are eliminating certain fluoroelastomer precursors, forcing reformulation of high-temperature automotive gaskets and aerospace seals. OSHA workplace exposure limits for isocyanates in polyurethane production are tightening manufacturing protocols across North American and European facilities. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and secure dual-certified raw material positions.
Market Dynamics
Automotive OEM thermal management specifications are compressing silicone elastomer qualification timelines while tightening performance thresholds for under-the-hood applications, forcing reformulation cycles that strain R&D bandwidth across the supplier base.
Growth Catalysts
- EU F-Gas Regulation phase-down:The elimination of certain fluoroelastomer precursors under REACH and F-Gas rules is redirecting automotive gasket demand toward high-performance silicone and hydrogenated nitrile alternatives that meet retained heat resistance requirements.
- Medical device biocompatibility mandates:ISO 10993 and USP Class VI certification requirements for implantable and diagnostic equipment are expanding addressable demand for platinum-cured silicone formulations in cardiology and neurology applications.
- Semiconductor fabrication expansion:Advanced node chip manufacturing in Taiwan, South Korea, and the United States is scaling demand for fluoropolymer elastomer seals and O-rings capable of withstanding aggressive plasma chemistries at sub-10 nanometer production.
Market Restraints
- Silicone intermediate supply concentration:Methyl chloride and silicon metal feedstock production clusters in China's Xinjiang and Inner Mongolia regions create geographic vulnerability for Western formulators lacking backward integration into upstream silicones.
- Isocyanate cost volatility:MDI and TDI price swings tied to benzene derivative markets compress polyurethane elastomer margin stability, particularly for industrial roller and mining equipment segments with limited pricing power.
- High-temperature thermoplastic limitations:TPV and TPE compounds face ceiling temperature constraints around 150 degrees Celsius that exclude them from turbocharger hoses and exhaust system mounts, ceding volume to thermoset alternatives.
Strategic Opportunities
- India automotive component localization:PLI scheme incentives for advanced chemistry cell and electric vehicle manufacturing are creating captive demand for domestic thermoplastic elastomer compounding capacity to serve Maruti Suzuki and Tata Motors supply chains.
- Green hydrogen infrastructure seals:Electrolyzer stack and compression equipment specifications for 700 bar hydrogen service represent an emerging application vector for specialized perfluoroelastomer formulations with permeation resistance.
- Digital twin-enabled formulation:Molecular simulation platforms are compressing silicone compound development cycles by predicting crosslink density and compression set performance before physical prototyping, reducing qualification costs.
Industry Challenges
- Dual-certified raw material procurement:Diverging EPA VOC limits and REACH substance restrictions require formulators to maintain parallel inventory positions for US and European automotive customers, inflating working capital requirements.
- Platinum catalyst supply security:Concentrated South African and Russian sourcing for platinum group metals used in addition-cure silicone systems exposes medical and electronics compounders to sanctions-related disruption and price spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Elastomer Market |
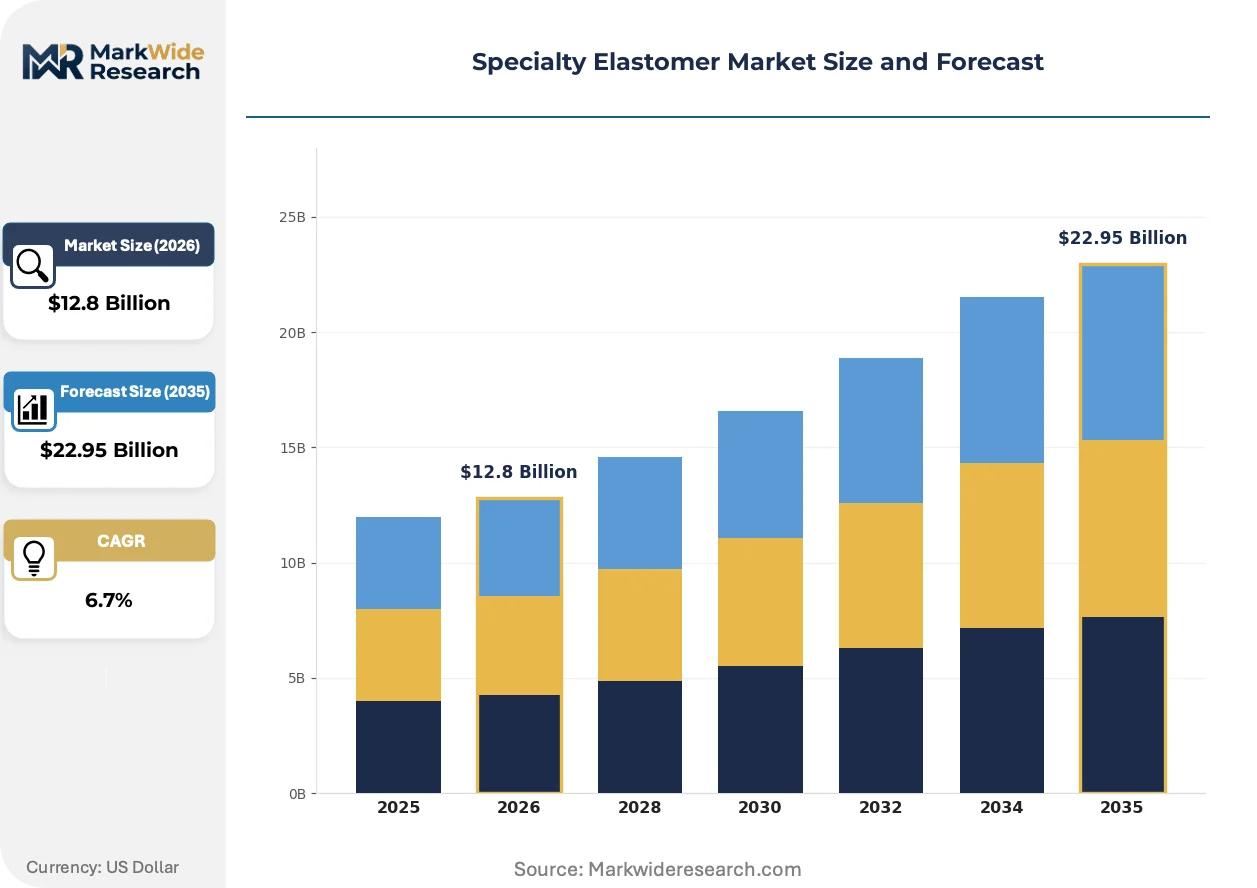
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Thermoplastic Elastomers, Silicone Elastomers, Polyurethane Elastomers, Butyl Elastomers Application: Automotive, Construction, Consumer Goods, Electronics End User: OEMs, Tier-1 Suppliers, Manufacturers, Distributors Form: Sheet, Foam, Sealant, Coating |
| Companies Covered | BASF SE, DuPont de Nemours, Inc., Dow, Wacker Chemie AG, Arkema, AGC Inc., Mitsui Chemicals, Inc., LANXESS AG, Avient Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Elastomer Market Strategic Shifts
Formulation science and manufacturing process control are converging to enable property gradients within single molded components, collapsing the traditional trade-off between injection molding efficiency and thermoset performance extremes.
Liquid silicone rubber injection molding is modularizing production economics for medical device manufacturers. Complex multi-material components with integrated rigid thermoplastic substrates and soft silicone seals now form in single-tool cycles. Device OEMs in Minnesota and Massachusetts are adopting these hybrid platforms for respiratory masks and surgical instruments. The technology is modularizing supplier relationships by collapsing tiered component sourcing into integrated single-source contracts.
REACH substance restrictions and the EU F-Gas Regulation are eliminating perfluorooctanoic acid-related precursors from fluoroelastomer supply chains. German and French automotive suppliers face reformulation deadlines for high-temperature gaskets previously dependent on legacy cure systems. Aerospace seal manufacturers in the United Kingdom and Italy are accelerating qualification of alternative peroxide-cure fluoropolymer compounds to maintain export certification.
Automotive OEMs are consolidating approved supplier lists for under-the-hood elastomer components. Tier-one suppliers now face technical audit requirements spanning material traceability, carbon footprint disclosure, and recycled content verification. This concentration is visible most acutely in German premium vehicle programs where BMW and Mercedes-Benz procurement teams enforce unified sustainability scorecards across silicone hose and damping component vendors.
Specialty Elastomer Market Segmentation
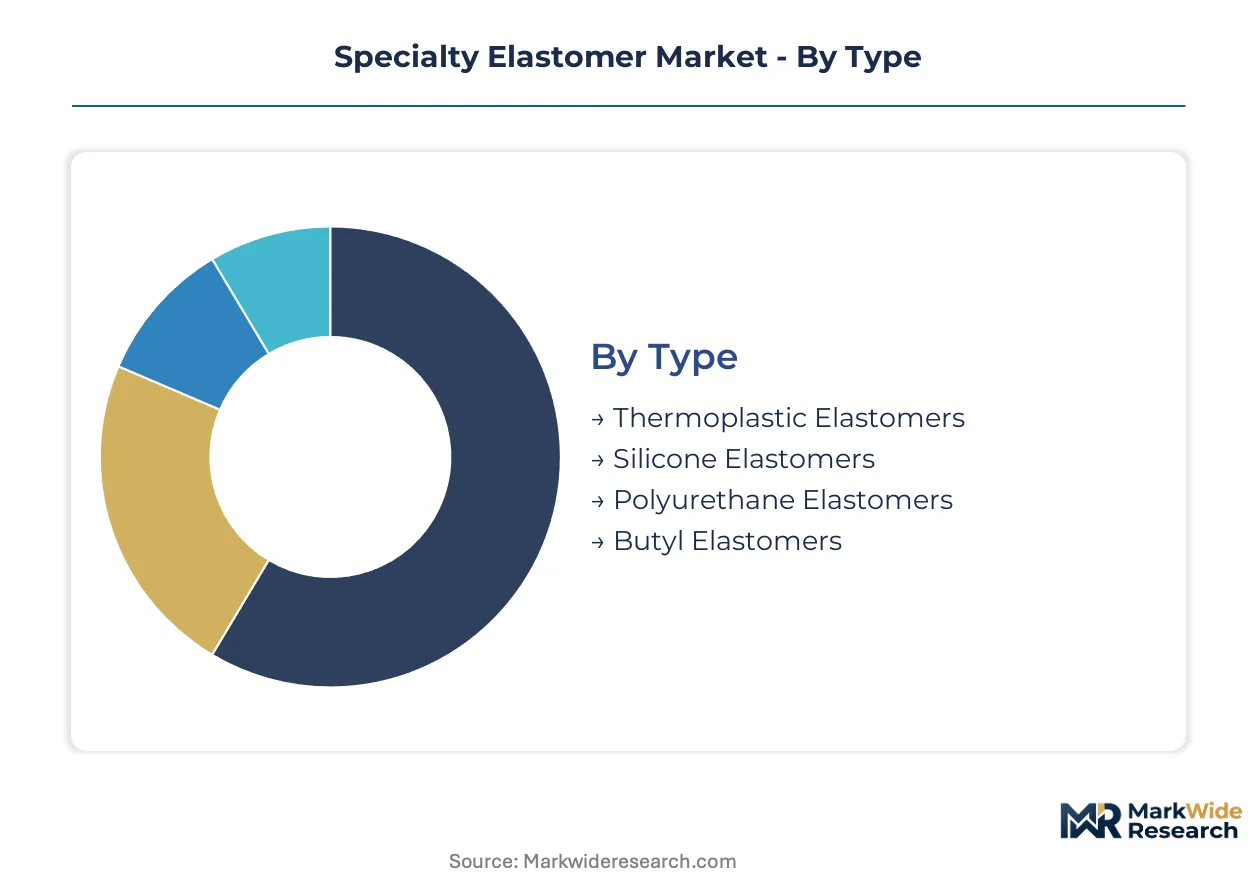
Specialty elastomer procurement decisions hinge on certification pathways that vary sharply by chemistry and end-use exposure. Formulators must map segment-specific compliance burdens against performance thresholds to avoid stranded inventory across diverging regulatory jurisdictions.
Type:
REACH substance restrictions and FDA biocompatibility mandates impose divergent certification timelines across elastomer chemistries, with thermoset grades facing longer qualification cycles than thermoplastic alternatives.
- Thermoplastic Elastomers:Injection-moldable block copolymers and dynamically vulcanized alloys process without crosslinking, enabling recyclability in automotive lightweighting programs. German and US automotive OEMs concentrate demand for TPV grades in air intake systems and underbody shields where EPA fuel economy standards drive material substitution.
- Silicone Elastomers:Platinum-cured and peroxide-cure polysiloxane networks deliver biocompatibility and dielectric stability across minus sixty to two hundred plus degrees Celsius. ISO 10993 and USP Class VI certifications position these materials in Minnesota and Massachusetts medical device clusters, with additional demand from Taiwan semiconductor fabrication seals.
- Polyurethane Elastomers:MDI and TDI-based segmented polymers dominate industrial roller and mining equipment segments.
- Butyl Elastomers:Isobutylene-isoprene copolymers serve tire inner liners and pharmaceutical stoppers with low gas permeability.
Thermoplastic Elastomers sits at the top of the volume ranking, with Polyurethane Elastomers climbing the fastest.
Application:
Cost tier stratification separates specification-grade automotive formulations from commodity construction sealants, with electronics applications commanding premium pricing for cleanroom-compatible grades.
- Automotive:Under-the-hood thermal management specifications from BMW and Mercedes-Benz procurement teams enforce unified sustainability scorecards across silicone hose and damping component vendors. REACH and EPA VOC limits require dual-certified inventory positions for US and European customers.
- Construction:Solvent-free curing systems redirect formulation investments as EPA regulations tighten volatile organic compound emissions from sealant applications.
- Consumer Goods:Platinum-cured silicones penetrate respiratory masks and surgical instruments through liquid silicone rubber hybrid molding platforms.
- Electronics:High-purity formulations for medical and electronics applications justify elevated formulation costs through dielectric stability requirements.
Automotive captures the largest revenue pool, with Electronics expanding most quickly on semiconductor fabrication scaling.
End User:
Procurement authority concentrates with OEMs in premium automotive segments, while Tier-1 suppliers face compressed qualification timelines and technical audit requirements spanning material traceability and carbon footprint disclosure.
- OEMs:BMW, Mercedes-Benz, Maruti Suzuki, and Tata Motors consolidate approved supplier lists and enforce sustainability scorecards across silicone hose and damping component vendors.
- Tier-1 Suppliers:Technical audit requirements now span material traceability, carbon footprint disclosure, and recycled content verification.
- Manufacturers:Medical device OEMs in Minnesota and Massachusetts adopt hybrid liquid silicone rubber platforms.
- Distributors:Parallel inventory positions for US and European automotive customers inflate working capital requirements.
OEMs sit at the top of the volume ranking, with Tier-1 Suppliers climbing the fastest on consolidation pressures.
Form:
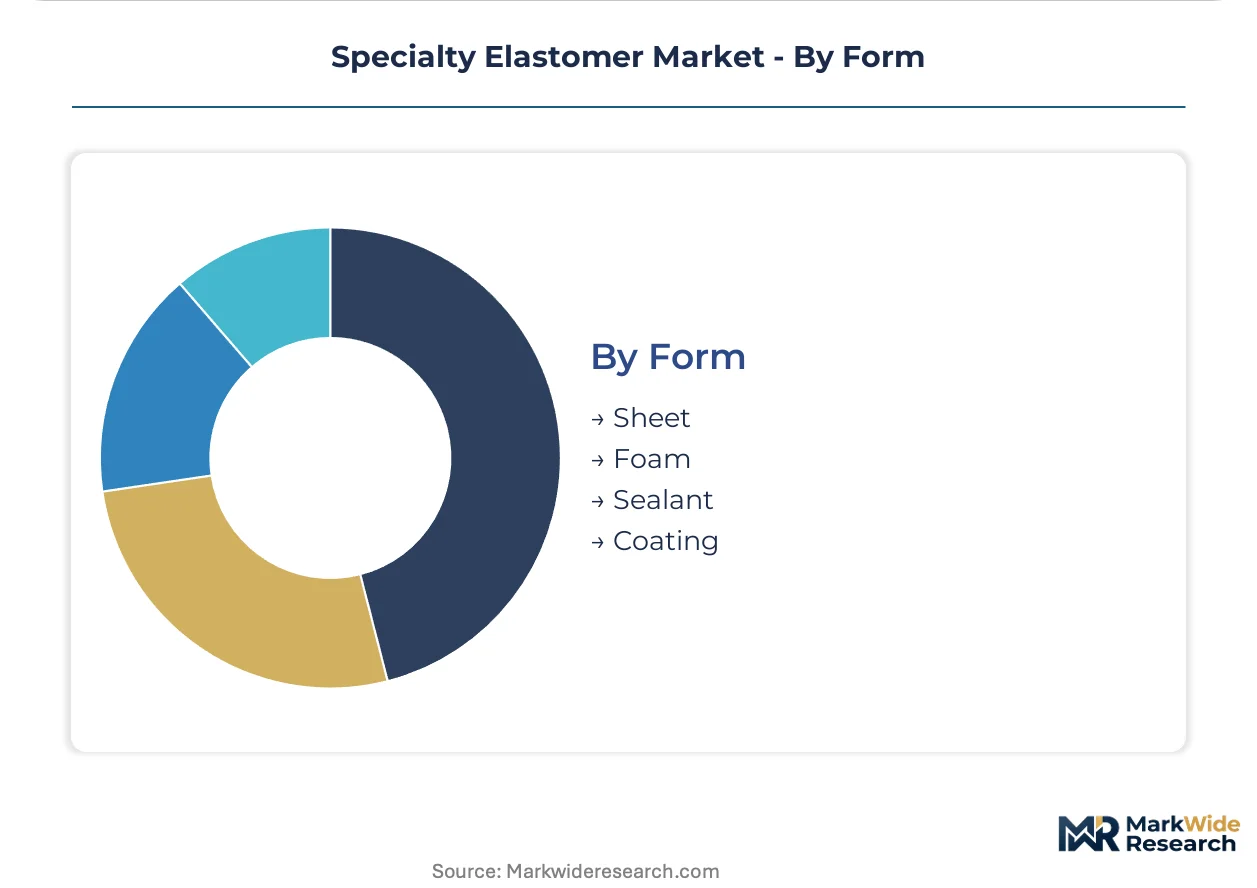
Processing method determines margin structure, with injection-moldable forms capturing efficiency premiums versus labor-intensive coating applications.
- Sheet:Calendered and extruded rolls serve gasket and diaphragm fabrication with thickness tolerances critical for aerospace seal qualification.
- Foam:Cellular silicones and polyurethanes provide compression set resistance in cushioning and insulation applications.
- Sealant:Solvent-free curing systems redirect formulation investments under EPA VOC regulations.
- Coating:Spray and dip applications face elevated compliance burdens under OSHA workplace exposure limits for isocyanates.
Sheet sits at the top of the volume ranking, with Foam climbing the fastest on medical device cushioning demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping specialty elastomer production geography as formulators seek cost-of-compliance advantages. REACH substance restrictions and EPA VOC limits create divergent certification burdens that favor integrated producers in jurisdictions with aligned upstream chemical infrastructure.
United States
Semiconductor fabrication expansion in Arizona and Texas scales demand for fluoropolymer elastomer seals. EPA regulations on volatile organic compound emissions redirect formulation investments toward solvent-free curing systems. Minnesota and Massachusetts medical device clusters adopt liquid silicone rubber hybrid molding platforms for respiratory masks and surgical instruments.
Germany
BMW and Mercedes-Benz procurement teams enforce unified sustainability scorecards across silicone hose and damping component vendors. EU F-Gas Regulation phase-down eliminates certain fluoroelastomer precursors, redirecting automotive gasket demand toward high-performance silicone alternatives. The Ludwigshafen integrated chemical site sustains differentiated thermoplastic elastomer grades for automotive OEMs.
China
Automotive OEM thermal management specifications compress silicone elastomer qualification timelines. Methyl chloride and silicon metal feedstock production clusters in Xinjiang and Inner Mongolia create geographic vulnerability for Western formulators lacking backward integration. Taiwan semiconductor fabrication seals generate parallel demand for high-purity silicone formulations.
India
PLI scheme incentives for advanced chemistry cell and electric vehicle manufacturing create captive demand for domestic thermoplastic elastomer compounding capacity. Maruti Suzuki and Tata Motors supply chains localize procurement for under-the-hood components. The country's national automotive regulator tightens emission standards that drive material substitution in gasket and sealing applications.
Japan
Advanced node chip manufacturing scales demand for fluoropolymer elastomer seals capable of withstanding aggressive plasma chemistries. METI industrial policy supports domestic silicone intermediate production to reduce import dependency. Osaka and Nagoya industrial corridors concentrate precision molding capacity for electronics-grade elastomer components.
Specialty Elastomer Market Competitive Environment
German producers anchor one tier; North American specialists hold process technology leadership in medical-grade silicones. The vendor base organizes around three strategic archetypes: integrated chemical conglomerates with captive silicone intermediates, mid-scale compounders serving regional automotive supply chains, and niche formulators certified for implantable medical devices. Competitive moves concentrate on backward integration into upstream silicones and molecular simulation platforms that compress compound development cycles.
Among German-based chemical conglomerates, BASF SE and LANXESS AG exemplify the integrated archetype with captive access to polyurethane precursors. Dow and DuPont de Nemours, Inc. occupy positions within the North American tier, with the latter representing fluoropolymer elastomer technology leadership in semiconductor fabrication applications. Wacker Chemie AG sits within the high-purity specialization segment, serving medical and electronics end-uses where biocompatibility certification commands premium positioning.
| Leading Market Players |
|---|
| BASF SE |
| DuPont de Nemours, Inc. |
| Dow |
| Wacker Chemie AG |
| Arkema |
| AGC Inc. |
| Mitsui Chemicals, Inc. |
| LANXESS AG |
| Avient Corporation |
| Others |
Value Chain & Pricing Dynamics
Silicone intermediate feedstock costs cascade through three distinct pricing tiers, with methyl chloride and silicon metal volatility from China's Xinjiang and Inner Mongolia clusters compressing margins for non-integrated Western compounders serving medical and automotive OEMs.
Pricing Analysis
Distributor markups widen for small-batch medical-grade silicone compounds versus direct-to-OEM contract pricing for automotive TPV volumes. Three-tier pricing structure across platinum-cured premium grades, standard peroxide-cure formulations, and economy TPE alternatives reflects certification burden and volume scale. Cost compression in standard silicone grades is intensifying because of concentrated Chinese upstream supply and European energy costs. Tier-1 automotive suppliers exhibit highest price sensitivity due to consolidated procurement power, while implantable medical device OEMs accept premium positioning for ISO 10993-certified formulations.
Supply Chain Analysis
ISO 10993 and REACH certification timelines gate supply relationships, with qualified compounders in Germany, the United States, and Japan commanding premium positioning over uncertified Asian competitors. Raw material dependencies center on South African platinum group metals for addition-cure silicones, Chinese silicon metal and methyl chloride for silicone intermediates, and benzene-derived MDI/TDI for polyurethane systems. Single-source vulnerability concentrates in platinum catalyst supply chains exposed to sanctions-related disruption. Distribution runs through authorized distributor networks for medical and electronics grades, with direct mill relationships dominating high-volume automotive compounds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialty elastomer market functions as a stable compounder anchored by irreplaceable sealing and thermal management functions in automotive and medical devices, with regulatory certification barriers protecting incumbent returns.
For Market Incumbents: Anticipate margin compression from Chinese silicone intermediate overcapacity and accelerate backward integration into upstream silicones or captive platinum group metal sourcing. BASF SE and Wacker Chemie AG demonstrate the defensive value of Ludwigshafen and Burghausen integrated sites. Prioritize dual REACH-EPA certification investments to defend automotive supplier positioning against emerging Indian compounders. For New Entrants and Emerging Players: Domestic Indian OEMs present the most penetrable buyer archetype, with PLI scheme incentives creating captive demand for localized TPV compounding capacity to serve Maruti Suzuki and Tata Motors. Green hydrogen infrastructure seals at 700 bar service specifications offer a second white-space vector with limited incumbent qualification. Pursue joint development agreements with electrolyzer stack manufacturers rather than direct OEM sales to bypass entrenched supplier lists. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale compounders lack backward integration and face simultaneous REACH reformulation and EPA VOC compliance costs. Long-term viability favors specialists with captive silicone intermediate production or implantable medical device certification moats. Monitor platinum group metal price spikes and South African supply disruptions as signals for margin inflection across addition-cure silicone compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Intermediates | BASF SE's Ludwigshafen site secures captive methyl chloride supply for automotive TPV grades. |
| Dual Certification Investment | REACH and EPA VOC alignment protects inventory positions across BMW and Mercedes-Benz supply chains. |
| Green Hydrogen Seal Qualification | Perfluoroelastomer development for 700 bar electrolyzer service opens emerging infrastructure demand. |
| Digital Twin Formulation Platform | Molecular simulation compresses silicone compound development cycles before physical prototyping investment. |
| Indian Domestic Compounding Capacity | PLI scheme incentives support localized TPV supply for Maruti Suzuki and Tata Motors procurement localization. |
Study Parameters
Coverage spans Germany, the United States, China, India, and Japan, with primary inputs from each market cluster combining interviews with silicone compound R&D directors, automotive Tier-1 procurement managers, medical device quality assurance leads, and specialty chemical distribution channel partners. Secondary validation draws from ECHA REACH substance databases, EPA VOC regulation filings, SEC 10-K disclosures from listed chemical producers, and customs trade data for silicone intermediate flows. Bottom-up segment sizing triangulates against top-down chemical industry association aggregates.
Rate-of-change decomposition separates volume growth from mix-shift and pricing trajectory across the projection horizon. Segmentation dimensions modeled include elastomer chemistry type, end-use industry vertical, certification tier, and regional production hub clustering. CAGRs derive from regression analysis against automotive production forecasts, semiconductor fabrication capacity buildouts, and medical device approval trajectories. Industry-specific inputs incorporate REACH substance restriction timelines and EPA VOC phase-down schedules.
Underlying measurement precision varies by segment; medical device and semiconductor fabrication grades carry tighter precision than construction sealant commodities due to disclosed procurement contract visibility. Forecasts reflect assumptions around regulatory implementation pace, platinum group metal supply continuity, and Chinese silicone intermediate export policy. Deviation in EU F-Gas Regulation enforcement timing or South African platinum mining output would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
South America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Industrial PU Elastomer Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
Europe Single-Ply Membrane Market
Elastomeric Membrane
Global Acrylic Elastomers Market
Elastomeric Membrane
Elastomeric Foam Insulation Market
Elastomeric Membrane
Global Thermoplastic Elastomers (TPE) Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
Butyl Elastomers Market
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Asia-Pacific Thermoplastic Elastomer (TPE) Market