
 Bio-Based Elastomers Market | 2026-2036
Bio-Based Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Elastomers Market Intelligence
High-purity specification tiers for medical-grade and food-contact bio-based elastomers is redrawing competitive boundaries among compounders. BASF SE leverages its backward integration into renewable feedstock certification to sustain premium positioning. Dow anchors North American supply through its ethylene-propylene terpolymer platforms with verified bio-carbon content. Kuraray Co., Ltd. specializes in liquid silicone rubber grades that meet JIS medical device standards, occupying a defensible niche in Asian healthcare procurement.
Bio-based elastomers comprise polymeric materials with at least partially renewable carbon content, typically derived from plant oils, sugars, or lignocellulosic biomass, exhibiting reversible elastic deformation with tensile recovery exceeding 80 percent and Shore A hardness ranging from 10 to 95. These materials serve as drop-in replacements for petroleum-derived rubbers in sealing, damping, and flexible containment applications where lifecycle carbon metrics influence supplier qualification. Thermoplastic elastomers lead volume consumption due to injection molding compatibility and end-of-life recyclability, while liquid silicone rubber represents the fastest-expanding margin pool driven by healthcare and personal care formulation demand. Polyurethane bio-based variants concentrate in coatings and adhesives where isocyanate-free curing systems command formulation premiums from automotive and consumer goods OEMs.
REACH registration requirements and the EU Green Deal sustainable product criteria are tightening disclosure obligations for bio-carbon content verification and endocrine disruptor screening across European compounder supply chains. The EPA's renewable fuel standard pathways and USDA BioPreferred program labeling rules shape market access conditions for U.S.-based producers seeking federal procurement eligibility. FDA 21 CFR 177.2600 compliance for repeated-use rubber articles remains the threshold standard for healthcare and food-contact applications, filtering out uncertified entrants. Stakeholders must monitor evolving polymer-specific carbon accounting methodologies and regulator alignment between the EU CSRD corporate sustainability reporting mandate and emerging SEC climate disclosure rules to anticipate qualification cost trajectories.
Market Dynamics
Automotive OEM Scope 3 decarbonization mandates are forcing Tier-1 seal and gasket suppliers to certify renewable carbon content across compounder supply chains, compressing qualification timelines and favoring backward-integrated feedstock producers.
Growth Catalysts
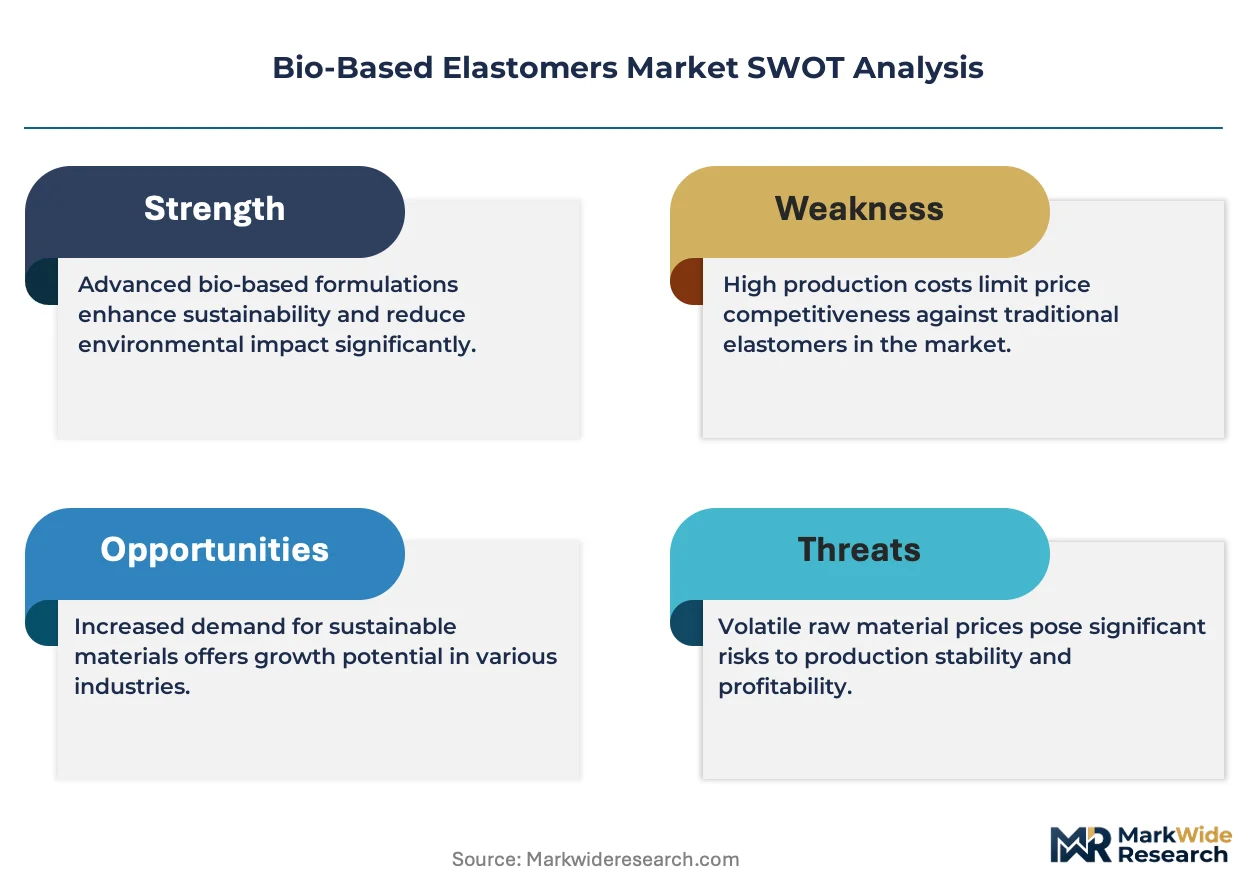
- EU Green Deal sustainable product criteria:Mandatory bio-carbon disclosure under REACH registration timelines accelerates compounder investment in certified renewable feedstock sourcing.
- Injection molding compatibility:Thermoplastic elastomer processability enables automotive and consumer goods manufacturers to substitute petroleum-derived rubbers without retooling capital.
- Germany:Concentrated compounder demand in Baden-Württemberg and Bavaria creates localized pull for high-purity medical-grade and food-contact specification tiers.
Market Restraints
- Plant oil feedstock price volatility:Castor oil and soybean oil price swings compress compounder margins during crude oil price dislocation events.
- Specialized polymerization catalyst scarcity:Limited European suppliers of stereospecific metallocene catalysts for bio-polyolefin elastomers create supply concentration risk.
- REACH endocrine disruptor screening:Expanding substance evaluation lists delay new bio-based formulation approvals by 18-36 months.
Strategic Opportunities
- USDA BioPreferred federal procurement:USDA labeling rules unlock Department of Defense and General Services Administration contract eligibility for verified bio-carbon content elastomers.
- Liquid silicone rubber-JIS convergence:Medical device manufacturers in Japan are qualifying bio-based liquid silicone rubber grades for implantable and diagnostic applications.
- Isocyanate-free polyurethane curing:Waterborne and UV-curable bio-polyurethane systems command formulation premiums in automotive interior coatings and adhesives.
Industry Challenges
- Polymer-specific carbon accounting methodology gaps:Misalignment between EU CSRD reporting mandates and emerging SEC climate disclosure rules creates dual compliance cost burdens for multinational compounders.
- Medical-grade certification timeline compression:FDA 21 CFR 177.2600 repeated-use rubber article approvals require 24-48 month validation cycles that strain R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Elastomers Market |
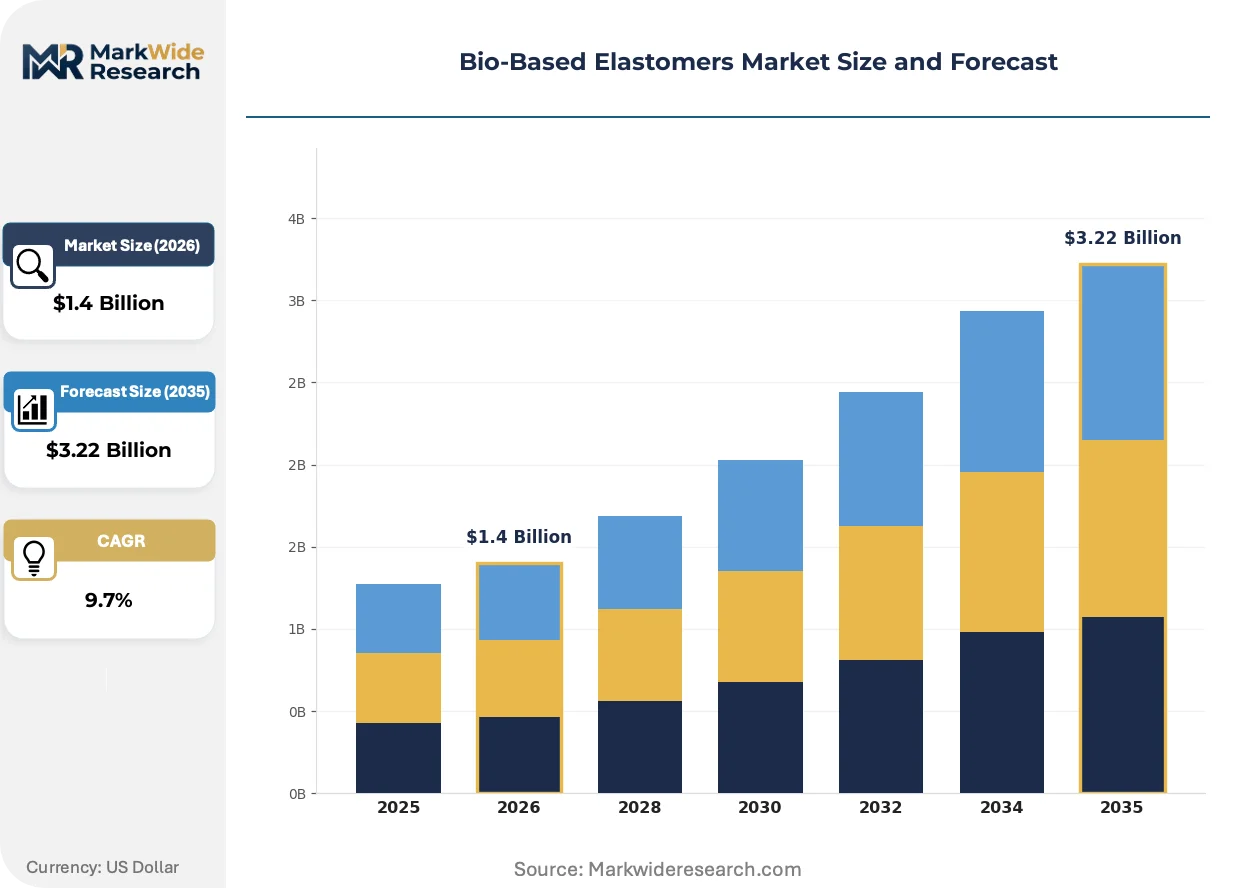
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic Elastomers, Thermosetting Elastomers, Liquid Silicone Rubber, Polyurethane End User: Automotive, Consumer Goods, Healthcare, Personal Care Form: Sheets, Films, Coatings, Adhesives Application: Sealing, Vibration Damping, Gaskets, O-Rings |
| Companies Covered | Dow, BASF SE, Lanxess AG, Asahi Kasei Corporation, Arkema, Huntsman International LLC, Covestro AG, Kuraray Co., Ltd., Trinseo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Elastomers Market Strategic Shifts & Innovations
Feedstock certification platforms and polymerization process intensification are redrawing technical differentiation boundaries among compounders, while regulatory carbon accounting convergence forces simultaneous multi-jurisdiction compliance investment.
Lignocellulosic-derived thermoplastic elastomers is fragmenting the mid-performance sealing segment previously dominated by petroleum-based styrenic block copolymers. Automotive weatherstrip and underhood hose manufacturers in Germany and France are piloting these grades at 10,000-ton annual offtake scales. The technology is fragmenting supplier consolidation by enabling regional biomass processors to forward-integrate into compounder feedstock supply.
REACH polymer-specific registration requirements are tightening substance identity disclosure for bio-based content verification across European compounder supply chains. ECHA evaluation deadlines now require renewable carbon mass balance documentation from feedstock origin through final formulation. Medical-grade and food-contact elastomer producers face the steepest compliance cost trajectories as endocrine disruptor screening expands to cover processing aids and stabilizer packages.
Automotive OEM direct material qualification is displacing traditional Tier-1 compounder-mediated specification setting for bio-based seal and gasket procurement. BMW, Mercedes-Benz, and Volkswagen Group sustainability procurement teams now mandate renewable carbon thresholds in supplier scorecards, bypassing historical rubber compounder formulation control. This pattern concentrates most visibly in German and French OEM engineering centers where Scope 3 target deadlines are tightest.
Bio-Based Elastomers Market Segmentation
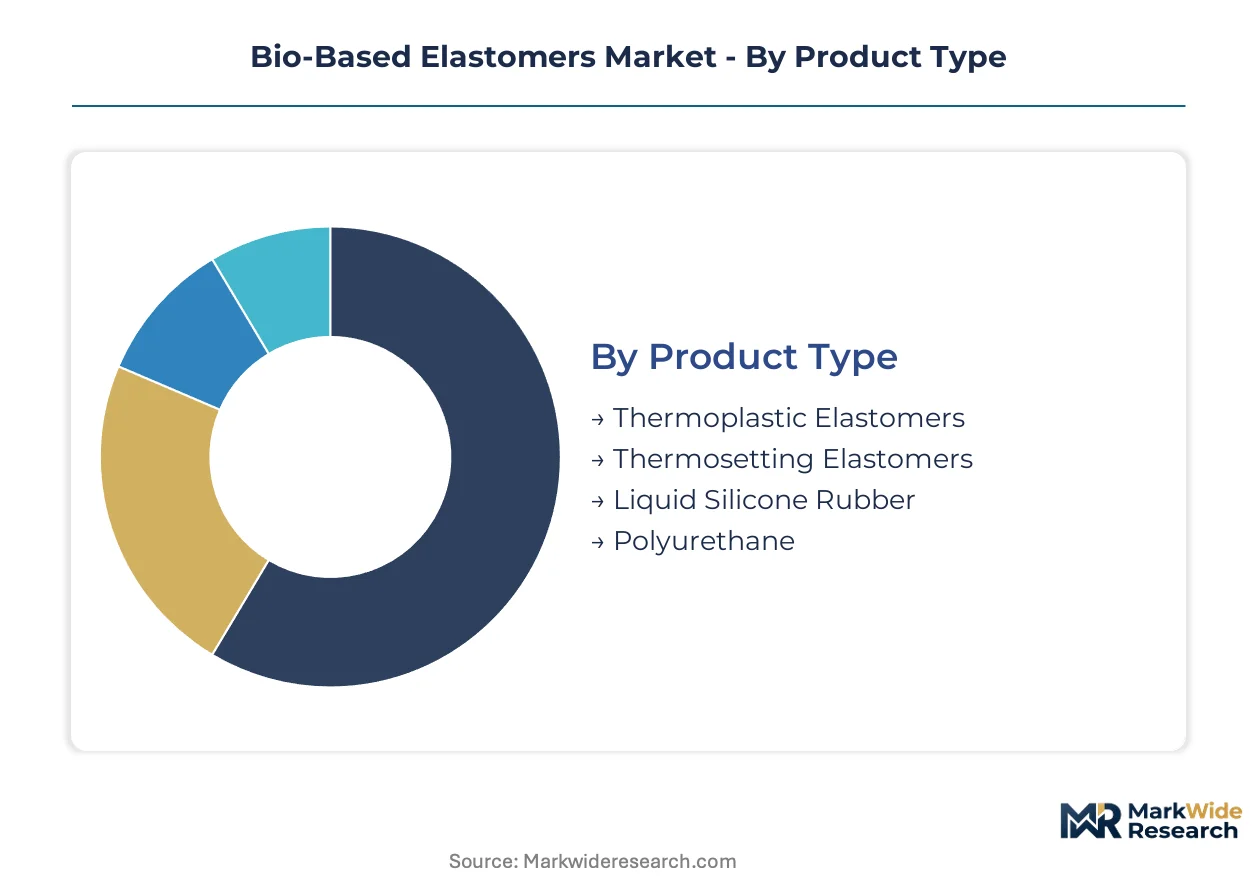
Segmentation in bio-based elastomers tracks how regulatory carbon accounting, medical certification tiers, and automotive OEM qualification pathways split demand across technically distinct material categories. Each dimension carries its own compliance cost structure and supplier qualification timeline.
Product Type:
REACH substance identity disclosure and FDA 21 CFR 177.2600 compliance timelines create divergent cost-to-qualify profiles across polymer chemistries, concentrating procurement power among backward-integrated feedstock producers.
- Thermoplastic Elastomers:Injection-moldable grades with verified bio-carbon mass balance dominate automotive weatherstrip and consumer goods casing production. German compounders in Baden-Württemberg process the highest European volumes for BMW and Mercedes-Benz seal programs under compressed Scope 3 deadlines.
- Liquid Silicone Rubber:Platinum-catalyzed two-part systems meeting JIS medical device standards command formulation premiums in diagnostic and implantable applications. Japanese healthcare OEMs are qualifying these grades fastest among Asian procurement centers.
- Thermosetting Elastomers:Crosslinked natural rubber and bio-synthetic blends serve heavy-duty damping and industrial belting where heat resistance exceeds TPU limits.
- Polyurethane:Isocyanate-free waterborne and UV-curable variants concentrate in automotive interior coatings and pressure-sensitive adhesives.
Thermoplastic elastomers handle the majority of throughput; liquid silicone rubber is climbing the fastest on share as medical-grade certification timelines compress.
End User:
Customer procurement maturity determines whether sustainability mandates translate into enforceable renewable carbon thresholds or remain aspirational scorecard metrics.
- Automotive:OEM Scope 3 decarbonization mandates now bypass Tier-1 compounders, with BMW, Mercedes-Benz, and Volkswagen Group engineering centers mandating direct feedstock certification. REACH registration documentation and ECHA evaluation deadlines filter supplier pools most aggressively in German and French engineering clusters.
- Healthcare:FDA 21 CFR 177.2600 repeated-use rubber article compliance and EU MDR substance disclosure requirements impose 24-48 month validation cycles. Japanese medical device manufacturers are expanding bio-based liquid silicone rubber qualification for implantable applications under PMDA guidance.
- Consumer Goods:USDA BioPreferred federal procurement eligibility drives Department of Defense and General Services Administration contract access for verified bio-carbon content elastomers.
- Personal Care:Formulation demand for skin-contact grades with endocrine disruptor screening documentation expands fastest among EU Green Deal sustainable product criteria adopters.
Automotive procurement enforces the strictest renewable carbon thresholds; healthcare is expanding most quickly as implantable-grade qualification accelerates.
Form:
Processing technology compatibility and end-of-life recyclability requirements shape form factor selection across application segments.
- Sheets:Calendered and extruded profiles serve gasket and industrial belting markets where die-cutting and fabrication flexibility matter most.
- Films:Thin-gauge blown and cast extrusions concentrate in medical packaging and personal care laminate structures requiring barrier performance.
- Coatings:Waterborne bio-polyurethane systems command automotive interior formulation premiums where VOC reduction and isocyanate-free curing align with OEM sustainability procurement scorecards.
- Adhesives:Pressure-sensitive and structural bonding grades leverage tackifier compatibility with bio-based tackifying resins for tape and label markets.
Sheets generate the highest unit volumes; coatings are gaining share fastest on automotive interior substitution.
Application:
Functional performance requirements and failure mode criticality determine whether bio-based substitutes qualify for safety-critical versus commodity replacement segments.
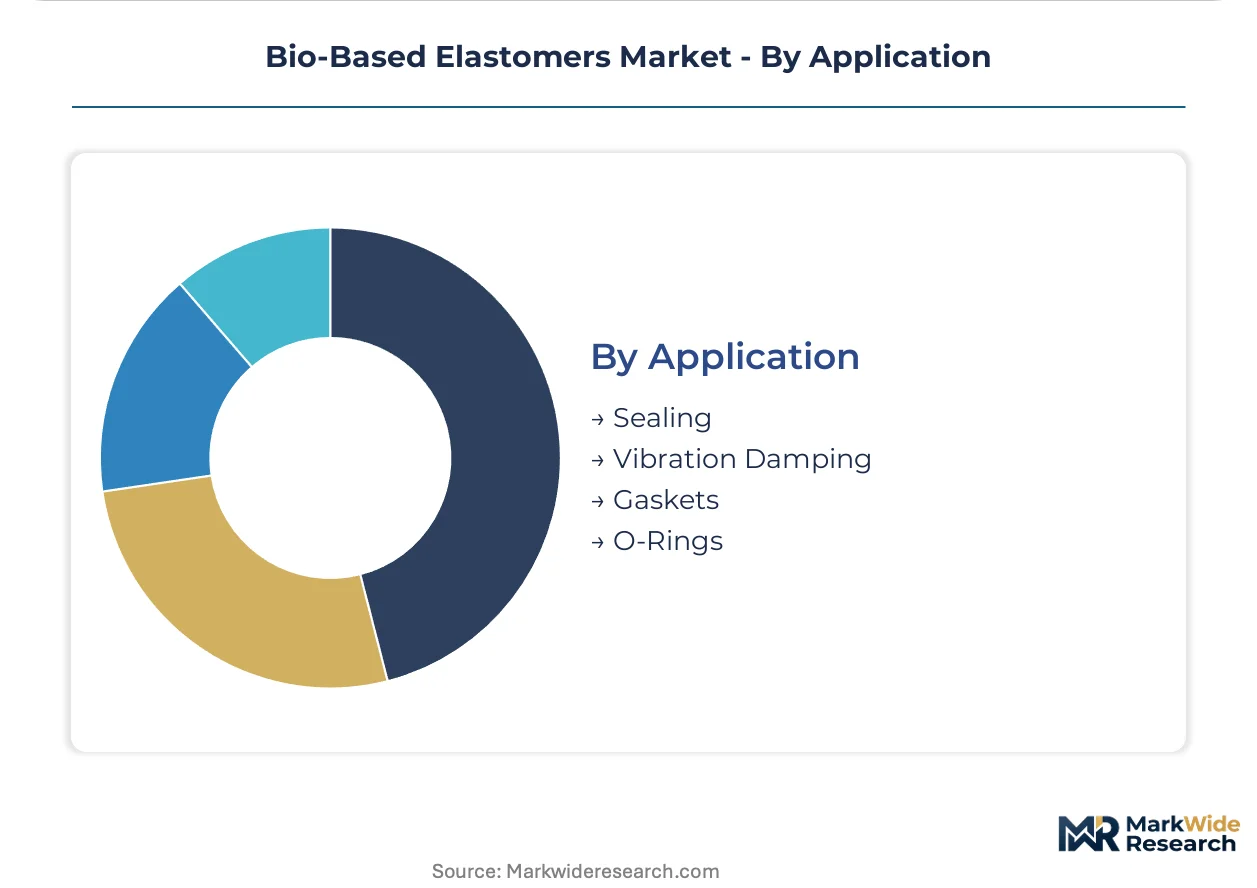
- Sealing:Dynamic and static seal designs for automotive underhood and weatherstrip applications require compression set resistance and fluid compatibility validation. German OEM engineering centers pilot lignocellulosic-derived thermoplastic elastomers at 10,000-ton annual offtake scales.
- Vibration Damping:Engine mount, suspension bushing, and HVAC isolation applications demand loss factor tuning across temperature and frequency ranges.
- Gaskets:Flange and joint sealing for fluid power and process equipment emphasizes chemical resistance and creep relaxation performance.
- O-Rings:Molded circular cross-section seals for hydraulic and pneumatic systems require tight dimensional tolerance control and standard groove compatibility.
Sealing absorbs the largest demand share; vibration damping is expanding most quickly as electrified powertrain NVH requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in bio-based elastomers tilt toward net importing in high-consumption automotive and medical device clusters, while feedstock-rich jurisdictions maintain surplus positions in renewable carbon intermediates.
Germany
Automotive OEM Scope 3 mandates from BMW, Mercedes-Benz, and Volkswagen Group concentrate procurement power in Baden-Württemberg and Bavaria. REACH registration timelines under ECHA enforcement compress supplier qualification windows to 18 months. Stuttgart and Munich engineering centers now mandate direct feedstock certification, bypassing traditional Tier-1 compounder mediation.
United States
Department of Defense and General Services Administration procurement through USDA BioPreferred labeling drives federal contract eligibility for verified bio-carbon content grades. EPA renewable fuel standard pathways shape market access conditions for domestic compounders. Automotive weatherstrip demand clusters in Michigan and Ohio, where OEM sustainability scorecards now enforce renewable carbon thresholds.
Japan
Medical device manufacturers under PMDA guidance accelerate qualification of bio-based liquid silicone rubber for implantable and diagnostic applications. METI circular economy roadmaps incentivize domestic feedstock processing. Osaka and Nagoya healthcare OEM procurement centers represent the fastest-expanding Asian demand node for JIS-compliant medical-grade elastomers.
France
EU Green Deal sustainable product criteria and REACH endocrine disruptor screening impose dual compliance burdens on compounder supply chains. ANSM medical device substance disclosure requirements extend to processing aids and stabilizer packages. Lyon and Paris automotive engineering clusters pilot lignocellulosic-derived thermoplastic elastomers at 10,000-ton annual offtake scales.
Netherlands
Rotterdam and Amsterdam harbor logistics support feedstock import flows for European compounder networks. ECHA substance evaluation deadlines require renewable carbon mass balance documentation from port of entry through final formulation. Specialized polymerization catalyst distribution for bio-polyolefin elastomers concentrates in the Randstad chemical corridor.
Bio-Based Elastomers Market Key Industry Players
Concentration sits with backward-integrated petrochemical majors and specialized medical-grade compounders. The vendor base splits between diversified multinationals with captive renewable feedstock supply and regional specialists with certification depth in narrow specification tiers. Three archetypes dominate: integrated feedstock-producers, healthcare-focused formulators, and automotive supply chain specialists. Competitive moves center on strategic partnerships for bio-carbon verification platforms and capacity expansion in medical-grade liquid silicone rubber.
Within the integrated feedstock-producer tier, Dow and BASF SE exemplify archetype dominance through captive renewable carbon sourcing. Kuraray Co., Ltd. occupies a defensible position among healthcare-focused formulators, anchoring the medical-grade specialization vector with JIS-compliant liquid silicone rubber capabilities. These three entities represent the competitive poles around which qualification timelines and pricing power currently organize.
| Leading Market Players |
|---|
| Dow |
| BASF SE |
| Lanxess AG |
| Asahi Kasei Corporation |
| Arkema |
| Huntsman International LLC |
| Covestro AG |
| Kuraray Co., Ltd. |
| Trinseo |
| Others |
Cost & Logistics Intelligence
10,000-ton pilot offtake scales at German OEM engineering centers compress unit economics for lignocellulosic-derived thermoplastic elastomers, concentrating price-setting power among backward-integrated feedstock producers while squeezing compounder margins during crude oil dislocation events.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on bio-carbon certification grade and REACH registration documentation completeness. Price differentiation rests on FDA 21 CFR 177.2600 compliance status and JIS medical device standard verification, with healthcare procurement showing least sensitivity and automotive Tier-1 suppliers facing acute pressure from Scope 3 target deadlines. Cost compression in medical-grade tiers is intensifying because validation cycle extensions strain R&D resource allocation.
Supply Chain Analysis
Germany and the Netherlands anchor European compounder networks, with Rotterdam harbor logistics feeding renewable carbon intermediates to Baden-Württemberg and Bavaria processing clusters. Raw material dependencies center on castor oil, soybean oil, and lignocellulosic biomass feedstocks. Single-source vulnerability concentrates in stereospecific metallocene catalyst supply from limited European suppliers. Distribution runs through Tier-1 automotive seal and gasket manufacturers, though BMW, Mercedes-Benz, and Volkswagen Group procurement teams increasingly mandate direct feedstock certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against petroleum-derived styrenic block copolymers and conventional silicone rubber incumbents, requiring bio-based compounders to demonstrate performance parity at validated carbon reduction thresholds.
For Market Incumbents: Fortify backward integration into certified renewable feedstock sourcing to sustain premium positioning against regional biomass processors forward-integrating into compounder supply. Deepen captive supply of castor and soybean oil derivatives to insulate margin structures from agricultural commodity volatility. Prioritize ECHA evaluation deadline compliance investment to compress qualification windows for German automotive procurement. For New Entrants and Emerging Players: Differentiate on JIS-compliant liquid silicone rubber grades for Japanese medical device implantable applications, where PMDA guidance is accelerating qualification timelines fastest among Asian procurement centers. Target USDA BioPreferred federal procurement eligibility for Department of Defense and General Services Administration contract access. Pursue isocyanate-free waterborne polyurethane formulation partnerships with automotive interior coating specialists. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors healthcare-focused formulators with certification depth in FDA 21 CFR 177.2600 repeated-use rubber articles and EU MDR substance disclosure compliance. Acquisition targets should demonstrate locked medical-grade validation pipelines and locked automotive OEM direct qualification relationships. The signal to watch is convergence between EU CSRD corporate sustainability reporting mandates and emerging SEC climate disclosure rules, which would accelerate compliance cost burdens for multinational compounders without unified carbon accounting platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstock | BASF SE leverages captive castor oil supply chains to sustain REACH-compliant mass balance documentation. |
| Medical-Grade Certification Investment | Kuraray Co., Ltd. anchors JIS-compliant liquid silicone rubber capacity for PMDA-guided implantable applications. |
| Long-term Supply Agreement | Dow secures ethylene-propylene terpolymer offtake with verified bio-carbon content for North American automotive OEMs. |
| Joint Venture for Catalyst Access | European compounders partner to reduce stereospecific metallocene catalyst supply concentration risk. |
| Green Manufacturing Transition | Isocyanate-free waterborne polyurethane systems command formulation premiums from automotive interior coating procurement. |
Research Approach
Cross-validation between primary interviews with polymerization plant managers, automotive Tier-1 procurement leads, and healthcare regulatory affairs directors and secondary validation through ECHA substance registration databases, USDA BioPreferred product listings, and FDA 21 CFR 177.2600 compliance records anchors the qualitative findings. Bottom-up triangulation of compounder capacity utilization and top-down reconciliation with automotive OEM sustainability procurement scorecards informs volume estimates. Trade data from German, French, and Dutch customs authorities tracks feedstock import flows and finished elastomer export balances.
Sensitivity analysis around plant oil feedstock price volatility and REACH endocrine disruptor screening timeline extensions shapes the analytical framework across the analysis window. Segmentation dimensions modeled include polymer chemistry tier, end-use industry procurement maturity, certification grade, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections for automotive weatherstrip substitution and medical-grade liquid silicone rubber qualification acceleration. Industry-specific inputs incorporate Scope 3 decarbonization mandate enforcement intensity and ECHA evaluation deadline compliance cost trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or abrupt petroleum-carbon price convergence would require recalibration. Forecasts reflect assumptions on bio-carbon mass balance verification technology adoption and automotive OEM direct qualification pattern persistence. Recalibration cycles align with material shifts in REACH polymer-specific registration requirements and regulator alignment between EU CSRD and SEC climate disclosure frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Rubber Membrane Market
Elastomeric Membrane
High Temperature Elastomers Market
Elastomeric Membrane
EPDM Waterproofing Membrane Market
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Industrial PU Elastomer Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
Olefinic Thermoplastic Elastomers Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
Global Acrylic Elastomers Market