
 Olefinic Thermoplastic Elastomers Market | 2026-2036
Olefinic Thermoplastic Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Olefinic Thermoplastic Elastomers Market Outlook
ISO 18064 polymer nomenclature certification is unwinding competitive access for compounders lacking accredited testing infrastructure. ExxonMobil Corporation leverages its Baytown integrated polyolefin complex to sustain captive supply of reactor-grade TPO resins. Mitsui Chemicals Inc. anchors its position through specialized hydrogenated styrenic block copolymer capacity in Singapore. BASF SE differentiates via formulated compounds that meet OEM interior emissions specifications without secondary annealing.
Olefinic thermoplastic elastomers comprise polyolefin-based polymers exhibiting rubber-like elasticity at service temperatures with thermoplastic processability above melting point, typically formulated with ethylene-propylene rubber domains dispersed in polypropylene matrices achieving Shore A hardness of 40-90. These materials primarily serve automotive lightweighting and medical device flexibility requirements where conventional vulcanized rubber incurs higher conversion costs. TPO compounds dominate volume consumption in bumper fascias and airbag covers where paintability and low-temperature ductility command premium positioning. SEBS grades represent the fastest-expanding category, driven by sterilizable medical tubing and overmolded consumer electronics grips where USP Class VI biocompatibility certification creates margin pools. EPDM-modified blends retain mature demand in roofing membranes and weatherstripping, competing on kilogram economics rather than formulation sophistication.
EU REACH restrictions on phthalate plasticizers and FDA 21 CFR 177.2600 compliance for repeated-use rubber articles constrain formulation freedom and elevate qualification costs for medical and food-contact applications. China's GB standards for automotive interior VOC emissions and Japan's JIS K 6250 rubber testing protocols further fragment regional specification requirements, forcing compounders to maintain multiple certificate portfolios. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions in Europe and North America, as fluorinated processing aids in TPO production face substitution pressures that could disrupt existing supply qualifications without advance raw material pivoting.
Market Dynamics
Automotive OEM recyclability mandates are compressing formulation freedom while concentrating procurement among compounders holding ISO 18064 polymer nomenclature certification, forcing mid-tier suppliers to absorb qualification costs or exit certified supply tiers entirely.
Growth Catalysts
- EU REACH recyclability mandates:German and Japanese automotive OEMs expand TPO content in interior trim to meet circular economy guidelines, pulling demand toward certified compounders with accredited testing infrastructure.
- Medical-grade SEBS sterilization protocols:USP Class VI biocompatibility certification creates margin pools in sterilizable tubing and overmolded consumer electronics grips, rewarding specialized hydrogenated styrenic block copolymer capacity.
- Yangtze River Delta manufacturing concentration:China's injection molding capacity for medical-grade SEBS compounds has tripled since 2022, anchoring regional supply security for Asia-Pacific device manufacturers.
Market Restraints
- Phthalate plasticizer restrictions:EU REACH constraints and FDA 21 CFR 177.2600 compliance requirements elevate qualification costs for medical and food-contact applications, compressing formulation flexibility.
- Reactor-grade TPO supply concentration:Captive supply from integrated polyolefin complexes limits independent compounder access to cost-competitive base resins.
- Fluorinated processing aid substitution pressure:Evolving per- and polyfluoroalkyl substance restrictions in Europe and North America threaten existing supply qualifications without advance raw material pivoting.
Strategic Opportunities
- Underpenetrated medical device segments:India's CDSCO regulatory harmonization with ISO 10993 standards opens qualification pathways for SEBS compounds in surgical instruments and drug delivery systems.
- Dual carbon goal alignment:China's MEE emissions trading scheme rewards low-VOC TPO formulations, creating preferential access for compounders meeting GB standards for automotive interior emissions.
- 3D printing filament convergence:Fused deposition modeling of soft-touch TPO filaments intersects with desktop manufacturing expansion in consumer electronics prototyping.
Industry Challenges
- Multi-certificate portfolio maintenance:Compounders must simultaneously satisfy Japan's JIS K 6250 rubber testing protocols, China's GB automotive VOC standards, and EU REACH documentation requirements, stretching technical staff across fragmented qualification timelines.
- Annealing process elimination:OEM interior emissions specifications demanding zero secondary annealing force reformulation of legacy TPO compounds without guaranteed performance parity, extending customer requalification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Olefinic Thermoplastic Elastomers Market |
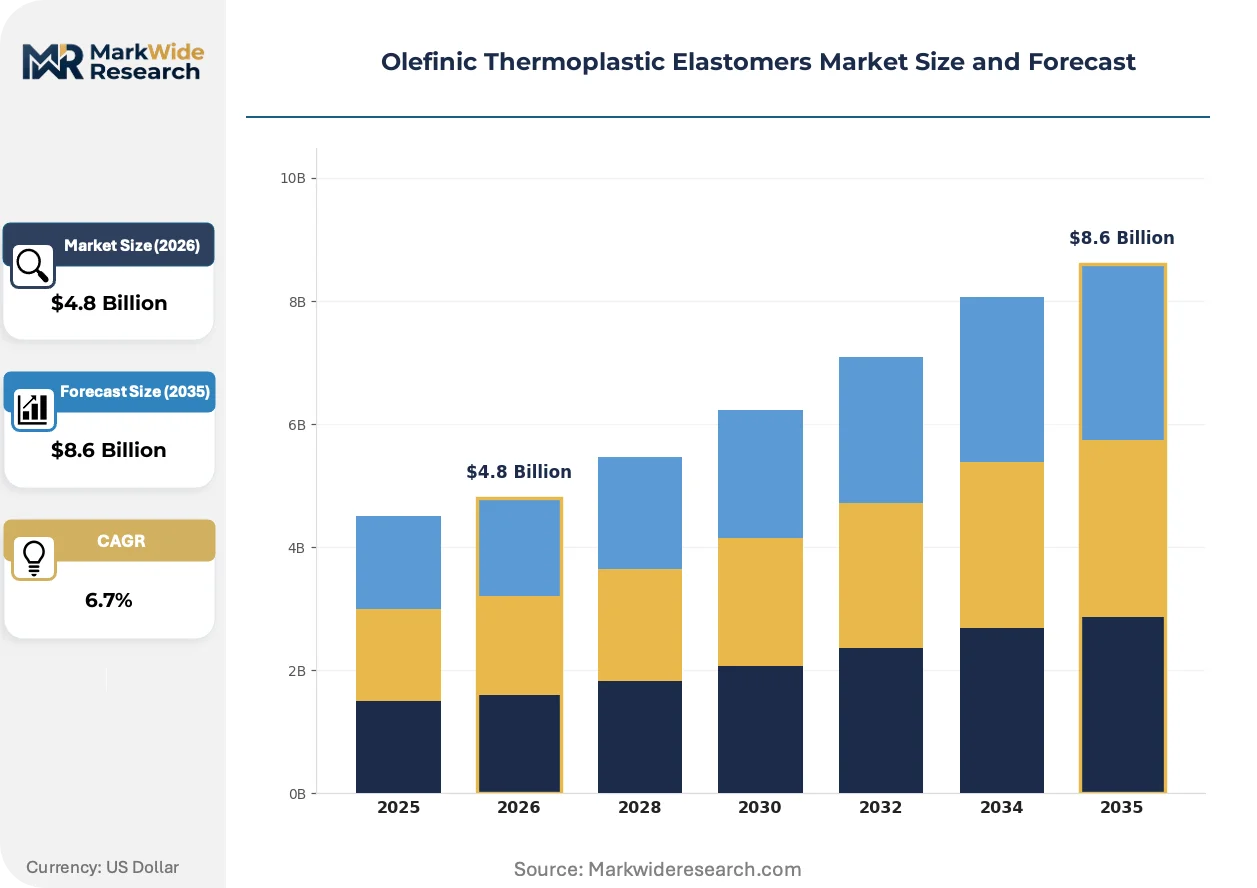
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPDM, TPO, SEBS, SIS Application: Automotive Interiors, Footwear, Medical Devices, Consumer Goods End User: Manufacturers, Distributors, OEMs, Retailers Technology: Injection Molding, Blow Molding, Extrusion, Compression Molding |
| Companies Covered | The Dow Chemical Company, BASF SE, ExxonMobil Corporation, Mitsui Chemicals Inc., Arkema SA, LyondellBasell Industries, SABIC, Asahi Kasei Corporation, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Olefinic Thermoplastic Elastomers Market Strategic Shifts
Formulation science and manufacturing process control are diverging toward specialized certification tiers, with medical-grade biocompatibility and automotive low-emissions specifications pulling compounder capabilities in opposing technical directions.
Hydrogenated styrenic block copolymer technology is bifurcating the elastomer landscape between sterilizable medical applications and conventional automotive grades. Medical device manufacturers in Germany and Switzerland are adopting USP Class VI certified SEBS compounds at three times the pace of standard TPO procurement. This divergence is compressing margins for undifferentiated commodity grades while enabling premium positioning for qualified medical compounders.
Europe's F-Gas Regulation and evolving ECHA restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated processing aids from TPO production lines. Compounders must reformulate extrusion and injection molding compounds with alternative lubricant packages without sacrificing surface finish quality. Automotive exterior applications in Germany and France face the steepest requalification burdens as OEMs enforce simultaneous compliance with REACH substance restrictions and KBA type-approval durability standards.
Medical device OEMs are consolidating supplier panels around compounders offering integrated regulatory documentation packages. Single-source relationships are displacing multi-vendor qualification strategies for SEBS tubing and overmolded components. This concentration is most visible in the Yangtze River Delta, where domestic device manufacturers now require compounders to pre-submit FDA master file references and CDSCO import license support documentation alongside material shipments.
Olefinic Thermoplastic Elastomers Market Segmentation
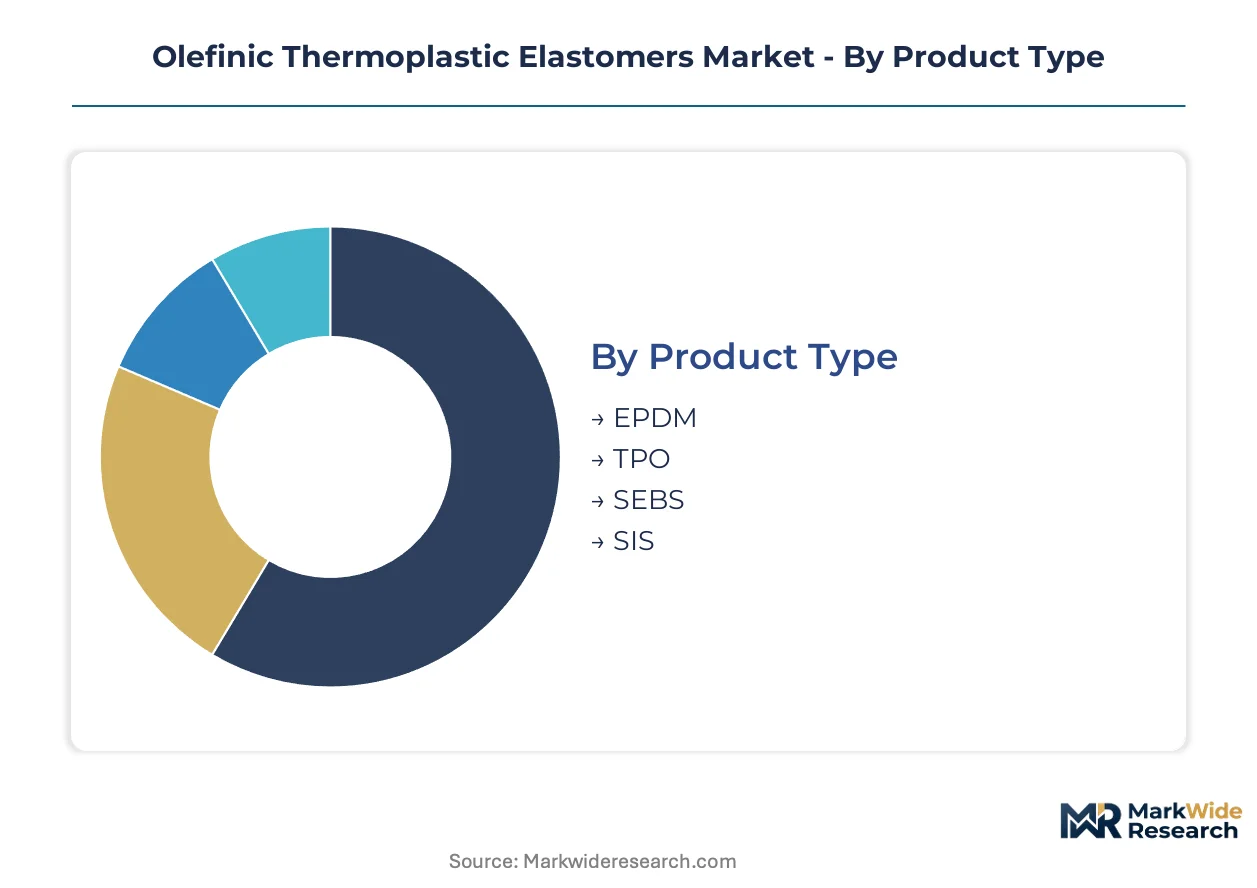
Margin capture in olefinic thermoplastic elastomers diverges sharply across product chemistries and certification tiers. Medical-grade SEBS commands premium positioning through USP Class VI biocompatibility, while automotive TPO volumes concentrate among compounders holding ISO 18064 nomenclature certification.
Product Type:
Premium margin pools concentrate in hydrogenated styrenic block copolymers serving sterilizable medical applications, with commodity polyolefin blends competing on kilogram economics in weatherstripping and roofing membranes.
- SEBS:Hydrogenated styrenic block copolymer with saturated midblock structure enables gamma and autoclave sterilization protocols without degradation. Demand concentrates in China's Yangtze River Delta for medical tubing and overmolded consumer electronics grips where USP Class VI certification creates supplier stickiness. German and Swiss device manufacturers are adopting certified SEBS compounds at triple the pace of standard TPO procurement.
- TPO:Reactor-grade thermoplastic polyolefin comprises ethylene-propylene rubber domains dispersed in polypropylene matrices achieving Shore A hardness of 40-90. Automotive OEMs in Germany and Japan are expanding TPO content in interior trim to meet EU REACH and METI circular economy recyclability mandates, pulling procurement toward compounders with captive resin supply from integrated polyolefin complexes.
- EPDM:Ethylene-propylene-diene monomer rubber retains mature demand in roofing membranes and automotive weatherstripping where formulation sophistication yields to kilogram economics.
- SIS:Styrene-isoprene-styrene block copolymer serves pressure-sensitive adhesive applications and flexible packaging sealant layers with lower heat resistance than hydrogenated grades.
The dominant share belongs to TPO, while SEBS is closing the gap fastest through medical device qualification pathways.
Application:
Application-driven margin stratification separates emission-compliant automotive formulations from sterilizable medical grades, with footwear and consumer goods occupying mid-tier positioning.
- Medical Devices:Surgical tubing, drug delivery systems, and overmolded instrument grips require USP Class VI biocompatibility and FDA 21 CFR 177.2600 compliance for repeated-use rubber articles. India's CDSCO regulatory harmonization with ISO 10993 standards is opening qualification pathways for SEBS compounds in surgical instruments.
- Automotive Interiors:Bumper fascias, airbag covers, and dashboard soft-touch surfaces demand paintability, low-temperature ductility, and zero secondary annealing to meet OEM emissions specifications. China's GB standards for automotive interior VOC emissions and Japan's JIS K 6250 rubber testing protocols fragment regional requirements.
- Footwear:Midsole cushioning and outsole components utilize TPO compounds for lightweighting and process efficiency in injection molding operations.
- Consumer Goods:Overmolded electronics grips and personal care packaging leverage SEBS for soft-touch aesthetics without sterilization requirements.
Medical Devices captures the steepest margin expansion, while Automotive Interiors retains volume leadership despite recyclability mandate compression.
End User:
Procurement authority concentrates with OEMs and qualified manufacturers holding multi-certificate portfolios across REACH, FDA, and GB compliance regimes.
- OEMs:German and Japanese automotive manufacturers and German, Swiss, and US medical device producers specify certified compounds and consolidate supplier panels around integrated regulatory documentation packages.
- Manufacturers:Injection molders in China's Yangtze River Delta and compounders with hydrogenated styrenic block copolymer capacity in Singapore anchor regional supply security.
- Distributors:Technical distributors bridge formulation expertise for mid-tier processors lacking in-house compounding capabilities.
- Retailers:Indirect channel for consumer goods applications with limited technical specification involvement.
OEMs command specification authority, while Manufacturers are consolidating fastest through vertical capability investments.
Technology:
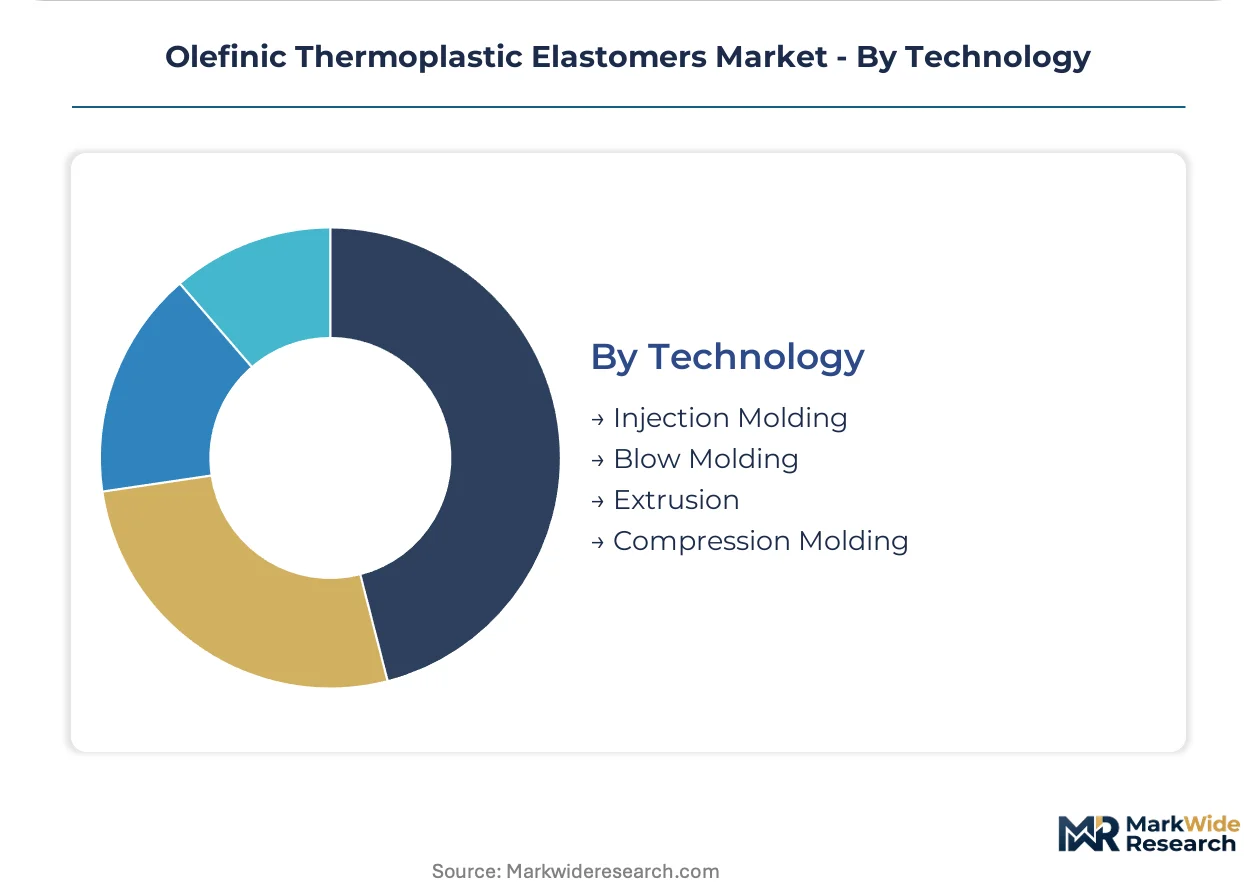
Process technology selection tracks part complexity and surface finish requirements, with injection molding dominating medical-grade SEBS and extrusion serving roofing membrane EPDM.
- Injection Molding:Precision molding of complex geometries for medical device components and automotive interior parts with tight dimensional tolerances. China's Yangtze River Delta capacity for medical-grade SEBS compounds has tripled since 2022.
- Extrusion:Continuous profile production for tubing, weatherstripping, and roofing membranes with alternative lubricant packages replacing fluorinated processing aids under Europe's F-Gas Regulation.
- Blow Molding:Hollow part formation for automotive ducting and consumer packaging applications.
- Compression Molding:Legacy process for thick-section parts and low-volume specialty components.
Injection Molding holds the dominant equipment base, while Extrusion faces the steepest reformulation burden from processing aid substitution pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH recyclability mandates and Japan's METI circular economy guidelines are redirecting automotive procurement toward certified compounders with accredited testing infrastructure across major manufacturing economies.
China
Medical-grade SEBS demand concentrates in the Yangtze River Delta where injection molding capacity has tripled since 2022. GB standards for automotive interior VOC emissions under MEE oversight reward low-emission TPO formulations with preferential market access. Domestic device manufacturers in Shanghai and Suzhou now require pre-submitted FDA master file references alongside material shipments.
Germany
Automotive OEMs expand TPO content in interior trim to meet EU REACH substance restrictions and KBA type-approval durability standards. The F-Gas Regulation eliminates fluorinated processing aids from TPO production lines, forcing reformulation with alternative lubricant packages. Production clusters in Bavaria and Baden-Württemberg face simultaneous compliance with REACH documentation and annealing-free emissions specifications.
United States
FDA 21 CFR 177.2600 compliance for repeated-use rubber articles elevates qualification costs for medical and food-contact TPO applications. USP Class VI biocompatibility certification creates margin pools in sterilizable tubing and overmolded consumer electronics grips. Device manufacturers in the Midwest and Northeast are consolidating supplier panels around compounders offering integrated regulatory documentation packages.
Japan
METI circular economy guidelines pull automotive procurement toward TPO compounds meeting recyclability mandates for interior trim applications. JIS K 6250 rubber testing protocols fragment regional specification requirements alongside ISO 18064 polymer nomenclature certification. Manufacturing concentrations in the Kanto and Kansai regions anchor hydrogenated styrenic block copolymer capacity for medical-grade SEBS production.
India
CDSCO regulatory harmonization with ISO 10993 standards opens qualification pathways for SEBS compounds in surgical instruments and drug delivery systems. Domestic medical device manufacturers in Maharashtra and Gujarat are expanding sterilizable tubing production. The PLI scheme for medical devices incentivizes compounders to establish local testing infrastructure for USP Class VI certification.
Olefinic Thermoplastic Elastomers Market Competitive Environment
Player mix skews toward integrated petrochemical conglomerates with captive polyolefin supply and specialized hydrogenated styrenic block copolymer producers. Three strategic archetypes dominate: reactor-grade resin suppliers with backward integration into cracker operations, formulated compounders holding multi-certificate portfolios across REACH and FDA regimes, and medical-grade specialists with USP Class VI biocompatibility accreditation. Competitive moves concentrate on capacity expansion in Asia-Pacific medical clusters and strategic partnerships to secure alternative lubricant packages replacing fluorinated processing aids.
Within the integrated petrochemical tier, ExxonMobil Corporation and BASF SE exemplify divergent positioning strategies. ExxonMobil anchors its competitive stance through captive supply of reactor-grade TPO resins from integrated polyolefin complexes. BASF occupies a formulated compounder position, differentiating through emission-compliant automotive grades that eliminate secondary annealing. Mitsui Chemicals Inc. represents the specialized hydrogenated styrenic block copolymer archetype, with production concentration in Singapore serving Asia-Pacific medical device manufacturers.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| BASF SE |
| ExxonMobil Corporation |
| Mitsui Chemicals Inc. |
| Arkema SA |
| LyondellBasell Industries |
| SABIC |
| Asahi Kasei Corporation |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
Alternative lubricant packages replacing fluorinated processing aids under Europe's F-Gas Regulation are simultaneously relocating compounding capacity toward Asia-Pacific hydrogenated styrenic block copolymer hubs and compressing margin structures for European automotive-grade TPO producers facing dual reformulation and requalification burdens.
Pricing Analysis
Certification level creates the primary spread across the olefinic thermoplastic elastomer landscape. USP Class VI biocompatibility and ISO 18064 polymer nomenclature accreditation command premium positioning in medical and automotive tiers respectively, while undifferentiated commodity grades compete on kilogram economics. Cost compression in standard TPO compounds is intensifying because captive reactor-grade resin supply limits independent compounder access to cost-competitive base materials. Medical device OEMs exhibit the lowest price sensitivity due to regulatory qualification stickiness, whereas roofing membrane and weatherstripping buyers prioritize kilogram economics above formulation sophistication.
Supply Chain Analysis
Inventory cycles for medical-grade SEBS compounds have lengthened as Yangtze River Delta injection molders pre-position certified materials ahead of FDA master file submission requirements. Supply concentrates in China, Singapore, and Germany, with hydrogenated styrenic block copolymer capacity anchored in Singapore serving Asia-Pacific device manufacturers. Raw material flows draw from integrated polyolefin complexes, hydrogenated styrenic monomer streams, and alternative lubricant feedstocks replacing fluorinated processing aids. Single-source vulnerability around reactor-grade TPO resin supply creates structural risk for independent compounders lacking backward integration. Distribution runs through technical distributors bridging formulation expertise for mid-tier processors lacking in-house compounding capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified testing infrastructure for multi-certificate portfolios across REACH, FDA, and GB compliance regimes represents the critical scarce capability, with compounders maintaining ISO 18064 accreditation and USP Class VI certification capturing disproportionate procurement authority from consolidating OEM supplier panels.
For Market Incumbents: Fortify captive resin supply positions through long-term offtake agreements with integrated polyolefin complexes or direct hydrogenated styrenic block copolymer capacity additions in Asia-Pacific medical clusters. Accelerate alternative lubricant package qualification to preempt ECHA restrictions on per- and polyfluoroalkyl substances that threaten existing automotive supply relationships. Certification investment in India's CDSCO harmonization pathways creates defensive moats against emerging regional compounders. For New Entrants and Emerging Players: Anchor in India's surgical instrument and drug delivery system segments where CDSCO regulatory harmonization with ISO 10993 standards has opened qualification pathways without entrenched incumbent relationships. Medical-grade SEBS for sterilizable tubing offers the most penetrable white space given triple-digit demand expansion in China's Yangtze River Delta. A go-to-market angle centered on pre-submitted FDA master file references and integrated regulatory documentation packages addresses OEM supplier consolidation preferences. For Investors and Strategic Acquirers: The market sits at a certification-concentration phase that favors compounders with multi-certificate portfolios and captive hydrogenated styrenic block copolymer capacity. Long-term viability across the analysis window hinges on sustained differentiation through regulatory qualification assets rather than commodity scale. Acquisition targets should display integrated testing infrastructure for ISO 18064, USP Class VI, and GB automotive VOC compliance. The signal to watch is OEM supplier panel consolidation velocity in German and Japanese automotive procurement and Swiss medical device sourcing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogenated Styrenic Monomer Supply | Secures cost-competitive feedstock for medical-grade SEBS production against Singapore-based competitors. |
| Alternative Lubricant Package Qualification | Preempts ECHA restrictions on fluorinated processing aids in European automotive TPO supply relationships. |
| CDSCO Testing Infrastructure Investment | Captures qualification pathways for SEBS compounds in India's expanding surgical instrument market. |
| Long-term Supply Agreement with Yangtze River Delta Mold | Locks in tripled injection molding capacity for medical-grade compounds since 2022. |
| Annealing-free Formulation Development | Meets German OEM interior emissions specifications without secondary processing, extending customer requalification cycles. |
Study Parameters
Desk research of regulatory filing databases, customs trade records, and SEC 10-K disclosures preceded structured interviews with polymer compounding plant managers, automotive OEM procurement leads, medical device regulatory affairs directors, and technical distribution channel partners. Primary fieldwork with hydrogenated styrenic block copolymer producers and injection molding operators in the Yangtze River Delta was cross-validated against secondary data from ECHA substance restriction notifications, FDA 510(k) filings, and CDSCO import license records. Bottom-up demand modeling across application segments was reconciled with top-down capacity assessments from integrated polyolefin complex disclosures.
Variance decomposition across the projection horizon separates volume drivers by product chemistry, certification tier, and regional regulatory cluster. Segmentation dimensions modeled include hydrogenation grade, Shore A hardness specification, sterilization protocol compatibility, and automotive OEM tier supply status. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking qualification pipeline visibility. Industry-specific forecast inputs incorporate REACH substance restriction timelines, METI circular economy guideline implementation phases, and MEE emissions trading scheme credit pricing.
Decision-makers should treat outputs as directional under assumptions of sustained EU REACH recyclability mandate enforcement and continued Yangtze River Delta manufacturing concentration; material deviation in fluorinated processing aid substitution velocity or CDSCO harmonization pace would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
South America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Industrial PU Elastomer Market
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
Middle-East and Africa Fluoroelastomers Market
Elastomeric Membrane
Modified Silicone Fluids Market
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Rubber Membrane Market
Elastomeric Membrane
Cold Cast Elastomers Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Europe Single-Ply Membrane Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
Ethylene Propylene Elastomers Market
Elastomeric Membrane
Medical Styrenic Block Copolymer (SBC) Market