
 Global High Temperature Resin Market | 2026-2036
Global High Temperature Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Temperature Resin Market Analysis
Modular pre-preg kit configurations is rebalancing procurement patterns among composite fabricators, letting buyers match resin chemistry to specific thermal and mechanical loads rather than purchasing generic formulations. Solvay S.A. leverages its vertically integrated polyimide supply chain from monomer synthesis to film conversion. Huntsman Corporation anchors its position through specialized benzoxazine formulations for aerospace structural adhesives. Hexion Inc. competes via broad phenolic resin capacity serving brake friction and ablative applications across multiple continents.
High temperature resins are thermosetting or thermoplastic polymers engineered to retain mechanical integrity, dimensional stability, and chemical resistance above 150 degrees Celsius, typically synthesized through condensation polymerization of aromatic monomers or ring-opening reactions of heterocyclic precursors for thermal barrier, structural bonding, and electrical insulation roles in harsh environments. Polyether ether ketone commands premium positioning in medical and aerospace segments due to its melt-processability and biocompatibility, while polyimide films dominate flexible electronics substrates where thermal cycling resistance determines device reliability. Phenolic resins occupy mature, high-volume niches in friction materials and foundry binders, generating steady cash flows but facing margin pressure from bio-based alternatives.
EPA emissions regulations and REACH chemical restrictions are forcing coatings manufacturers to eliminate formaldehyde and reduce solvent content in phenolic and silicone formulations, directly altering R&D priorities and raw material sourcing. FDA biocompatibility requirements and EU MDR standards for implantable devices create parallel compliance pathways for PEEK suppliers serving medical device OEMs. Stakeholders must monitor evolving carbon border adjustment mechanisms and dual carbon goals in China, as these frameworks will reshape cost structures for imported aromatic monomers and energy-intensive polymerization processes.
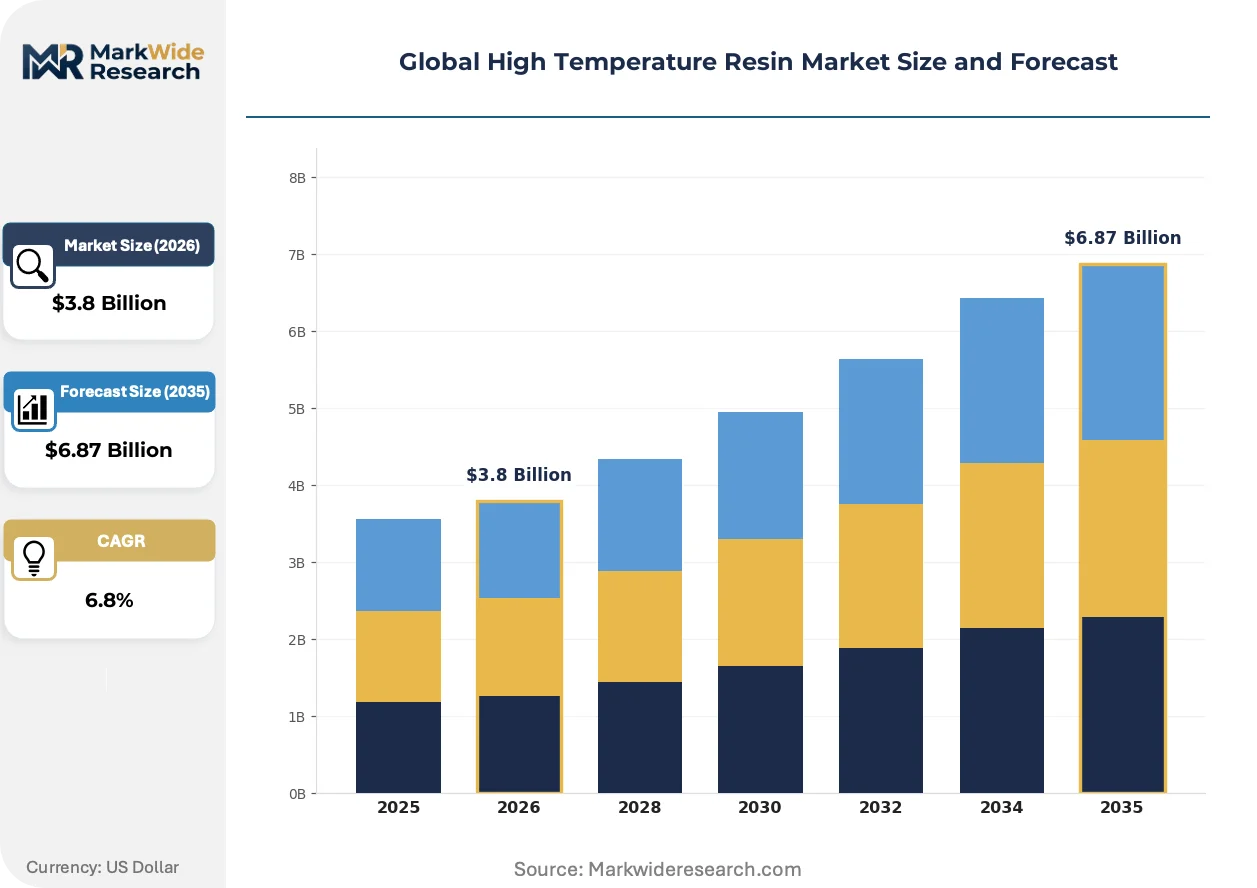
Market Dynamics
REACH chemical restrictions and EPA emissions standards are forcing simultaneous reformulation of phenolic and silicone resin systems, compressing R&D timelines while elevating raw material qualification costs for coatings and composite manufacturers.
Growth Catalysts
- Aerospace procurement expansion:North American and European engine manufacturers are qualifying polyimide and PEEK composites for thermal protection systems and structural components, creating pull-through demand for high-purity monomer feedstocks.
- REACH VOC limits:The European regulation's tightening thresholds on volatile organic compounds in industrial coatings are accelerating solvent-free and water-borne high temperature resin development across automotive and industrial maintenance segments.
- Ceramic-filled phenolic integration:German automotive OEMs and tier suppliers are embedding these resins into electric vehicle battery enclosures and power electronics housings, opening volume applications beyond traditional friction materials.
Market Restraints
- Aromatic monomer supply concentration:Production of key precursors for polyimide and PEEK synthesis clusters in China and Germany, exposing buyers to carbon border adjustment mechanism cost shocks and dual carbon policy implementation timelines.
- Formaldehyde elimination mandates:EPA and REACH restrictions on formaldehyde emissions in phenolic resin curing are forcing costly resin architecture redesigns without mature drop-in alternatives at equivalent cost-performance ratios.
- Bio-based substitution pressure:Lignin-derived and furan-based thermosets are capturing niche volume in brake friction and foundry applications, eroding margin stability in phenolic resin's mature cash-generating segments.
Strategic Opportunities
- Indian electric vehicle component localization:The country's PLI scheme for advanced chemistry cell manufacturing is creating demand for thermally stable battery module housings and cell-to-pack structural adhesives.
- Japan's semiconductor packaging expansion:METI-backed domestic fab construction is elevating demand for polyimide films in wafer-level packaging and flexible printed circuit substrates.
- FDA-MDR convergence pathway:Harmonized biocompatibility documentation requirements between US and EU medical device regulations are enabling single-qualification PEEK supply strategies for implantable device OEMs.
Industry Challenges
- Polymerization process engineering talent scarcity:Specialized expertise in aromatic condensation and heterocyclic ring-opening reactions is concentrating among retiring cohorts at established resin houses, constraining capacity expansion timelines.
- Multi-jurisdiction certification synchronization:Aerospace suppliers must simultaneously satisfy FAA flame-smoke-toxicity standards, EASA comparable requirements, and emerging CAAC protocols for Chinese airframe programs, fragmenting qualification resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Temperature Resin Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyimide, Phenolic, Polyether Ether Ketone, Silicones End User: Aerospace, Automotive, Electronics, Oil & Gas Application: Coatings, Adhesives, Films, Composites Form: Liquid, Powder, Granular, Sheet |
| Companies Covered | Solvay S.A., Huntsman Corporation, Hexion Inc., Toray Industries Inc., BASF SE, DIC Corporation, UBE Industries Ltd., Henkel AG & Co. KGaA, Royal Tencate N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Temperature Resin Market Emerging Trajectories
Additive manufacturing of high temperature thermoplastic composites is disrupting traditional subtractive machining workflows for aerospace brackets and ducting, compressing lead times from months to days while redefining scrap economics.
Continuous fiber-reinforced PEEK filament deposition is absorbing tooling and prototyping volume from conventional compression molding in medical device and aerospace supply chains. Orthopedic implant manufacturers in Switzerland and Germany are adopting the technology for patient-specific instrument guides and trial spacers. The process is absorbing low-volume, high-complexity production that previously required machined metallic or thermoset alternatives.
EPA formaldehyde emission standards under TSCA Title VI and the EU F-Gas Regulation's phase-down of hydrofluorocarbon blowing agents are jointly pressuring phenolic foam and insulation manufacturers. Coatings formulators are pivoting toward water-borne phenolic dispersions and latent curing systems to maintain industrial maintenance market access. The regulatory stack is most acute in US architectural coatings and EU cold-chain insulation applications, where reformulation timelines now determine contract renewal viability.
Composite fabricators are unbundling resin procurement from fiber supply, purchasing modular pre-preg kits that match chemistry to specific thermal and mechanical load cases rather than accepting generic formulations. Tier 1 aerospace suppliers in France and Italy are driving this specification, using digital twin validation to justify premium resin selections. The behavior is most visible in satellite structure and unmanned aerial vehicle airframe programs, where mass optimization commands explicit value capture mechanisms.
Global High Temperature Resin Market Segmentation
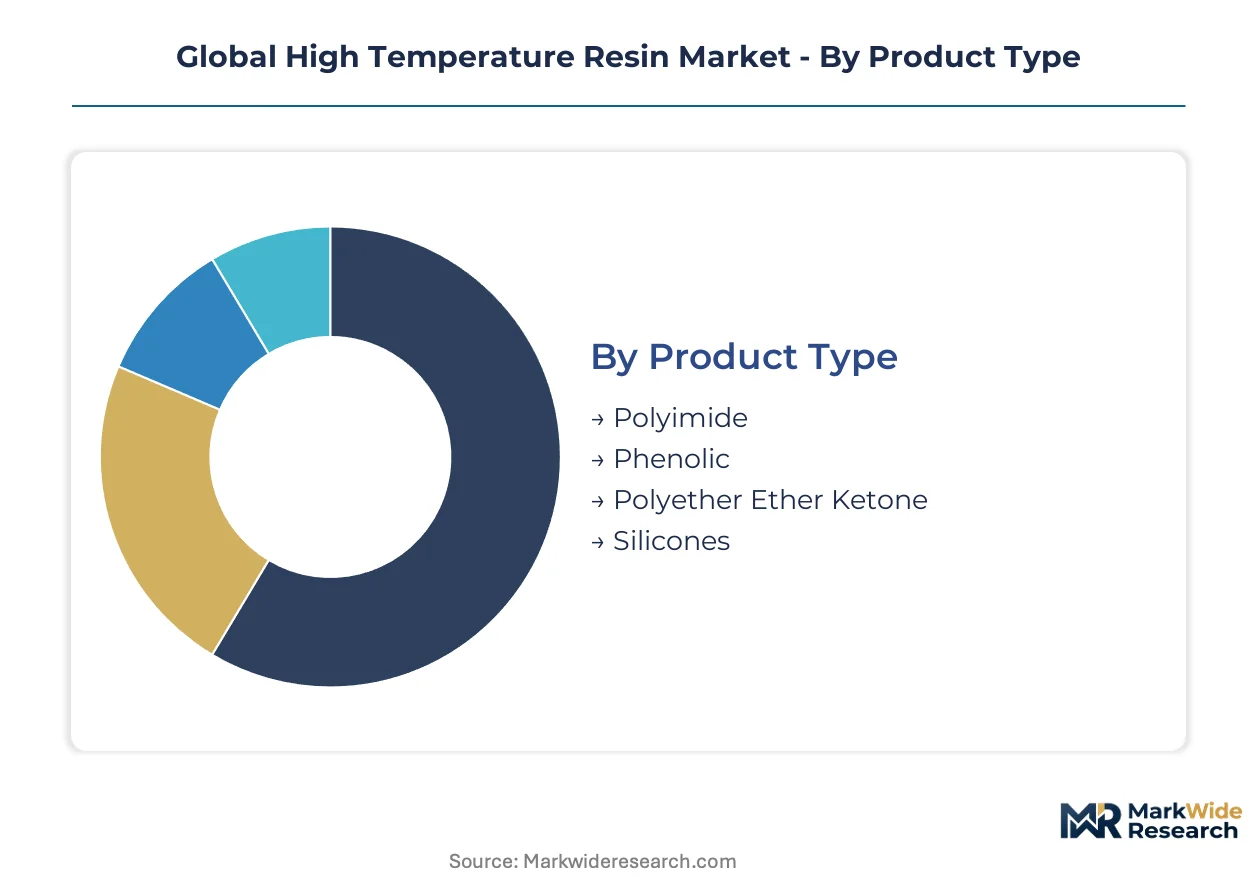
High temperature resin procurement patterns diverge sharply across chemistry families and end-use specifications. Buyers in aerospace and electronics prioritize thermal stability certifications over unit cost, while automotive and industrial segments optimize for process throughput and scrap rates.
Product Type:
Capital intensity varies dramatically across synthesis routes, with condensation polymerization of aromatic monomers demanding specialized reactor infrastructure and environmental controls.
- Polyimide:Synthesized through dianhydride-diamine condensation yielding imide ring structures with continuous service temperatures exceeding 300 degrees Celsius. Demand concentrates in Japanese semiconductor packaging expansion and US aerospace thermal protection systems, where METI-backed domestic fab construction and FAA flame-smoke-toxicity standards drive qualification timelines.
- Phenolic:Formaldehyde-phenol condensation produces highly cross-linked networks with excellent ablation resistance and friction properties. German automotive OEMs and tier suppliers embed ceramic-filled grades into electric vehicle battery enclosures, though EPA and REACH formaldehyde elimination mandates force costly resin architecture redesigns.
- Polyether Ether Ketone:Melt-processable thermoplastic with biocompatibility certification for implantable devices.
- Silicones:Siloxane backbone polymers delivering flexible thermal stability across wide temperature ranges.
Most installed capacity flows through Phenolic. Expansion is steepest in Polyether Ether Ketone.
End User:
Application-specific certification requirements create divergent margin profiles across customer verticals.
- Aerospace:Structural adhesives, ablative heat shields, and engine components requiring FAA, EASA, and CAAC flame-smoke-toxicity compliance. North American and European engine manufacturers are qualifying polyimide and PEEK composites for thermal protection systems.
- Electronics:Flexible printed circuit substrates and wafer-level packaging films where thermal cycling resistance determines device reliability.
- Automotive:Brake friction materials, battery module housings, and power electronics thermal management. German OEM procurement of ceramic-filled phenolic resins for electric vehicle architectures is opening volume applications beyond traditional friction segments.
- Oil & Gas:Downhole sealing and pipeline corrosion protection in high-pressure, high-temperature reservoirs.
Aerospace commands premium pricing through multi-jurisdiction certification requirements. Electronics is gaining share fastest on semiconductor packaging demand.
Application:
Formulation complexity and regulatory exposure determine R&D resource allocation across functional categories.
- Composites:Fiber-reinforced pre-preg systems for structural components. Modular kit configurations are rebalancing procurement patterns among fabricators, letting buyers match resin chemistry to specific thermal and mechanical loads.
- Coatings:Thermal barrier and corrosion protection systems. REACH VOC limits and EPA emissions standards are accelerating solvent-free and water-borne high temperature resin development.
- Adhesives:Structural bonding for metal, ceramic, and composite substrates.
- Films:Flexible substrates for electronics and insulation applications.
Composites absorb the largest share of specialty resin volume. Coatings is expanding most quickly on regulatory reformulation cycles.
Form:
Processing method compatibility shapes logistics requirements and working capital needs.
- Liquid:Solvent-borne and water-borne systems for coatings and impregnation processes.
- Powder:Dry blends for compression molding and friction material manufacturing.
- Granular:Extrusion and injection molding feedstocks for thermoplastic processing.
- Sheet:Pre-impregnated fiber reinforcements for lay-up and autoclave curing.
Granular forms dominate thermoplastic throughput. Sheet formats are climbing the fastest on additive manufacturing adoption for aerospace prototyping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The high temperature resin industry traces its commercial origins to German phenolic chemistry developed for early automotive friction materials and electrical insulation, with subsequent scaling of polyimide and PEEK production in the United States and Japan during the aerospace and electronics booms of the 1970s-1980s.
United States
FAA flame-smoke-toxicity standards and EPA emissions regulations under TSCA Title VI drive qualification timelines for aerospace and coatings applications. The IRA's clean energy manufacturing tax credits accelerate domestic production of thermally stable battery module materials. Huntsville, Alabama and Wichita, Kansas host concentrated aerospace composite fabrication clusters serving defense and commercial aviation programs.
Germany
REACH chemical restrictions and formaldehyde elimination mandates force resin architecture redesigns for automotive and industrial coatings. The country's national automotive regulator KBA enforces stringent emissions compliance for electric vehicle thermal management systems. Stuttgart and Munich anchor ceramic-filled phenolic resin integration into EV battery enclosures and power electronics housings by major OEMs and tier suppliers.
China
Dual carbon goals and carbon border adjustment mechanisms reshape cost structures for imported aromatic monomers and energy-intensive polymerization processes. The Ministry of Ecology and Environment enforces tightening emissions standards for phenolic resin production. Shanghai and Jiangsu province concentrate domestic polyimide film capacity serving semiconductor packaging and flexible electronics substrate demand.
Japan
METI-backed domestic semiconductor fab construction elevates demand for polyimide films in wafer-level packaging and flexible printed circuit substrates. The country's national pharmaceutical regulator PMDA maintains rigorous biocompatibility standards for implantable device materials. Nagoya and Osaka host precision polymerization expertise clusters for high-purity monomer feedstock production.
India
The PLI scheme for advanced chemistry cell manufacturing creates demand for thermally stable battery module housings and cell-to-pack structural adhesives. The Bureau of Indian Standards develops domestic certification frameworks for high-performance composite materials. Gujarat and Tamil Nadu emerge as electric vehicle component localization hubs attracting resin system suppliers.
Global High Temperature Resin Market Vendor Landscape
The competitive structure tilts toward vertically integrated specialty chemical conglomerates with captive monomer synthesis capabilities. Three to five multinational resin houses control premium polyimide and PEEK supply chains through backward integration into dianhydride and ketone precursor production. Two dominant competitive moves define current positioning: strategic partnerships between resin suppliers and aerospace OEMs for multi-jurisdiction qualification bundling, and geographic expansion of phenolic resin capacity into Indian and Southeast Asian automotive manufacturing corridors.
Within the integrated specialty chemical tier, Solvay S.A. and Huntsman Corporation exemplify divergent strategic positioning—Belgian-headquartered Solvay represents full vertical control from monomer synthesis through film conversion, while Texas-based Huntsman occupies specialized formulation expertise for aerospace structural adhesives. Hexion Inc. anchors the broad-capacity phenolic resin segment with multi-continental production footprints serving brake friction and ablative applications. These three entities collectively illustrate how scale, specialization, and integration depth segment competitive positioning across chemistry families and end-use specifications.
| Leading Market Players |
|---|
| Solvay S.A. |
| Huntsman Corporation |
| Hexion Inc. |
| Toray Industries Inc. |
| BASF SE |
| DIC Corporation |
| UBE Industries Ltd. |
| Henkel AG & Co. KGaA |
| Royal Tencate N.V. |
| Others |
Supply Flow & Price Mechanics
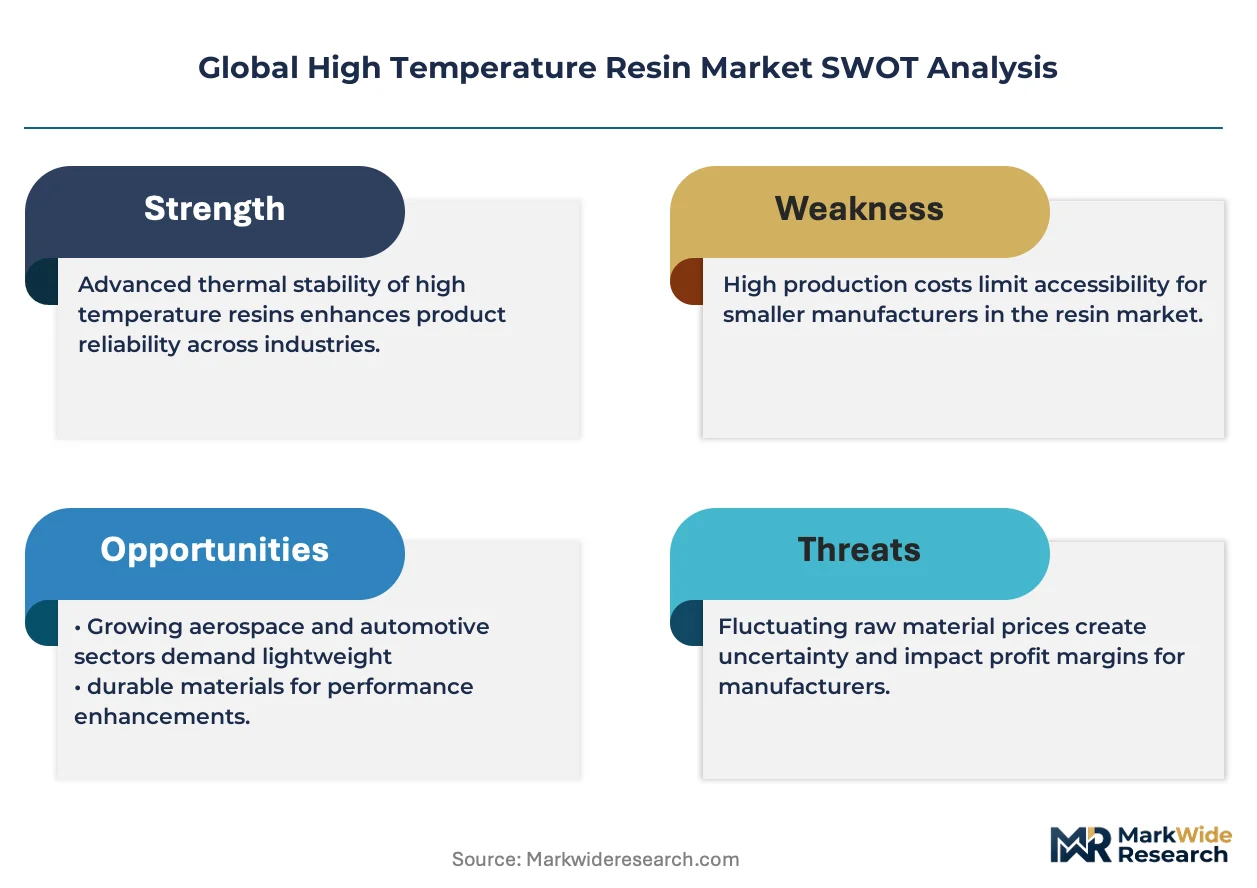
Private-equity-rolled-up phenolic resin specialists in North America and Europe exercise asymmetric pricing power over automotive friction material buyers, while their limited backward integration into formaldehyde feedstock exposes margins to EPA emission compliance cost shocks.
Pricing Analysis
Three-tier pricing structure across aerospace-certified, industrial-grade, and commodity phenolic tiers dominates procurement contracts. Price differentiation hinges on FAA flame-smoke-toxicity certification tier and volume scale commitments from Tier 1 suppliers. Cost compression in commodity phenolic runs through lignin-derived bio-based substitutes eroding traditional brake friction margins. Automotive OEM procurement teams exhibit highest price sensitivity, while medical device manufacturers prioritize biocompatibility documentation over unit cost.
Supply Chain Analysis
Ocean freight rates for aromatic dianhydride monomers from Shanghai to Rotterdam directly compress polyimide film converter margins in European electronics supply chains. Production of key precursors clusters in China, Germany, and Japan, drawing from concentrated anhydride and ketone feedstock sources. Single-source vulnerability pervades high-purity diamine supply for aerospace-grade polyimide synthesis. Distribution runs through authorized distributor networks serving composite fabricators and coatings formulators with technical service bundled.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by irreplaceable thermal protection requirements in next-generation aerospace propulsion architectures.
For Market Incumbents: Anchor market position through captive dianhydride monomer synthesis capacity additions in low-carbon-intensity production zones, insulating against carbon border adjustment mechanism cost shocks. Deepen certification investment in simultaneous FAA-EASA-CAAC qualification bundling to fragment competitor R&D resources. Bio-based phenolic substitution in brake friction represents the most acute margin threat requiring formulation lock-in contracts with legacy automotive platforms.
For New Entrants and Emerging Players: Direct-to-formulator digital channels for modular pre-preg kit configuration tools bypass established distributor technical service relationships. White-space concentrates in Indian electric vehicle battery enclosure resin supply under PLI scheme localization mandates, and in water-borne phenolic dispersions for EU industrial maintenance coatings facing REACH VOC deadlines. Target qualification-light prototyping volumes in additive manufacturing filament before attacking certified aerospace production.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap phenolic resin houses with automotive-heavy revenue mixes facing bio-based substitution headwinds. Long-term viability frames around polymerization process engineering talent scarcity constraining capacity expansion timelines industry-wide. Acquisition target archetype: regional polyimide film converters with underutilized metallization capacity serving semiconductor packaging demand inflection. Watch Japanese METI fab construction acceleration as signal for polyimide substrate demand step-up.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Synthesis | Captive dianhydride production insulates Solvay and Huntsman from carbon border adjustment cost volatility in European supply chains. |
| Multi-Jurisdiction Certification Bundling | Simultaneous FAA-EASA qualification compresses competitor R&D timelines and fragments aerospace procurement decision-making. |
| Ceramic-Filled Phenolic Formulation Lock-In | Long-term supply agreements with German automotive OEMs defend against lignin-derived bio-based substitution in EV battery enclosures. |
| Water-Borne Phenolic Dispersion Scale-Up | REACH VOC compliance in EU industrial maintenance coatings determines contract renewal viability for Hexion and regional specialists. |
| Additive Manufacturing Filament Partnership | Continuous fiber-reinforced PEEK deposition partnerships with Swiss orthopedic implant manufacturers absorb low-volume prototyping demand from machining. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down monomer capacity tracking forms the analytical core of this study. Primary interviews with polymerization process engineers, aerospace Tier 1 procurement directors, automotive thermal management specialists, and coatings formulators informed demand segmentation. Secondary validation drew from ECHA REACH substance registrations, EPA TSCA filings, METI industrial statistics, and customs trade data for aromatic monomer flows. Triangulation between consumption-side qualification timelines and supply-side reactor utilization rates anchored volume estimates.
Input-output matrices mapped dianhydride and ketone precursor availability through polyimide and PEEK conversion stages across the projection horizon. Segmentation dimensions encompassed chemistry family, thermal stability tier, certification grade, end-use vertical, and regional production hub. CAGRs derived from elasticity-adjusted demand curves reflecting regulatory compliance cost pass-through and substitution threshold pricing. Forecast inputs included semiconductor packaging film area expansion, electric vehicle battery enclosure resin content per vehicle, and aerospace engine program qualification pipelines.
The model assumes a particular technology adoption path; alternative pathways for additive manufacturing of high temperature thermoplastic composites would alter the outlook if deposition speed and surface finish specifications achieve production-grade thresholds ahead of baseline assumptions. Forecasts reflect documented assumptions about regulatory implementation timelines and carbon intensity accounting methodologies. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Thermoplastic Ester Elastomer (TPEE) Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
Welan Gum Market
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
Thermoplastic Polyolefin Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Asia-Pacific Flooring Resins Market
Polymers & Resins
Hair Styling Biopolymers Market
Polymers & Resins
Polyimide and Imide Polymers Market
Polymers & Resins
Polyisoprene Latex Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Antimicrobial Plastics Market
Polymers & Resins
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market
Polymers & Resins
Europe Polyolefin Market