
 Elastomeric Polyolefins Market | 2026-2036
Elastomeric Polyolefins Market Size, Share, and Industry Trends Forecast 2026-2036
Elastomeric Polyolefins Market Analytics
Software-defined material certification and digital twin validation services is broadening what suppliers monetize beyond resin volumes. Dow Chemical Company leverages integrated catalyst technology to sustain differentiation in metallocene-grade production. ExxonMobil Corporation anchors North American supply through proprietary solution polymerization platforms. Mitsui Chemicals competes on specialized medical-grade formulations with biocompatibility clearances.
Elastomeric polyolefins comprise thermoplastic polymers combining rubber-like elasticity with polyolefin processability, typically produced via metallocene or Ziegler-Natta catalysis with density ranges of 0.85–0.91 g/cm³ and Shore A hardness between 60–90. These materials primarily enable injection-molded seals, flexible tubing, and impact-modified automotive interior surfaces that replace thermoset rubbers and PVC. Thermoplastic elastomers command the widest application breadth across medical devices and automotive components due to recyclability advantages and halogen-free formulations. Polypropylene grades concentrate margin pools in thin-wall packaging and appliance gaskets where flow properties and cycle time reduction justify premium positioning. Amorphous polyolefins occupy niche optical and adhesive layers where clarity and tack balance prove critical.
REACH compliance in Europe and FDA 21 CFR 177.1520 food-contact regulations in the United States shape formulation chemistry by restricting plasticizer migration and specifying extractables thresholds. China's SAMR enforces GB 4806 polymer safety standards that diverge from OECD testing protocols, creating dual-certification burdens for multinational suppliers. South Korea's MFDS maintains separate medical-device polymer registers that delay market entry without local toxicology dossiers. Stakeholders must monitor regulatory divergence between Asian and Western certification regimes when allocating R&D and qualification budgets.
Market Dynamics
Automotive OEMs in Germany and Japan are accelerating thermoplastic elastomer substitution for thermoset rubbers, compressing qualification cycles and forcing resin suppliers to synchronize R&D roadmaps with platform redesign schedules.
Growth Catalysts
- REACH compliance deadlines:ECHA's evolving substance restrictions on plasticizer migration are compelling European automotive Tier-1s to source halogen-free elastomeric polyolefins for interior seals and gaskets.
- Medical device re-shoring:FDA 21 CFR 177.1520 food-contact clearances for specialized grades are enabling domestic tubing production for US-based diagnostic equipment manufacturers.
- Metallocene catalyst diffusion:Solution polymerization platforms with single-site catalysis are improving molecular weight distribution control for thin-wall packaging applications in East Asian manufacturing clusters.
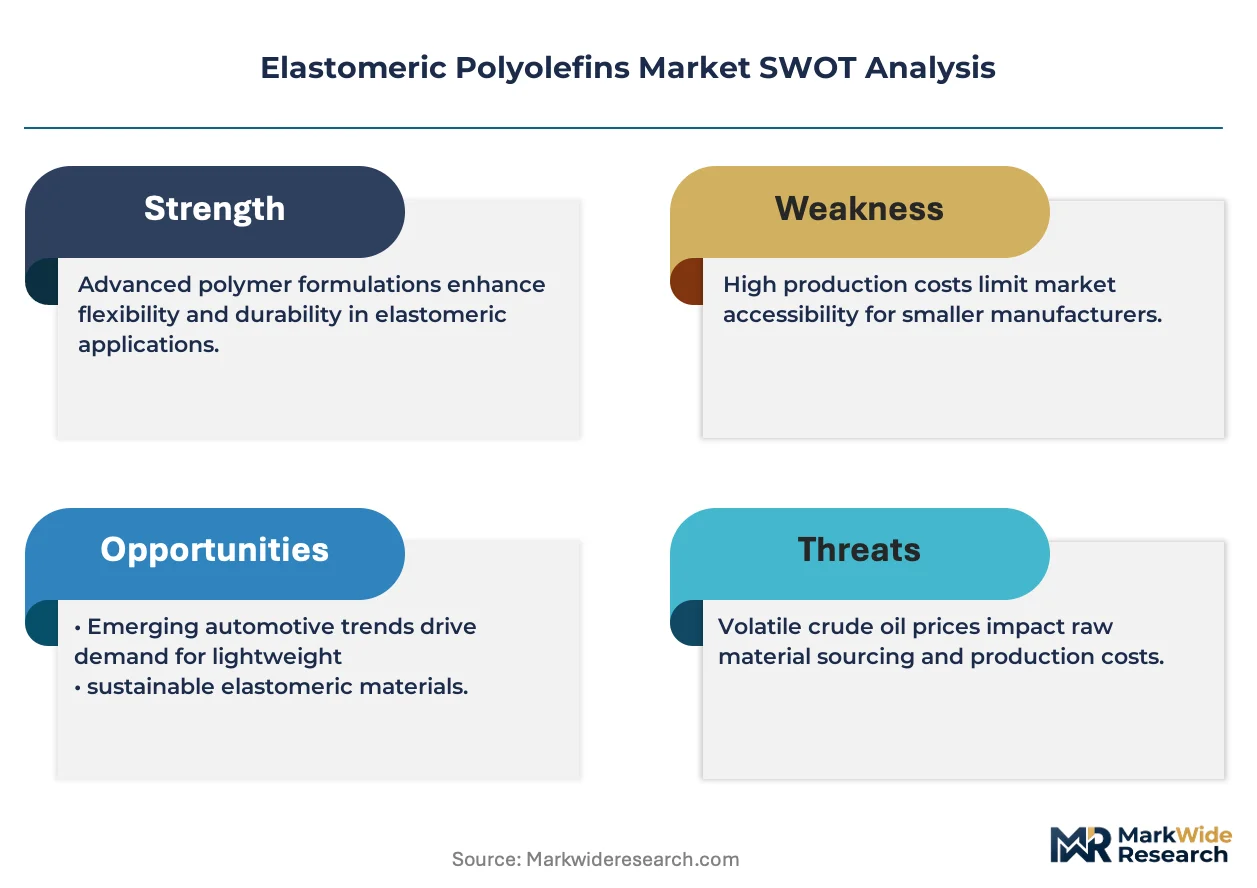
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking margins and shale-gas economics create input cost instability that compresses compounder margins during crude price spikes.
- Supply concentration risk:Specialty medical-grade production concentrates among integrated petrochemical majors with captive catalyst technology, limiting qualified second-source options.
- Performance ceiling in high-temperature applications:Continuous service temperatures above 120°C remain inaccessible to standard thermoplastic elastomer formulations without crosslinked thermoset alternatives.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives are creating localized demand for biocompatibility-cleared elastomeric grades that bypass import dependency.
- Digital twin validation services:Software-defined material certification is integrating with injection-molding simulation platforms, opening recurring revenue streams beyond resin tonnage.
- Optical-grade amorphous polyolefins:Clarity and tack balance in adhesive layers for flexible electronics laminates represents an underpenetrated specification space.
Industry Challenges
- Dual-certification complexity:China's SAMR GB 4806 polymer safety standards diverge from OECD testing protocols, forcing multinational suppliers to maintain parallel toxicology dossiers for identical formulations.
- Metallocene catalyst IP licensing:Proprietary single-site technology remains concentrated among integrated majors, constraining independent compounders from entering premium specification tiers without royalty burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastomeric Polyolefins Market |
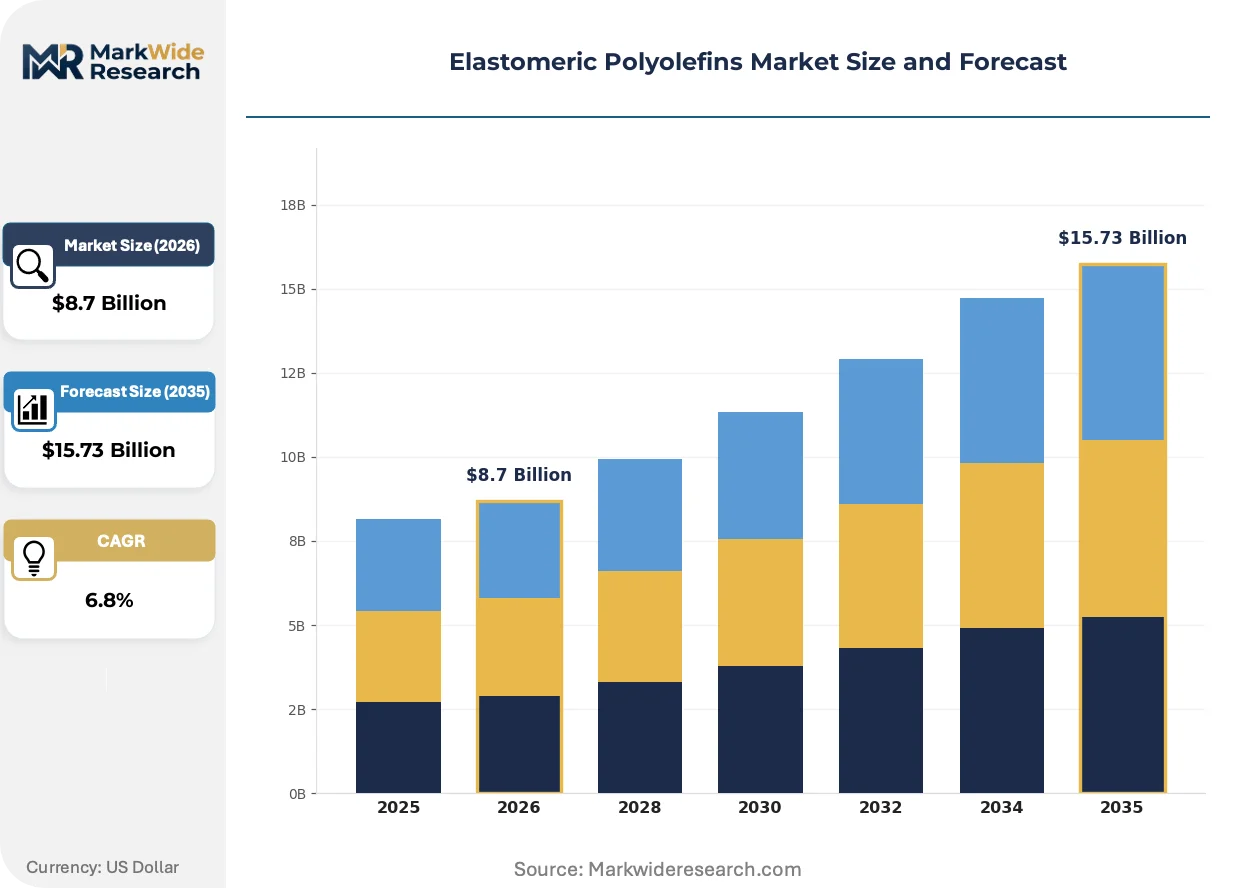
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amorphous Polyolefins, Thermoplastic Elastomers, Polyethylene, Polypropylene Application: Automotive Components, Medical Devices, Consumer Goods, Industrial Applications End User: Manufacturers, Distributors, OEMs, Retailers Delivery Mode: Bulk, Totes, Drums, Pallets |
| Companies Covered | Dow Chemical Company, ExxonMobil Corporation, Mitsui Chemicals, LG Chem, SABIC, LyondellBasell Industries, Mitsubishi Chemical Holdings, Sumitomo Chemical, PolyOne Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastomeric Polyolefins Market Evolving Landscape
Digital validation workflows and regulatory chemistry restrictions are converging to redefine how material suppliers capture value, shifting monetization from commodity resin volumes toward certified formulation services.
Advanced metallocene catalysis is integrating with real-time rheology monitoring during extrusion, enabling automotive seal manufacturers to reduce scrap rates and tighten hardness tolerances. Tier-1 suppliers in South Korea's Ulsan corridor are adopting these closed-loop systems for just-in-time interior component production. The technology is compressing traditional batch-release testing timelines into continuous process verification.
EU REACH substance restrictions on phthalate plasticizers are forcing reformulation of legacy PVC alternatives across European appliance gasket applications. Compounders must resubmit technical dossiers to ECHA for modified extractables profiles. Medical tubing manufacturers serving the European market face the steepest requalification burdens due to biocompatibility revalidation requirements.
Specification-driven procurement is consolidating buyer power among automotive platform integrators who now demand resin suppliers pre-certify grades against multiple OEM material standards simultaneously. This behavior compresses supplier qualification timelines and raises barriers for specialty compounders without dedicated regulatory affairs capacity. The shift is most visible in German automotive supply chains where Volkswagen, BMW, and Mercedes-Benz coordinate material approval processes through shared industry databases.
Elastomeric Polyolefins Market Segmentation
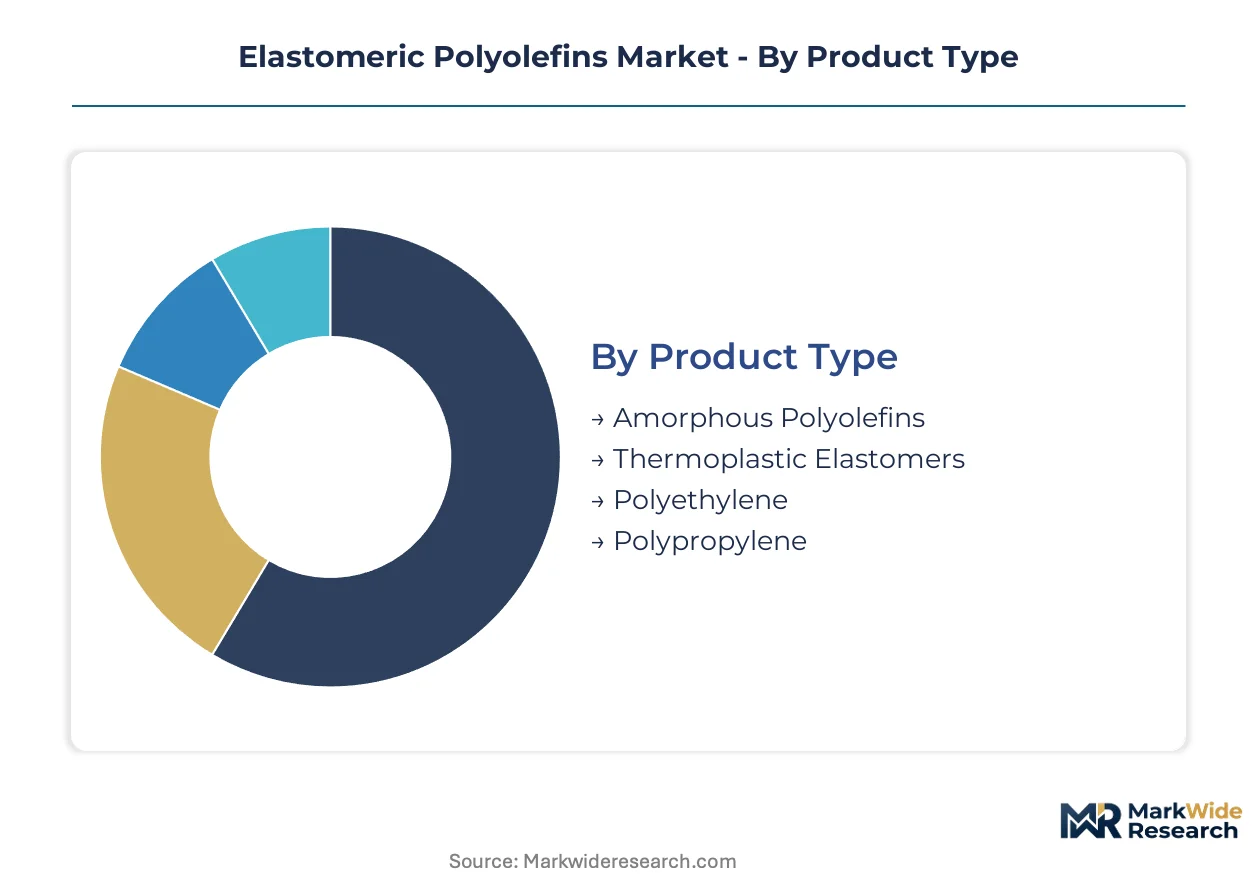
Segmentation in elastomeric polyolefins reveals how specification intensity varies with end-use criticality. Medical and automotive applications demand certified grades with full toxicology dossiers, while industrial buyers prioritize volume throughput and packaging flexibility.
Product Type:
Standardization dominates commodity polyolefins, but customization intensity escalates toward specialty elastomer grades with catalyst-controlled molecular architecture.
- Thermoplastic Elastomers:These polymers combine rubber-like elasticity with thermoplastic processability, typically produced via metallocene or Ziegler-Natta catalysis with Shore A hardness between 60–90. Demand concentrates in German and Japanese automotive supply chains where OEMs substitute thermoset rubbers for recyclable interior seals and gaskets, driven by REACH plasticizer restrictions.
- Polypropylene:Semi-crystalline grades with controlled melt flow rates enable thin-wall packaging and appliance gasket applications where cycle time reduction justifies premium positioning. South Korea's Ulsan petrochemical corridor hosts the densest concentration of injection-molding compounders serving East Asian appliance manufacturers.
- Amorphous Polyolefins:Low-crystallinity grades with optical clarity and surface tack serve adhesive layer applications in flexible electronics laminates.
- Polyethylene:Density-modified grades from 0.85–0.91 g/cm³ provide cost-positioned alternatives for general-purpose tubing and non-critical seals.
Most installed capacity flows through Polypropylene. Expansion is steepest in Thermoplastic Elastomers.
Application:
Regulatory burden intensity separates medical and automotive tiers from industrial and consumer segments with lighter certification requirements.
- Automotive Components:Interior seals, gaskets, and impact-modified surfaces represent the highest-volume specification tier. German OEMs coordinate material approvals through shared industry databases, compressing supplier qualification timelines for halogen-free formulations.
- Medical Devices:Tubing, diagnostic equipment housings, and flexible connectors require FDA 21 CFR 177.1520 clearances and biocompatibility validation. US-based diagnostic equipment manufacturers are reshoring production, creating localized demand for certified grades.
- Consumer Goods:Appliance gaskets and flexible packaging applications prioritize cost efficiency over certification depth.
- Industrial Applications:General-purpose seals and conveyor components tolerate broader specification tolerances with faster procurement cycles.
Automotive Components anchor current volume. Medical Devices are climbing the fastest as re-shoring accelerates domestic qualification programs.
End User:
Technical capability and regulatory sophistication determine procurement behavior across buyer categories.
- OEMs:Platform integrators in automotive and medical device sectors demand pre-certified grades against multiple material standards simultaneously, consolidating supplier power.
- Manufacturers:Tier-1 component producers in South Korea and Germany adopt closed-loop rheology monitoring systems for just-in-time production.
- Distributors:Inventory-holding intermediaries serve smaller compounders without direct resin supplier relationships.
- Retailers:Minimal direct engagement; limited to specialty grades for aftermarket repair segments.
Procurement concentration sits with OEMs. Distributors are gaining share fastest among mid-tier compounders seeking supply security.
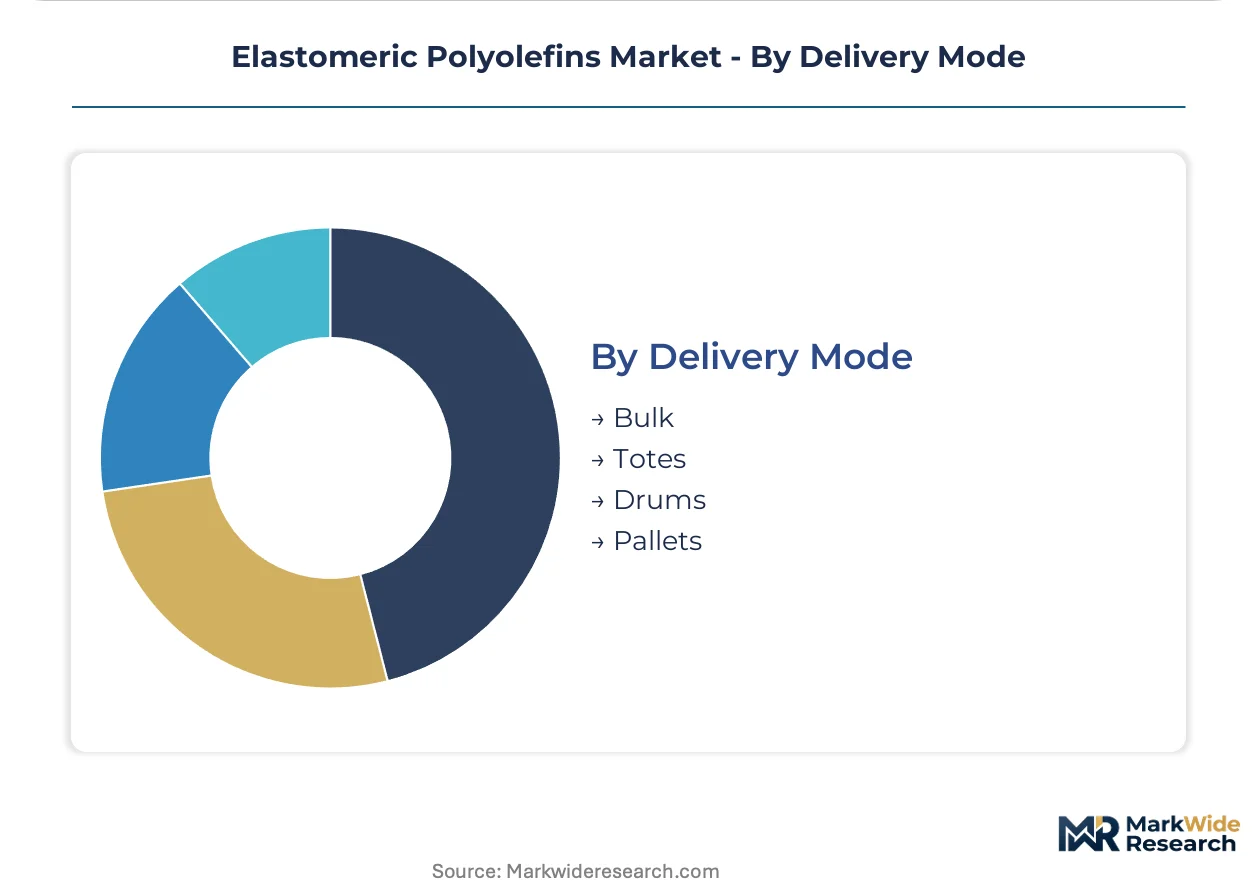
Delivery Mode:
Packaging economics and handling infrastructure shape logistics configuration across customer scales.
- Bulk:Railcar and tanker deliveries serve high-volume automotive and appliance manufacturers with dedicated unloading infrastructure near Ulsan and German industrial corridors.
- Totes:Intermediate bulk containers balance flexibility with unit economics for mid-tier compounders.
- Drums:Standardized containers support specialty medical-grade shipments requiring lot-traceability and contamination control.
- Pallets:Boxed and bagged formats enable small-lot procurement for R&D sampling and niche formulation trials.
Bulk shipments dominate tonnage. Totes are expanding most quickly as regional compounding capacity fragments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing production maps as manufacturers relocate to jurisdictions with streamlined certification pathways. Cost-of-compliance gaps between REACH-regulated Europe and Asia's evolving standards are accelerating capacity shifts toward East Asian petrochemical corridors.
China
SAMR's GB 4806 polymer safety standards enforce extractables thresholds that diverge from OECD protocols, forcing dual-certification investments. The Yangtze River Delta hosts compounding facilities serving domestic appliance manufacturers seeking halogen-free gasket materials. Shanghai-based laboratories now process parallel toxicology dossiers for export-bound formulations.
Germany
Automotive OEMs coordinate material approvals through shared industry databases, compressing supplier qualification timelines. ECHA's evolving plasticizer restrictions under REACH are compelling Tier-1s to source certified elastomeric grades for interior seals. The Ruhr industrial corridor concentrates injection-molding compounders serving Volkswagen, BMW, and Mercedes-Benz platform redesigns.
United States
FDA 21 CFR 177.1520 food-contact clearances enable domestic tubing production for reshoring diagnostic equipment manufacturers. EPA oversight of polymer manufacturing emissions shapes facility siting decisions. The Gulf Coast petrochemical corridor near Houston anchors metallocene-grade production with integrated catalyst technology and shale-gas feedstock access.
Japan
METI promotes lightweight material adoption in automotive supply chains through targeted R&D subsidies. PMDA maintains stringent biocompatibility validation requirements for medical-grade polymer imports. The Nagoya-Toyota industrial corridor concentrates thermoplastic elastomer demand for interior component substitution programs.
South Korea
MFDS operates separate medical-device polymer registers that delay market entry without local toxicology dossiers. The Ulsan petrochemical corridor hosts the densest concentration of closed-loop rheology monitoring systems for just-in-time automotive seal production. Busan-based compounders serve export markets with pre-certified grades against multiple OEM standards.
Elastomeric Polyolefins Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical majors commanding premium specification tiers through captive catalyst technology. The market structure concentrates qualified production among integrated majors with proprietary solution polymerization platforms, while independent compounders compete on volume throughput in industrial segments. Three archetypes dominate: integrated majors with metallocene IP, regional compounders with formulation flexibility, and distributors with inventory-holding scale. Competitive moves center on capacity expansion in East Asian corridors and strategic partnerships for digital twin validation services.
Among integrated petrochemical majors, Dow Chemical Company and ExxonMobil Corporation exemplify the technology-licensing archetype with proprietary catalysis platforms, while Mitsui Chemicals occupies a position within the medical-grade specialization tier. These anchors demonstrate how geographic origin and corporate structure map to competitive positioning: US-based majors leverage shale economics, Japanese specialists pursue biocompatibility clearances, and Korean conglomerates integrate backward into catalyst production.
| Leading Market Players |
|---|
| Dow Chemical Company |
| ExxonMobil Corporation |
| Mitsui Chemicals |
| LG Chem |
| SABIC |
| LyondellBasell Industries |
| Mitsubishi Chemical Holdings |
| Sumitomo Chemical |
| PolyOne Corporation |
| Others |
Value Network & Pricing Analysis
REACH plasticizer restrictions gate qualified supply and premium-tier pricing access for elastomeric polyolefins, forcing compounders to absorb dual-certification costs for ECHA-compliant grades while OEMs in Germany and Japan consolidate procurement around pre-certified suppliers with captive metallocene technology.
Pricing Analysis
Capacity additions in South Korea's Ulsan corridor are reshaping price floors for standard thermoplastic elastomer grades. Three-tier pricing structure across medical-certified, automotive-grade, and industrial economy levels separates biocompatibility-cleared formulations from commodity alternatives. Cost compression in industrial polyethylene tiers is intensifying because naphtha-cracking margin volatility feeds into compounder input costs. Appliance manufacturers in East Asian clusters exhibit the highest price sensitivity, while medical device OEMs tolerate premium positioning for FDA-cleared tubing grades.
Supply Chain Analysis
Freight differentials between bulk railcar deliveries and drum shipments for medical-grade lots compress margins for mid-tier compounders without dedicated logistics infrastructure. Supply concentrates in South Korea, Germany, and the United States Gulf Coast, with each hub anchoring distinct specification tiers. Feedstock draws from propylene monomer streams and metallocene catalyst supplies, both tethered to integrated petrochemical majors with proprietary polymerization platforms. Single-source vulnerability in medical-grade catalyst technology creates qualification bottlenecks. Distribution runs through direct mill relationships for high-volume automotive Tier-1s and regional distributors serving fragmented compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Elastomeric polyolefins function as a stable compounder market, with automotive lightweighting mandates and medical device re-shoring providing durable demand foundations across the analysis window.
For Market Incumbents: Extend certification coverage across divergent regulatory regimes to defend against specialty compounders exploiting dual-dossier complexity. Backward integration into captive catalyst production protects margin pools in metallocene-grade tiers where IP licensing constraints limit independent competitors. Capacity expansion in India's PLI-subsidized medical device corridor captures localized demand before import substitution matures.
For New Entrants and Emerging Players: The gap between premium medical-grade pricing and economy industrial tiers creates entry space for mid-market compounders with flexible formulation capabilities. Target optical-grade amorphous polyolefins for flexible electronics laminates, an underpenetrated specification segment lacking entrenched suppliers. Partner with digital twin validation platforms to offer certified formulation services rather than commodity resin volumes.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounders with formulation flexibility but without dedicated regulatory affairs capacity. Long-term viability hinges on exposure to medical and automotive end-uses with recertification cycles that sustain recurring revenue. Watch for inflection where India's domestic medical device production crosses threshold scale, triggering localized polymer demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Metallocene Capacity Expansion | Integrated majors in Ulsan and Houston anchor premium-grade supply with proprietary catalyst technology. |
| Backward Integration into Catalyst Production | Korean conglomerates reduce royalty burdens and tighten molecular architecture control for medical formulations. |
| Digital Twin Validation Partnership | Software-defined certification services shift monetization from tonnage to recurring formulation subscriptions. |
| Dual-Certification Infrastructure Investment | Parallel toxicology dossiers for China's SAMR and ECHA unlock access to both Asian and European OEM supply chains. |
| Localized Compounding in India | PLI scheme subsidies for medical device manufacturing create captive demand for biocompatibility-cleared grades. |
Research Methodology
Direct dialogue with polymer plant managers, automotive Tier-1 procurement leads, medical device regulatory affairs directors, and distribution channel partners grounded the qualitative assessment. Secondary validation drew from customs trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated petrochemical majors, and SAMR GB standard documentation. Bottom-up segment sizing triangulated against top-down production capacity estimates across the analysis window.
Segment-level outputs across product type, application intensity, end-user procurement sophistication, and regional regulatory clustering fed into the analytical framework. CAGRs were derived from elasticity-adjusted demand projections incorporating automotive platform redesign cycles and medical device re-shoring trajectories. Feedstock cost scenarios and catalyst diffusion curves provided industry-specific forecast inputs.
Caveats apply where propylene feedstock volatility, REACH substance restriction amendments, or India's PLI scheme implementation pace could materially shift the outlook. Forecasts reflect documented assumptions about regulatory harmonization timelines and OEM qualification cycle compression. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
Rubber Membrane Market
Elastomeric Membrane
Styrene Ethylene Butylene Styrene (SEBS) Market
Elastomeric Membrane
South America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Polysulfide Elastomers Market
Elastomeric Membrane
Middle-East and Africa Fluoroelastomers Market
Elastomeric Membrane
North America Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
Specialty Elastomer Market
Elastomeric Membrane
Global Fluoroelastomers Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
Global Acrylic Elastomers Market
Elastomeric Membrane
Thermo Elastic Acrylic Market