
 Ethylene Propylene Diene Monomer(EPDM) Market | 2026-2036
Ethylene Propylene Diene Monomer(EPDM) Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene Propylene Diene Monomer(EPDM) Market Analysis
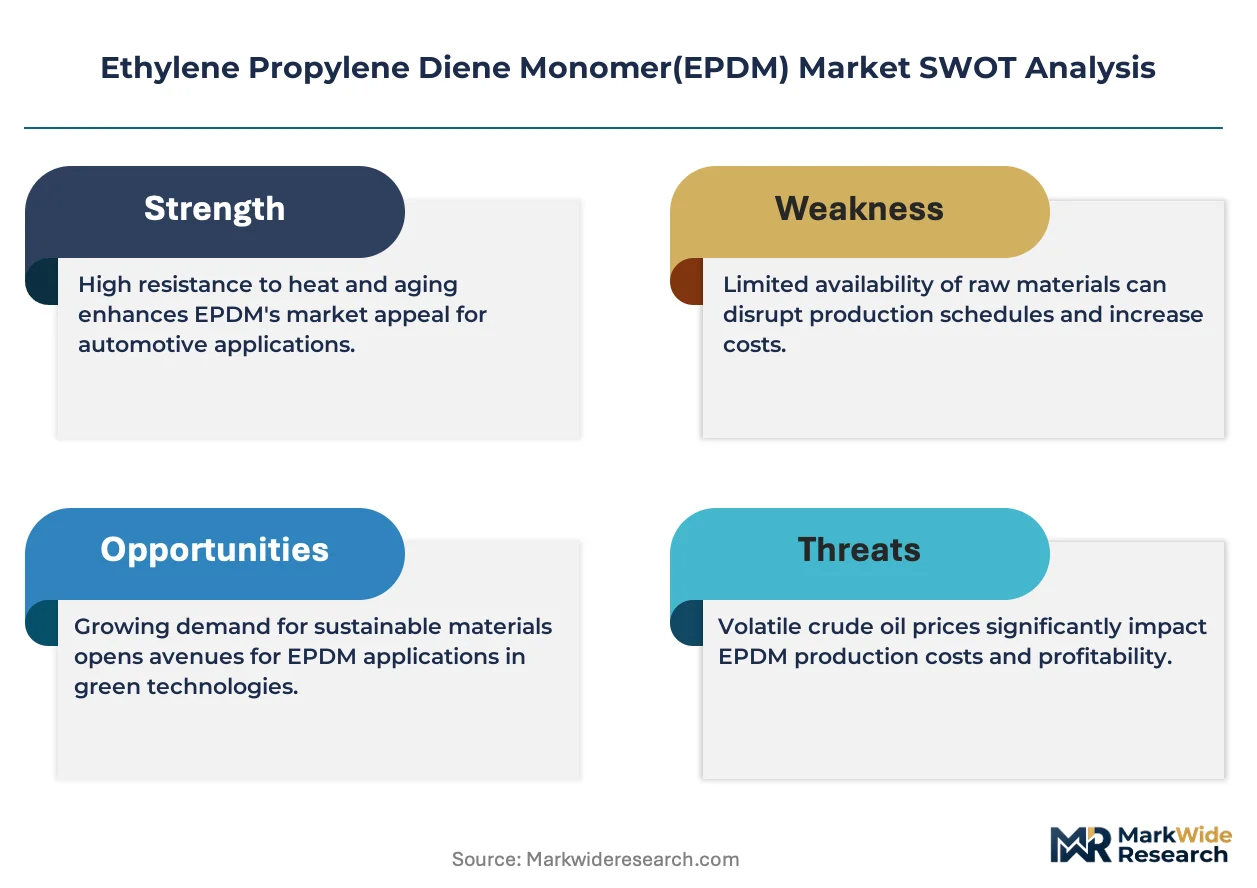
Advanced polymer compounding is tilting EPDM formulation toward higher ethylene content and tailored diene levels for specific vulcanization performance. ExxonMobil Corporation leverages its integrated feedstock position to sustain cost-competitive supply of specialty EPDM grades across multiple continents. Dow anchors its market presence through deep expertise in metallocene catalyst technology, while Kumho Polychem competes aggressively on volume in the Asia-Pacific construction segment.
Ethylene Propylene Diene Monomer is a synthetic elastomer synthesized via Ziegler-Natta or metallocene coordination polymerization, typically containing 45-75% ethylene, 25-55% propylene, and 2-12% non-conjugated diene termonomer to enable sulfur vulcanization. Its saturated main chain delivers exceptional ozone resistance, thermal stability, and electrical insulation properties, making it indispensable for automotive sealing systems, roofing membranes, and cable jacketing. Solid EPDM dominates volume consumption in automotive weatherstrip and hose applications where compression set resistance commands premium positioning. Liquid EPDM represents the fastest-growing product format, penetrating industrial coatings and adhesive formulations that demand sprayable or castable elastomer systems.
EPA regulations under the Toxic Substances Control Act and OSHA workplace exposure standards shape permissible monomer residuals and processing emissions in United States manufacturing facilities. REACH registration requirements and RoHS compliance directives in Europe restrict certain curing system additives while mandating full supply chain disclosure for EPDM compounds used in electrical and electronic equipment. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as pressure builds to certify EPDM formulations as PFAS-free alternatives in critical sealing applications.
Market Dynamics
EPDM formulation chemistry is pivoting toward higher ethylene content and tailored diene levels as automotive OEMs demand compression set resistance for next-generation sealing systems. This structural shift in polymer architecture is redrawing competitive advantage across the synthetic rubber value chain.
Growth Catalysts
- Automotive lightweighting mandates:NHTSA fuel economy standards in the United States are accelerating EPDM substitution for heavier thermoset alternatives in underhood hose and weatherstrip applications.
- REACH-compliant curing systems:ECHA restrictions on conventional accelerators are pulling demand toward peroxide-cured EPDM grades with lower volatile organic compound emissions.
- Infrastructure polymerization:China's state-led urban renewal programs are sustaining consumption of solid-grade EPDM for roofing membrane and waterproofing systems.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics and refinery output swings create margin compression for non-integrated compounders without captive ethylene supply.
- Geographic supply concentration:Northeast Asian producers control disproportionate share of merchant EPDM capacity, creating disruption risk for European and North American formulators.
- Thermoplastic vulcanizate substitution:TPV materials are capturing select automotive sealing applications where recyclability and processing speed outweigh EPDM's compression set performance.
Strategic Opportunities
- India construction vertical:BIS certification requirements for building envelope materials are creating pull for EPDM membrane systems in commercial roofing and civil infrastructure projects.
- Liquid EPDM coatings:Sprayable elastomer formulations are penetrating industrial maintenance and marine coating segments previously served by solvent-based systems.
- PFAS-free certification:EPA and state-level restrictions on per- and polyfluoroalkyl substances are opening positioning for EPDM as a verified fluorine-free sealing alternative.
Industry Challenges
- Metallocene catalyst expertise scarcity:Formulation chemists capable of tailoring molecular weight distribution for niche applications command premium compensation and limited mobility.
- Multi-jurisdiction compliance synchronization:Simultaneous REACH, RoHS, and evolving EPA Toxic Substances Control Act filings strain regulatory affairs bandwidth at mid-sized compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene Propylene Diene Monomer(EPDM) Market |
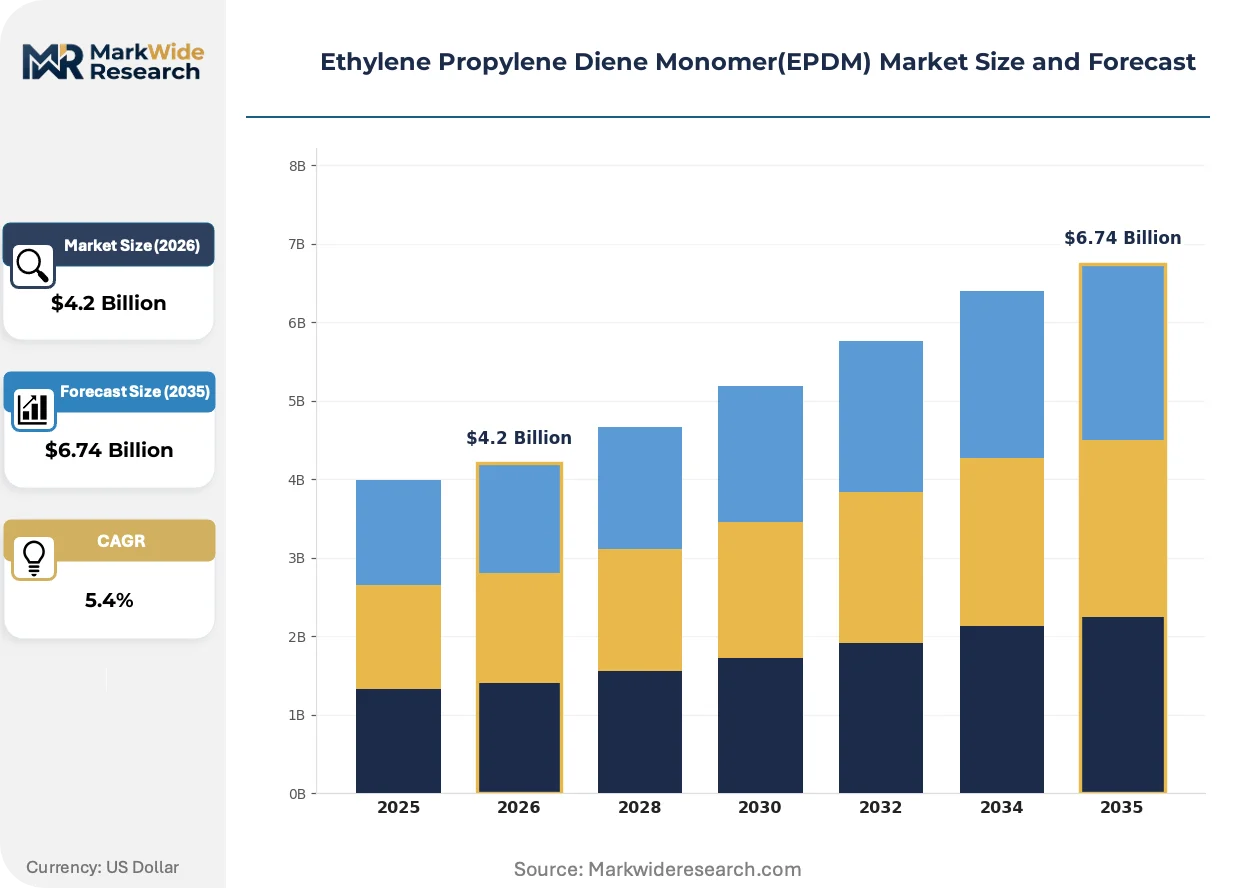
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.74 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Granule, Powder Application: Automotive Parts, Roofing Membranes, Electrical Insulation, Hose End User: Construction, Automotive, Manufacturing, Electronics Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | ExxonMobil Corporation, Dow, ARLANXEO, Kumho Polychem, Versalis S.p.A., Mitsui Chemicals, Inc., PetroChina Company Limited, Lion Elastomers, SK geo centric Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene Propylene Diene Monomer(EPDM) Market Emerging Trajectories
EPDM production technology and application engineering are converging around sustainability verification, advanced catalyst control, and demand-pattern reconfiguration across automotive and construction verticals.
Metallocene catalyst platforms are migrating from specialty grade production toward broader commercial EPDM volumes. Tier 1 automotive suppliers are qualifying these materials for coolant hose and dynamic sealing applications where batch-to-batch consistency reduces downstream scrap rates. The technology is migrating from niche positioning toward mainstream adoption as integrated producers scale reactor throughput.
REACH registration requirements and RoHS compliance directives in Europe are tightening disclosure obligations for diene termonomer residuals and curing system additives. Compounders serving electrical equipment OEMs must now document full supply chain composition for cable jacketing grades. German automotive suppliers are responding by consolidating qualified material sources to reduce audit burden.
Automotive OEMs are compressing material qualification cycles and unbundling compound supply from finished part contracts. Tier 2 formulators in the United States are gaining direct specification authority previously held by integrated system suppliers. This pattern is most visible in electric vehicle platform launches where thermal management hose architectures require rapid iteration cycles.
Ethylene Propylene Diene Monomer(EPDM) Market Segmentation
EPDM segmentation reflects divergent technical requirements across automotive sealing, construction waterproofing, and electrical insulation. Product format, application severity, and end-user procurement patterns each create distinct specification tiers that compounders must navigate.
Product Type:
Mature solid grades anchor volume consumption while emerging liquid formats reshape application possibilities.
- Solid:Dense rubber bales with 45-75% ethylene content deliver compression set resistance for automotive weatherstrip and coolant hose systems. Tier 1 suppliers in Germany and the United States specify solid EPDM for underhood applications where NHTSA durability standards mandate 15-year service life.
- Liquid:Low-viscosity polymers enable sprayable and castable elastomer systems without solvent carriers. Industrial maintenance coatings in marine and infrastructure sectors adopt liquid EPDM for seamless membrane application where substrate access limits solid rubber installation.
- Granule:Pre-dispersed pellets accelerate mixing cycles for high-volume compounders serving roofing membrane producers.
- Powder:Fine particle grades penetrate adhesive and sealant formulations requiring rapid incorporation into solvent or water-based systems.
Solid EPDM retains volume leadership; liquid EPDM holds the steepest expansion curve.
Application:
Cost tier differentiation separates commodity construction membranes from precision-engineered automotive components.
- Automotive Parts:Dynamic seals, coolant hoses, and brake system components demand peroxide-cured grades with low compression set. OEM thermal management architectures for electric vehicles specify EPDM coolant hoses that withstand glycol exposure across -40°C to 150°C operating windows.
- Roofing Membranes:Single-ply sheet systems utilize carbon-black-reinforced EPDM for UV resistance and puncture tolerance. China's state-led urban renewal programs sustain membrane demand for commercial building envelopes.
- Electrical Insulation:Cable jacketing grades require RoHS-compliant curing systems with full supply chain disclosure for European electrical equipment OEMs.
- Hose:Industrial and automotive tubing applications balance oil resistance flexibility against steam and ozone degradation tolerance.
Automotive Parts commands premium pricing tiers; Roofing Membranes generates the broadest geographic footprint.
End User:
Customer type determines specification authority and procurement complexity across the value chain.
- Construction:Roofing contractors and civil engineers specify membrane systems where BIS certification in India and local fire codes dictate compound selection.
- Automotive:Tier 1 system suppliers and emerging Tier 2 formulators qualify materials against OEM material performance standards.
- Manufacturing:Industrial gasket and hose producers purchase standard grades through distributor networks with technical service support.
- Electronics:Cable and connector OEMs impose restricted substance documentation exceeding baseline REACH requirements.
Construction sustains the deepest volume base; Automotive extracts the highest margin realization.
Distribution Channel:
Supply concentration shapes channel economics and technical service intensity.
- Direct Sales:Integrated producers supply automotive OEMs and major roofing membrane manufacturers under long-term offtake agreements with embedded technical collaboration.
- Distributors:Regional stocking distributors serve mid-sized compounders with just-in-time delivery and formulation support.
- Online:Digital procurement platforms penetrate standard-grade spot purchases for small-batch industrial applications.
- Retail:Limited penetration through construction supply outlets for specialty repair and maintenance quantities.
Direct Sales captures the largest contract values; Distributors maintains the widest account coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean EPDM producers export substantial volumes to automotive compounders in Germany and the United States, reflecting the concentration of premium sealing applications in these end-markets. This trade corridor shapes regional capacity allocation and technical specification flows across the synthetic rubber value chain.
China
State-led urban renewal programs and electric vehicle platform launches sustain solid-grade EPDM consumption for roofing membranes and coolant hose systems. MIIT emission standards for automotive materials tighten monomer residual limits in manufacturing facilities. The Yangtze River Delta hosts integrated polymer plants supplying domestic automotive OEMs and construction material producers.
United States
NHTSA fuel economy standards accelerate EPDM substitution for heavier thermoset alternatives in underhood applications. EPA regulations under the Toxic Substances Control Act shape permissible processing emissions and workplace exposure standards. The Gulf Coast petrochemical corridor anchors merchant EPDM production with captive ethylene feedstock integration.
Germany
REACH registration requirements and RoHS compliance directives restrict curing system additives while mandating full supply chain disclosure. ECHA restrictions on conventional accelerators pull demand toward peroxide-cured grades with lower volatile organic compound emissions. The Rhine-Ruhr industrial region concentrates automotive sealing system compounders serving premium OEM platforms.
Japan
METI industrial standards for electrical insulation materials sustain cable jacketing demand with full material composition documentation. JIS certification requirements for building envelope products create specification barriers for imported membrane systems. The Chubu region around Nagoya hosts precision rubber compounders serving automotive and electronics OEMs.
India
BIS certification requirements for commercial roofing and civil infrastructure projects create pull for EPDM membrane systems in building envelope applications. The country's national construction regulator mandates fire performance testing for polymer-based waterproofing materials. Gujarat's chemical manufacturing belt hosts emerging compounding facilities serving domestic automotive and construction verticals.
Ethylene Propylene Diene Monomer(EPDM) Market Vendor Landscape
Channel-controlling players compete with product-specialist players across differentiated specification tiers. Integrated petrochemical groups with captive ethylene supply anchor volume positions in automotive and construction segments. Three archetypes dominate: feedstock-integrated majors leveraging coordination polymerization expertise, regional volume specialists competing on construction-grade pricing, and technology-focused compounders serving electrical insulation niches. Capacity expansion and metallocene catalyst licensing represent the dominant competitive vectors reshaping supply-side positioning.
Within the feedstock-integrated tier, ExxonMobil Corporation and Dow exemplify archetypes built on upstream control and catalyst technology specialization respectively. Kumho Polychem occupies a position representing Asia-Pacific volume competition in construction applications. These three anchors illustrate how geographic origin and corporate structure map to strategic positioning without requiring specific product or technology claims.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Dow |
| ARLANXEO |
| Kumho Polychem |
| Versalis S.p.A. |
| Mitsui Chemicals, Inc. |
| PetroChina Company Limited |
| Lion Elastomers |
| SK geo centric Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor carries EPDM bales and compound shipments that absorb bunker fuel volatility and canal transit fees, compressing margins for European compounders while amplifying price spreads between feedstock-integrated majors and merchant buyers dependent on spot resin purchases.
Pricing Analysis
Metallocene-catalyzed EPDM commands a 15-20% premium over conventional Ziegler-Natta grades, while liquid EPDM formats trade at elevated unit costs reflecting specialized reactor control and downstream formulation support. Three-tier pricing structure across premium, standard, and economy levels separates peroxide-cured automotive grades from construction-grade solid compounds and commodity roofing membrane resins. Pricing pressure stems from propylene feedstock volatility and naphtha-cracking economics, eroding compounder margins in Europe and North America. Construction segment buyers exhibit the highest price sensitivity, while automotive OEMs prioritize batch consistency and technical service over unit cost.
Supply Chain Analysis
Extended payment terms from South Korean producers to German automotive compounders reflect supply-chain finance facilities that lock in volume commitments across the 90-120 day production cycle. Production concentrates in China, South Korea, and the United States, with the Yangtze River Delta and Ulsan industrial corridor anchoring Asian capacity. Feedstock dependencies center on ethylene from naphtha crackers, propylene from FCC units, and ENB or DCPD diene termonomers from specialty chemical producers. Single-source vulnerability persists for metallocene catalyst systems licensed to limited reactor operators. Distribution runs through direct sales for automotive OEMs and regional distributors serving construction compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPDM market fragmentation creates niches as automotive OEMs unbundle compound supply from finished part contracts and electric vehicle platforms demand rapid material iteration cycles.
For Market Incumbents: Pre-empt thermoplastic vulcanizate substitution in automotive sealing by qualifying next-generation peroxide-cured grades with compression set performance below 15%. Secure captive ethylene supply through backward integration into Gulf Coast or Middle Eastern feedstock positions. Consolidate qualified material sources to reduce REACH audit burden for European electrical equipment customers. For New Entrants and Emerging Players: Establish a beachhead in India's BIS-certified construction membrane segment where domestic compounding capacity lags infrastructure investment growth. Target liquid EPDM coatings for marine maintenance applications previously served by solvent-based systems. Differentiate through PFAS-free certification and rapid supply chain disclosure protocols for European electronics OEMs. For Investors and Strategic Acquirers: Technology-focused compounders with metallocene catalyst expertise and established automotive qualification records represent the most defensible acquisition profile. Long-term viability hinges on positioning for electric vehicle thermal management hose architectures and PFAS-free sealing alternatives. Monitor EPA state-level restrictions on per- and polyfluoroalkyl substances as inflection indicators for EPDM demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Metallocene Catalyst Licensing | Enables batch-to-batch consistency for Tier 1 automotive coolant hose specifications. |
| Backward Integration into Ethylene | Captures margin compression from naphtha-cracking volatility for non-integrated compounders. |
| PFAS-Free Certification Program | Positions EPDM as verified fluorine-free alternative for EPA-regulated sealing applications. |
| Long-Term Supply Agreement | Locks in volume commitments from Chinese state-led urban renewal membrane programs. |
| Joint Venture in India | Addresses BIS certification barriers for commercial roofing and civil infrastructure projects. |
Methodological Framework
Operator-level perspectives from EPDM plant managers, Tier 1 automotive procurement leads, roofing membrane technical directors, and distribution channel partners anchored the qualitative base. Primary interviews combined with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and MIIT emission standard disclosures. Bottom-up segment modeling and top-down macroeconomic triangulation ensured cross-verification of volume and value estimates.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning grade tier, end-use industry, product format, and regional production hub. CAGRs derived from historical trajectory analysis and forward-looking capacity-expansion schedules. Modeled inputs included automotive platform launch timelines, electric vehicle thermal management content per vehicle, and infrastructure investment flows from China's state-led urban renewal programs.
Sensitivities concentrate around propylene feedstock volatility, REACH accelerator restrictions, and thermoplastic vulcanizate substitution rates in automotive sealing. Forecasts reflect documented assumptions on catalyst technology adoption curves and regional capacity utilization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Elastomeric Membrane Market
Elastomeric Membrane
Ethylene Propylene Elastomers Market
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
Elastic Laminates Market
Elastomeric Membrane
Polyisoprene Elastomers Market
Elastomeric Membrane
Elastomeric Polyolefins Market
Elastomeric Membrane
Polyurethane Elastomers Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
Global Elastomeric Coating Market
Elastomeric Membrane
Modified Silicone Fluids Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Polysulfide Elastomers Market