
 Asia-Pacific Thermoplastic Elastomer (TPE) Market | 2026-2036
Asia-Pacific Thermoplastic Elastomer (TPE) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Thermoplastic Elastomer (TPE) Market Outlook
Bio-based feedstock integration is reconfiguring polymer formulation roadmaps across the Asia-Pacific TPE value chain. BASF SE leverages its Ludwigshafen-derived R&D pipeline to anchor premium thermoplastic polyurethane development for medical-grade films. LG Chem sustains Korean domestic supply security through backward integration into polyol precursors at its Yeosu complex. China Petroleum & Chemical Corporation dominates styrenic block copolymer volume through captive butadiene supply from its Sinopec refining network.
Thermoplastic elastomers combine rubber-like elasticity with thermoplastic processability, enabling injection molding and extrusion without vulcanization, typically operating across Shore A 20 to Shore D 70 hardness ranges. These materials serve as drop-in replacements for thermoset rubber in sealing, cushioning, and flexible structural applications where manufacturing cycle time reduction matters. Styrenic block copolymers occupy the mature volume tier, supplying commodity automotive interior skins and footwear midsoles where margin compression is structural. Thermoplastic vulcanizates represent the fastest-growing product category, penetrating under-hood automotive ducts and industrial hose segments that demand heat resistance above 120°C. Thermoplastic polyurethanes concentrate margin pools in healthcare films and protective coatings where optical clarity and biocompatibility certification command price premiums.
China's SAMR enforces GB standards for automotive interior VOC emissions that restrict plasticizer migration, directly shaping TPE compound formulation requirements for domestic OEM supply. Japan's METI promotes circular economy material flows through its Resource Circulation Strategy, creating compliance obligations for post-industrial TPE scrap recovery in automotive supply chains. South Korea's MFDS regulates skin-contact medical device polymers, establishing biocompatibility testing protocols that filter market access for healthcare-grade TPE entrants. Stakeholders must monitor how China's dual carbon goals tighten upstream petrochemical feedstock allocations, as this will determine regional cost competitiveness between bio-based and conventional TPE routes.
Market Dynamics
Automotive lightweighting mandates across Japan, South Korea, and China are compressing substitution cycles for conventional rubber and rigid plastics, forcing compounders to certify grades faster than historical development timelines permitted.
Growth Catalysts
- China's GB emission standards:Tightening VOC limits for vehicle interiors force domestic OEMs to source certified low-migration TPE compounds, expanding qualified supplier lists.
- Thermoplastic vulcanizate heat resistance:Penetration into under-hood ducts and charge-air cooler hoses above 120°C opens segments previously locked by thermoset rubber performance floors.
- Shanghai-Guangzhou supplier clustering:Tier-one automotive seating and sealing manufacturers concentrate procurement decisions in China's eastern manufacturing corridor, accelerating regional volume aggregation.
Market Restraints
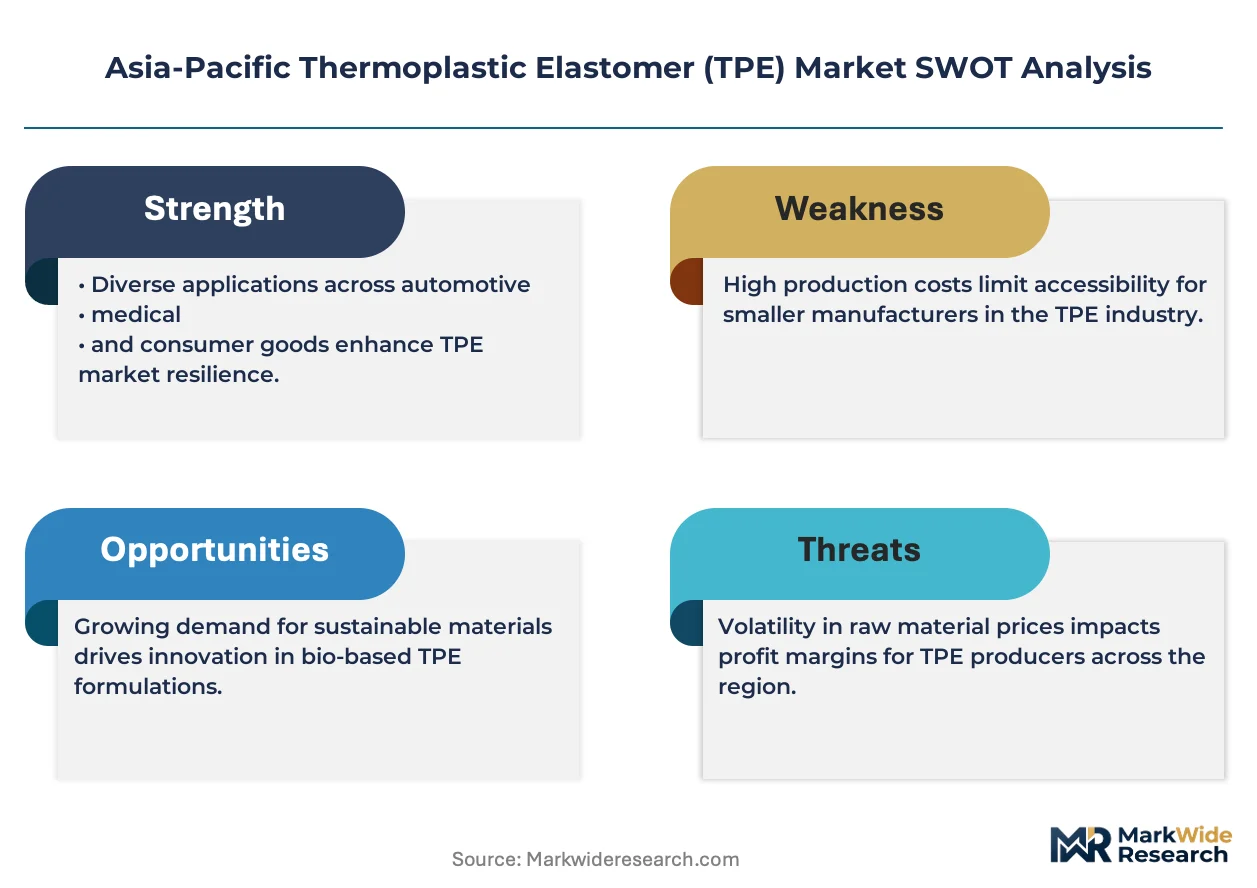
- Butadiene feedstock volatility:Styrenic block copolymer margins compress when naphtha-cracker co-product availability fluctuates, squeezing commodity-grade producers without captive olefin supply.
- Sinopec refining network concentration:China's dominant butadiene supply position creates single-source dependency risk for regional SBC compounders lacking alternative feedstock arrangements.
- Medical-grade biocompatibility timelines:MFDS skin-contact testing protocols extend South Korean healthcare TPE qualification cycles beyond eighteen months, filtering market access.
Strategic Opportunities
- India's automotive component import substitution:PLI scheme incentives for domestic manufacturing create openings for TPE suppliers establishing local compounding capacity.
- Bio-based polyol integration:Renewable feedstock routes for thermoplastic polyurethane soften exposure to petrochemical allocation tightening under China's dual carbon goals.
- Post-industrial scrap recovery mandates:Japan's METI Resource Circulation Strategy obligates automotive supply chains to close-loop TPE waste streams, creating service revenue pools.
Industry Challenges
- Multi-standard certification complexity:Compounders must simultaneously satisfy China's SAMR VOC limits, Japan's METI circularity reporting, and South Korea's MFDS biocompatibility protocols, fragmenting quality systems.
- Retrofitting legacy injection molding assets:Automotive tier suppliers face capital intensity in adapting equipment for TPE processing parameters distinct from incumbent thermoset rubber vulcanization lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Thermoplastic Elastomer (TPE) Market |
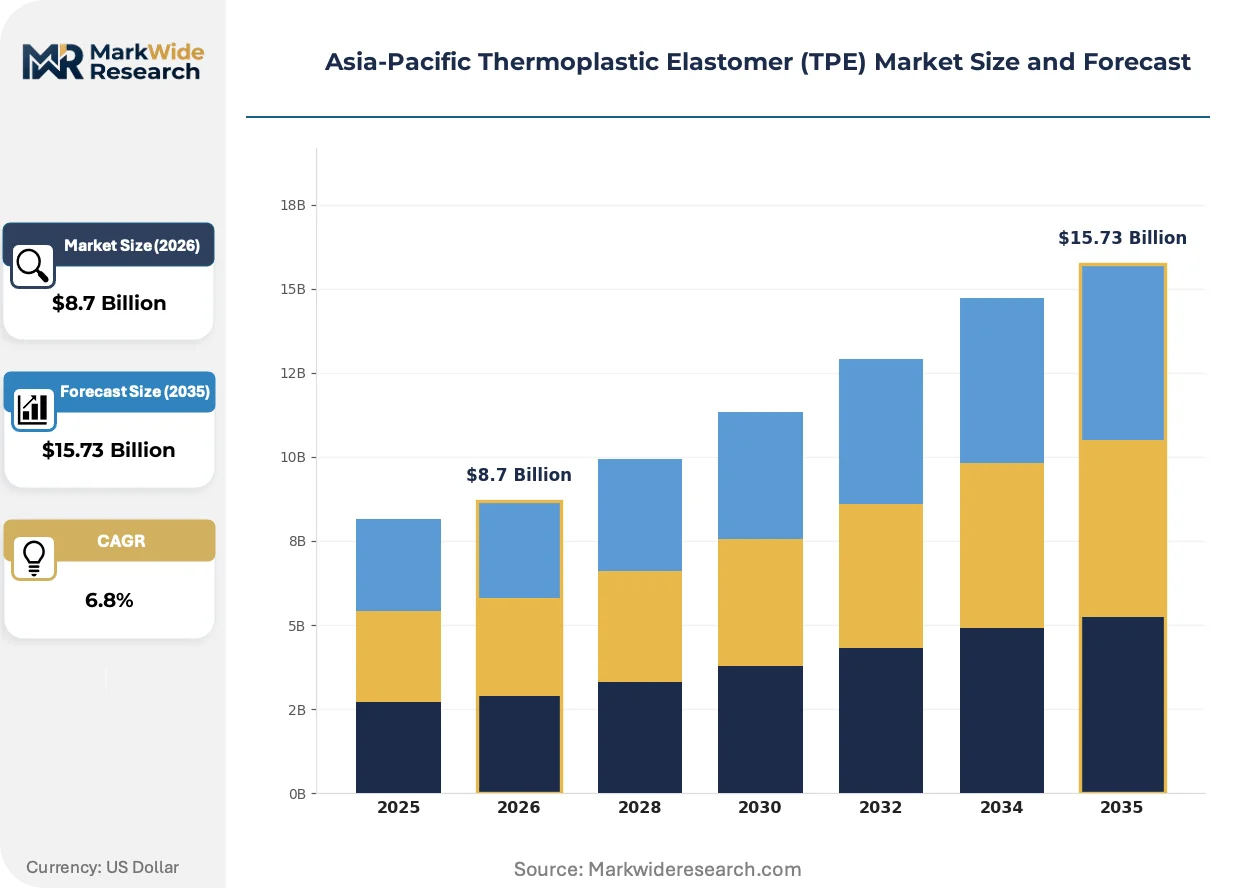
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrenic Block Copolymers, Thermoplastic Polyurethanes, Thermoplastic Vulcanizates, Olefin Block Copolymers End User: Automotive, Consumer Goods, Healthcare, Industrial Application: Sealants, Adhesives, Coatings, Films Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Huntsman Corporation, LyondellBasell Industries N.V., BASF SE, Teknor Apex, Avient Corporation, China Petroleum & Chemical Corporation, LG Chem, Nippon Polyurethane Industry Co. Ltd, Arkema S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Thermoplastic Elastomer (TPE) Market Strategic Shifts
Digital formulation platforms and closed-loop material verification systems are compressing development cycles and reshaping how compounders demonstrate compliance to automotive and medical buyers.
Real-time rheology monitoring embedded in extrusion lines is digitizing quality assurance for automotive sealing profiles. Tier-one suppliers in Japan and South Korea deploy these sensors to capture Shore hardness and melt flow index deviations before finished goods release, compressing batch rejection rates and reducing warranty exposure from field failures.
China's SAMR enforcement of GB standards for plasticizer migration is tightening compound documentation requirements. Domestic OEMs now demand certificates of analysis traceable to raw material lot codes, forcing compounders to upgrade laboratory information management systems. Medical device manufacturers face parallel pressure from MFDS biocompatibility testing protocols.
Automotive procurement teams are consolidating qualified material lists to reduce supplier management overhead. Japanese and Korean OEMs increasingly specify certified TPE grades from compounders with integrated testing laboratories, displacing smaller regional blenders lacking in-house analytical capability. This concentration is most visible in seating and interior skin applications where VOC compliance is non-negotiable.
Asia-Pacific Thermoplastic Elastomer (TPE) Market Segmentation
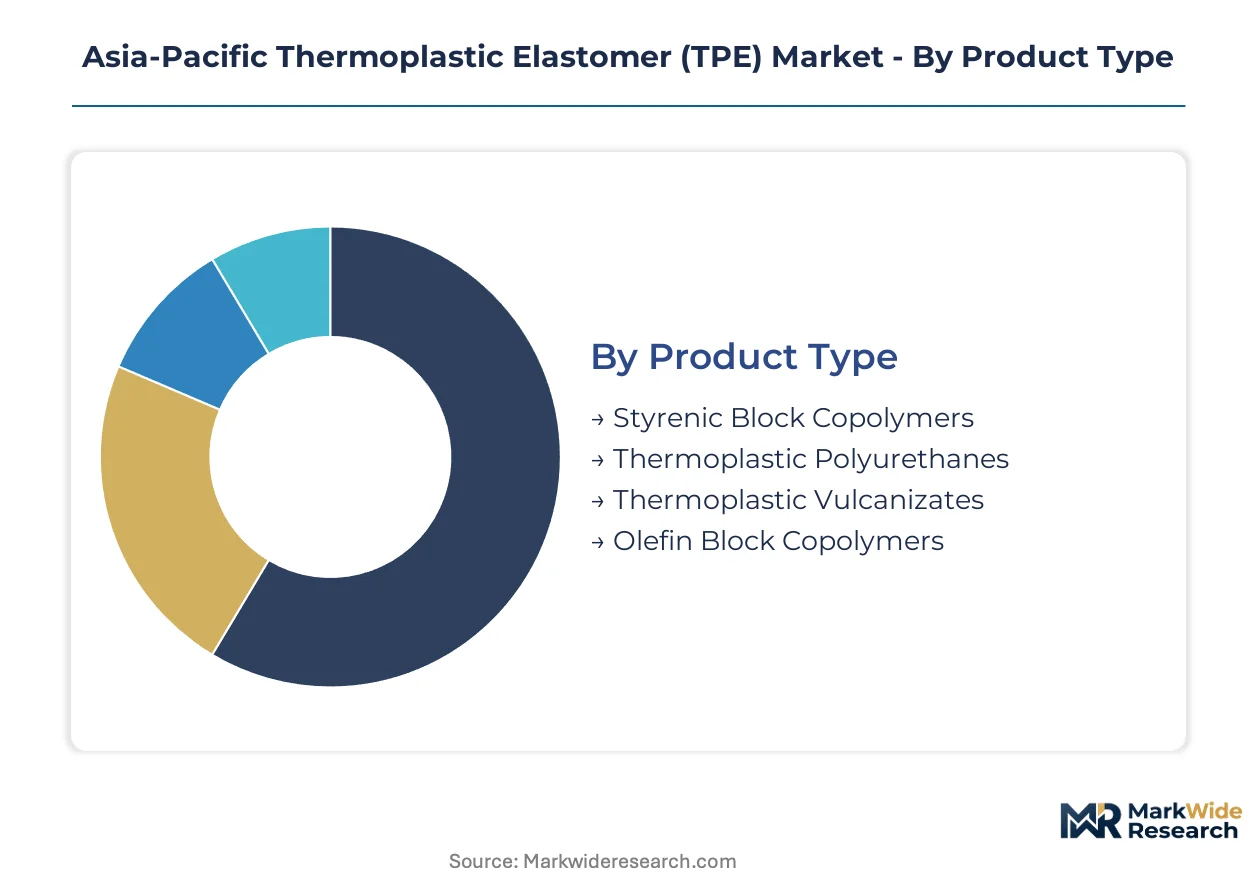
Product chemistry, end-use performance requirements, and procurement channel preferences fragment the Asia-Pacific TPE market into distinct commercial battlegrounds. Each segmentation dimension carries different margin structures, certification barriers, and regional concentration patterns that shape supplier positioning.
Product Type:
Cost tier differentiation separates commodity volume plays from specialty margin pools across the four major TPE chemistries.
- Styrenic Block Copolymers:These hydrogenated mid-block polymers deliver Shore A 30-90 hardness with styrene end-block reinforcement. China's eastern manufacturing corridor consumes the dominant share for automotive interior skins and footwear midsoles where Sinopec's captive butadiene supply anchors cost competitiveness.
- Thermoplastic Vulcanizates:Dynamic vulcanization creates dispersed EPDM rubber domains within polypropylene matrices, yielding heat resistance above 120°C. Japanese and Korean automakers specify these grades for under-hood ducts and charge-air cooler hoses where thermoset rubber previously dominated.
- Thermoplastic Polyurethanes:Soft segment polyol chemistry enables Shore A 70 to Shore D 75 hardness with optical clarity for medical films. LG Chem's Yeosu complex backward integration into polyol precursors secures Korean domestic supply security.
- Olefin Block Copolagen:Chain-shuttling catalysis produces narrow composition distribution for elastic films and soft-touch overmolding. These grades penetrate packaging and consumer electronics applications where haptics differentiate end products.
Styrenic block copolymers hold installed capacity. Thermoplastic vulcanizates are rotating up the share rankings.
End User:
Application maturity and regulatory intensity create divergent customer requirements across the four demand verticals.
- Automotive:GB standards for VOC emissions and recyclability dominate material specifications. Tier-one seating and sealing suppliers around Shanghai and Guangzhou consolidate procurement decisions, forcing compounders to maintain integrated testing laboratories for rapid certification.
- Healthcare:MFDS skin-contact testing protocols and SAMR biocompatibility documentation extend qualification cycles beyond eighteen months. Medical device manufacturers demand certificates of analysis traceable to raw material lot codes, filtering market access to compounders with upgraded laboratory information management systems.
- Consumer Goods:Footwear midsoles and personal care packaging drive volume with compressed development timelines. Price sensitivity here pushes compounders toward SBC grades where margin compression is structural.
- Industrial:Hose, belt, and gasket applications require heat and chemical resistance that thermoplastic vulcanizates increasingly satisfy. METI Resource Circulation Strategy obligations for post-industrial scrap recovery add service revenue complexity to supply relationships.
Automotive commands the deepest supplier relationships. Healthcare is climbing the fastest on margin contribution.
Application:
Functional performance requirements and processing method constraints segment the market by finished goods category.
- Sealants:Compression set resistance and Shore hardness stability across temperature cycles determine specification. Real-time rheology monitoring in Japanese and Korean extrusion lines digitizes quality assurance for automotive sealing profiles.
- Films:Optical clarity, biocompatibility certification, and barrier properties concentrate demand in healthcare and premium packaging. Thermoplastic polyurethanes capture margin pools here where performance premiums offset higher raw material costs.
- Adhesives:Tack and peel strength requirements span pressure-sensitive labels to structural bonding. Formulation flexibility enables SBC and TPU grades to compete based on specific substrate compatibility.
- Coatings:Abrasion resistance and haptics drive soft-touch overmolding for consumer electronics and appliance handles. Olefin block copolymers penetrate this segment where processing simplicity matters.
Sealants anchor volume throughput. Films are expanding most quickly on value per kilogram.
Distribution Channel:
Customer scale and technical service requirements determine channel economics across the four routes to market.
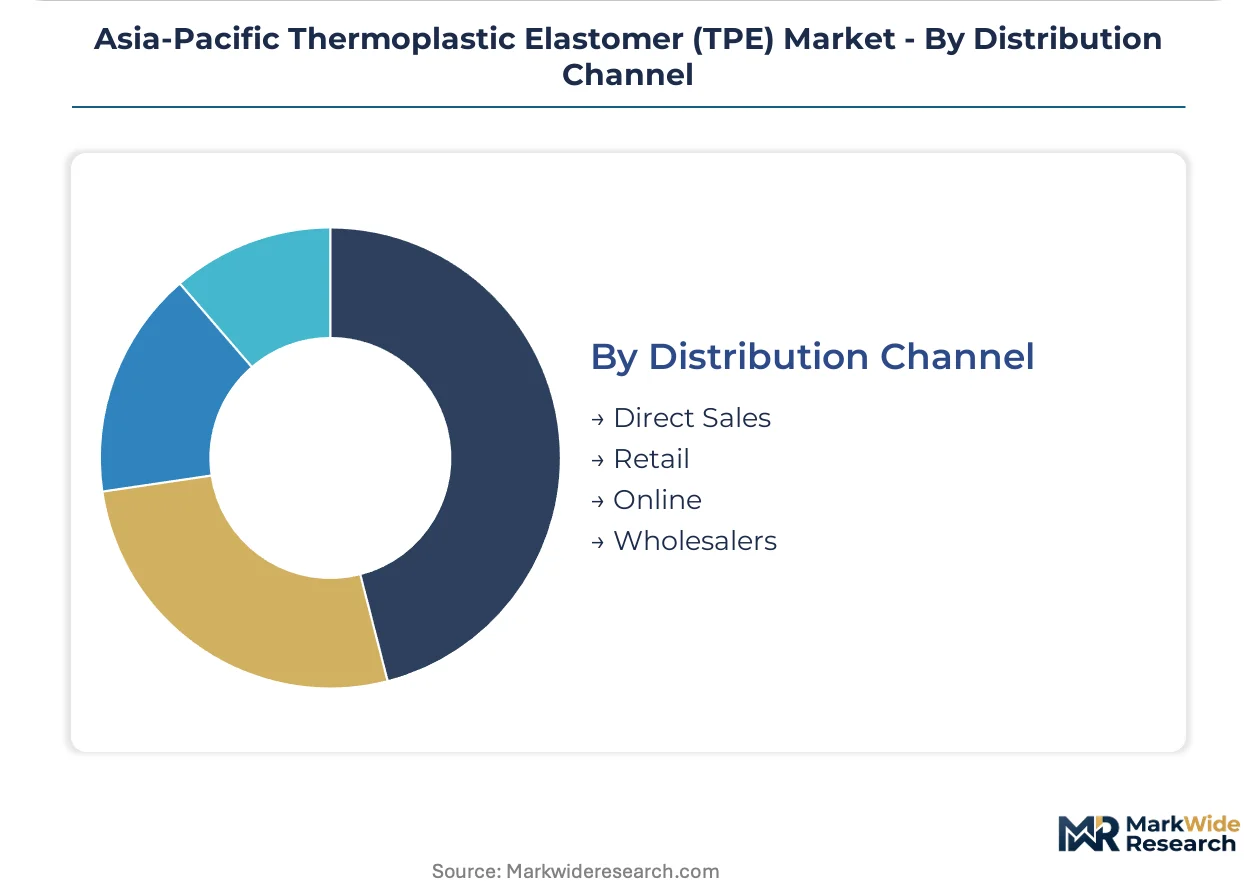
- Direct Sales:Automotive OEMs and medical device manufacturers demand technical collaboration on compound formulation. Compounders with integrated R&D pipelines anchor premium relationships through Ludwigshafen-derived or Yeosu-based development support.
- Wholesalers:Regional blenders and smaller processors rely on distributor inventory positioning for commodity SBC grades. China's eastern manufacturing corridor concentration enables efficient bulk logistics.
- Online:Standardized grades with published datasheets migrate to digital procurement platforms. This channel serves prototype development and small-batch industrial applications where speed outweighs technical consultation.
- Retail:Limited to hobbyist and repair segments with minimal TPE volume contribution in Asia-Pacific.
Direct sales commands the specification influence. Wholesalers are gaining share in commodity tier supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and Korean TPE exports flow primarily into China's eastern manufacturing corridor, where tier-one automotive suppliers cluster around Shanghai and Guangzhou for just-in-time delivery to domestic OEMs.
China
Automotive lightweighting programs and GB emission standards for vehicle interiors drive TPE substitution for conventional rubber. SAMR enforces VOC limits that restrict plasticizer migration, forcing compounders to upgrade laboratory information management systems. Manufacturing concentrates in the Yangtze River Delta and Pearl River Delta, where Sinopec's refining network supplies captive butadiene to styrenic block copolymer producers.
Japan
METI's Resource Circulation Strategy creates compliance obligations for post-industrial TPE scrap recovery in automotive supply chains. Real-time rheology monitoring digitizes quality assurance for sealing profiles exported to regional OEMs. Production clusters in the Chubu region around Nagoya, where tier-one suppliers maintain integrated testing laboratories for rapid grade certification.
South Korea
MFDS regulates skin-contact medical device polymers through biocompatibility testing protocols that extend qualification cycles beyond eighteen months. LG Chem's Yeosu complex maintains backward integration into polyol precursors for thermoplastic polyurethane supply security. The Busan-Ulsan corridor hosts specialty compounders serving domestic automotive and healthcare manufacturers.
India
PLI scheme incentives for domestic automotive component manufacturing create openings for TPE suppliers establishing local compounding capacity. Import substitution priorities favor suppliers with localized technical service capabilities. Industrial activity concentrates in Maharashtra and Gujarat, where tier-two suppliers are upgrading extrusion lines for TPE processing parameters.
Thailand
Japanese automaker transplant operations sustain demand for certified TPE grades in seating and interior skin applications. Regional trade agreements position Thai compounders as alternative supply sources for Southeast Asian assembly plants. Manufacturing concentrates in the Eastern Economic Corridor, where suppliers serve export-oriented automotive electronics producers.
Asia-Pacific Thermoplastic Elastomer (TPE) Market Competitive Environment
On the supply side, the industry is consolidating around compounders with integrated testing laboratories and captive feedstock positions. Three strategic archetypes dominate: petrochemical majors with refinery-derived olefin supply, specialty chemical houses with medical-grade certification capabilities, and regional compounders serving price-sensitive footwear and packaging segments. Competitive moves center on backward integration into polyol precursors and geographic expansion into India's PLI-incentivized manufacturing zones.
Within the petrochemical-major tier, BASF SE and China Petroleum & Chemical Corporation exemplify contrasting feedstock strategies. BASF anchors premium thermoplastic polyurethane development through Ludwigshafen-derived R&D pipelines for medical-grade films. Sinopec dominates styrenic block copolymer volume through captive butadiene supply from its refining network. Among specialty compounders, LG Chem occupies a position defined by Yeosu-based backward integration into polyol precursors, securing Korean domestic supply security against petrochemical allocation tightening under China's dual carbon goals.
| Leading Market Players |
|---|
| Huntsman Corporation |
| LyondellBasell Industries N.V. |
| BASF SE |
| Teknor Apex |
| Avient Corporation |
| China Petroleum & Chemical Corporation |
| LG Chem |
| Nippon Polyurethane Industry Co. Ltd |
| Arkema S.A. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's SBC resin base is compressing margins for commodity-grade compounders while tightening feedstock allocations under dual carbon goals force selective price firming in specialty TPU tiers. This utilization divergence splits supplier behavior between volume defense and premium positioning.
Pricing Analysis
Current-generation thermoplastic vulcanizates command meaningful premiums over styrenic block copolymer grades, while next-generation bio-based TPU formulations sit at the apex of the price hierarchy. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and captive feedstock access. Cost compression in SBC automotive interior grades is intensifying because Sinopec's refining network concentration squeezes non-integrated compounders. Tier-one automotive seating suppliers exhibit lowest price sensitivity due to VOC compliance non-negotiability, while footwear midsole processors remain most sensitive to resin cost swings.
Supply Chain Analysis
Tariff exposure between China and key export destinations for Japanese and Korean automotive components dominates supply chain risk calculus for regional TPE compounders. Geographic supply concentrates in China, South Korea, and Japan, with China's eastern manufacturing corridor anchoring volume production. Raw material dependencies rest on butadiene from naphtha crackers, polyol precursors from integrated petrochemical complexes, and hydrogenated mid-block polymers from specialty catalyst operations. Single-source vulnerability around Sinopec's butadiene supply creates concentration risk for regional SBC producers. Distribution runs through direct technical sales for automotive and medical grades, with wholesale channels serving commodity footwear and packaging segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoset rubber substitution cycles are accelerating, forcing TPE incumbents to defend against performance-grade EPDM and advanced polyolefin elastomers in under-hood applications.
For Market Incumbents: Insulate qualified supplier status with Japanese and Korean OEMs by upgrading laboratory information management systems for GB and MFDS traceability requirements. Secure captive butadiene arrangements or bio-based polyol pathways to offset Sinopec supply concentration risk. Reinforce medical-grade certification moats against emerging Korean and Chinese specialty compounders. For New Entrants and Emerging Players: Pursue India's PLI-incentivized automotive component zones where localized compounding capacity gaps persist against import-dependent tier-two suppliers. Target industrial hose and gasket segments in Maharashtra and Gujarat where TPV penetration remains below automotive tier levels. Lead with technical service partnerships rather than price-based displacement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with integrated testing laboratories and multi-OEM qualification portfolios. Long-term viability hinges on feedstock security against China's dual carbon allocation tightening. Acquisition focus should center on Korean and Japanese specialty houses with MFDS medical-grade certifications. Watch for Sinopec refining network disruption signals as inflection indicators for regional cost competitiveness shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Precursors | LG Chem's Yeosu complex demonstrates how captive supply secures Korean domestic TPU margins against petrochemical volatility. |
| Medical-Grade Certification Investment | MFDS biocompatibility protocols filter market access, creating defensible margin pools for qualified compounders. |
| India PLI Zone Manufacturing Establishment | Localized compounding capacity captures automotive component import substitution incentives in Maharashtra and Gujarat. |
| Post-Industrial Scrap Recovery Systems | METI Resource Circulation Strategy obligations create service revenue streams in Japanese automotive supply chains. |
| Digital Formulation Platform Deployment | Real-time rheology monitoring compresses batch rejection rates for tier-one sealing profile suppliers. |
Study Parameters
Cross-validation between executive interviews at tier-one automotive seating manufacturers and customs trade data anchors the qualitative findings. Primary fieldwork engaged TPE compounder technical directors, OEM procurement leads, and medical device polymer specialists across China, Japan, South Korea, and India. Secondary validation drew from SAMR GB standard filings, MFDS biocompatibility registration databases, METI circular economy policy documents, and SEC disclosures from listed petrochemical majors. Bottom-up resin demand modeling and top-down automotive production forecasts were reconciled through iterative triangulation.
Calibration against historical substitution rates in under-hood automotive segments and footwear midsole material transitions informed the projection framework. Segmentation modeling spanned product chemistry, end-use vertical, Shore hardness tier, and regional regulatory cluster across the analysis window. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion announcements. Industry-specific inputs included GB standard enforcement timelines, PLI scheme incentive trajectories, and dual carbon goal petrochemical allocation scenarios.
Macroeconomic conditions sit as an overlay; deviation in naphtha-cracker operating rates, automotive production schedules, or China's carbon-intensive feedstock restrictions would shift the trajectory. Forecasts reflect documented assumptions about substitution elasticity and certification timeline stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
Polydimethylsiloxane (PDMS) Market
Elastomeric Membrane
Ultra-Soft Thermoplastic Elastomer Market
Elastomeric Membrane
Middle-East and Africa (EMEA) Elastomers Market
Elastomeric Membrane
Ethylene Propylene Elastomers Market
Elastomeric Membrane
Medical Grade Silicone Rubber Market
Elastomeric Membrane
High Temperature Elastomers Market
Elastomeric Membrane
Bio-Based Elastomers Market
Elastomeric Membrane
Europe Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Water Soluble Elastomers Market
Elastomeric Membrane
Elastomeric Polyolefins Market
Elastomeric Membrane
Perfluoroelastomer (FFKM) Market
Elastomeric Membrane
UV Stabilized Thermoplastic Elastomer Market
Elastomeric Membrane
Elastomer Coated Fabric Market
Elastomeric Membrane
Polyurethane Elastomers Market
Elastomeric Membrane
Hot Cast Elastomers Market