
 Polyethylene Vapor Barrier Films for Under Slab Market | 2026-2036
Polyethylene Vapor Barrier Films for Under Slab Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Vapor Barrier Films for Under Slab Market Intelligence
Certified polyethylene film installers is redrawing competitive boundaries in the under-slab barrier trade. Stego Industries, LLC sustains technology leadership through proprietary seam-tape systems that reduce field failure rates. Poly-America, L.P. leverages massive blown-film extrusion capacity to dominate bulk residential supply channels. W. R. Meadows, Inc. anchors its position in commercial and infrastructure specifications through deep specification relationships with engineering firms.
Polyethylene vapor barrier films for under slab are high-density or linear low-density polyethylene sheets, typically 6 to 20 mils thick, manufactured through blown-film extrusion with carbon black or colorant loading for UV stability and puncture resistance, installed directly beneath concrete slabs to block soil moisture vapor transmission and prevent flooring degradation. Non-reinforced films occupy the volume base in residential construction where cost sensitivity dominates specification, while multi-layer coextruded films command premium positioning in commercial and industrial facilities where long-term warranty coverage and radon mitigation dual-functionality justify higher material outlays. The 10 Mil and 15 Mil thickness tiers represent the most contested specification battleground, with 15 Mil films displacing 10 Mil in code-advanced jurisdictions requiring enhanced puncture resistance during steel placement and concrete pours.
ASTM International governs material performance through E1745 Class A, B, and C ratings that permeability, tensile strength, and puncture thresholds, while the International Code Council references these standards in International Residential Code and International Energy Conservation Code adoption cycles that drive municipal enforcement. EPA radon mitigation guidelines and state-level energy stretch codes, particularly in the northeastern United States, are expanding mandatory barrier coverage to previously exempt slab configurations. Stakeholders must monitor code harmonization friction between ASTM material standards and emerging performance-based building codes that may shift specification authority from commodity producers to systems-level solution providers.
Market Dynamics
ASTM E1745 Class A certification requirements are compressing the supply base as municipal code adoption accelerates across moisture-prone construction corridors, forcing specifiers to trade up from commodity films to engineered barrier systems with documented permeability performance.
Growth Catalysts
- Code stringency in coastal zones:Municipal adoption of International Residential Code amendments in Florida, Louisiana, and Texas is mandating 15 Mil minimum thickness for slab-on-grade foundations, eliminating thinner specification tiers from permitted construction.
- Radon mitigation dual-functionality:EPA guidance expanding barrier coverage to previously exempt crawl space conversions is creating specification pull for coextruded films with sub-slab depressurization compatibility in the northeastern United States.
- Steel placement puncture resistance:Reinforced mesh integration in multi-layer films is reducing field failure rates during rebar installation, accelerating contractor preference for engineered products over commodity alternatives.
Market Restraints
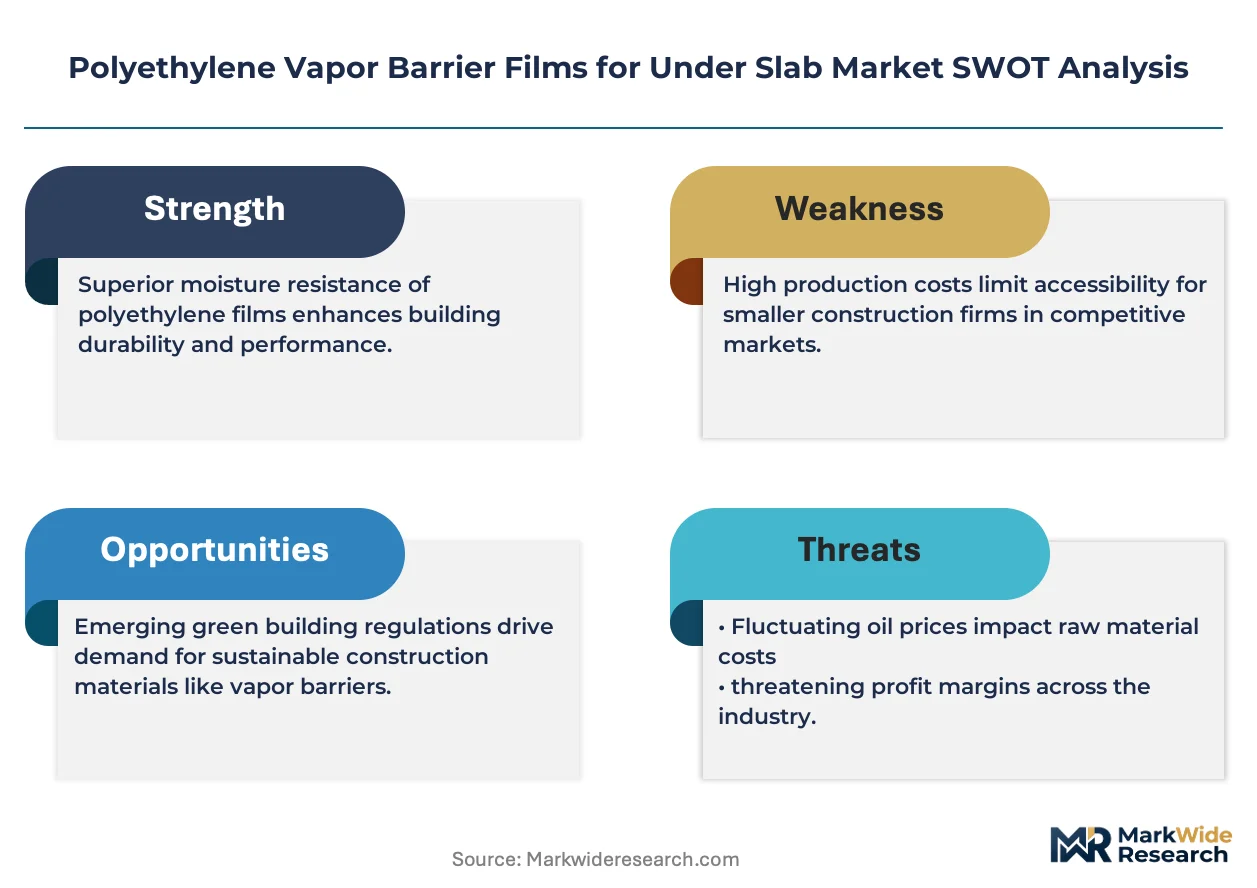
- Resin cost volatility:Linear low-density polyethylene feedstock prices fluctuate with ethylene cracker margins, compressing converter margins and creating pricing friction in bulk residential channels.
- Blown-film capacity concentration:Domestic extrusion capacity clusters along the Texas-Louisiana petrochemical corridor, exposing supply chains to hurricane disruption and force majeure risk.
- Alternative moisture management:Fluid-applied membrane systems are capturing specification share in commercial podium slabs where complex geometries defeat sheet membrane installation.
Strategic Opportunities
- Retrofit radon mitigation:Basement barrier retrofit installations in Minnesota, Wisconsin, and Iowa represent underpenetrated demand as state health departments expand testing mandates.
- Coextruded barrier-tape integration:Factory-applied adhesive seam systems are reducing field labor and failure rates, creating premium positioning for systems-level solution providers.
- Energy stretch code alignment:Massachusetts and Vermont stretch code adoption is extending mandatory barrier coverage to accessory dwelling units and garage slabs previously exempt from vapor protection.
Industry Challenges
- Certified installer scarcity:Stego Industries' proprietary certification program has created a bottleneck as demand outpaces qualified technician availability in the Gulf Coast corridor.
- ASTM E1745 testing backlog:Third-party laboratory capacity constraints are extending product qualification timelines for new film formulations seeking Class A rating.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Vapor Barrier Films for Under Slab Market |
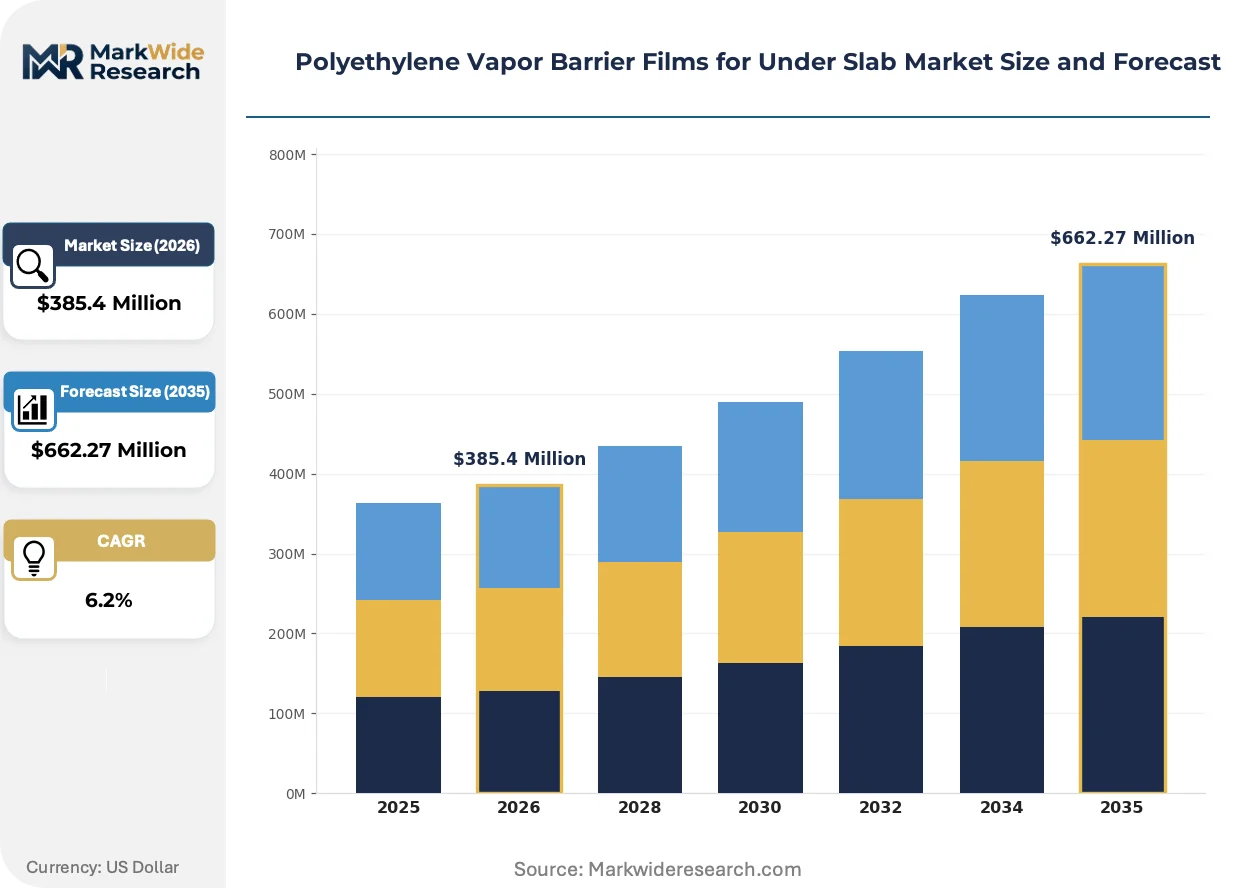
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reinforced Films, Non-Reinforced Films, Multi-Layer Films, Specialty Films Thickness: 6 Mil, 10 Mil, 15 Mil, 20 Mil Application: Residential Construction, Commercial Construction, Industrial Facilities, Infrastructure Projects Delivery Mode: Direct Shipment, Local Distribution, Bulk Orders, Retail Supply |
| Companies Covered | W. R. Meadows, Inc., Poly-America, L.P., Reef Industries, Inc., Polyguard Products, Inc., Layfield Group Ltd., Berry Global Inc., Stego Industries, LLC, RKW Group, Cover-Tech Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Vapor Barrier Films for Under Slab Market Strategic Shifts & Innovations
Material science convergence with installation robotics is compressing field labor requirements while elevating performance documentation standards. Specification authority is migrating from commodity producers to systems integrators with certified installation networks.
Multi-layer coextruded barrier films with factory-integrated seam tape are miniaturizing the installation crew footprint on commercial slabs. General contractors in Texas and Florida are adopting these systems to accelerate concrete pour schedules. The technology is compressing competitive differentiation from raw material cost toward total installed cost and warranty coverage terms.
EPA radon mitigation guideline expansion is mandating sub-slab barrier coverage in new residential construction across Minnesota, Wisconsin, and Iowa. State health department enforcement is elevating product traceability requirements. The policy shift is forcing commodity film producers to invest in third-party certification or cede specification to engineered systems providers with documented permeability testing.
Builder procurement consolidation through national production homebuilders is compressing distributor margins and favoring direct mill relationships. Lennar, D.R. Horton, and PulteGroup are centralizing vapor barrier specification at corporate level. The channel shift is most visible in the Phoenix and Houston metropolitan areas where production housing dominates new construction volume.
Polyethylene Vapor Barrier Films for Under Slab Market Segmentation
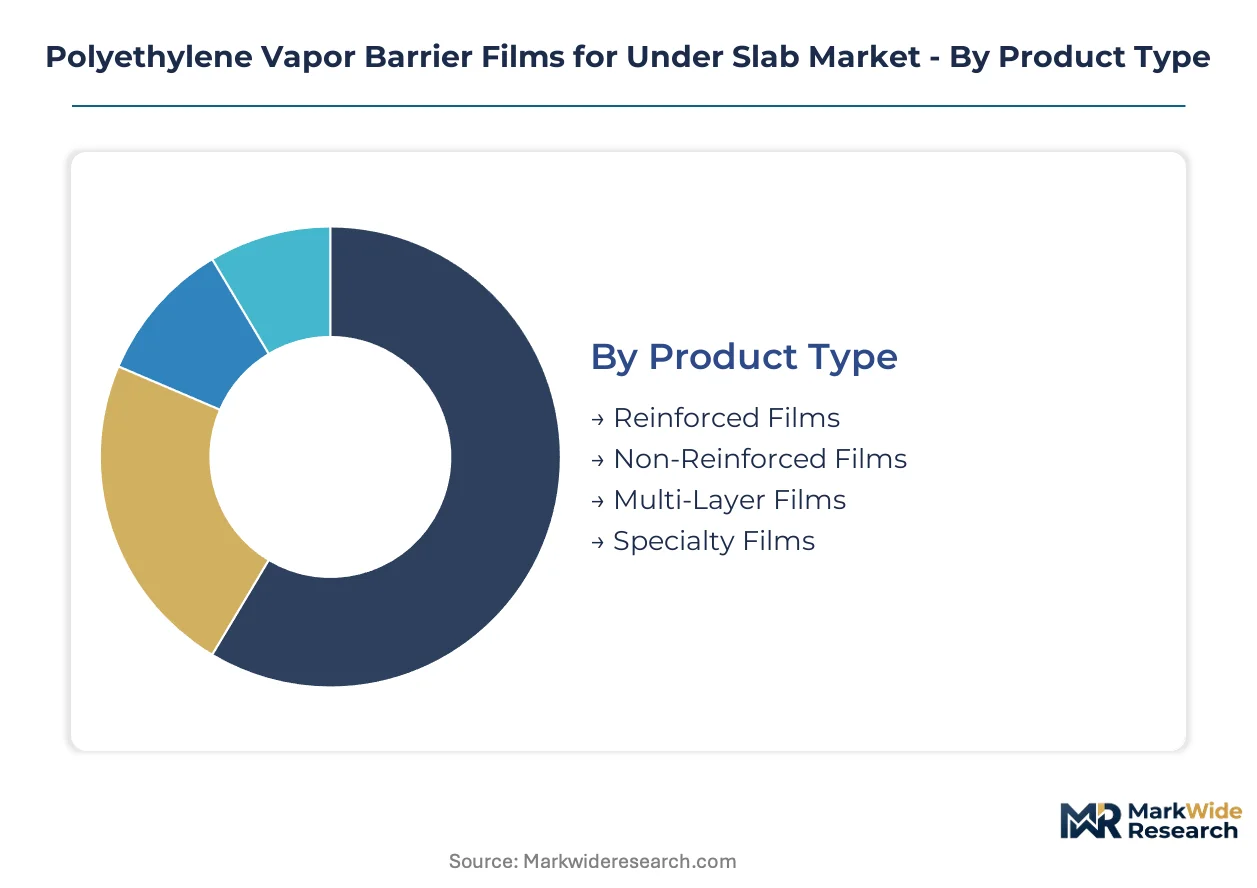
Segmentation in the polyethylene vapor barrier films for under slab market reveals how specification authority migrates across product tiers, thickness grades, and channel structures. Understanding these divisions exposes where margin concentrates and where commoditization pressure intensifies.
Product Type:
Domestic production dominates reinforced and non-reinforced categories, while multi-layer coextruded films draw specialized resin formulations from export-led supply chains in Western Europe and East Asia.
- Reinforced Films:High-density polyethylene substrates laminated with woven polypropylene or fiberglass scrim deliver puncture resistance exceeding 70 lbs per ASTM D1709. Demand clusters in Texas and Florida commercial slabs where steel placement density and accelerated pour schedules elevate failure cost. ASTM E1745 Class A certification is becoming baseline specification in these jurisdictions.
- Non-Reinforced Films:Single-layer blown-film extrusion of linear low-density polyethylene with carbon black loading for UV stability constitutes the residential volume base. Cost sensitivity in production homebuilder procurement compresses margin to resin-plus-conversion economics, with specification authority consolidating through Lennar, D.R. Horton, and PulteGroup corporate purchasing.
- Multi-Layer Films:Coextruded barriers with factory-integrated seam tape systems command premium positioning through reduced field labor and documented permeability performance.
- Specialty Films:Radon-blocking formulations with sub-slab depressurization compatibility serve Minnesota, Wisconsin, and Iowa health department mandates.
Non-Reinforced Films holds the largest share; momentum sits with Multi-Layer Films.
Thickness:
Cost tier stratification separates commodity residential specification from engineered commercial systems, with thickness grade directly correlating to code advancement and warranty term length.
- 10 Mil:The historical residential standard now faces displacement in code-advanced jurisdictions. Surviving demand concentrates in legacy construction corridors with slower IRC adoption cycles and in accessory dwelling unit exemptions from stretch code coverage.
- 15 Mil:ASTM E1745 Class A compliance at this thickness tier has become mandatory in Florida, Louisiana, and Texas municipal adoptions of International Residential Code amendments. Enhanced puncture resistance during rebar installation reduces contractor callback exposure and accelerates concrete pour schedules.
- 6 Mil:Minimal viable thickness persists only in agricultural and temporary structure applications outside enforced residential codes.
- 20 Mil:Heavy-duty specification serves industrial facilities with long-term warranty requirements and infrastructure projects with extended design life.
15 Mil commands specification authority in enforced jurisdictions; 10 Mil retains volume in lagging adoption corridors.
Application:
Customer type fragmentation separates production homebuilder procurement consolidation from commercial specification through engineering firm relationships.
- Residential Construction:Slab-on-grade foundations in moisture-prone Gulf Coast states drive volume demand. Corporate-level specification by national production builders compresses distributor margins and favors direct mill relationships in Phoenix and Houston metropolitan areas.
- Commercial Construction:Podium slabs and complex geometries are capturing specification share by fluid-applied membrane alternatives, though sheet barriers retain position in standard slab configurations.
- Industrial Facilities:Long-term warranty coverage and radon mitigation dual-functionality justify premium material outlays for coextruded systems.
- Infrastructure Projects:Extended design life requirements and federal procurement protocols elevate documentation and traceability standards.
Residential Construction generates the volume base; Industrial Facilities deliver the margin premium.
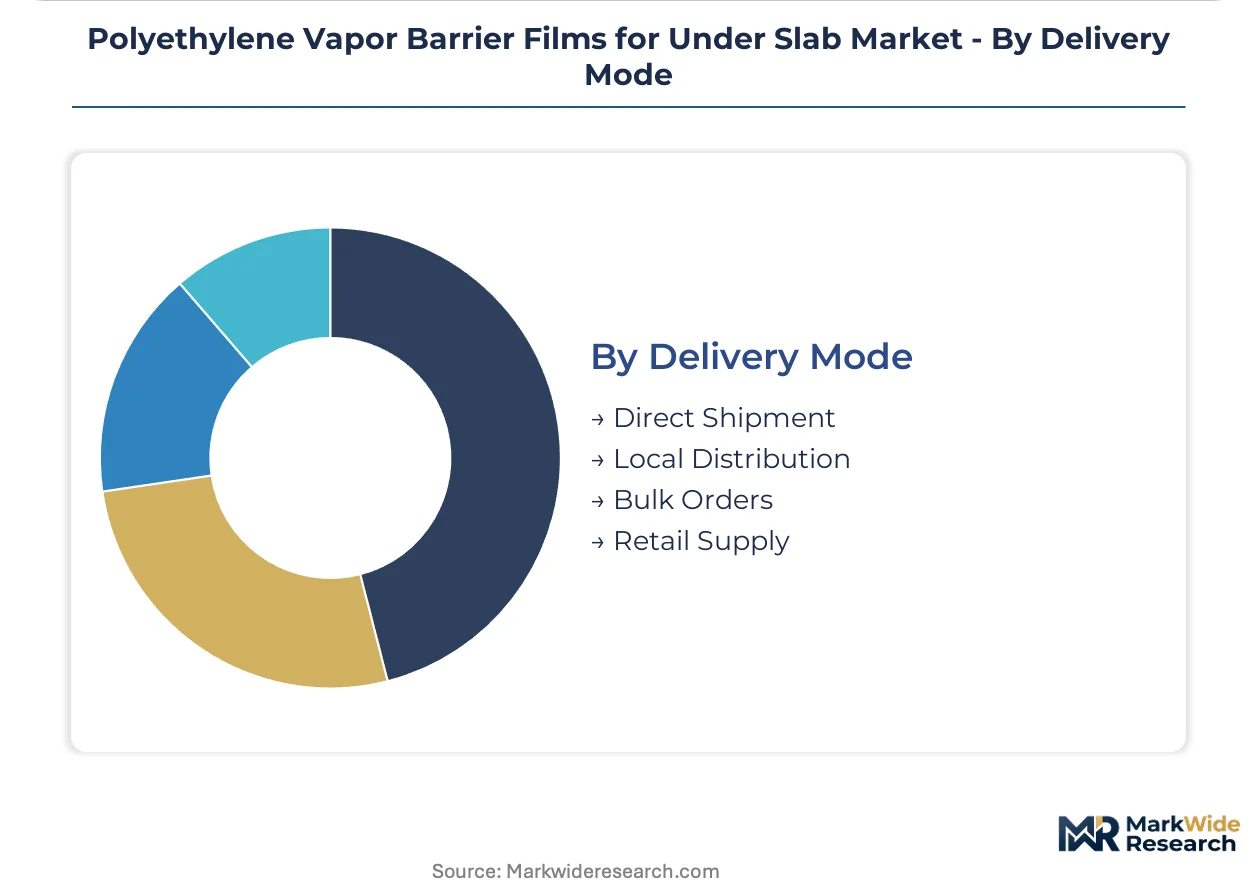
Delivery Mode:
Supply concentration along the Texas-Louisiana petrochemical corridor shapes channel economics, with hurricane exposure forcing redundancy investment in distribution networks.
- Direct Shipment:Mill-to-jobsite delivery serves national production builders with centralized procurement and volume scale sufficient to bypass distributor markup. Channel control reinforces price transparency and compresses margin for converter intermediaries.
- Bulk Orders:Pooled procurement through regional contractor cooperatives captures truckload pricing for mid-sized commercial contractors without corporate-level purchasing power.
- Local Distribution:Stocking distributors serve emergency replacement and small-project demand with markup recovery for inventory carrying cost.
- Retail Supply:Big-box and specialty construction retail captures DIY and renovation demand with limited specification influence.
Direct Shipment is expanding fastest; Local Distribution retains position in fragmented contractor bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA guidelines and IRC amendments in the United States are establishing the regulatory template that other jurisdictions reference for vapor barrier specification. Construction corridors in moisture-prone zones drive specification intensity, while code harmonization efforts create cross-border influence patterns.
United States
Gulf Coast slab-on-grade construction dominates residential volume, with Florida, Louisiana, and Texas mandating 15 Mil minimum thickness through municipal IRC adoptions. EPA radon mitigation guidelines expand barrier coverage to previously exempt configurations in Minnesota, Wisconsin, and Iowa. The Houston and Phoenix metropolitan areas concentrate production homebuilder procurement through centralized corporate specification.
Canada
National Building Code of Canada moisture protection requirements elevate performance thresholds in Ontario and British Columbia residential construction. Health Canada guidelines on radon mitigation align with EPA protocols, creating specification pull for dual-functionality barriers. The Greater Toronto Area anchors demand through high-density residential development and energy code stringency.
Germany
DIN standards for building envelope moisture control influence specification across Central European export markets. Energy efficiency regulations in the Energieeinsparverordnung extend vapor protection requirements to accessory structures previously exempt. The Rhine-Ruhr industrial corridor concentrates distribution infrastructure for blown-film extrusion supply chains.
United Kingdom
Building Regulations Part L conservation of fuel and power amendments elevate airtightness requirements that indirectly strengthen vapor barrier specification. NHBC warranty standards for new homes mandate moisture protection in slab-on-grade foundations. The Southeast England construction corridor drives specification volume through high-output residential development zones.
Australia
National Construction Code condensation management provisions expand vapor barrier coverage in slab-on-ground construction across Queensland and New South Wales. State-level energy efficiency disclosure requirements elevate product documentation standards. The Sydney-Perth development corridor concentrates demand through climate-zone-specific moisture management protocols.
Polyethylene Vapor Barrier Films for Under Slab Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with differentiation anchored in certification depth and installation network scale. The upper tier commands specification authority through documented ASTM E1745 Class A performance and proprietary seam-tape systems. Mid-tier fabricators compete on resin cost efficiency and regional distribution proximity. Capacity expansion along the Texas-Louisiana petrochemical corridor and strategic certification investments represent the dominant competitive moves.
Within the integrated systems tier, Stego Industries, LLC exemplifies the certification-driven positioning model, while Poly-America, L.P. occupies the scale-commodity vector through massive blown-film capacity. W. R. Meadows, Inc. anchors the engineering-relationship archetype in commercial and infrastructure channels. These three represent the structural poles around which competitive positioning organizes.
| Leading Market Players |
|---|
| W. R. Meadows, Inc. |
| Poly-America, L.P. |
| Reef Industries, Inc. |
| Polyguard Products, Inc. |
| Layfield Group Ltd. |
| Berry Global Inc. |
| Stego Industries, LLC |
| RKW Group |
| Cover-Tech Inc. |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day resin inventory cycles at Gulf Coast converters compress margin recovery windows when ethylene cracker margins spike, tethering pricing power to petrochemical corridor logistics rather than product differentiation alone. This inventory-lead time dynamic concentrates bargaining power with blown-film extruders possessing backward integration into resin supply, while forcing distributors to absorb price volatility through working capital intensity.
Pricing Analysis
Geographic price spreads widen by fifteen to twenty-five percent between Texas-Louisiana mill-direct shipments and Northeast distributor-stocked material, reflecting hurricane-risk premiums and logistics fragmentation. Three-tier pricing structure across engineered multi-layer systems, standard reinforced films, and commodity non-reinforced grades anchors the market, with ASTM E1745 Class A certification and factory-integrated seam tape systems commanding measurable premiums. Cost compression in the residential non-reinforced tier intensifies as national production homebuilders centralize procurement through direct mill relationships, rendering distributor intermediaries margin-vulnerable. Production homebuilders exhibit acute price sensitivity, while industrial facilities with long-term warranty requirements demonstrate relative inelasticity.
Supply Chain Analysis
Thirty-to-forty-five day order-to-delivery lead times for standard thickness grades extend to ninety-plus days for certified multi-layer formulations, exposing capacity constraints at third-party testing laboratories. Blown-film extrusion capacity clusters in the United States, Canada, and Germany, with specialized coextrusion lines drawing engineered resin formulations from South Korea and Japan. Domestic supply chains rest on linear low-density polyethylene feedstock, carbon black masterbatch, and woven reinforcement scrim as critical inputs. Hurricane exposure along the Texas-Louisiana corridor constitutes the dominant structural risk, forcing redundancy investment in secondary distribution nodes. Distribution runs through mill-direct channels for volume buyers, regional stocking distributors for fragmented contractors, and big-box retail for renovation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The under-slab barrier market approaches a platform-economics inflection as specification authority migrates from commodity producers to systems integrators with certified installation networks and documented permeability performance. Factory-integrated seam-tape systems and proprietary installer certification programs are creating interoperability moats that reshape competitive boundaries.
For Market Incumbents: Compound technology leadership through captive production of multi-layer coextruded films with factory-applied adhesive systems, while extending proprietary installer certification programs to lock out commodity competitors. Fluid-applied membrane alternatives threaten sheet barrier share in commercial podium slabs; defend against displacement by deepening specification relationships with engineering firms and embedding performance documentation into standard project deliverables.
For New Entrants and Emerging Players: Differentiate on retrofit radon mitigation specialization, targeting basement barrier installations in Minnesota, Wisconsin, and Iowa where state health department testing mandates are expanding coverage requirements. The retrofit segment remains underpenetrated by incumbent certified networks, offering white-space access without direct confrontation with Stego Industries' proprietary installer infrastructure. Pursue state-level certification as an approved radon mitigation contractor to bypass ASTM E1745 testing backlogs and accelerate market entry.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building materials conglomerates with underoptimized polyethylene film divisions lacking Class A certification depth or certified installer network scale. Long-term viability hinges on specification authority migration toward systems-level solution providers with documented performance and installation control. Watch for EPA radon mitigation guideline expansion into additional states as the signal indicating inflection toward dual-functionality barrier demand.
| Strategic Initiative | Industry Significance |
|---|---|
| ASTM E1745 Class A Certification Investment | Third-party laboratory qualification compresses supply base and elevates specification authority for certified producers. |
| Factory-Integrated Seam-Tape System Development | Field labor reduction and failure-rate documentation shift competitive differentiation toward total installed cost. |
| Proprietary Installer Certification Program Expansion | Stego Industries' model creates bottleneck scarcity that locks out commodity competitors from premium specification tiers. |
| Backward Integration into Resin Supply | Captive ethylene supply insulates margin from cracker-margin volatility and hurricane-force majeure disruption. |
| Retrofit Radon Mitigation Market Entry | State health department mandate expansion in Minnesota, Wisconsin, and Iowa creates underpenetrated demand corridor. |
Research Approach
The analysis maps reinforced films, non-reinforced films, multi-layer coextruded systems, and specialty radon-blocking formulations, each validated through plant managers at blown-film extrusion facilities, procurement leads at national production homebuilders, specification engineers at commercial contracting firms, and distribution channel partners. Primary interviews combined with secondary validation from ASTM International standards documentation, International Code Council adoption cycle records, EPA radon mitigation guidelines, and SEC filings from publicly traded building materials conglomerates. Bottom-up volume modeling and top-down value triangulation cross-validated segment outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled thickness tiers, product type categories, application segments, and delivery mode channels, with regional regulatory adoption cycles as an industry-specific dimension. CAGRs derived from segment-level growth trajectory analysis incorporating code stringency adoption curves, construction permit data, and energy efficiency stretch code expansion patterns. Resin cost pass-through elasticity and certified installer capacity constraints served as key forecast inputs.
Forecasts assume regulatory continuity in EPA radon mitigation protocols and IRC amendment adoption cycles across moisture-prone states; material policy shifts would require re-modeling demand trajectories for dual-functionality barrier systems. Supply chain disruption from hurricane exposure or ethylene cracker force majeure events represents specific risk factors that could revise forecast outputs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Barrier Packaging Market
Packaging Barrier Films
Specialty Films Market
Packaging Barrier Films
Cryogenic Insulation Films Market
Packaging Barrier Films
Tray Liners Market
Packaging Barrier Films
High Barrier Lidding Film Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
North America Protective Films Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Transport Protection Film Market
Packaging Barrier Films
Middle East and Africa Airless Packaging Market
Packaging Barrier Films
Microwavable Barrier Films Market
Packaging Barrier Films
Decorative Films and Foils Market
Packaging Barrier Films
Waterproof Packaging Market
Packaging Barrier Films
Packaging Barrier Films Market
Packaging Barrier Films
Barrier Shrink Bags Market