
 North America Protective Films Market | 2026-2036
North America Protective Films Market Size, Share, and Industry Trends Forecast 2026-2036
North America Protective Films Market Analytics
Aftermarket service revenue is fragmenting across the North America Protective Films Market as original equipment manufacturers build captive application capabilities. 3M leverages its adhesive science heritage to sustain premium positioning in industrial-grade polyethylene solutions. Eastman Chemical Company anchors its competitive stance through backward integration into specialty polyester resin production. DuPont differentiates via fluoropolymer-enhanced films that command pricing power in electronics cleanroom environments.
Protective films in North America comprise multilayer polymer laminates, typically 25-150 microns thick, with a pressure-sensitive adhesive coated onto a backing substrate such as polyethylene, polypropylene, PVC, or PET; these films shield surfaces from abrasion, chemical exposure, and contamination during manufacturing, transport, and installation. Polyethylene dominates volume across automotive paint protection and construction glazing applications due to cost-efficient extrusion processing and adequate mechanical properties for temporary guarding. PET films capture disproportionate margin pools in electronics, where optical clarity and dimensional stability under thermal cycling justify premium positioning over polypropylene alternatives.
The EPA regulates volatile organic compound emissions from adhesive coating operations under Clean Air Act Title V permitting, while OSHA mandates hazard communication for isocyanate-containing formulations used in some high-performance protective films. California's Air Resources Board imposes the nation's strictest VOC limits, effectively setting the compliance ceiling that suppliers must meet for access to the region's electronics and automotive manufacturing base. Stakeholders should monitor state-level regulatory divergence, as Illinois and Michigan contemplate tighter alignment with California standards that would reshape formulation requirements across the Great Lakes supply chain.
Market Dynamics
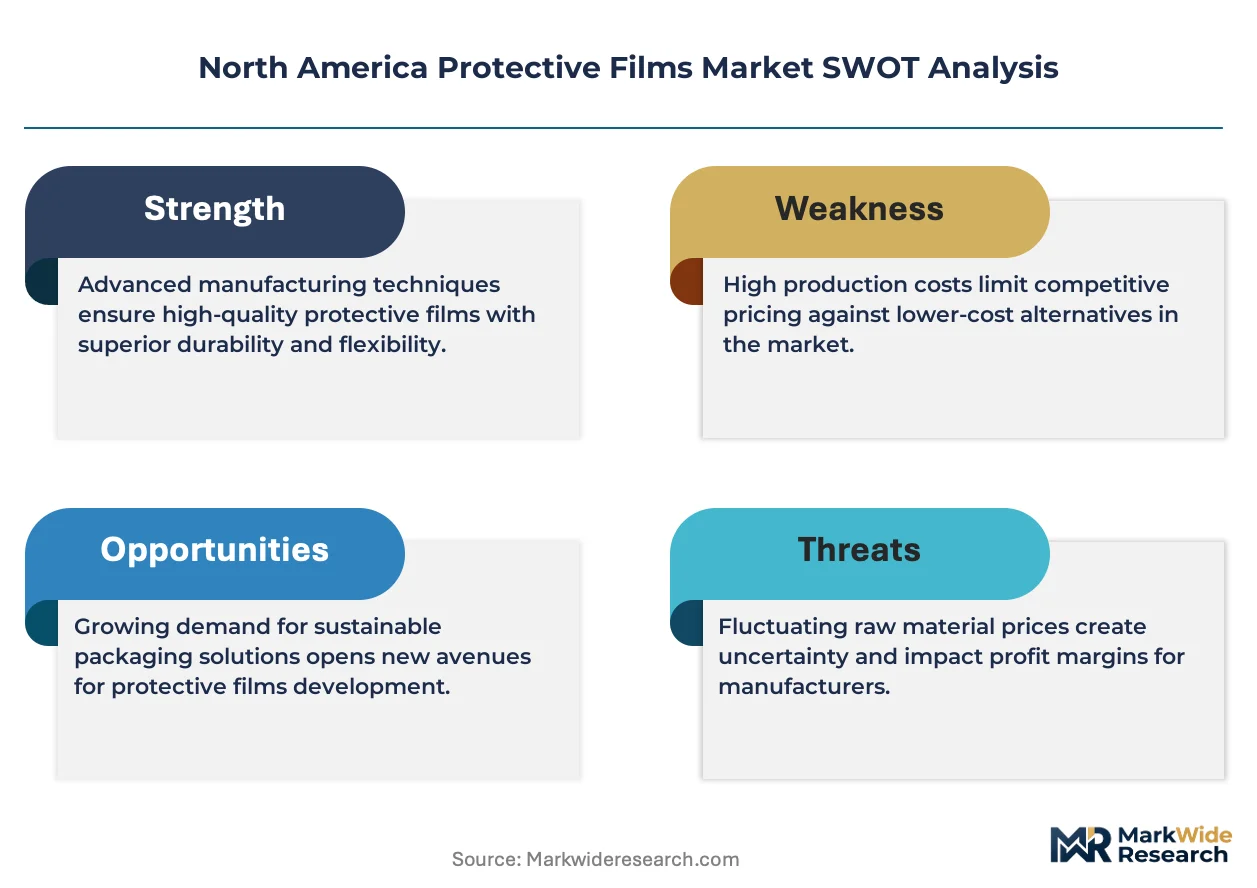
EPA's evolving VOC emission standards under Clean Air Act Title V are forcing solvent-based adhesive suppliers toward waterborne and UV-curable alternatives, compressing formulation margins while reshaping competitive positioning across the Great Lakes manufacturing corridor.
Growth Catalysts
- Electronics Cleanroom Expansion:Semiconductor fabrication facilities in Arizona and Texas are specifying fluoropolymer-enhanced films for wafer handling, pulling premium-grade material volumes upward.
- California Air Resources Board Standards:The nation's strictest VOC limits are creating regulatory arbitrage opportunities for early movers with compliant solvent-free formulations.
- Automotive Paint Protection:OEM captive application capabilities in Michigan and Ohio are expanding polyethylene film consumption for vehicle transit guarding.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene and propylene price swings directly compress margins for polyethylene and polypropylene film extruders.
- Specialty Polyester Resin Concentration:Backward-integrated resin production sits with a limited supplier base, creating bottleneck risk for PET film availability.
- Mechanical Property Ceiling:Polypropylene alternatives face substitution pressure from PET in electronics thermal cycling applications due to dimensional stability limitations.
Strategic Opportunities
- Mexico Nearshoring Corridor:Automotive assembly expansion in Nuevo León and Guanajuato is creating demand for transit protection films with shorter logistics loops.
- Solar Panel Manufacturing:Domestic PV module production incentives under the Inflation Reduction Act are opening new application vectors for temporary surface protection.
- UV-Curable Adhesive Convergence:Combination with digital printing technologies is enabling on-demand customization for short-run industrial labeling films.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Pressure-sensitive adhesive development requires polymer science expertise that competes with broader specialty chemicals sectors.
- Multi-State Compliance Complexity:Divergent VOC standards between California, Illinois, and Michigan are fragmenting SKU requirements and inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Protective Films Market |
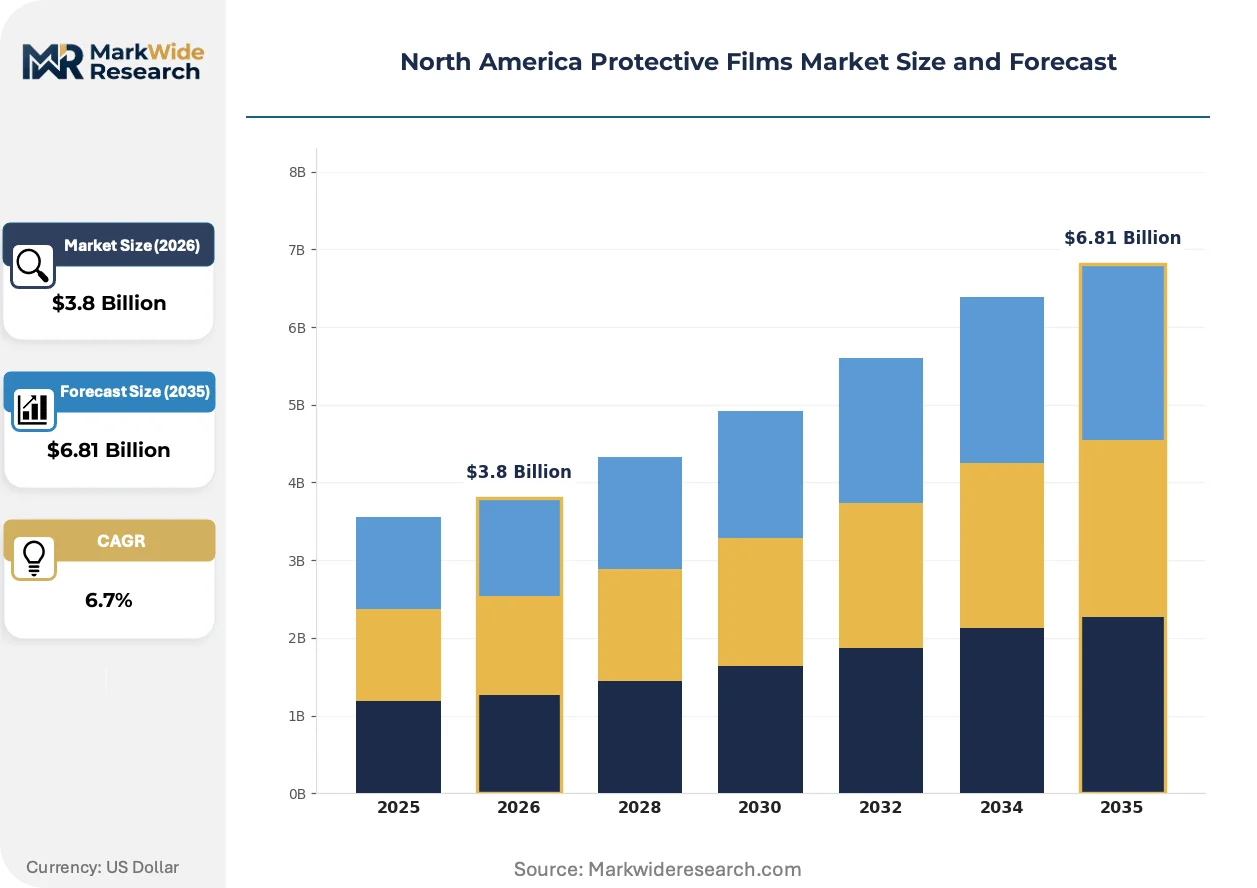
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, PET Application: Automotive, Electronics, Medical, Construction End User: Manufacturers, Distributors, Retailers, Consumers Distribution Channel: Online, Offline, Direct, Indirect |
| Companies Covered | 3M, XPEL, Eastman Chemical Company, DuPont, Saint-Gobain, Avery Dennison Corporation, Tee Group Films, Lamin-x, Mactac, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Protective Films Market Evolving Landscape
Adhesive chemistry platforms are bifurcating between commodity waterborne systems and high-performance UV-curable formulations, with equipment retrofit decisions locking in competitive trajectories for the next capital cycle.
UV-curable pressure-sensitive adhesive technology is collapsing the curing energy and floor space requirements historically associated with thermal drying ovens. Electronics contract manufacturers in California and Texas are adopting these systems at replacement cycle pace. The structural consequence is collapsing minimum efficient scale thresholds for regional film coating operations.
OSHA hazard communication mandates for isocyanate-containing formulations are tightening exposure monitoring protocols across adhesive coating facilities. Industrial consequence includes accelerated capital deployment toward containment infrastructure and personnel protective systems. High-performance automotive and aerospace film segments are responding fastest, with Tier-1 suppliers in Michigan and Ohio leading compliance timelines.
Application service unbundling is fragmenting procurement relationships as OEMs build in-house film application capabilities for repetitive high-volume operations. Traditional distributor channels serving construction glazing and automotive aftermarket segments are losing share to direct supplier-OEM contracting. The shift is most visible in the US Great Lakes corridor, where captive application centers at major automotive assembly plants are displacing third-party service providers.
North America Protective Films Market Segmentation
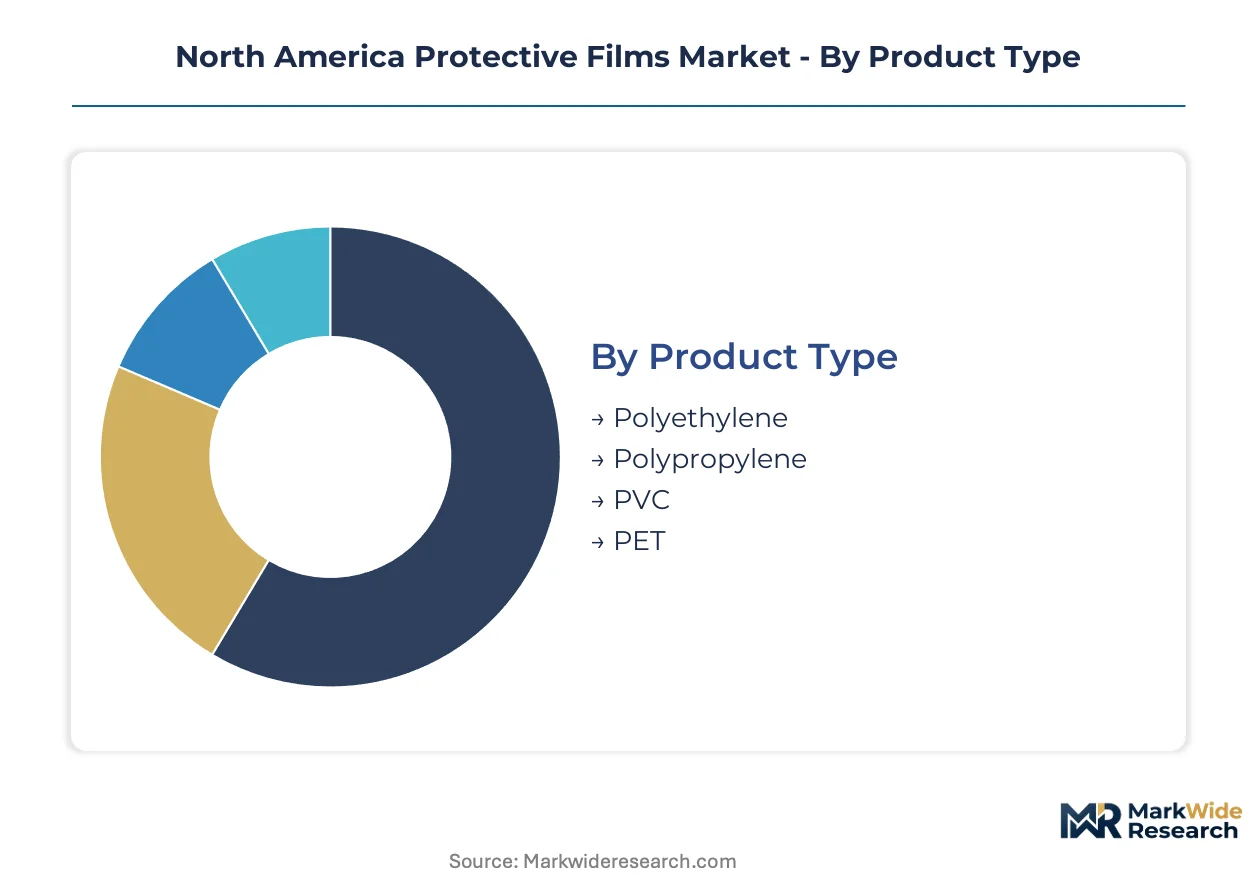
Protective film purchasing decisions in North America diverge sharply across material chemistry, application environment, and supply chain position. Each segmentation dimension carries distinct margin profiles and regulatory exposure that reshape supplier competitive strategy.
Product Type:
Material selection maps directly to durability requirements and cost tolerance across the use-case spectrum from temporary transit guarding to precision electronics handling.
- Polyethylene:Extruded low-density and linear low-density formulations deliver cost-efficient temporary surface protection with adequate puncture resistance. Automotive OEMs in Michigan and Ohio specify polyethylene for vehicle transit guarding, where 30-60 day UV stability satisfies logistics timelines without premium pricing.
- PET:Biaxially oriented polyester films provide optical clarity and dimensional stability under thermal cycling. Electronics cleanrooms in Arizona and Texas specify PET for wafer handling and display lamination, where coefficient of thermal expansion tolerance justifies 3-4x material cost premiums over polypropylene alternatives.
- Polypropylene:Cast and oriented variants occupy the mid-tier for construction glazing and appliance surface protection. The material faces substitution pressure in high-temperature electronics applications.
- PVC:Calendered vinyl films retain niche positioning in decorative surface protection and textured masking applications. California's CARB VOC regulations constrain adhesive formulation flexibility for PVC backings.
The dominant share belongs to polyethylene, while PET is closing the gap fastest.
Application:
End-use environments impose divergent performance certifications and compliance burdens that fragment supplier specialization.
- Automotive:Paint protection films and temporary transit guarding dominate volume. OEM captive application centers in the Great Lakes corridor are displacing third-party service providers for high-volume repetitive operations.
- Electronics:Semiconductor fabrication and display manufacturing specify ultra-clean, low-outgassing films. Fluoropolymer-enhanced formulations command pricing power in Arizona and Texas cleanroom environments.
- Construction:Glazing protection and surface guarding during installation drive seasonal demand peaks. Distributor relationships fragment as contractors consolidate procurement.
- Medical:Sterile barrier films and device surface protection carry FDA 510(k) pathway requirements. The segment demands validated manufacturing processes that limit supplier participation.
Automotive anchors current volume, though electronics applications are expanding most quickly.
End User:
Procurement authority concentrates differently across the value chain, reshaping pricing power and service bundling requirements.
- Manufacturers:Direct specification authority for captive application operations. Tier-1 automotive and electronics producers negotiate multi-year supply agreements with formulation customization.
- Distributors:Inventory risk-bearing intermediaries serving fragmented construction and aftermarket segments. Channel power erodes as OEMs build in-house capabilities.
- Retailers:Big-box and specialty retailers serve DIY automotive paint protection and home improvement applications. Price transparency pressures margin.
- Consumers:End purchasers of aftermarket films for vehicle and device protection. Digital channels displace traditional retail for research and purchase.
Manufacturers retain specification control, while distributor influence is compressing fastest.
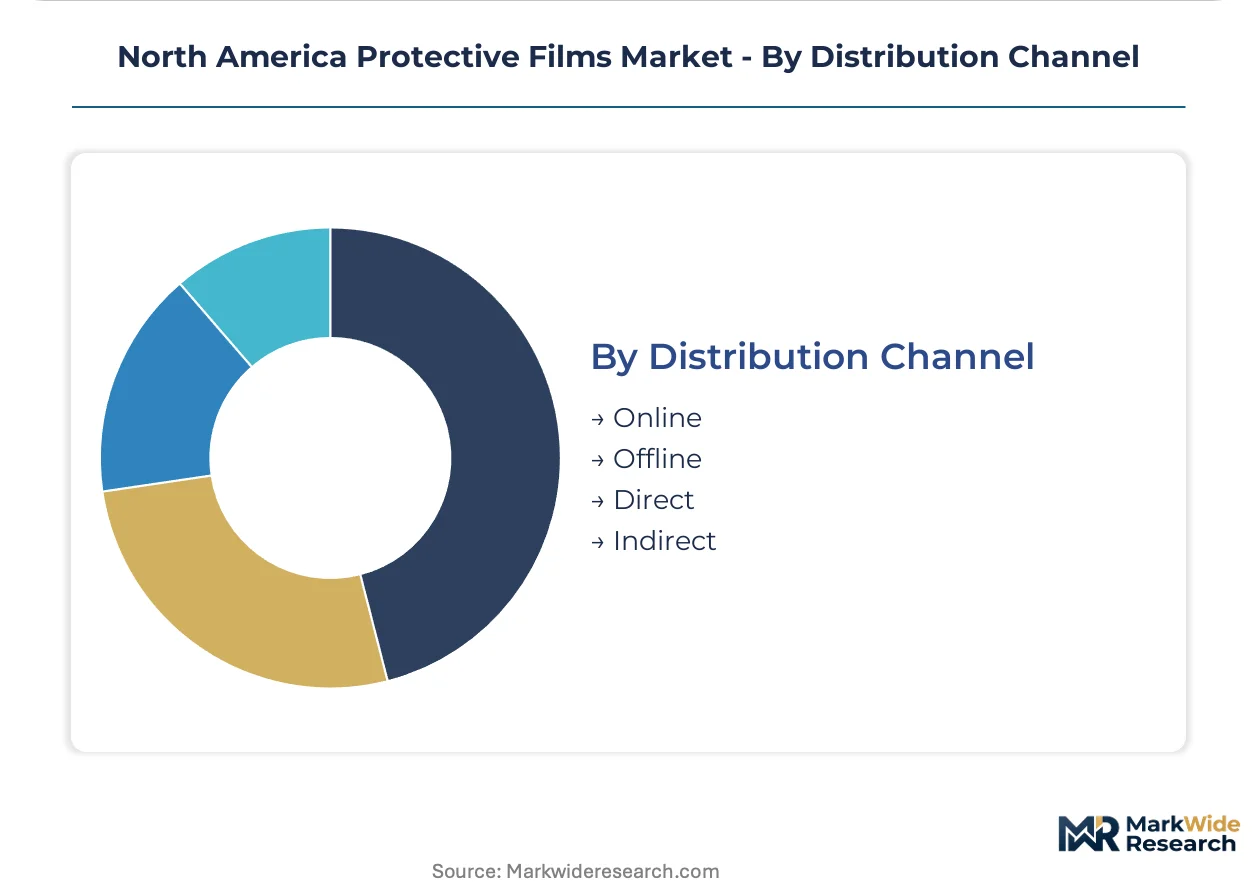
Distribution Channel:
Channel selection locks in service intensity requirements and margin capture mechanics.
- Direct:Supplier-to-OEM contracting for high-volume automotive and electronics producers. Technical service engineers co-locate at major manufacturing clusters.
- Indirect:Distributor and dealer networks serving fragmented construction and aftermarket segments. Inventory carrying costs concentrate with intermediaries.
- Online:E-commerce platforms capture consumer and small-contractor procurement. Product information standardization accelerates price comparison.
- Offline:Traditional branch and retail presence for specification support and emergency fulfillment. Footprint rationalization proceeds alongside digital investment.
Direct channels capture the dominant value pool, while online is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Film coating capacity clusters along the US Great Lakes corridor, where automotive OEM captive application centers and electronics contract manufacturers pull volume through direct supplier relationships. Mexico's nearshoring corridor and Canada's industrial heartland extend this supply base north and south.
United States
Semiconductor fabrication expansion in Arizona and Texas drives fluoropolymer-enhanced film specification for wafer handling. EPA Clean Air Act Title V permitting shapes adhesive formulation decisions across coating facilities. The Great Lakes manufacturing corridor concentrates automotive paint protection demand, with Michigan and Ohio assembly plants operating captive film application centers.
Canada
Ontario's automotive supply chain integrates protective films for vehicle transit guarding and component surface protection. Environment and Climate Change Canada administers VOC emission regulations that track EPA standards with province-specific enforcement timelines. The Windsor-Toronto industrial corridor houses film converting operations serving Detroit-area OEMs.
Mexico
Automotive assembly expansion in Nuevo León and Guanajuato creates transit protection film demand with compressed logistics loops. PROFEPA environmental enforcement is tightening air quality standards for adhesive coating operations in border states. Querétaro's aerospace cluster specifies precision films for component handling during export assembly.
North America Protective Films Market Competitive Landscape
Integrated resin producers and specialized film coaters split the market between margin capture at the polymer level and service intensity at the application layer. Market structure tilts toward consolidation in electronics-grade PET films, where backward integration into specialty polyester resin production limits viable participation. Two strategic archetypes dominate: chemical conglomerates with captive resin supply, and focused film converters with regional coating infrastructure. Competitive moves concentrate on adhesive formulation licensing and captive application center partnerships with automotive OEMs.
Within the integrated chemical conglomerate tier, 3M and Eastman Chemical Company exemplify divergent paths to margin defense. DuPont occupies a position linking fluoropolymer material science to electronics cleanroom specification. These three anchors demonstrate how raw material access, patent estate depth, and end-use certification relationships stratify competitive position.
| Leading Market Players |
|---|
| 3M |
| XPEL |
| Eastman Chemical Company |
| DuPont |
| Saint-Gobain |
| Avery Dennison Corporation |
| Tee Group Films |
| Lamin-x |
| Mactac |
| Others |
Value Network & Pricing Analysis
Specialty polyester resin production concentrates with Eastman Chemical Company and a limited supplier base, anchoring margin capture upstream while PET film converters downstream compete on coating service intensity and formulation customization.
Pricing Analysis
Aftermarket service revenue from captive application center partnerships drives lifetime value for incumbent suppliers. Three-tier pricing structure across fluoropolymer-enhanced premium films, standard PET electronics grades, and commodity polyethylene transit guarding reflects certification level and thermal cycling performance. Cost compression in waterborne adhesive formulations is intensifying because EPA Title V compliance investments are amortizing across thinner margin pools. DIY automotive consumers exhibit highest price sensitivity, whereas semiconductor cleanroom procurement teams prioritize low-outgassing certification over unit economics.
Supply Chain Analysis
Ethylene and propylene feedstock supply draws from US Gulf Coast petrochemical complexes, Canadian oil sands derivatives, and Mexican Pemex refining output. Polyethylene pellet supply, pressure-sensitive adhesive monomers, and release liner substrates constitute critical input dependencies. Single-source vulnerability sits with biaxially oriented PET film capacity concentrated among backward-integrated resin producers. Distribution runs through direct supplier-OEM contracting for automotive and electronics clusters, with distributor networks serving fragmented construction and aftermarket segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent suppliers face substitution defense against in-house film extrusion capabilities at major automotive OEMs, where captive application centers threaten to disintermediate traditional coating relationships.
For Market Incumbents: Insulate formulation IP through exclusive adhesive chemistry licensing agreements with regional coating operations. Deepen backward integration into specialty polyester resin production to bottleneck competitor PET film availability. The EPA's evolving VOC standards threaten margin compression for solvent-based adhesive portfolios, making UV-curable platform investments the critical defensive lever. For New Entrants and Emerging Players: Mexico's Nuevo León and Guanajuato automotive assembly corridors represent the most penetrable entry point for transit protection film suppliers lacking electronics cleanroom certification. Solar panel manufacturing facilities qualifying for Inflation Reduction Act incentives offer a second white-space vector with shorter qualification timelines than semiconductor applications. A direct contracting model bypassing legacy distributor relationships accelerates OEM penetration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across UV-curable adhesive coating operations as minimum efficient scale thresholds collapse. Electronics-grade PET film converters with validated low-outgassing processes and established Arizona or Texas cleanroom supply relationships represent the preferred acquisition archetype. Watch for EPA state-level alignment announcements between California, Illinois, and Michigan as the signal indicating formulation compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resin | Eastman Chemical Company's captive polyester supply bottlenecks competitor PET film availability. |
| UV-Curable Adhesive Platform Migration | California electronics manufacturers adopt curing systems that collapse thermal oven floor space requirements. |
| Captive Application Center Partnerships | Michigan and Ohio automotive OEMs displace third-party service providers for repetitive transit guarding. |
| Fluoropolymer-Enhanced Formulation Development | DuPont leverages material science heritage for wafer handling specification in Arizona cleanrooms. |
| Mexico Nearshoring Corridor Expansion | Nuevo León assembly plants demand compressed logistics loops for just-in-time surface protection. |
Research Methodology
A standing panel of adhesive R&D directors, automotive OEM procurement managers, electronics cleanroom operations leads, and distributor channel partners provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against EPA enforcement databases, SEC 10-K chemical segment disclosures, and ACC resin production statistics. Bottom-up volume estimates from coating facility utilization rates triangulated against top-down petrochemical feedstock consumption patterns.
Scenario-bracketing around regulatory compliance timelines and feedstock price volatility informed the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry tier, end-use industry cluster, adhesive formulation platform, and regional manufacturing corridor concentration. CAGRs derived from facility expansion announcements, OEM contract award patterns, and substitution elasticity estimates for electronics thermal cycling applications.
Practitioners should monitor EPA state-level regulatory divergence, resin producer capacity utilization reports, and automotive OEM captive center buildout announcements for early signals requiring forecast revision. Cross-checking against ACC polyethylene production statistics and IHS Markit vehicle assembly data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Lining Market
Packaging Barrier Films
USA Stretch Hood Films Market
Packaging Barrier Films
Barrier Films Market
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
Barrier Shrink Films Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Global Metalized Barrier Films Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
Specialty Films Market
Packaging Barrier Films
Insulation Film Market