
 Aluminum Foil Laminated Paper Market | 2026-2036
Aluminum Foil Laminated Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Foil Laminated Paper Market Outlook
Skilled laminating technicians is collapsing across European converting hubs, tightening output capacity for precision-coated rolls. Mondi Group anchors its position through captive pulp supply and in-house metallization lines. Amcor Limited leverages pharmaceutical-grade cleanroom certifications to dominate medical pouch demand. Constantia Flexibles specializes in confectionery wrapping formats for premium chocolate brands.
Aluminum foil laminated paper bonds thin metallic layers to paper substrates through extrusion or adhesive lamination, achieving oxygen transmission rates below 0.1 cc per square meter per day for sensitive goods. Flexible Packaging leads volume as snack and coffee brands adopt high-barrier pouches with reseal features. Medical Packaging posts the fastest structural expansion as sterilizable laminated formats replace rigid trays in surgical kit wrapping. Food Containers command premium margins where direct-heat tolerance differentiates specialty grades from standard barrier wraps.
FDA food-contact substance notifications govern laminate composition for US-bound exports, while EU REACH restricts certain adhesive chemistries in consumer-facing packaging. Germany's national packaging regulator enforces extended producer responsibility fees that favor recyclable paper-aluminum structures over multi-plastic alternatives. Stakeholders must monitor evolving state-level extended producer responsibility laws and calibrate laminate recyclability claims against emerging fiber recovery standards.
Market Dynamics
Skilled laminating technician availability is collapsing across European converting hubs, tightening precision-coated roll output capacity and forcing converters to automate or consolidate. This labor scarcity intersects with tightening EU Packaging and Packaging Waste Regulation compliance timelines to reshape competitive positioning.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates favor recyclable paper-aluminum structures over multi-plastic alternatives, accelerating brand switching in Germany and France.
- Pharmaceutical sterilization demand:Surgical kit wrapping formats are replacing rigid trays, pulling medical-grade laminated volumes upward.
- Confectionery barrier requirements:Premium chocolate brands in Switzerland and Belgium specify high-oxygen-barrier wraps for extended shelf stability.
Market Restraints
- Aluminum ingot price volatility:Raw material swings compress converter margins and complicate long-term contract pricing.
- Adhesive chemistry restrictions:EU REACH limits certain solvent-based bonding agents, forcing reformulation investments.
- Plastic film substitution threat:Multi-layer polymer pouches retain cost advantages in commodity snack segments.
Strategic Opportunities
- India pharmaceutical export growth:CDSCO-registered converters can capture rising demand for sterilizable medical pouches bound for Middle Eastern and African markets.
- Water-based lamination convergence:Combining aqueous adhesive systems with in-house metallization lines eliminates solvent recovery capex.
- Direct-to-brand e-commerce channels:Specialty coffee roasters in Scandinavia now procure custom-printed laminated rolls bypassing traditional distributors.
Industry Challenges
- Precision coating technician scarcity:European technical schools produce fewer qualified operators than retiring cohorts.
- FDA food-contact notification timelines:US-bound exporters face 12-18 month clearance windows for novel laminate compositions.
- Legacy extrusion line retrofit costs:Converters must integrate inline defect detection without halting continuous production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Foil Laminated Paper Market |
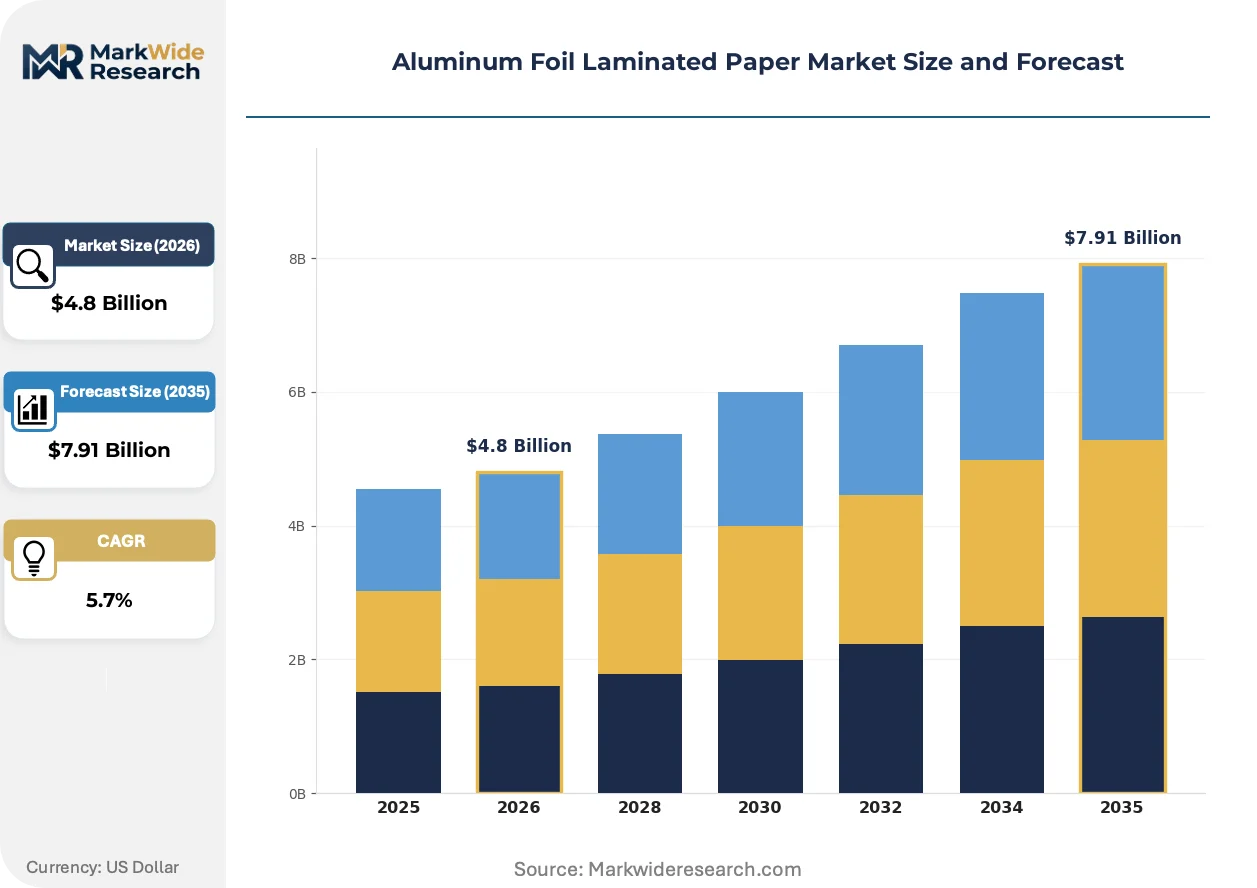
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Confectionery Wrapping, Food Containers, Medical Packaging Application: Food & Beverage, Pharmaceuticals, Cosmetics, Industrial Uses End User: Manufacturers, Retailers, Wholesalers, Distributors Packaging Type: Rolls, Sheets, Pouches, Bags |
| Companies Covered | Amcor Limited, Mondi Group, Huhtamäki Oyj, Tetra Pak International, Smurfit Kappa Group, Constantia Flexibles, Sealed Air Corporation, Berry Global, Alcoa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Foil Laminated Paper Market Strategic Shifts
Water-based and solventless lamination technologies are actively displacing conventional adhesive systems across European converting floors. These shifts compress capital recovery timelines while raising the technical floor for market participation.
Nano-coating deposition systems are fragmenting barrier performance thresholds by enabling sub-micron ceramic layers atop paper substrates. Snack brands in the Netherlands and Denmark pilot these formats for oxygen-sensitive nut and dried fruit applications. The technology is fragmenting the traditional aluminum foil thickness specifications that dominated premium barrier segments.
REACH adhesive chemistry restrictions are forcing converters to validate water-based bonding agents for high-speed production lines. German and Austrian regulators now require comprehensive migration testing for consumer-facing packaging. Medical pouch converters are responding by segregating pharmaceutical-grade cleanroom operations from food-contact lamination to prevent cross-contamination liability.
Brand procurement teams are consolidating supplier panels from twelve-plus vendors to three or four strategic partners. Coffee roasters and confectionery houses in Italy and Spain now demand vertically integrated converters capable of pulp-to-metallized-film production. This concentration is most visible in northern Italy, where family-owned chocolate brands negotiate multi-year laminated roll supply agreements with integrated paper mills.
Aluminum Foil Laminated Paper Market Segmentation
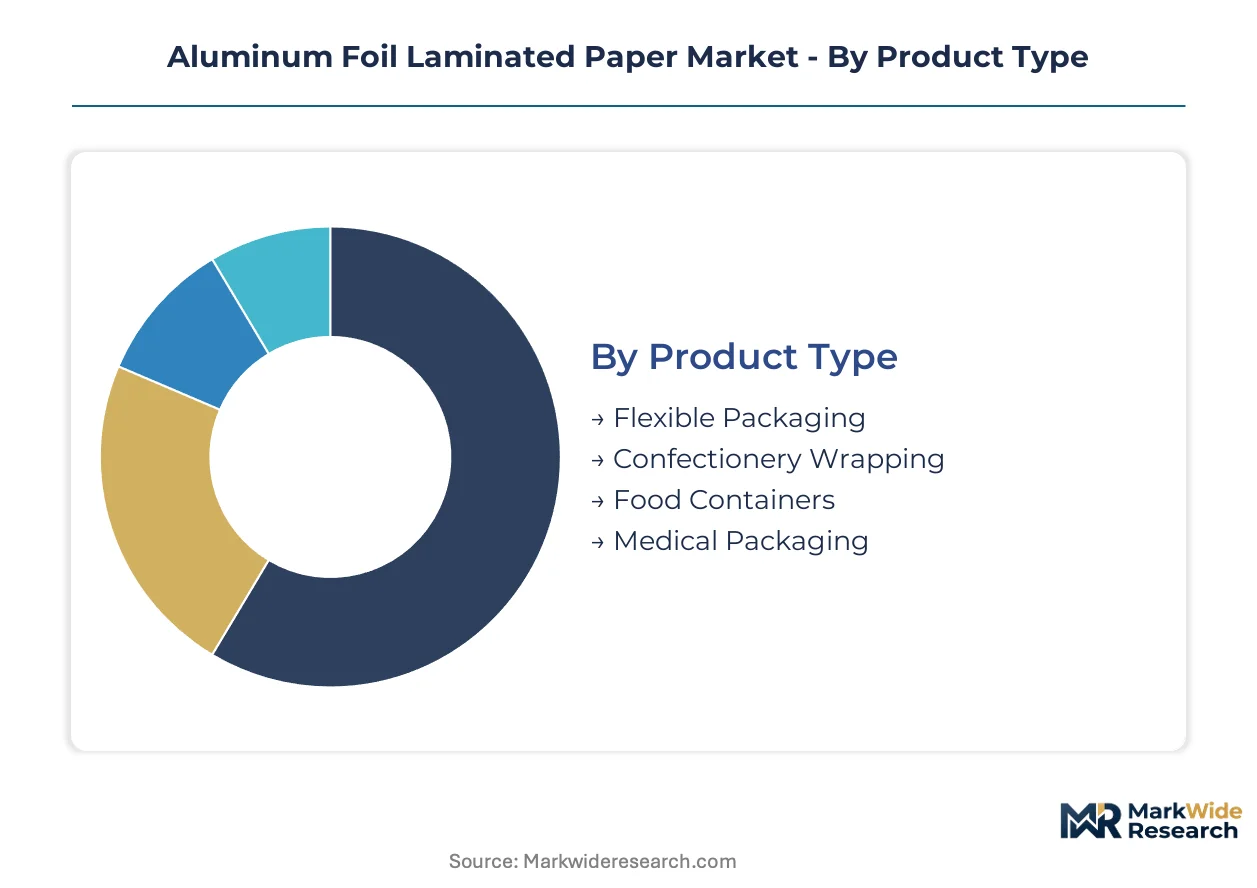
Segmentation in aluminum foil laminated paper reveals how barrier performance requirements and regulatory compliance reshape procurement patterns across converting channels. Distinct product specifications, application demands, and packaging formats each command dedicated supply chain configurations.
Product Type:
Flexible Packaging and Medical Packaging flow through certified converting hubs, while Confectionery Wrapping and Food Containers route through specialty printers with direct brand relationships.
- Flexible Packaging:Multi-layer laminates with 6-12 micron aluminum foil bonded to kraft or glassine substrates achieve oxygen transmission rates below 0.1 cc/m²/day. Snack and coffee brands in Germany and the Netherlands specify resealable pouch formats with inline zipper applications, pulling volume through high-speed slitting operations.
- Medical Packaging:Sterilizable laminated formats for surgical kit wrapping replace rigid tray systems in hospital supply chains. Cleanroom-certified converters in Switzerland and Belgium dominate this segment as EMA medical device regulations tighten barrier documentation requirements.
- Confectionery Wrapping:Premium chocolate brands specify dead-fold properties and grease resistance for twist-wrap applications.
- Food Containers:Direct-heat tolerant grades serve ready-meal applications where microwave safety differentiates specialty laminates.
Flexible Packaging dominates installed base. Medical Packaging is where expansion concentrates.
Application:
Cost tier stratification separates commodity food wraps from pharmaceutical-grade certified laminates with tenfold price multiples.
- Food & Beverage:Dairy and confectionery processors in Germany specify high-barrier laminated wraps for extended shelf stability under EU Packaging and Packaging Waste Regulation compliance timelines. REACH adhesive restrictions force reformulation investments across this volume-leading segment.
- Pharmaceuticals:Sterilizable pouch demand climbs as surgical kit distributors abandon rigid trays. CDSCO-registered converters in India capture rising export volumes bound for Middle Eastern hospital supply chains.
- Cosmetics:Premium skincare brands specify metallized paper for sustainable luxury positioning against plastic alternatives.
- Industrial Uses:Insulation and electronics shielding applications consume standard-grade laminates with less stringent barrier specifications.
Food & Beverage commands volume scale. Pharmaceuticals generates margin expansion.
End User:
Customer type determines order minimums and technical service intensity, with Manufacturers requiring metallurgical certification that Distributors rarely demand.
- Manufacturers:Confectionery and dairy processors in northern Italy negotiate multi-year laminated roll supply agreements with integrated paper mills capable of pulp-to-metallized-film production.
- Retailers:Private-label coffee roasters in Scandinavia procure custom-printed laminated rolls through direct-to-brand e-commerce channels, bypassing traditional distribution tiers.
- Wholesalers:Stock-and-sell operations in France and Spain aggregate standard grades for smaller converting operations without metallization capacity.
- Distributors:Pan-European logistics networks serve fragmented snack producers with just-in-time roll deliveries.
Manufacturers anchor long-term contract structures. Retailers are gaining share fastest in custom-format procurement.
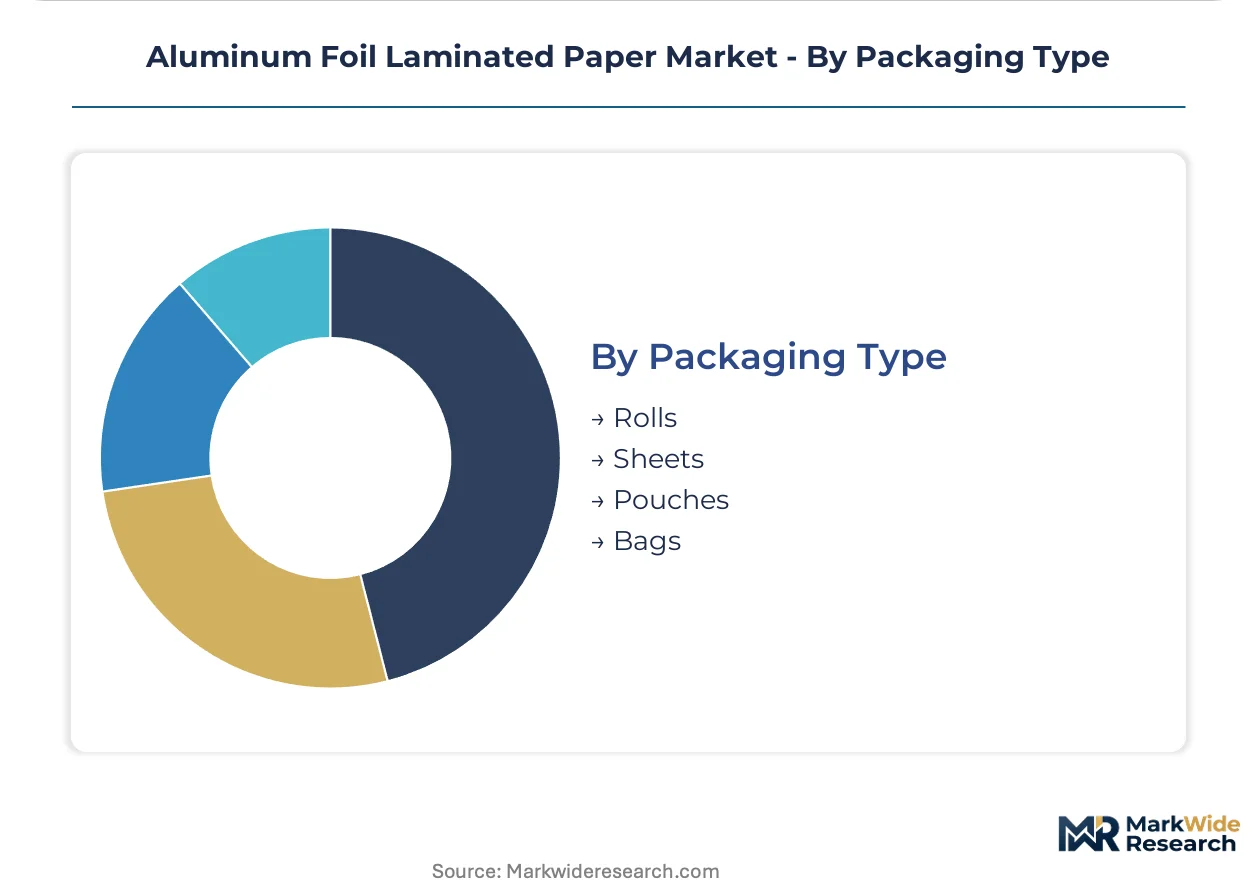
Packaging Type:
Supply concentration varies by format, with Pouches requiring precision converting equipment that Rolls do not.
- Rolls:Master rolls of 1000-2000 meter length feed downstream slitting and printing operations. German and Austrian converters maintain captive metallization lines to control barrier consistency for pharmaceutical-grade shipments.
- Sheets:Cut-to-size formats serve artisan chocolate producers in Belgium and Switzerland with low minimum order quantities and rapid changeover requirements.
- Pouches:Pre-formed bags with reseal features demand inline zipper welding and defect detection systems that raise technical entry barriers.
- Bags:Side-gusseted formats for coffee and nuts require high-strength seal layers compatible with vacuum packaging equipment.
Rolls dominate production throughput. Pouches concentrate technology investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA medical device regulations tighten barrier documentation requirements across Switzerland and Belgium, while EU Packaging and Packaging Waste Regulation compliance timelines reshape procurement patterns in Germany and France.
Germany
Confectionery and dairy processors in Bavaria and North Rhine-Westphalia specify high-barrier laminated wraps for extended shelf stability. The national packaging regulator enforces extended producer responsibility fees favoring recyclable paper-aluminum structures. Converting hubs around Hamburg and Cologne face collapsing skilled laminating technician availability, tightening precision-coated roll output capacity.
Switzerland
Premium chocolate brands in Zurich and Geneva demand dead-fold properties and grease resistance for twist-wrap applications. Swissmedic pharmaceutical regulations govern sterilizable pouch formats for surgical kit wrapping. Cleanroom-certified converters in the Basel region dominate medical-grade laminated volumes as EMA requirements intensify.
Belgium
Artisan chocolate producers in Brussels and Antwerp procure cut-to-size sheet formats with low minimum order quantities. REACH adhesive chemistry restrictions force validation of water-based bonding agents for high-speed production lines. Converting operations in the Flanders region segregate pharmaceutical-grade cleanroom operations from food-contact lamination.
Netherlands
Snack brands in Amsterdam and Rotterdam pilot nano-coating deposition systems for oxygen-sensitive nut and dried fruit applications. EU Green Deal packaging sustainability targets accelerate brand switching from multi-plastic alternatives. High-speed slitting operations in the Randstad serve resealable pouch formats with inline zipper applications.
India
CDSCO-registered converters capture rising export volumes for sterilizable medical pouches bound for Middle Eastern hospital supply chains. FSSAI food-contact regulations govern laminate composition for domestic dairy and confectionery processors. Pharmaceutical packaging clusters in Maharashtra and Gujarat expand metallization capacity to serve African market demand.
Aluminum Foil Laminated Paper Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Integrated paper mills with captive metallization lines control premium barrier consistency for pharmaceutical-grade shipments. Specialist converters without upstream pulp access compete on rapid changeover and custom-printing capabilities for artisan chocolate and specialty coffee segments. Dominant competitive moves include backward integration into pulp supply and geographic expansion into CDSCO-registered production hubs for Middle Eastern medical pouch exports.
Within the integrated leader tier, Mondi Group and Amcor Limited exemplify divergent strategic positioning. Mondi anchors its market presence through captive pulp supply and in-house metallization lines, representing the backward-integrated archetype. Amcor occupies a position defined by pharmaceutical-grade cleanroom certifications, exemplifying the regulatory-specialist archetype for medical pouch demand.
| Leading Market Players |
|---|
| Amcor Limited |
| Mondi Group |
| Huhtamäki Oyj |
| Tetra Pak International |
| Smurfit Kappa Group |
| Constantia Flexibles |
| Sealed Air Corporation |
| Berry Global |
| Alcoa |
| Others |
Value Chain & Pricing Dynamics
FDA food-contact substance notifications gate both supply qualification and price differentiation simultaneously, as converters without cleared laminate compositions forfeit US-bound pharmaceutical and food export volumes while commanding premium tier positioning through certification investment.
Pricing Analysis
German pharmaceutical-grade laminates trade at substantial premiums over standard food-contact grades produced in India and Southeast Asia. Three-tier pricing structure across premium, standard, and economy levels reflects cleanroom certification status, barrier performance documentation, and metallization consistency. Cost compression in standard food-contact tiers is intensifying because aluminum ingot price volatility forces converters to absorb raw material swings in contracted volumes. Commodity snack producers exhibit highest price sensitivity, while Swiss medical device manufacturers prioritize barrier documentation over unit cost.
Supply Chain Analysis
Metallized film capacity concentration in Germany, Switzerland, and Austria creates chokepoint vulnerability for pharmaceutical-grade laminates serving EMA-regulated markets. Raw material flows draw from Norwegian aluminum smelters, Finnish pulp mills, and specialty adhesive manufacturers in the Netherlands. Single-source vulnerability runs through captive metallization lines at integrated paper mills, where technical failures halt precision-coated roll output. Distribution runs through certified converting hubs for medical grades and direct mill relationships for food-contact volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement panels, as coffee roasters and confectionery houses in Italy and Spain reduce supplier counts from twelve-plus vendors to three or four strategic partners with pulp-to-metallized-film capabilities.
For Market Incumbents: Compound barrier performance advantages by segregating pharmaceutical-grade cleanroom operations from food-contact lamination to prevent cross-contamination liability. Deepen upstream control over metallization lines in Germany and Switzerland to defend against nano-coating deposition systems that fragment traditional aluminum foil specifications. Prioritize water-based lamination technology investments as EU REACH adhesive restrictions eliminate solvent-based alternatives. For New Entrants and Emerging Players: Differentiate on CDSCO-registered production for sterilizable medical pouches bound for Middle Eastern and African hospital supply chains, where demand outpaces qualified converter capacity. Target artisan chocolate producers in Belgium and Switzerland with cut-to-size sheet formats and rapid changeover capabilities that integrated mills disdain. Pursue direct-to-brand e-commerce channels for specialty coffee roasters in Scandinavia, bypassing traditional distribution tiers entirely. For Investors and Strategic Acquirers: Secondary-cycle assets sit with family-owned Italian and Spanish converters possessing custom-printing capabilities but lacking captive pulp supply or in-house metallization lines. Five-to-ten year viability hinges on water-based lamination technology adoption and REACH-compliant adhesive validation. Watch for aluminum ingot price volatility spikes as inflection indicators that compress converter margins and force distressed asset sales.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Lamination Transition | Eliminates solvent recovery capex while satisfying EU REACH adhesive chemistry restrictions. |
| Captive Metallization Line Investment | Secures barrier consistency for pharmaceutical-grade shipments to Swissmedic-regulated markets. |
| CDSCO Registration for Export Growth | Unlocks sterilizable medical pouch demand from Middle Eastern hospital supply chains. |
| Cleanroom Operation Segregation | Prevents cross-contamination liability between pharmaceutical and food-contact lamination. |
| Direct-to-Brand E-Commerce Channel | Bypasses traditional distribution tiers for specialty coffee roasters in Scandinavian markets. |
Study Parameters
A standing panel of laminating technicians, pharmaceutical packaging procurement managers, confectionery brand supply chain directors, and EU regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from EMA medical device regulation filings, FDA food-contact substance notifications, EU REACH compliance databases, and customs trade data for aluminum foil and metallized paper categories. Bottom-up volume estimates from converting capacity and top-down demand segmentation from end-use applications underwent iterative reconciliation.
Forecast outputs were validated against external benchmarks including trade association production statistics and regulatory filing trends across the analysis window. Segmentation dimensions modeled include product type, application, end user, and packaging format alongside regional regulatory cluster differentiation. CAGRs were derived from installed base growth rates and substitution dynamics rather than extrapolated trend lines. Industry-specific inputs incorporated aluminum ingot price volatility patterns and skilled technician availability trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EU Packaging and Packaging Waste Regulation enforcement or abrupt aluminum supply disruptions would require recalibration. Forecasts reflect documented assumptions regarding REACH adhesive reformulation timelines and nano-coating deposition technology adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Letterpress Card Market
Paper & Paperboard Packaging
Coated Recycled Paperboard Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Global Food Contact Papers Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
South East Asia Corrugated Packaging Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Global Solid Board Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
Australia Corrugated Board Packaging Market