
 Modified Atmosphere Packaging (MAP) Market | 2026-2036
Modified Atmosphere Packaging (MAP) Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Atmosphere Packaging (MAP) Market Foresight
Asset-light leasing models for gas-distribution equipment are tilting competitive dynamics toward mid-scale food processors that previously lacked capital for in-house MAP systems. Sealed Air Corporation leverages its integrated film-and-equipment portfolio to sustain pricing power across high-volume protein accounts. Amcor PLC anchors its position through global resin sourcing networks that compete effectively against regional converters. Linde AG differentiates by controlling captive carbon dioxide and nitrogen supply chains in key European production zones.
Modified Atmosphere Packaging is a technique that replaces air inside a sealed package with a controlled gas mixture—typically nitrogen, carbon dioxide, and oxygen in ratios tailored to specific food chemistries—to slow microbial growth and oxidative degradation. The process operates at precise residual oxygen levels, often below one percent for red meat applications, to preserve color and extend commercial viability. Meat applications dominate value generation due to protein spoilage sensitivity and retail premiumization, while polyethylene films lead material volumes owing to cost-performance balance in barrier structures. E-commerce end-use represents the fastest-expanding demand channel as chilled last-mile requirements reshape fulfillment specifications.
FDA food-contact substance notifications govern barrier film chemistries in the United States, while the EU Packaging and Packaging Waste Regulation mandates recyclability targets that reshape material selection across European supply chains. ISO 22000 food safety management standards further condition market access by requiring documented gas-mixture calibration protocols. Stakeholders must monitor evolving extended producer responsibility frameworks and assess whether mono-material barrier innovations can satisfy both performance and circularity requirements without triggering reformulation costs.
Market Dynamics
Asset-light leasing models for gas-distribution equipment are dismantling capital barriers that historically excluded mid-scale food processors from in-house MAP capabilities, reshaping competitive access across protein packaging tiers.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are accelerating mono-material barrier film R&D, pulling converters toward circular design investments that lock in long-term supply relationships with retail chains.
- Prepared meal delivery expansion:Food service operators scaling chilled last-mile networks are specifying MAP for extended shelf-life guarantees, creating equipment demand from ghost kitchen clusters and centralized commissaries.
- Residual oxygen control below one percent:Precision gas-mixture calibration protocols required for red meat color retention are differentiating equipment vendors and locking protein processors into integrated film-and-system contracts.
Market Restraints
- Captive carbon dioxide supply concentration:Industrial gas majors control CO2 sourcing in key European production zones, exposing processors to input cost volatility when fertilizer plant curtailments disrupt merchant supply.
- Multi-layer barrier film complexity:Current polyethylene-EVOH laminates resist mechanical recycling under EU circularity mandates, forcing converters to absorb reformulation costs or risk market exclusion.
- High-pressure gas equipment capex:In-house MAP system deployment requires nitrogen and CO2 distribution infrastructure that mid-tier processors cannot finance without leasing intermediaries.
Strategic Opportunities
- India cold chain infrastructure gaps:Underpenetrated organized retail and quick-commerce fulfillment networks present first-mover positioning for MAP equipment lessors targeting protein and dairy processors in Mumbai and Delhi corridors.
- ISO 22000 certification convergence:Documented gas-mixture calibration protocols are becoming de facto market access requirements, creating service revenue streams for auditors and equipment validation specialists.
- E-commerce chilled fulfillment specifications:Last-mile temperature integrity mandates from quick-commerce platforms are displacing passive cooling with active MAP specifications in fresh produce categories.
Industry Challenges
- Gas-mixture calibration technician scarcity:Qualified personnel capable of maintaining residual oxygen levels below one percent across red meat production lines command wage premiums that compress processor margins.
- Legacy film inventory stranding:Multi-layer barrier stockpiles face accelerated obsolescence as EU recyclability deadlines approach, forcing write-downs for converters slow to pivot toward mono-material structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Atmosphere Packaging (MAP) Market |
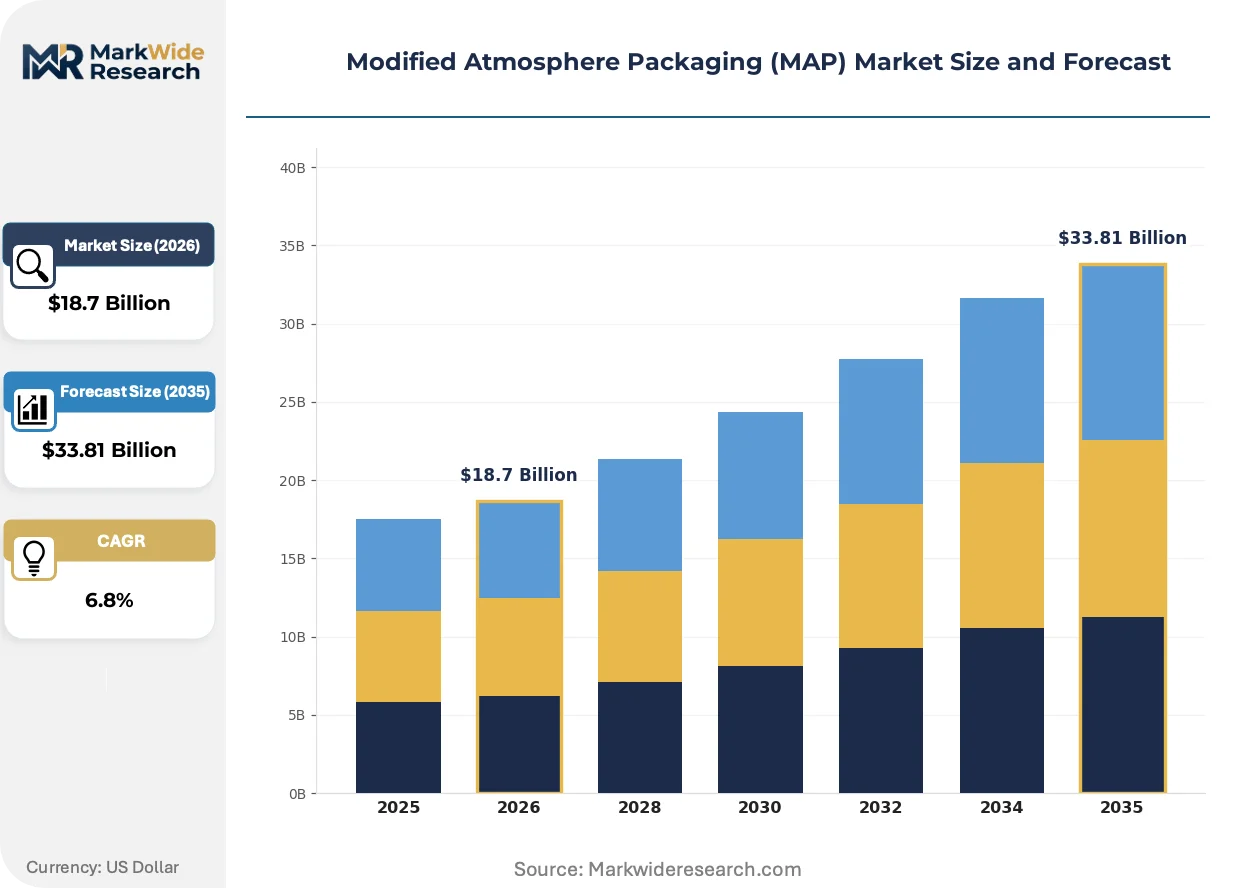
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat, Dairy, Vegetables, Snacks Packaging Material: Polyethylene, Polypropylene, Nylon, Paper Application: Food Preservation, Extended Shelf Life, Retail Packaging, Bulk Packaging End User: Food Service, Retail, Agriculture, E-Commerce |
| Companies Covered | Sealed Air Corporation, Amcor PLC, Linde AG, Berry Global Inc., Air Products and Chemicals Inc., Mondi Group, Praxair Inc., Multivac Group, Multisorb Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Atmosphere Packaging (MAP) Market Shifts & Advancements
Digital integration across gas-mixture control systems and barrier film traceability is compressing quality assurance cycles and enabling predictive maintenance models that reshape equipment procurement economics.
Smart sensor arrays embedded in MAP equipment are digitizing real-time residual oxygen monitoring, replacing manual sampling protocols. Mid-scale protein processors in Germany's Ruhr corridor are deploying these systems to reduce spoilage claims. The technology is digitizing quality control workflows and compressing the window between deviation detection and corrective action.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant coatings from barrier film formulations. European converters are accelerating plasma-deposited silicon oxide alternatives to maintain oxygen barrier performance. High-volume poultry accounts face the steepest reformulation timelines as coating substitutions require line-speed validation.
Subscription-based equipment leasing is displacing outright purchase for gas-distribution infrastructure. Quick-commerce fulfillment centers in São Paulo and Mexico City are specifying operating-expense models that bundle maintenance and gas supply. Brazil's protein processors report faster deployment cycles under this structure compared to capital-approval timelines at legacy retail chains.
Modified Atmosphere Packaging (MAP) Market Segmentation
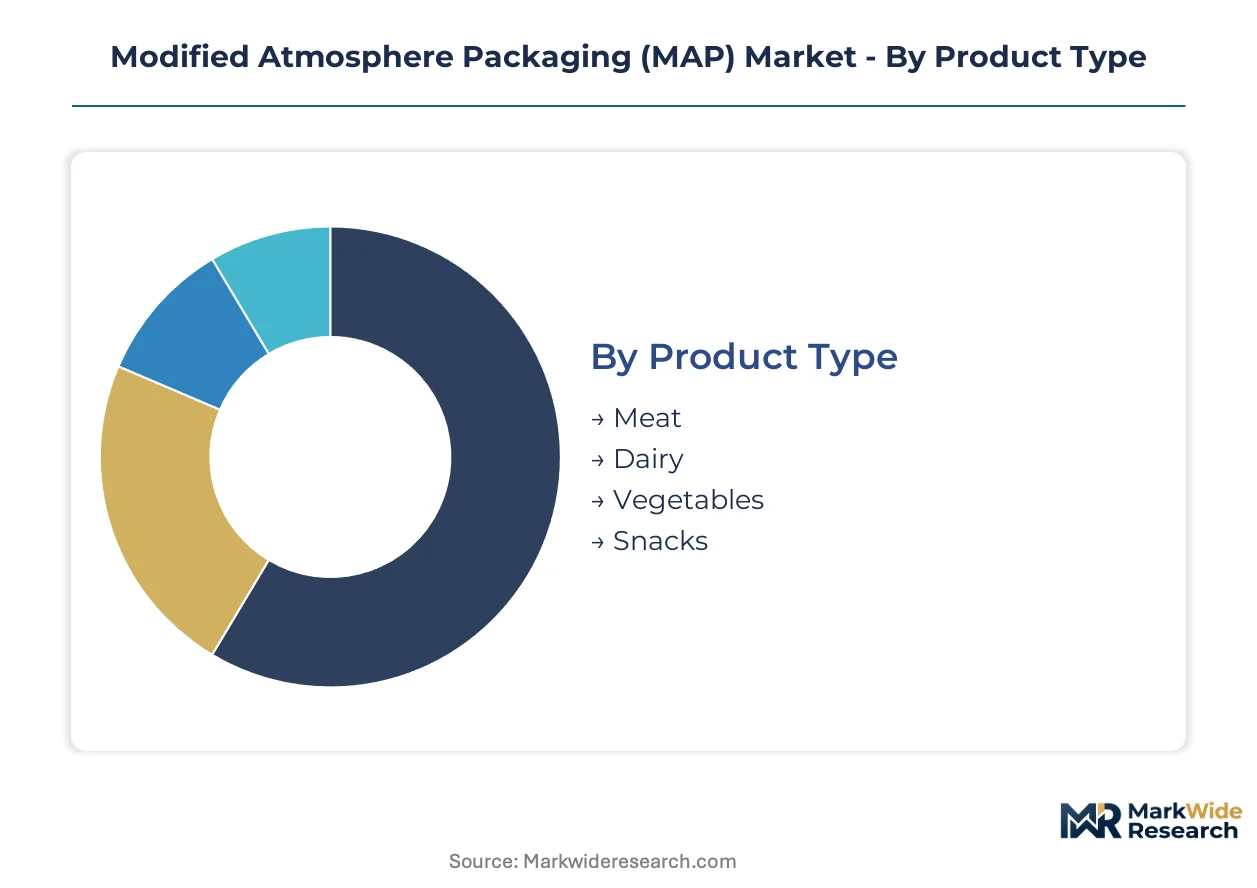
Segmentation in Modified Atmosphere Packaging reveals divergent equipment-service intensity across protein categories, with red meat applications demanding precision calibration support while produce segments tolerate lower-touch deployment models.
Product Type:
After-sales service intensity escalates dramatically for high-spoilage proteins, where residual oxygen control failures trigger immediate commercial losses and equipment vendors capture recurring calibration revenue.
- Meat:Requires sub-one-percent residual oxygen protocols to preserve myoglobin color stability in beef and pork. German processors in the Ruhr corridor anchor equipment demand due to centralized slaughterhouse capacity and retail premiumization mandates.
- Dairy:Moderate gas-mixture precision suffices for cheese and yogurt applications, with nitrogen flushing dominating over complex multi-gas blends. Demand clusters in French and Italian specialty cheese corridors where export shelf-life requirements drive MAP specification.
- Vegetables:Respiring produce demands dynamic oxygen-carbon dioxide balancing that adjusts to metabolic rates. Modified atmosphere specifications vary sharply by cultivar and harvest season.
- Snacks:Nitrogen displacement of oxygen prevents rancidity in nuts and crisps with relatively standardized equipment configurations. Volume scale in snack manufacturing favors rapid equipment amortization.
By volume, Meat leads. By growth pace, Vegetables is ahead.
Packaging Material:
Material cost tiers stratify converter margins, with commodity polyolefins competing on throughput scale while engineered barrier films command formulation premiums tied to recyclability compliance deadlines.
- Polyethylene:Dominates flexible barrier structures through cost-performance balance in lidding and base webs. European converters face forced reformulation as EU Packaging and Packaging Waste Regulation deadlines approach for multi-layer laminate phase-out.
- Polypropylene:Stiffness and clarity advantages suit rigid tray applications for fresh-cut produce. Retort-compatible grades expand into prepared meal segments requiring thermal processing compatibility.
- Nylon:Oxygen barrier and puncture resistance serve bone-in meat and vacuum skin packaging where mechanical abuse risks concentrate. Higher resin costs limit penetration in price-sensitive poultry accounts.
- Paper:Emerging fiber-based barriers target single-use plastic reduction mandates in Nordic retail chains. Barrier coating integrity remains the critical performance gap for high-moisture protein applications.
By installed base, Polyethylene dominates. By substitution pressure from circularity mandates, Paper is climbing fastest.
Application:
Application maturity determines equipment standardization, with established food preservation protocols commoditizing while emerging extended shelf-life specifications demand customized gas-mixture engineering.
- Food Preservation:Standard nitrogen-carbon dioxide blends for microbial inhibition across commodity proteins. Equipment configurations have achieved high standardization.
- Extended Shelf Life:Precision gas tailoring for export logistics and distant retail distribution. Brazilian beef exporters to Asian markets specify 45-day shelf-life guarantees requiring advanced barrier films.
- Retail Packaging:Case-ready meat programs in US and European supermarkets drive high-barrier lidding film demand. Overwrap transparency and printability condition brand differentiation.
- Bulk Packaging:Master bag-in-box configurations for food service and industrial ingredient supply. Lower barrier requirements permit cost-optimized material structures.
By revenue concentration, Retail Packaging leads. By specification complexity expansion, Extended Shelf Life is gaining share fastest.
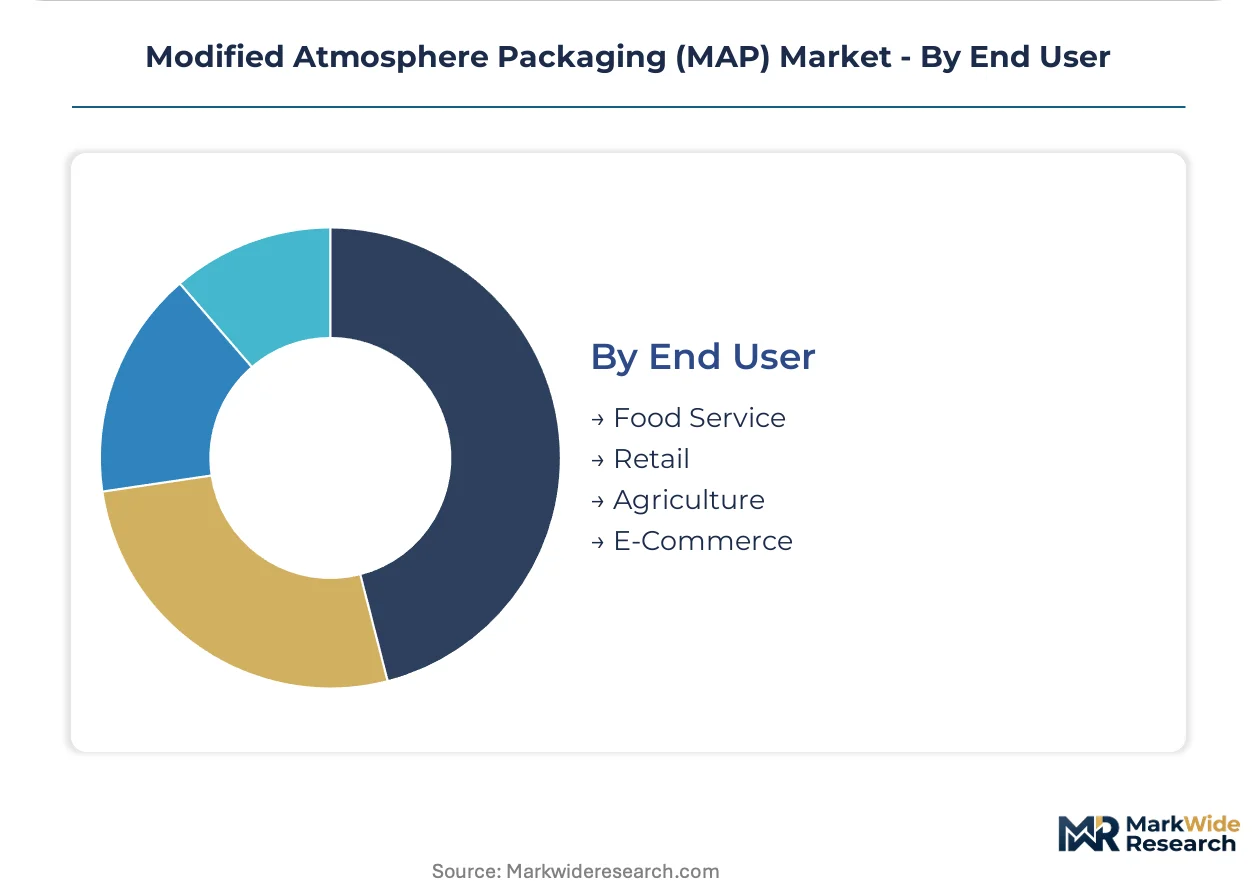
End User:
Customer procurement scale and technical sophistication determine equipment deployment models, with fragmented food service operators driving leasing innovation while consolidated retail chains exercise direct purchasing leverage.
- Food Service:Ghost kitchen clusters and centralized commissaries specify MAP for prepared meal consistency. Asset-light leasing models dismantle capital barriers for mid-scale operators.
- Retail:Supermarket private-label programs demand integrated film-and-equipment contracts with volume guarantees. German discounters and UK grocers anchor category purchasing power.
- Agriculture:Fresh produce cooperatives adopt modified atmosphere for export conditioning. Technical advisory requirements exceed in-house capabilities for smaller grower associations.
- E-Commerce:Quick-commerce fulfillment centers in São Paulo and Mexico City specify active MAP over passive cooling for last-mile temperature integrity. Chilled delivery guarantees reshape equipment specifications.
By current equipment installed base, Retail leads. By deployment velocity, E-Commerce is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment vendors extract pricing premiums from Ruhr corridor processors that Brazilian exporters cannot replicate, creating a transatlantic margin asymmetry that shapes investment flows across the MAP value chain.
Germany
Centralized slaughterhouse capacity in North Rhine-Westphalia drives demand for sub-one-percent residual oxygen systems. The EU Packaging and Packaging Waste Regulation mandates mono-material barrier transitions by 2030, forcing converters in the Ruhr corridor to absorb reformulation costs. Dortmund-based equipment clusters anchor aftermarket service revenue for gas-mixture calibration.
United States
FDA food-contact substance notifications govern barrier film chemistries for retail meat programs. Case-ready specifications from Walmart and Kroger concentrate purchasing power in the Midwest protein belt. Chicago-area processors deploy nitrogen-CO2 distribution infrastructure for 45-day shelf-life guarantees on export beef.
Brazil
Beef exporters to Asian markets specify extended shelf-life MAP for transoceanic logistics. ANVISA regulates food-contact materials with compliance timelines shorter than European equivalents. São Paulo quick-commerce fulfillment centers specify subscription-based equipment leasing over capital purchase.
China
Dual carbon goals under MIIT guidance accelerate cold chain infrastructure investment in Yangtze River Delta protein processing. GB standards for food packaging materials diverge from ISO frameworks, creating compliance friction for multinational film suppliers. Shanghai corridor processors trial smart sensor arrays for real-time oxygen monitoring.
India
Organized retail penetration in Mumbai and Delhi corridors lags cold chain coverage, creating first-mover positioning for equipment lessors. FSSAI packaging regulations are tightening food-contact safety protocols for dairy applications. Maharashtra dairy cooperatives adopt nitrogen-flush systems for paneer export conditioning.
Modified Atmosphere Packaging (MAP) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in film and gas supply. The vendor base stratifies across three tiers: industrial gas majors with captive CO2 sourcing, integrated film-and-equipment houses, and regional converters serving price-sensitive poultry accounts. Two strategic moves dominate: leasing intermediaries dismantling capital barriers for mid-scale processors, and mono-material barrier R&D investments locking in retail chain supply relationships.
Among integrated packaging houses, Sealed Air Corporation and Amcor PLC exemplify the film-equipment convergence archetype, anchoring positions through global resin networks and high-volume protein account contracts. Industrial gas majors including Linde AG occupy a distinct tier by controlling merchant nitrogen and carbon dioxide supply chains in European production zones. Berry Global Inc. represents the regional converter archetype, competing on throughput scale in price-sensitive segments while absorbing EU-mandated reformulation costs.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Amcor PLC |
| Linde AG |
| Berry Global Inc. |
| Air Products and Chemicals Inc. |
| Mondi Group |
| Praxair Inc. |
| Multivac Group |
| Multisorb Technologies Inc. |
| Others |
Supply & Pricing Matrix
Captive carbon dioxide sourcing in German and Dutch industrial gas clusters anchors margin capture at the equipment-and-gas tier, forcing downstream film converters and protein processors to absorb volatility through inventory buffers or contract renegotiation. Mono-material barrier R&D investments are reshaping procurement economics as EU recyclability deadlines approach.
Pricing Analysis
Configured-to-order pricing for precision gas-mixture systems commands substantial premiums over standardized nitrogen-flush configurations. Three-tier pricing structure across premium, standard, and economy levels separates integrated film-and-equipment contracts from component-only sales and bare equipment leases. Pricing pressure stems from mid-scale processor consolidation around leasing intermediaries that commoditize base hardware. Price-sensitive poultry accounts in Brazil and Mexico resist barrier film premiums, while German red meat processors accept configured-system pricing for color-retention guarantees.
Supply Chain Analysis
Upstream feedstock concentration for high-barrier resins centers on Saudi Arabia, South Korea, and Belgium for ethylene and propylene derivatives. Industrial gas supply draws from German, Dutch, and US Gulf Coast production zones for merchant nitrogen and carbon dioxide. Single-source vulnerability concentrates in EVOH barrier resin supply from Japanese and US specialty polymer houses. Distribution runs through converter-tied film distributors for lidding and base web materials, with direct equipment-vessel relationships for gas-distribution infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modified Atmosphere Packaging sits in early-cycle expansion as asset-light leasing dismantles capital barriers for mid-scale food processors across underpenetrated cold chain corridors. Subscription-based equipment models are accelerating deployment velocity beyond traditional capital-approval timelines.
For Market Incumbents: Harden integrated film-and-equipment contract structures against emerging regional converter consortia in India and Southeast Asia. Deepen captive gas supply positioning in European production zones to offset merchant CO2 volatility from fertilizer plant curtailments. Prioritize aftermarket calibration service density in Germany's Ruhr corridor where technician scarcity threatens processor margins.
For New Entrants and Emerging Players: Build out subscription-based leasing infrastructure targeting quick-commerce fulfillment centers in São Paulo, Mexico City, and Mumbai corridors. India's underpenetrated organized retail and dairy cooperative segments offer first-mover positioning for nitrogen-flush systems. Lead with ISO 22000 certification bundling to differentiate against legacy equipment vendors lacking documented gas-mixture protocols.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed equipment lessors in Latin American protein processing corridors. The five-to-ten year viability window favors platform integrators over component specialists as retail chains consolidate supplier relationships. Watch mono-material barrier film validation timelines at German and Nordic retail chains as inflection signals for converter M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Gas Supply | Linde AG and Air Products control CO2 sourcing in European production zones, locking processor relationships. |
| Mono-Material Barrier Film R&D Investment | Converters in the Ruhr corridor absorb reformulation costs to meet EU Packaging and Packaging Waste Regulation deadlines. |
| Subscription-Based Equipment Leasing | Quick-commerce fulfillment centers in São Paulo specify operating-expense models that bundle maintenance and gas supply. |
| Smart Sensor Array Deployment | German protein processors digitize real-time residual oxygen monitoring to compress deviation detection windows. |
| ISO 22000 Certification Convergence | Documented gas-mixture calibration protocols become de facto market access requirements for export-oriented processors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EU regulatory databases, and industrial gas trade publications. Conversations with equipment engineering directors at Multivac and Multisorb, protein procurement leads at German retail chains, barrier film technical directors at Amcor and Berry Global, and aftermarket service managers at Linde Gas anchor qualitative inputs. Bottom-up equipment deployment counts triangulate against top-down packaging material consumption estimates from resin producer disclosures.
Forecast inputs incorporate protein processing capacity expansion, cold chain infrastructure investment trajectories, and regulatory compliance deadline schedules. Segmentation models disaggregate by protein category spoilage sensitivity, barrier film material chemistry, application shelf-life specification, and end-user procurement scale. CAGRs derive from installed base growth rates, replacement cycle compression, and technology substitution elasticities across the projection horizon. Gas-mixture precision requirements and mono-material barrier adoption curves condition equipment and material demand respectively.
Practitioners should monitor EU Packaging and Packaging Waste Regulation enforcement timelines, fertilizer plant curtailment frequency affecting merchant CO2 supply, and quick-commerce fulfillment center buildout rates for early signals of forecast revision. Cross-checking against cold chain infrastructure investment disclosures from major protein exporters is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
Barrier Foil Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
High Performance Barrier Films Market
Packaging Barrier Films
Barrier Tube Packaging Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Global Adhesive Films Market
Packaging Barrier Films
Non Heat Sealable Film Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
North America Barrier Films Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
USA Stretch Hood Films Market
Packaging Barrier Films
Barrier Coated Papers Market
Packaging Barrier Films
Sealant Web Films Market
Packaging Barrier Films
Disposable Barrier Sleeves Market