
 Stretch Films Packs Market | 2026-2036
Stretch Films Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Stretch Films Packs Market Analytics
Buyer concentration among third-party logistics providers is recalibrating procurement volumes across the stretch films value chain. Berry Global, Inc. leverages integrated resin-to-film manufacturing to secure cost positions with national distribution networks. Manuli Stretch anchors European supply through specialized cast film lines serving automated warehouse systems. Sigma Plastics Group competes on regional density, operating multiple extrusion sites within single-day delivery radiuses of major Midwest distribution hubs.
Stretch Films Packs are multilayer polyolefin films engineered with cling additives and puncture-resistant coextrusion, typically ranging from 8 to 35 microns in gauge, designed to unitize palletized goods through mechanical tension retention. Machine stretch film dominates volume throughput in automated distribution centers where throughput economics favor pre-stretch ratios above 250 percent. Specialty stretch film captures margin concentration in temperature-sensitive pharmaceutical lanes requiring anti-fog and UV-stabilized formulations. Polyethylene formulations sustain material leadership while bio-based and recycled-content grades gain specification traction among sustainability-focused industrial packaging buyers.
The EPA oversees resin manufacturing emissions under Clean Air Act provisions, while FDA compliance governs food-contact adhesive layers in direct-wrap applications. OSHA ergonomic standards influence hand-film specifications in manual palletizing operations, driving pre-stretched formats that reduce worker strain during application. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and resin recycling infrastructure buildouts to anticipate specification shifts before they disrupt existing supply agreements.
Market Dynamics
Automated warehouse systems are compressing film specification cycles as third-party logistics providers consolidate procurement around pre-stretched machine formats that maximize pallet throughput per labor hour.
Growth Catalysts
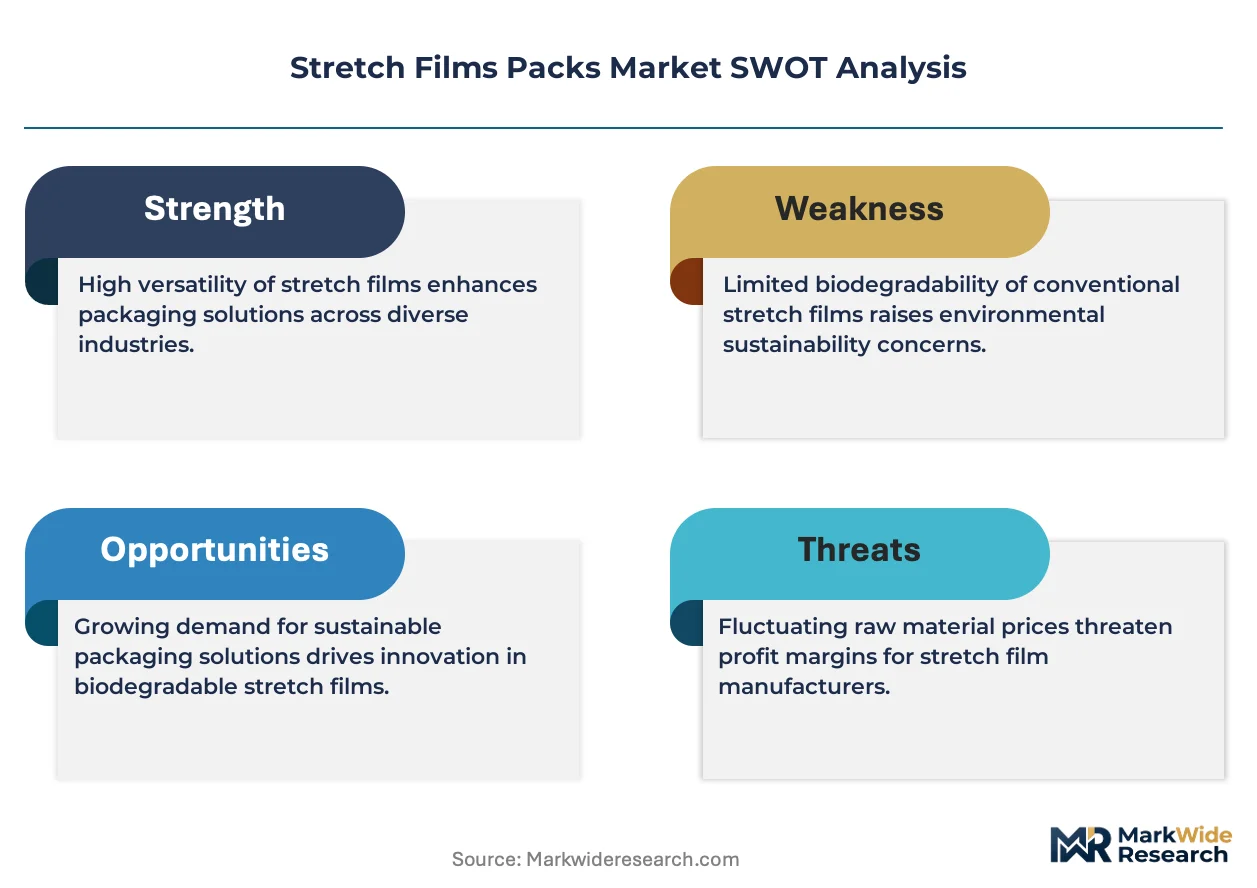
- EU Packaging and Packaging Waste Regulation:Mandatory recycled-content thresholds are pulling post-consumer resin into food-contact film formulations, expanding addressable supply pools for compliant converters.
- E-commerce fulfillment density:Parcel consolidation at Southeast Asian export hubs is multiplying palletization touchpoints, driving film consumption per shipped unit.
- Pre-stretch ratios above 250 percent:Mechanical tension optimization is reducing gauge requirements while maintaining load stability, lowering resin input per pallet wrapped.
Market Restraints
- Ethylene feedstock volatility:Crude-linked naphtha pricing transmits directly to polyethylene resin costs, compressing converter margins during upstream spikes.
- China GB standards compliance:Migration testing protocols for food-contact plastics extend certification timelines, freezing supplier switches until documentation clears.
- Paper-based pallet containment:Corner board and strapping systems capture specification share in rigid load categories where film elasticity offers marginal benefit.
Strategic Opportunities
- Indonesia manufacturing clusters:Export-oriented processing facilities in Java and Batam are scaling automated pallet lines faster than local film supply can match.
- Pharmaceutical cold chain lanes:Temperature-sensitive biologics distribution is creating specification demand for anti-fog and UV-stabilized specialty grades.
- Extended producer responsibility frameworks:State-level EPR buildouts in the US are incentivizing film-to-film recycling infrastructure that secures post-industrial resin streams.
Industry Challenges
- Extrusion technician scarcity:Cast film line operation requires specialized coextrusion die tuning expertise that regional labor pools struggle to replenish.
- Legacy warehouse management system integration:Automated stretch wrapper procurement demands API compatibility with existing inventory platforms, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stretch Films Packs Market |
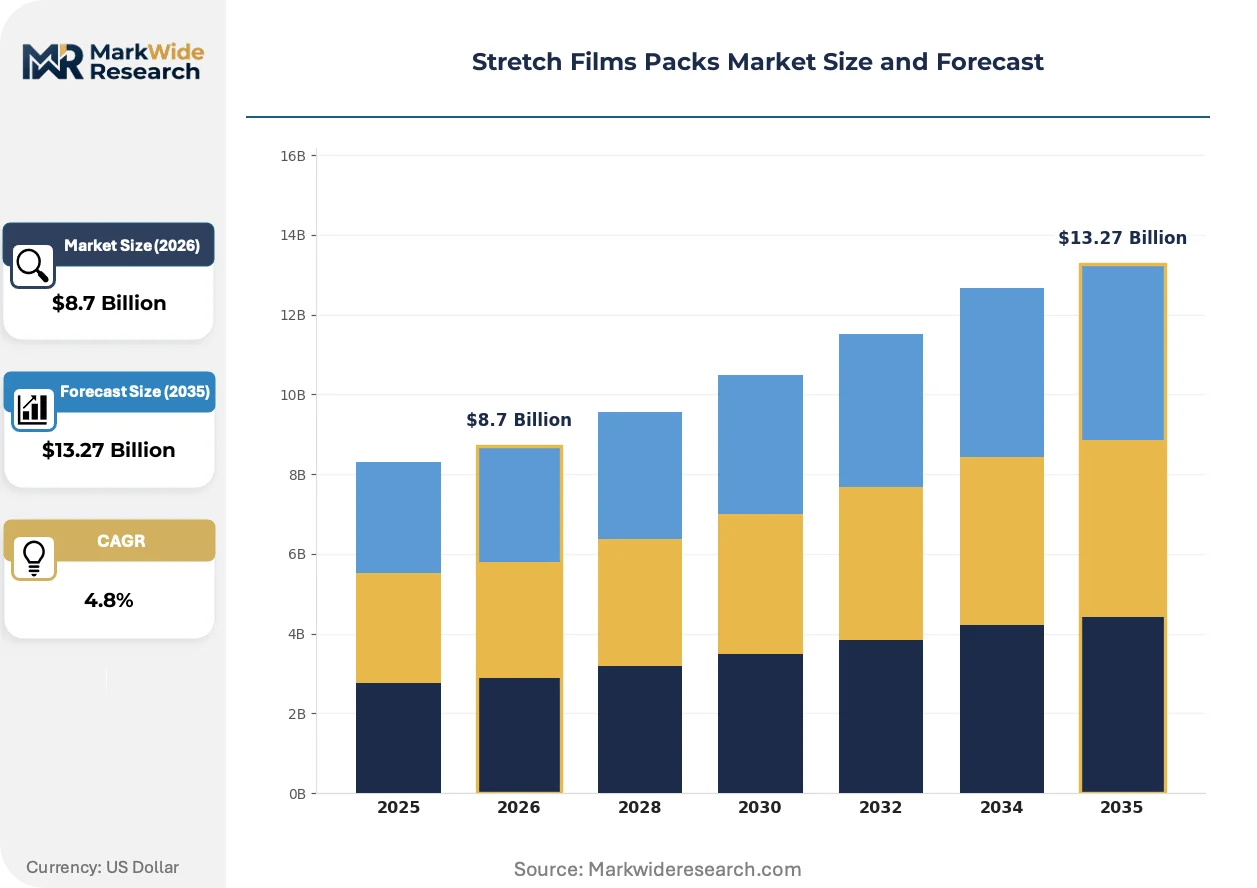
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Stretch Film, Machine Stretch Film, Pre-Stretched Film, Specialty Stretch Film Material: Polyethylene, PVC, Polypropylene, Others End User: Food Packaging, Industrial Packaging, Consumer Goods Packaging, Healthcare Packaging Distribution Channel: Direct Sales, Retail, E-Commerce, Wholesale |
| Companies Covered | Intertape Polymer Group, Manuli Stretch, Berry Global, Inc., Thong Guan Industries, Scientex, Sigma Plastics Group, Darnel, Inc., Paragon Films, Inteplast Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stretch Films Packs Market Evolving Landscape
Film engineering is pivoting from commodity gauge competition toward functional layering that addresses specific load hazards and regulatory compliance requirements.
Multilayer coextrusion with metallocene polyethylene is electrifying load containment performance in high-throughput distribution centers. Automated grocery fulfillment operators in Germany and the Netherlands are specifying these grades for irregular pallet profiles. The technology is compressing total applied cost per pallet by enabling downgauging without puncture failure.
REACH restrictions on persistent organic pollutants are tightening additive migration limits for cling agents in European food-contact applications. Film converters are reformulating tackifier packages to maintain cling performance under reduced dosage ceilings. Cold chain dairy distributors in France and Poland are accelerating qualification timelines for compliant alternatives.
Consolidated procurement by national third-party logistics networks is displacing fragmented regional film purchasing. Tier-one warehouse operators are mandating single-source supply agreements with technical service support. This concentration is most visible across Midwest US distribution corridors where pallet volumes justify dedicated extrusion capacity commitments.
Stretch Films Packs Market Segmentation
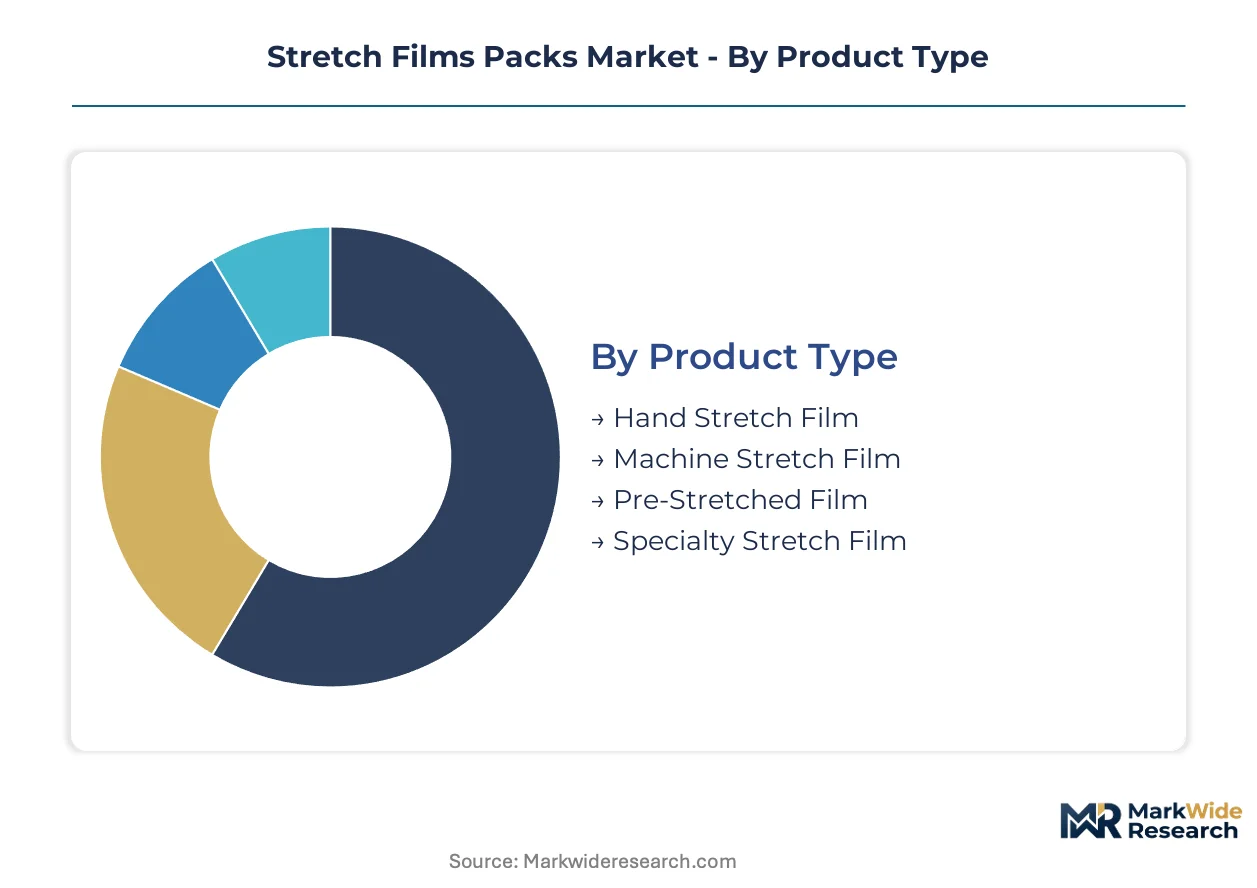
Stretch film procurement patterns diverge sharply between manual warehouse operations and automated distribution centers, with specification cycles compressing as buyers consolidate around formats that maximize throughput economics. Segmentation reveals how material choices, application requirements, and channel structures create distinct competitive arenas with divergent margin profiles and supplier qualification barriers.
Product Type:
Equipment replacement cycles and automation investments are redrawing the product mix as warehouse operators retire legacy stretch wrappers and consolidate procurement around pre-stretched formats.
- Machine Stretch Film:Cast or blown polyolefin formulations engineered for automated stretch wrappers operating at pre-stretch ratios exceeding 250 percent. Demand concentrates in German and Dutch grocery fulfillment centers where irregular pallet profiles require superior puncture resistance and cling retention under mechanical tension.
- Pre-Stretched Film:Factory-stretched rolls that reduce gauge requirements and worker strain during manual application. Adoption accelerates among US third-party logistics providers seeking OSHA ergonomic compliance while maintaining load stability across Midwest distribution corridors.
- Hand Stretch Film:Conventional blown film grades for manual palletizing operations in smaller facilities without wrapper automation. Specifications favor cling additives and easy unwind characteristics.
- Specialty Stretch Film:Functional grades incorporating UV stabilizers, anti-fog agents, or color coding for pharmaceutical and agricultural applications. Cold chain biologics distribution in France and Poland drives qualification timelines for compliant formulations.
Volume placements concentrate in Machine Stretch Film; the faster expansion belongs to Pre-Stretched Film.
Material:
Feedstock cost structures and regulatory compliance requirements are fragmenting material specifications across geographic markets with divergent recycling infrastructure maturity.
- Polyethylene:Linear low-density and metallocene grades dominate through superior puncture resistance, clarity, and cling compatibility. LLDPE sustains leadership in European automated warehouse systems where REACH additive restrictions demand reformulated tackifier packages.
- Polypropylene:Oriented and cast grades capture niche applications requiring higher stiffness and temperature resistance. Specification share expands in Southeast Asian export processing facilities where palletized goods face extended tropical storage conditions.
- PVC:Legacy formulations retain position in specific cling-intensive applications despite environmental scrutiny. Regulatory pressure from EU Packaging and Packaging Waste Regulation accelerates substitution timelines.
- Others:Bio-based polyethylenes and post-consumer recycled content grades emerging under extended producer responsibility frameworks. California and New York state-level EPR buildouts incentivize film-to-film recycling infrastructure development.
Polyethylene commands the installed base; bio-based and recycled-content grades are climbing the fastest.
End User:
Application-specific performance requirements and regulatory exposure create divergent specification barriers and supplier stickiness across end-use sectors.
- Food Packaging:Direct-contact and secondary wrap applications governed by FDA and EU food-contact migration limits. China's GB standards compliance extends certification timelines for adhesive layer formulations.
- Industrial Packaging:Heavy-duty unitization for construction materials, chemicals, and bulk goods. Puncture resistance and load retention prioritize over optical clarity.
- Consumer Goods Packaging:Retail-ready pallet containment with printed branding and color differentiation. E-commerce fulfillment density multiplies touchpoints at Southeast Asian export hubs.
- Healthcare Packaging:Sterility maintenance and temperature-sensitive distribution requirements. Anti-fog and UV-stabilized grades specified for pharmaceutical cold chain lanes.
Industrial Packaging absorbs the highest tonnage; Healthcare Packaging shows the steepest expansion trajectory.
Distribution Channel:
Procurement consolidation patterns and technical service requirements are reshaping channel economics as national accounts displace fragmented regional purchasing.
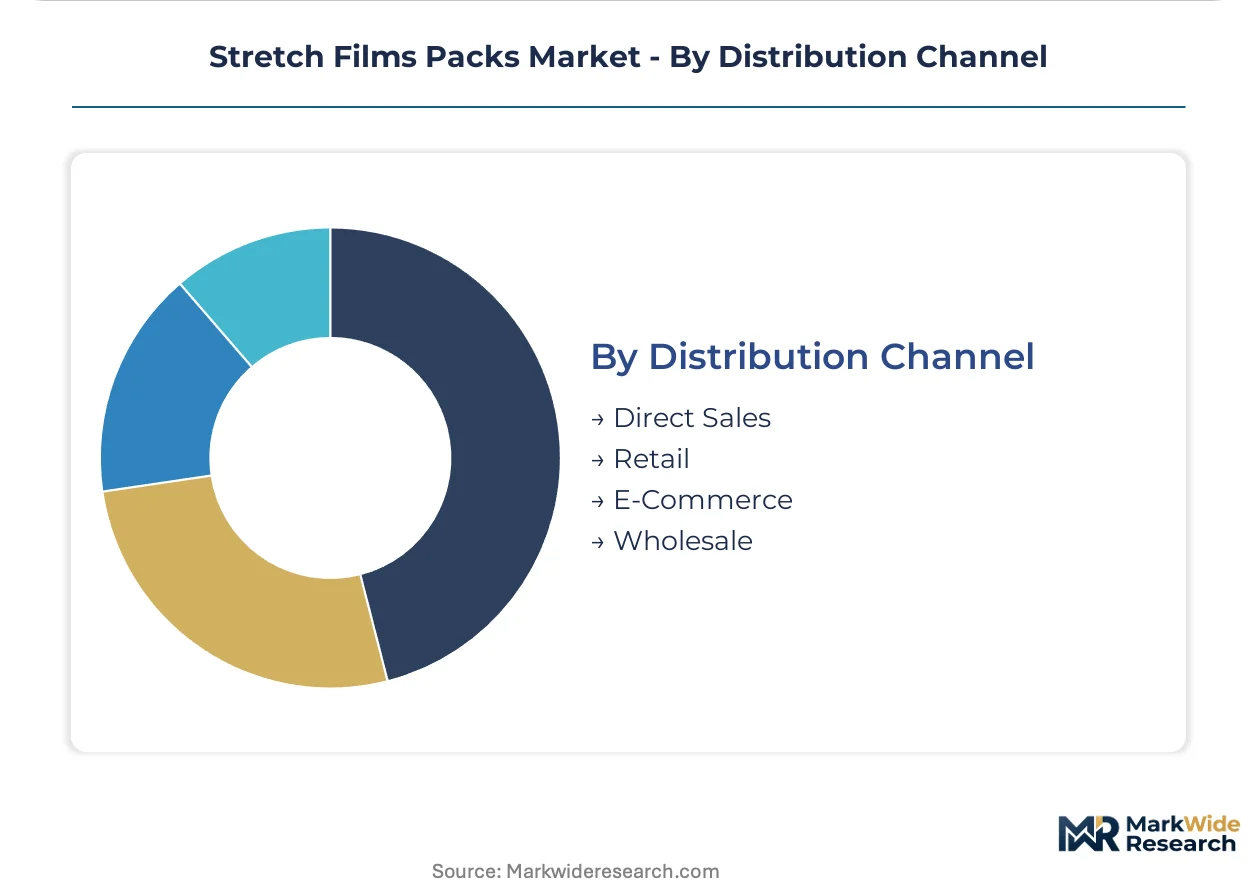
- Direct Sales:Converter-direct relationships with dedicated extrusion capacity commitments and technical support teams. Tier-one warehouse operators mandate single-source agreements with API-compatible inventory platform integration.
- Wholesale:Regional distributors maintaining single-day delivery radiuses around major Midwest US distribution hubs. Sigma Plastics Group competes through density of multiple extrusion sites.
- E-Commerce:Digital procurement platforms capturing smaller volume accounts with standardized specifications and transparent pricing.
- Retail:Big-box and hardware channels for hand-film and light industrial grades. Warehouse club chains expand film consumption through private label programs.
Direct Sales captures the largest contract values; E-Commerce is gaining share fastest among emerging accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Third-party logistics consolidation is redrawing procurement geography across major warehouse economies. Automated distribution center buildouts in specific national markets are concentrating film specification authority with fewer buyers commanding larger contract volumes.
United States
OSHA ergonomic standards are accelerating pre-stretched film adoption among Midwest distribution operators seeking manual palletizing compliance. The EPA oversees resin manufacturing emissions under Clean Air Act provisions affecting Texas and Louisiana petrochemical corridors. Chicago and Indianapolis warehouse clusters anchor automated stretch wrapper deployment for grocery and consumer goods fulfillment.
Germany
REACH restrictions on persistent organic pollutants are forcing tackifier reformulation in food-contact cling applications. The EU Packaging and Packaging Waste Regulation mandates recycled-content thresholds pulling post-consumer resin into film formulations. Automated grocery fulfillment operators in the Ruhr Valley and Bavaria specify metallocene polyethylene grades for irregular pallet profiles.
China
GB standards for food-contact plastics extend migration testing timelines, freezing supplier qualification cycles for adhesive layer formulations. The MIIT oversees industrial packaging material compliance through mandatory certification protocols. Export-oriented processing facilities in Shenzhen and Dongguan are scaling palletization operations faster than local film supply expansion.
Vietnam
E-commerce parcel consolidation at Ho Chi Minh City and Hai Phong export hubs is multiplying palletization touchpoints per shipped unit. The country's national standards body enforces food-contact plastic safety protocols aligned with import market requirements. Manufacturing clusters in Binh Duong and Dong Nai provinces are installing automated warehouse systems ahead of domestic film converter capacity.
Indonesia
Export processing facilities in Java and Batam are scaling automated pallet lines faster than local stretch film supply can match. The national industrial ministry regulates packaging material imports through technical barrier mechanisms. Jakarta and Surabaya distribution corridors concentrate demand from electronics and textile export operations requiring temperature-stable load containment.
Stretch Films Packs Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based and recycled-content specializations. The vendor base stratifies between integrated resin-to-film manufacturers, regional extrusion specialists, and niche functional grade developers. Three archetypes dominate: multinational converters with captive resin supply, mid-scale regional fabricators competing on delivery density, and specialty formulators serving pharmaceutical cold chain requirements. Competitive moves concentrate on backward integration into resin sourcing and capacity commitments tied to national account procurement consolidation.
Among North American integrated producers, Berry Global, Inc. and Sigma Plastics Group exemplify contrasting scale strategies. Manuli Stretch anchors European supply positioning for automated warehouse specifications. These three occupy distinct competitive terrain—multinational vertical integration, regional density fabrication, and specialized cast film engineering—without overlapping core customer segments.
| Leading Market Players |
|---|
| Intertape Polymer Group |
| Manuli Stretch |
| Berry Global, Inc. |
| Thong Guan Industries |
| Scientex |
| Sigma Plastics Group |
| Darnel, Inc. |
| Paragon Films |
| Inteplast Group |
| Others |
Value Network & Pricing Analysis
The EU Packaging and Packaging Waste Regulation gates qualified supply and premium-tier pricing access by mandating recycled-content thresholds that only integrated converters with film-to-film recycling infrastructure can satisfy. Buyers seeking compliant food-contact formulations face extended qualification timelines and contracted supply pools, compressing negotiating leverage against certified suppliers.
Pricing Analysis
Volume placements concentrate in standard polyethylene grades where resin cost pass-through dominates contract structures; margin capture belongs to specialty grades incorporating metallocene layers and anti-fog formulations. Pricing stratifies across premium, standard, and economy tiers based on certification grade and pre-stretch ratio performance. Cost compression in commodity blown film is intensifying because ethylene feedstock volatility transmits directly from naphtha pricing. Third-party logistics providers commanding national contract volumes exhibit lowest price sensitivity; small Midwest fabricators competing on single-day delivery radiuses face highest pressure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from automated grocery fulfillment operators in Germany and the Netherlands, while wholesale distribution serves regional density requirements around Chicago and Indianapolis clusters. Manufacturing concentrates in China, Vietnam, and Indonesia where export-oriented processing facilities scale palletization operations. Raw material dependencies center on linear low-density polyethylene resin, metallocene catalyst systems, and tackifier additive packages. Single-source vulnerability runs through specialized coextrusion die tuning expertise that regional labor pools struggle to replenish. Distribution runs through converter-direct relationships with technical service support for tier-one warehouse operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among national third-party logistics networks is forcing weaker regional converters out as single-source agreements displace fragmented purchasing patterns.
For Market Incumbents: Anchor backward integration into post-industrial resin streams to secure feedstock positions ahead of extended producer responsibility framework buildouts in California and New York. Defend market position by committing dedicated extrusion capacity to tier-one warehouse operators demanding API-compatible inventory platform integration, neutralizing emerging entrants lacking legacy system connectivity. For New Entrants and Emerging Players: Begin with bio-based polyethylene and recycled-content specializations where sustainability-focused industrial packaging buyers face specification gaps. Indonesia manufacturing clusters in Java and Batam present the most penetrable geography, with local film supply trailing automated pallet line expansion. Pursue qualification partnerships with cold chain dairy distributors in France and Poland accelerating timelines for REACH-compliant tackifier alternatives. For Investors and Strategic Acquirers: State-level EPR legislation passage is the leading indicator that film-to-film recycling infrastructure will command strategic premium valuations. Mid-scale regional fabricators with captive post-industrial resin streams and single-day delivery density around Midwest distribution hubs represent priority acquisition archetypes. Monitor extrusion technician training program expansion as signal of supply-side capability investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Recycling | Captive post-industrial streams secure compliance positions under California and New York EPR frameworks. |
| Capacity Commitment to National Accounts | Dedicated extrusion lines lock in tier-one warehouse operators mandating single-source supply agreements. |
| Specialty Grade Development | Anti-fog and UV-stabilized formulations capture margin concentration in pharmaceutical cold chain lanes. |
| Geographic Expansion to Indonesia | Local supply deficit against automated pallet line growth creates first-mover positioning in Java and Batam. |
| Technical Service Platform Integration | API-compatible inventory systems extend sales cycles but displace competitors lacking legacy connectivity. |
Research Methodology
Multi-period observation of pre-stretch ratio adoption rates, automated wrapper deployment timelines, and resin price volatility anchored the trend analysis, supplemented by interviews with plant managers at extrusion facilities, procurement leads at third-party logistics providers, technical R&D directors at film converters, and distribution channel partners. Secondary validation drew from customs and trade data, SEC 10-K filings of integrated packaging producers, industrial packaging association reports, and EU regulatory notification databases. Bottom-up volume modeling triangulated against top-down demand aggregation from end-use sector consumption patterns.
Input-output matrices mapped polyethylene resin feedstock costs through converter margin structures to end-user pricing across machine film, pre-stretched, hand film, and specialty grade segments. Segmentation dimensions modeled include product format, material composition, end-use application, and distribution channel structure. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Forecast inputs incorporated REACH additive restriction timelines, GB standards certification lag estimates, and OSHA ergonomic standard enforcement patterns.
Underlying measurement precision varies by segment; machine stretch film and polyethylene material categories carry tighter precision than emerging bio-based grades where supply volumes remain fragmented. Forecasts reflect assumptions regarding resin price transmission mechanisms, regulatory compliance timeline adherence, and automation investment continuity. Periodic stress-testing of base assumptions is recommended against ethylene feedstock volatility spikes and extrusion technician labor pool constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Poly Coated Kraft Paper Market
Poly film
Chocolate Wrapping Films Market
Poly film
Automotive Wrap Films Market
Poly film
North America Shrink and Stretch Film Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Canada Plastic Packaging Films Market
Poly film
North America BOPP Films Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
Packaging Film Market
Poly film
Bio-PET Film Market
Poly film
Embossed Film Market
Poly film
Latin America Plastic Packaging Films Market
Poly film
Nigeria Plastic Packaging Films Market
Poly film
Co Extruded Films Market
Poly film
Polylaminate Capsules Market
Poly film
Global Polycarbonate Sheets and Films Market