
 Barrier Films Market | 2026-2036
Barrier Films Market Size, Share, and Industry Trends Forecast 2026-2036
Barrier Films Market Intelligence
Food packaging is expanding as the dominant end-use vertical for barrier films, displacing slower-growing industrial wrapping segments. Amcor Limited leverages its global manufacturing footprint to supply multilayer coextruded films to protein and dairy processors across North America and Europe. Toray Industries anchors Asian supply through its biaxially oriented nylon and EVOH film production in Japan and China. Berry Global competes on scale in the North American retail channel, operating extrusion lines that serve private-label and branded food customers.
Barrier films are engineered polymer laminates, typically incorporating EVOH or polyamide interlayers between 5 and 50 microns thick, designed to restrict oxygen and moisture transmission below specified cm³/m²/day thresholds for sensitive contents. Their primary commercial purpose is shelf-life extension for perishables and protection of moisture-sensitive electronics and pharmaceutical actives. EVOH grades command premium positioning due to superior oxygen barrier performance in retort and modified-atmosphere applications, while polyethylene and polypropylene substrates dominate volume through cost-efficient monolayer and coextruded structures in standard food packaging. Biodegradable material variants represent the fastest-growing structural pocket, though recyclability mandates in European retail are accelerating migration toward mono-material multi-layer configurations that balance sortability with functional performance.
REACH registration requirements and the EU Green Deal packaging rules shape material selection and layer architecture decisions for European converters, while FDA food-contact notifications govern additive and adhesive approvals in the United States. Japan's METI circular economy guidelines and China's GB standards for packaging recyclability add compliance layers for exporters serving those markets. Stakeholders must monitor evolving extended-producer-responsibility frameworks and chemical-recycling infrastructure buildout to determine whether mechanical recycling compatibility or advanced recycling feedstock qualification offers the more durable competitive position.
Market Dynamics
Mono-material recyclability mandates under the EU Green Deal are forcing converters to dismantle legacy multilayer architectures and rebuild barrier performance within single-polymer chemistries, compressing R&D timelines and supplier qualification windows.
Growth Catalysts
- Retort-ready EVOH grades:Protein processors in Germany and France are specifying high-barrier coextrusions that withstand 121°C sterilization cycles, pulling material innovation toward oxygen transmission rates below 0.5 cm³/m²/day.
- REACH registration deadlines:ECHA's 2025-2027 substance evaluation waves are accelerating substitution of legacy adhesive systems with compliant water-based alternatives in flexible laminates.
- Fresh-produce supply chains:Modified-atmosphere packaging for berries and leafy greens is expanding cold-chain infrastructure investment across the Netherlands and Spain, driving demand for breathable high-barrier films.
Market Restraints
- Ethylene vinyl alcohol resin concentration:Asian petrochemical complexes control over 70% of global EVOH polymer supply, exposing European converters to freight cost volatility and currency hedging complexity.
- Mechanical recycling incompatibility:Legacy multilayer structures containing polyamide tie layers cannot be sorted in existing polyethylene/polypropylene waste streams, creating stranded asset risk for installed converting equipment.
- Polyolefin price volatility:Crude-linked feedstock costs for polyethylene and polypropylene substrates compress converter margins during energy price spikes without corresponding pass-through mechanisms in annual supply contracts.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:Temperature-sensitive biologics distribution in India and Brazil is creating demand for ultra-high-barrier pouches with integrated desiccant functionality and thermal insulation layers.
- Chemical recycling feedstock qualification:Advanced recycling infrastructure buildout in the Netherlands and Belgium offers converters a compliance pathway for technically non-recyclable barrier structures through pyrolysis-derived circular content certification.
- Digital printing convergence:Inkjet and electrophotographic systems are enabling short-run customized barrier packaging for regional craft food brands, collapsing minimum order quantities from 10-ton film rolls to sub-ton digital batches.
Industry Challenges
- Mono-material barrier engineering:Replacing EVOH or polyamide interlayers with compatible high-barrier polyethylene grades requires reformulation of entire coextrusion die configurations and downstream orientation parameters.
- Extended producer responsibility accounting:National packaging fee structures in Italy, France, and Germany impose divergent reporting requirements for multi-component flexible packaging, complicating pan-European product portfolio management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barrier Films Market |
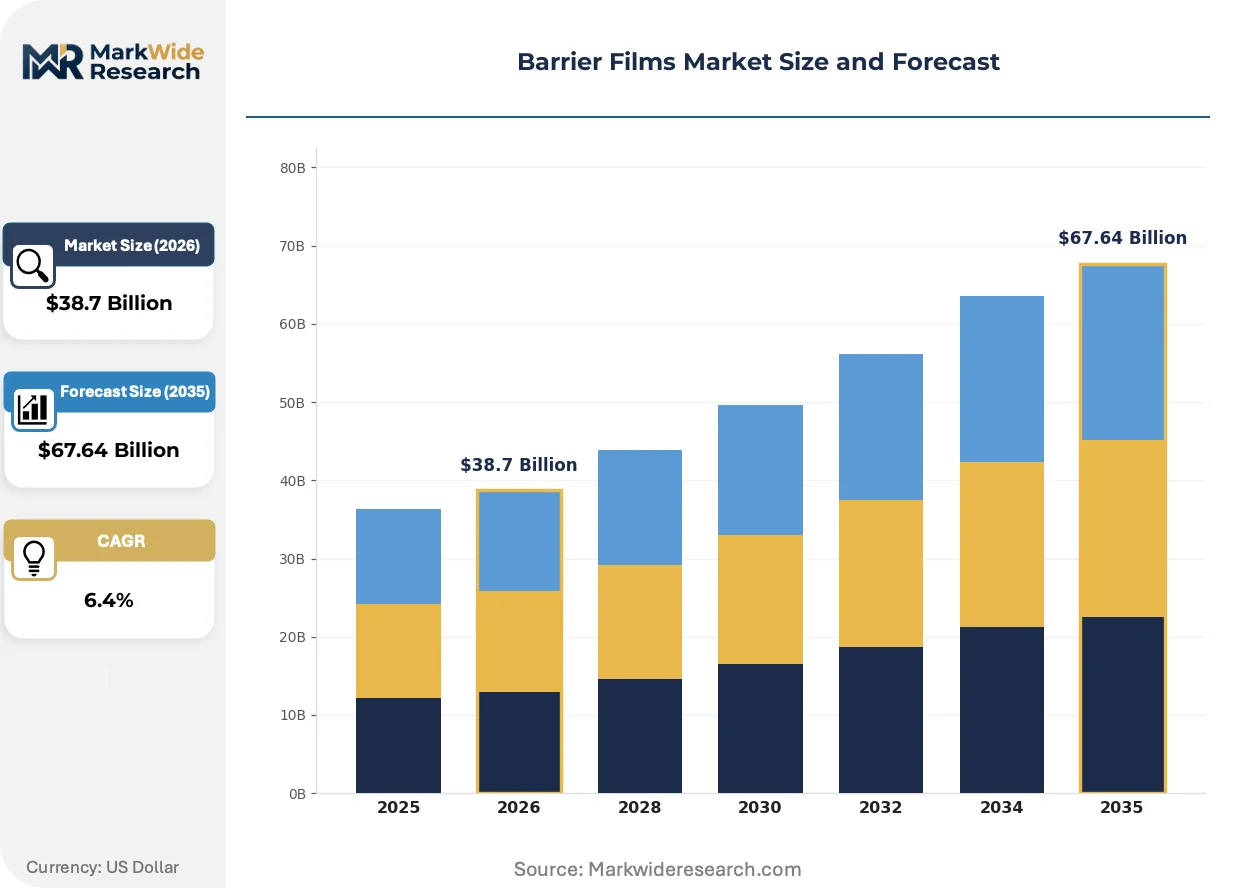
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Nylon, EVOH Application: Food Packaging, Pharmaceuticals, Electronics, Automotive End User: Manufacturers, Retailers, Distributors, Consumers Material: Biodegradable, Recyclable, Multi-Layer, PET |
| Companies Covered | Mondi Group, Toray Industries, Inc., Amcor Limited, Winpak Ltd., Uflex Limited, Sealed Air Corporation, Mitsubishi Chemical Corporation, Huhtamaki Oyj, Berry Global, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barrier Films Market Strategic Shifts & Innovations
Active and intelligent packaging functionalities are migrating from premium pharmaceutical applications into mainstream food protection, embedding sensors and indicators directly within barrier film substrates rather than applying them as secondary labels.
Machine-vision-guided extrusion control is automating thickness uniformity in multilayer coextrusion lines, reducing oxygen transmission rate variability from ±15% to ±3% in production runs. Dairy and meat processors in Germany are specifying these tightened tolerances for modified-atmosphere applications. The technology is automating quality assurance labor out of converting operations while enabling real-time barrier performance certification.
The EU Green Deal packaging and packaging waste regulation is mandating design-for-recycling criteria across all flexible packaging placed on the European market by 2030. Converters must demonstrate compatibility with mechanical recycling streams or qualify for chemical recycling feedstock pathways. High-barrier food pouches containing aluminum oxide coatings are most affected, driving substitution toward transparent silicon oxide barriers that pass near-infrared sorting systems.
Brand-owners are consolidating supplier relationships from 15-20 regional converters to 3-4 strategic partners capable of pan-European compliance documentation and mono-material technical support. This concentration is compressing quoting cycles and demanding integrated design services spanning substrate selection, barrier modeling, and recyclability certification. The shift is most visible in German and French retail private-label programs, where sustainability scorecards now determine 40-60% of sourcing decisions.
Barrier Films Market Segmentation
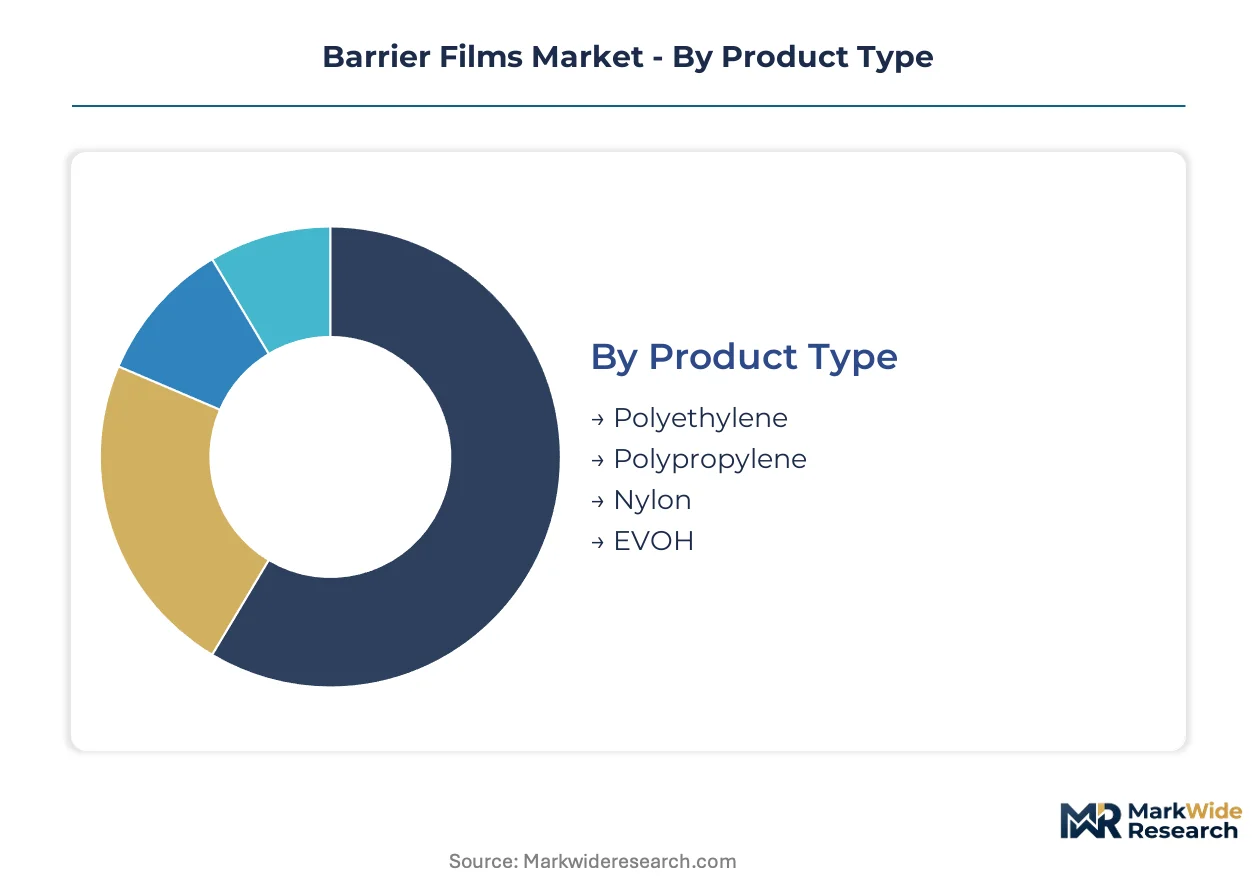
Barrier films segmentation reveals how material chemistry and end-use performance requirements dictate manufacturing complexity and margin structures. Product type and application dimensions dominate strategic planning for converters balancing functional specifications against recyclability mandates.
Product Type:
Standardization prevails in commodity polyolefins while EVOH and nylon grades demand customized coextrusion engineering for oxygen barrier thresholds.
- Polyethylene:Low-density and linear-low-density grades form the substrate foundation for cost-sensitive food pouches and industrial wraps. German retailers specify polyethylene-dominant mono-material structures to satisfy EU Green Deal sorting requirements, though oxygen barrier performance lags multilayer alternatives.
- Polypropylene:Biaxially oriented polypropylene delivers moisture resistance and optical clarity for snack and confectionery packaging. French dairy processors favor cast polypropylene coextrusions for thermoformed cheese trays requiring 30-day shelf-life extension.
- Nylon:Polyamide layers provide puncture resistance and moderate oxygen barrier in vacuum-packed meat applications.
- EVOH:Ethylene vinyl alcohol copolymers achieve sub-1 cm³/m²/day oxygen transmission rates for retort pouches and modified-atmosphere produce bags.
Leading the category by volume: Polyethylene. Expanding most quickly: EVOH grades specified for protein sterilization applications.
Application:
Volume concentrates in food protection while pharmaceutical and electronics segments command premium pricing for contamination control.
- Food Packaging:Modified-atmosphere and vacuum configurations dominate fresh-produce, meat, and ready-meal segments. Netherlands cold-chain infrastructure investments drive breathable high-barrier film specifications for berry exports to German retail networks.
- Pharmaceuticals:Blister packs and sachets for moisture-sensitive actives require WVTR below 0.1 g/m²/day. Indian biologics distributors specify ultra-high-barrier pouches with integrated desiccant layers for temperature-sensitive vaccine distribution.
- Electronics:Static-dissipative barrier films protect semiconductors and displays from moisture ingress during ocean freight.
- Automotive:Fuel vapor barrier films in tank and hose applications face substitution pressure from electrification trends.
Food packaging generates absolute volume. Pharmaceutical applications yield steepest margin expansion.
End User:
Procurement sophistication varies sharply across the value chain, with manufacturers demanding technical co-development and retailers enforcing sustainability scorecards.
- Manufacturers:Protein processors and pharmaceutical compounders specify oxygen transmission rates and seal integrity parameters in supply contracts. German meatpackers require 121°C retort compatibility with post-sterilization barrier retention.
- Retailers:Pan-European grocery chains mandate mono-material recyclability documentation and extended producer responsibility fee transparency. French and Italian private-label programs weight sustainability criteria at 40-60% of sourcing decisions.
- Distributors:Regional packaging wholesalers aggregate demand from small-format food producers with limited technical specification capabilities.
- Consumers:Direct purchasing concentrates in premium organic and specialty food segments with visible sustainability certifications.
Manufacturers drive technical innovation requirements. Retailers are accelerating compliance standardization across supplier bases.
Material:
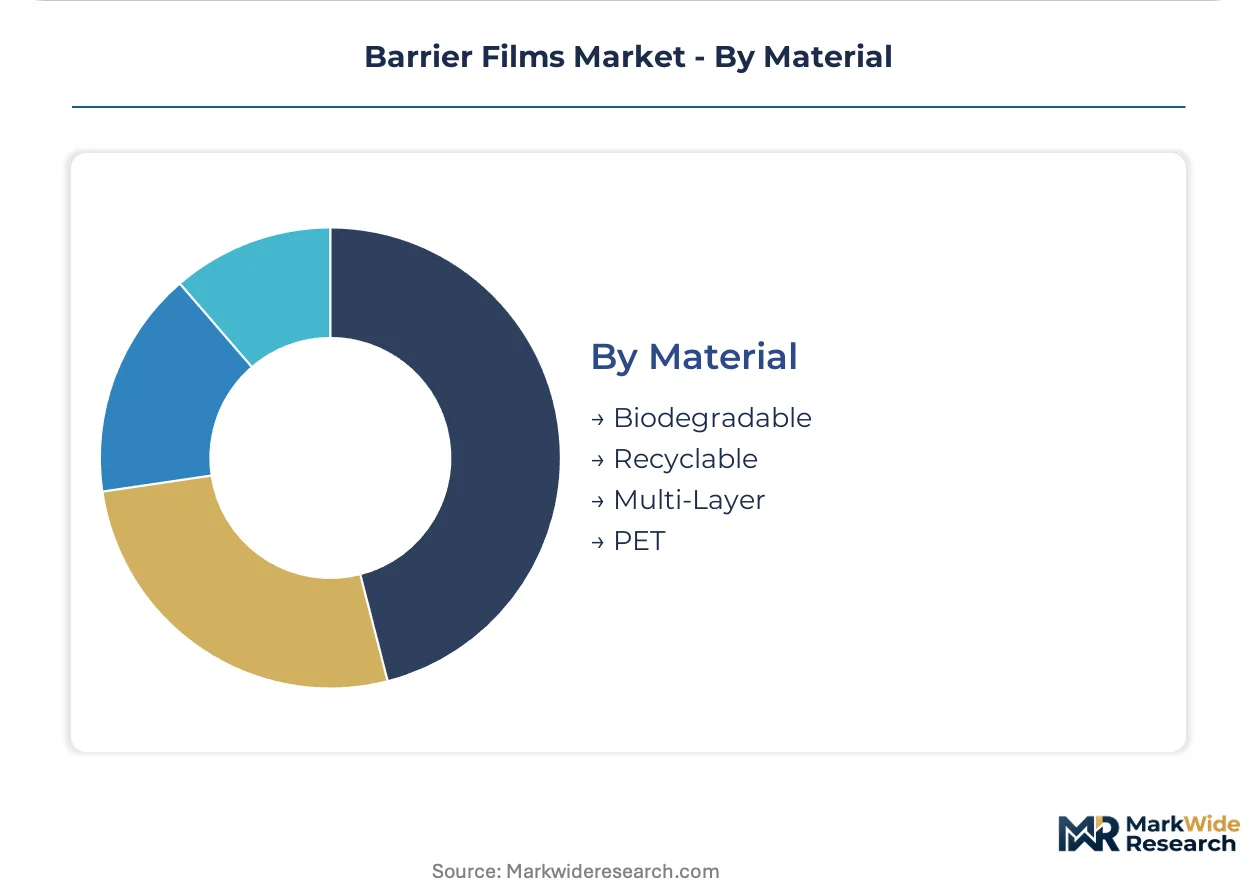
Regulatory pressure is fragmenting the landscape between mechanical-recycling-compatible mono-materials and certified biodegradable alternatives.
- Biodegradable:PLA and starch-based films degrade in industrial composting facilities. Netherlands retailers pilot these structures for fresh-produce bags despite moisture barrier limitations.
- Recyclable:Single-polymer polyethylene or polypropylene configurations satisfy EU Green Deal design-for-recycling criteria. Spanish converters invest in near-infrared sorting-compatible silicon oxide coatings to replace aluminum oxide barriers.
- Multi-Layer:Legacy EVOH-polyamide-polyethylene laminates face stranded asset risk as mechanical recycling incompatibility triggers extended producer responsibility penalties.
- PET:Biaxially oriented polyethylene terephthalate provides clarity and moderate barrier for cosmetic and pharmaceutical blister applications.
Recyclable mono-materials dominate new product development. Biodegradable variants gain share fastest in fresh-produce retail bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asian petrochemical complexes generate the majority of EVOH resin feedstock, while European converters dominate high-value film fabrication for regulated food and pharmaceutical applications. This production-consumption divide shapes freight cost exposure and currency hedging strategies across the value chain.
Germany
Retort-ready protein processors in Bavaria and Lower Saxony specify EVOH coextrusions with sub-0.5 cm³/m²/day oxygen transmission rates for sterilization cycles. REACH registration deadlines through ECHA accelerate adhesive system substitutions in flexible laminates. Mondi Group and Huhtamaki Oyj operate major converting facilities serving pan-European retail networks from industrial clusters near Hamburg and Cologne.
United States
FDA food-contact notifications govern additive approvals for multilayer dairy and meat packaging across the Midwest protein processing belt. Berry Global maintains extrusion capacity serving private-label retail channels. Chicago and Green Bay industrial corridors concentrate thermoforming and pouch fabrication equipment for national distribution networks.
China
GB standards for packaging recyclability and dual carbon goals reshape material selection for export-oriented converters in the Yangtze River Delta. Toray Industries anchors Asian EVOH and biaxially oriented nylon supply through production facilities in Japan and China. Shanghai and Jiangsu Province clusters supply barrier substrates to electronics manufacturers and domestic food brands.
India
Temperature-sensitive biologics distribution in Mumbai and Hyderabad drives specification of ultra-high-barrier pouches with integrated desiccant layers. CDSCO pharmaceutical regulations govern primary packaging material qualifications for vaccine cold chains. Uflex Limited represents domestic converting capacity serving regional pharmaceutical and food processing demand.
Netherlands
Modified-atmosphere packaging for berry exports to German retail networks drives breathable high-barrier film demand through Rotterdam cold-chain infrastructure. EU Green Deal design-for-recycling criteria accelerate chemical recycling feedstock qualification at advanced pyrolysis facilities near Antwerp. Wageningen food technology clusters pilot biodegradable PLA structures for fresh-produce retail bags.
Barrier Films Market Key Industry Players
Top-tier vendors anchor premium EVOH and multilayer coextrusion capacity, while mid-tier converters compete on mono-material recyclability compliance and regional logistics efficiency. The vendor base stratifies across integrated resin-to-film producers, specialized flexible packaging converters, and diversified materials conglomerates with packaging divisions. Strategic archetypes include petrochemical-integrated film manufacturers, brand-owner-aligned co-development partners, and sustainability-certified niche suppliers. Dominant competitive moves encompass chemical recycling infrastructure partnerships and mono-material barrier R&D alliances with polymer suppliers.
Among diversified packaging conglomerates, Amcor Limited and Berry Global occupy positions spanning global manufacturing footprints and private-label retail channel scale. Sealed Air Corporation represents the protective packaging archetype with vacuum and modified-atmosphere system integration. Japanese industrial groups Toray Industries and Mitsubishi Chemical Corporation anchor high-performance resin and film production for Asian electronics and pharmaceutical supply chains. Mondi Group and Huhtamaki Oyj exemplify European converters navigating EU Green Deal compliance through mono-material technical development and extended producer responsibility fee transparency.
| Leading Market Players |
|---|
| Mondi Group |
| Toray Industries, Inc. |
| Amcor Limited |
| Winpak Ltd. |
| Uflex Limited |
| Sealed Air Corporation |
| Mitsubishi Chemical Corporation |
| Huhtamaki Oyj |
| Berry Global, Inc. |
| Others |
Cost & Logistics Intelligence
EU Green Deal packaging and packaging waste regulation gates qualified supply and premium-tier pricing access for converters, mandating design-for-recycling documentation that separates compliant mono-material structures from legacy multilayer alternatives facing extended producer responsibility penalties.
Pricing Analysis
Cost-down pressure on EVOH-containing laminates accelerates because Asian petrochemical complexes control over 70% of global resin supply, exposing European converters to freight cost volatility and currency hedging complexity. Contract-based long-term offtake agreements dominate procurement between protein processors and film suppliers, with pricing stratifies across premium, standard, and economy tiers based on oxygen transmission rate performance and REACH registration status. German retailers exhibit highest price sensitivity for commodity polyethylene mono-materials, while pharmaceutical cold-chain distributors absorb premium pricing for ultra-high-barrier pouches with integrated desiccant functionality.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for pan-European retail network fulfillment. Manufacturing concentrates in Germany, China, and Japan, with Toray Industries anchoring Asian EVOH and biaxially oriented nylon supply while Mondi Group and Huhtamaki Oyj operate major converting facilities near Hamburg and Cologne. Raw material dependencies center on ethylene vinyl alcohol copolymers, polyamide tie layers, and polyethylene substrates. Single-source vulnerability from Asian petrochemical complex concentration creates freight cost volatility exposure. Distribution runs through cold-chain infrastructure investments across the Netherlands and Spain for modified-atmosphere produce applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration deadlines through ECHA create a barrier-to-entry moat for compliant players, elevating cost-of-compliance as the defining competitive axis for converters and resin suppliers across the European market.
For Market Incumbents: Deploy chemical recycling feedstock qualification partnerships at advanced pyrolysis facilities near Antwerp to secure compliance pathways for technically non-recyclable barrier structures. Deepen backward integration into captive EVOH resin supply through offtake agreements with Japanese and Chinese petrochemical complexes, insulating margin position from freight cost volatility and currency hedging complexity that threatens converter profitability. For New Entrants and Emerging Players: The mid-tier pricing gap between premium EVOH coextrusions and commodity polyethylene mono-materials creates entry space for silicon oxide barrier coatings compatible with near-infrared sorting systems. Target Spanish and Italian converters transitioning from aluminum oxide barriers to transparent alternatives satisfying EU Green Deal criteria. Lead with digital printing convergence capabilities enabling short-run customized batches for regional craft food brands, collapsing minimum order quantities from traditional 10-ton film rolls to sub-ton digital production. For Investors and Strategic Acquirers: Chemical recycling infrastructure buildout in the Netherlands and Belgium is the leading indicator that circular content certification will determine durable competitive positioning for European converters. Five-to-ten year viability favors petrochemical-integrated film manufacturers with demonstrated mono-material barrier R&D alliances and extended producer responsibility fee transparency capabilities. Monitor ECHA substance evaluation waves as the inflection signal for adhesive system substitution momentum accelerating toward water-based compliant alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier R&D Alliance | Polymer suppliers and converters co-develop high-barrier polyethylene grades replacing EVOH interlayers for EU Green Deal compliance. |
| Chemical Recycling Feedstock Qualification | Converters secure circular content certification through pyrolysis-derived pathways at advanced facilities near Antwerp. |
| Digital Printing Convergence Investment | Inkjet and electrophotographic systems enable sub-ton batch production for regional craft food brands. |
| REACH-Compliant Adhesive Substitution | Water-based alternatives replace legacy solvent systems ahead of ECHA substance evaluation deadlines. |
| Cold-Chain Infrastructure Partnership | Converters align with Rotterdam and Netherlands logistics hubs for modified-atmosphere produce distribution. |
Research Approach
Document review covered trade association filings, customs and import-export databases, and SEC regulatory disclosures, complemented by interviews with plant managers at converting facilities, procurement leads at protein processing and dairy OEMs, distribution channel partners serving pan-European retail networks, and technical R&D directors at polymer suppliers. Secondary validation drew from Cefic chemical industry reports, ECHA substance registration databases, and EU packaging waste regulation documentation. Bottom-up volume modeling triangulated against top-down value chain analysis across the forecast period.
Historical capacity utilization and pricing panel input cross-referenced against forward-looking investment announcements to anchor projection assumptions. Segmentation dimensions modeled include material chemistry tier, end-use application, packaging format configuration, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating substitution dynamics between multilayer and mono-material structures. Industry-specific forecast inputs encompassed EVOH resin supply announcements and chemical recycling infrastructure development timelines.
Inputs from ECHA registration databases and converter capacity announcements were available through the study window; gaps in real-time pricing transparency for confidential long-term supply contracts introduce uncertainty bands around margin compression estimates. Forecasts reflect documented assumptions regarding regulatory implementation timelines and resin supply concentration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Oil Resistant Packaging Market
Packaging Barrier Films
Tray Liners Market
Packaging Barrier Films
Sealant Web Films Market
Packaging Barrier Films
PET Release Liner Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Barrier Materials Market
Packaging Barrier Films
Decorative Films and Foils Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Barrier Coated Carton Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Barrier Coatings for Packaging Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Specialty Films Market
Packaging Barrier Films
North America Protective Films Market