
 Cryogenic Insulation Films Market | 2026-2036
Cryogenic Insulation Films Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Insulation Films Market Outlook
Buyer concentration in the energy sector is decoupling from traditional aerospace procurement patterns as LNG terminal operators and hydrogen liquefaction projects fragment demand across new industrial customers. Aspen Aerogels leverages its aerogel technology leadership to anchor premium positions in space-constrained installations. Mitsubishi Chemical Corporation sustains supply relationships across Asian industrial gas networks through specialized polyethylene film grades. Saint-Gobain competes on manufacturing scale, operating integrated production lines that control cost structures for medium-thickness specifications.
Cryogenic insulation films are multilayer polymer laminates engineered to maintain thermal barrier performance at temperatures below minus 150 degrees Celsius, typically incorporating metallized substrates and low-conductivity adhesives to minimize heat ingress into liquefied gas containment systems. Composite films command margin concentration due to their tailored layering sequences for extreme-duty cycles in hydrogen and helium applications, while polyester variants lead volume throughput across standard LNG insulation tasks. Thin-film segments dominate aerospace weight-critical applications, though ultra-thick configurations are expanding fastest in offshore energy infrastructure where mechanical durability requirements override space constraints.
The EPA enforces emissions thresholds for LNG facility equipment under the Clean Air Act, compelling operators to specify higher-performance insulation barriers that reduce boil-off gas release. ECHA's REACH framework governs chemical composition disclosures for adhesive and substrate materials, shaping formulation choices for suppliers seeking European market access. ISO 23953 standards for cryogenic vessel insulation provide baseline thermal performance benchmarks that differentiate qualified suppliers from marginal entrants. Stakeholders must monitor evolving hydrogen liquefaction scale-up timelines and corresponding shifts in thickness specifications before committing to dedicated production capacity.
Market Dynamics
The EU F-Gas Regulation is tightening permissible leakage rates for cold-chain equipment, compelling material upgrades across LNG infrastructure and hydrogen liquefaction projects. This regulatory pressure is fragmenting demand patterns as energy sector procurement decouples from traditional aerospace sourcing.
Growth Catalysts
- Hydrogen liquefaction scale-up:Industrial gas majors in Germany are anchoring regional sourcing for European hydrogen projects, creating concentrated demand for ultra-thick film configurations.
- REACH framework compliance:ECHA's chemical disclosure requirements for adhesive and substrate materials are qualifying premium suppliers and marginalizing marginal entrants.
- Offshore energy infrastructure expansion:Mechanical durability requirements in marine LNG containment are accelerating procurement of composite multilayer systems over standard polyester variants.
Market Restraints
- Metallized substrate supply concentration:Specialized aluminum deposition capacity clusters among integrated chemical conglomerates, exposing buyers to input bottlenecks.
- Low-conductivity adhesive cost volatility:Fluoropolymer resin prices fluctuate with semiconductor industry demand cycles, compressing margins for film laminators.
- ISO 23953 certification timelines:Thermal performance benchmarking protocols extend qualification periods, delaying new supplier market entry.
Strategic Opportunities
- India hydrogen hub development:The country's PLI scheme for clean hydrogen production is creating virgin demand for cryogenic containment materials without incumbent supplier relationships.
- Aerospace weight reduction mandates:Thin-film segments are capturing design wins in next-generation launch vehicle insulation as satellite constellation deployment accelerates.
- Digital procurement platforms:Industrial gas distributors are unbundling specification-grade film sourcing from legacy bundled service contracts.
Industry Challenges
- Cryogenic materials engineering talent scarcity:Specialized polymer chemists with minus-150-degrees-Celsius formulation experience command premium compensation, constraining R&D scaling.
- Legacy vessel retrofit complexity:Integrating advanced multilayer films into existing LNG storage infrastructure requires custom engineering without standardized mounting protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Insulation Films Market |
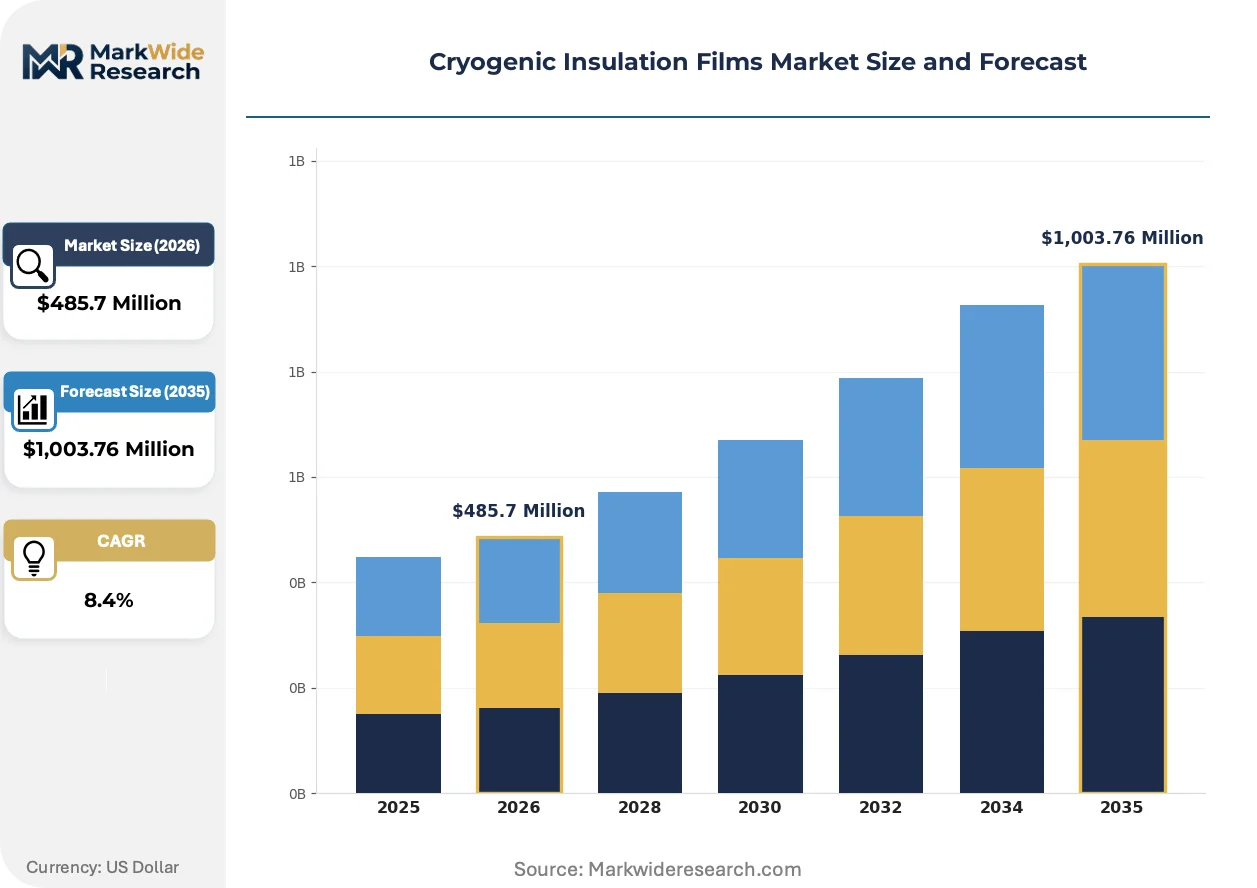
| Market Size in 2026 | $485.7 Million |
| Market Size in 2035 | $1,003.76 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Polyethylene, Polypropylene, Polyester, Composite End Use Industry: Aerospace, Energy, Chemical Processing, Food & Beverage Thickness: Thin, Medium, Thick, Ultra-Thick Application: Insulation, Packaging, Vibration Dampening, Soundproofing |
| Companies Covered | Aspen Aerogels, Mitsubishi Chemical Corporation, Saint-Gobain, Polyplex, DuPont de Nemours Inc, CryoWorks, Dunmore Corporation, Linde plc, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Insulation Films Market Strategic Shifts
Aerogel-infused film architectures are overtaking conventional multilayer laminates in space-constrained installations. Material science advances and regulatory leakage thresholds are jointly reshaping competitive positioning across the value chain.
Composite films incorporating silica aerogel interlayers are overtaking standard metallized polyester stacks in hydrogen and helium applications. LNG terminal operators facing boil-off gas penalties are specifying these configurations despite 40% thickness premiums. The technology is overtaking incumbent solutions by enabling thermal barrier performance in confined vessel geometries previously inaccessible to bulk insulation.
The EPA's Clean Air Act enforcement for LNG facility emissions is compelling operators to specify higher-performance insulation barriers. Boil-off gas release thresholds now function as de facto procurement mandates for terminal expansion projects. Gulf Coast operators are responding by pre-qualifying suppliers against thermal conductivity benchmarks exceeding ISO 23953 baselines.
Buyer concentration in energy infrastructure is fragmenting procurement authority across project finance consortia rather than centralized corporate engineering departments. Specification decisions now migrate to EPC contractors with incentive structures favoring first-cost minimization over lifecycle thermal performance. This pattern is most visible in German hydrogen liquefaction projects where industrial gas majors delegate material selection to construction-phase procurement teams.
Cryogenic Insulation Films Market Segmentation
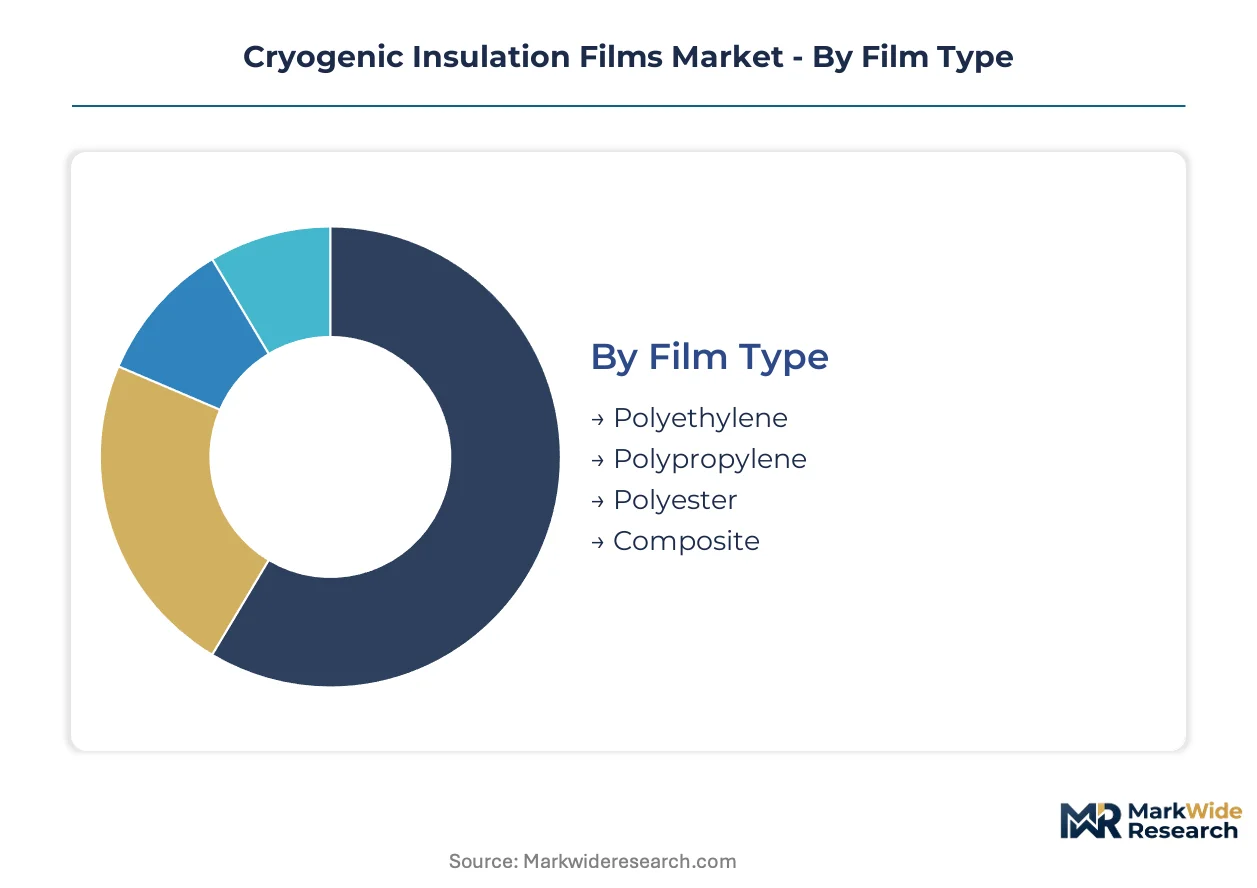
Cryogenic insulation films fragment across multiple technical dimensions that dictate procurement patterns. Film composition and thickness specifications determine qualification pathways for LNG infrastructure versus aerospace applications. End-use concentration in energy infrastructure is reshaping volume distribution across traditional segment boundaries.
Film Type:
Specialized resin supply concentrates among integrated chemical conglomerates with captive polymerization capacity.
- Polyethylene:Low-density formulations dominate standard LNG containment tasks with cost-optimized thermal conductivity profiles. Procurement from German industrial gas networks anchors European volume for hydrogen liquefaction pre-qualification.
- Composite:Tailored layering sequences incorporating metallized substrates and aerogel interlayers deliver extreme-duty performance below minus 150 degrees Celsius. Hydrogen and helium applications in space-constrained geometries command specification premiums despite manufacturing complexity.
- Polypropylene:Biaxially oriented grades offer moisture resistance for marine LNG containment environments.
- Polyester:Metallized variants serve baseline aerospace weight-critical applications with established qualification protocols.
Composite absorbs the bulk of installed capacity in premium hydrogen infrastructure; polyethylene is expanding most quickly across standardized LNG terminal expansions.
End Use Industry:
Application requirements diverge sharply between lifecycle thermal performance mandates and first-cost procurement incentives.
- Energy:LNG terminal operators and hydrogen liquefaction projects specify multilayer systems under boil-off gas penalty structures. Gulf Coast infrastructure expansion and German hydrogen hub development concentrate procurement authority with EPC contractors rather than centralized engineering departments.
- Aerospace:Satellite constellation deployment and next-generation launch vehicles drive thin-film specification for weight-critical insulation. ISO 23953 thermal performance benchmarks differentiate qualified suppliers from marginal entrants in this qualification-intensive segment.
- Chemical Processing:Industrial gas containment for helium and specialty gases requires customized thickness configurations.
- Food & Beverage:Cold-chain equipment faces tightening EU F-Gas Regulation leakage thresholds compelling material upgrades.
Energy absorbs the bulk of installed capacity; aerospace represents the fastest-growing trajectory as launch cadence accelerates.
Thickness:
Mechanical durability requirements in offshore environments are displacing space-constrained specifications.
- Ultra-Thick:Configurations exceeding standard multilayer stacks address mechanical durability requirements in offshore energy infrastructure where space constraints yield to structural loading. Marine LNG containment procurement is accelerating adoption despite installation complexity.
- Thin:Aerospace weight reduction mandates capture design wins in next-generation launch vehicle insulation. Satellite constellation deployment timelines concentrate demand with specialized laminators possessing precision deposition equipment.
- Medium:Standard LNG terminal specifications balance thermal performance with handling practicality.
- Thick:Chemical processing applications for industrial gas containment utilize intermediate configurations.
Medium thickness absorbs the bulk of installed capacity; ultra-thick is expanding most quickly in offshore marine applications.
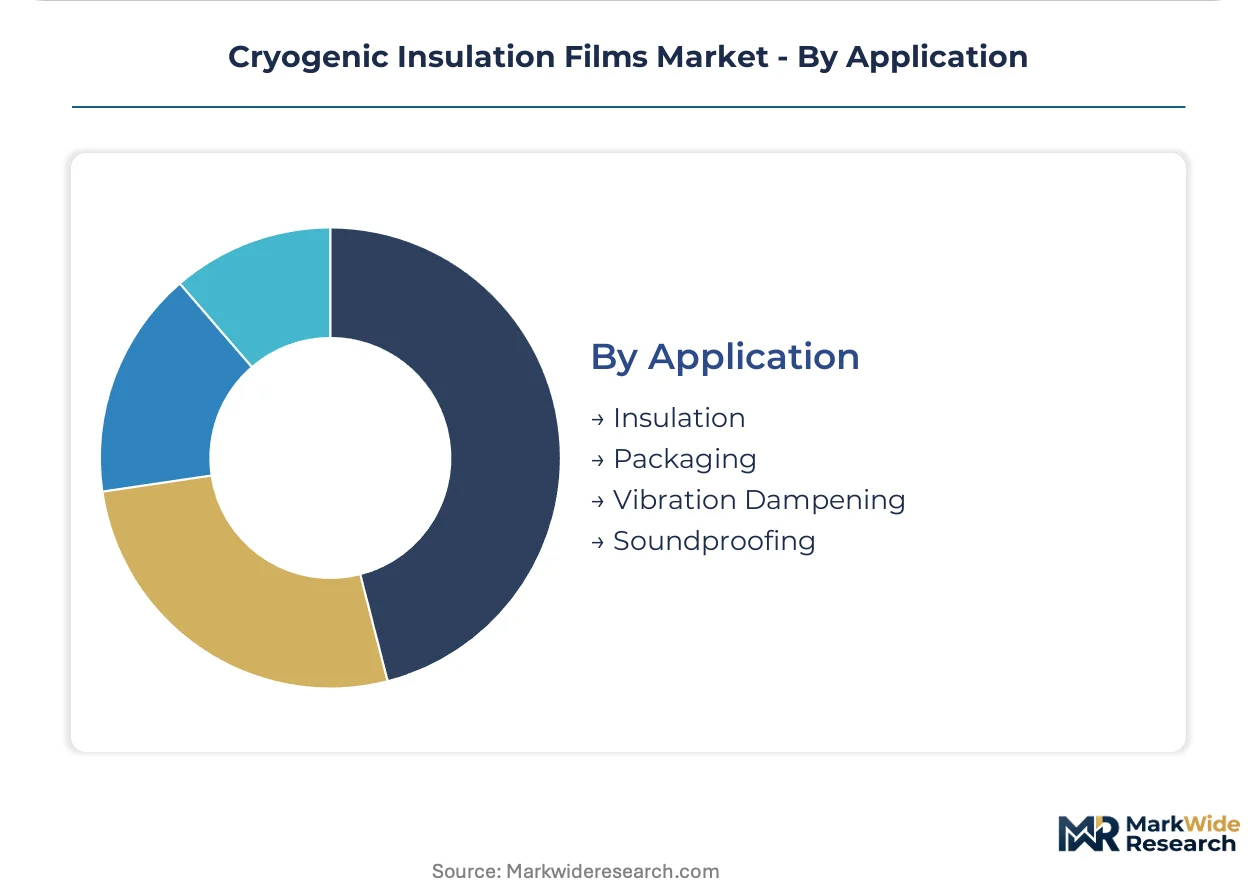
Application:
Functional performance requirements segment procurement between thermal barrier specifications and secondary mechanical properties.
- Insulation:Primary thermal barrier systems for liquefied gas containment incorporate metallized substrates and low-conductivity adhesives to minimize heat ingress. EPA Clean Air Act enforcement for LNG facility emissions compels specification of higher-performance configurations exceeding baseline ISO 23953 benchmarks.
- Packaging:Cold-chain logistics applications face tightening leakage thresholds under EU F-Gas Regulation compliance timelines.
- Vibration Dampening:Marine transport applications address structural dynamics in LNG carrier cargo containment.
- Soundproofing:Secondary acoustic management functions in aerospace and industrial installations.
Insulation absorbs the bulk of installed capacity; packaging is expanding most quickly as cold-chain infrastructure upgrades accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial gas majors in Germany are anchoring concentrated procurement for European hydrogen liquefaction projects, fragmenting demand patterns across new energy infrastructure customers. LNG terminal operators on the US Gulf Coast are expanding multilayer insulation procurement as liquefaction capacity scales. Regulatory leakage thresholds under the EU F-Gas Regulation are compelling material upgrades across cold-chain equipment networks.
United States
Gulf Coast LNG terminal expansion and hydrogen hub development are driving specification-grade film procurement. EPA Clean Air Act enforcement for LNG facility emissions compels operators to pre-qualify suppliers against thermal conductivity benchmarks exceeding ISO 23953 baselines. Houston-area EPC contractors are fragmenting procurement authority across project finance consortia.
Germany
Industrial gas majors anchor regional sourcing for European hydrogen liquefaction projects, creating concentrated demand for ultra-thick film configurations. ECHA's REACH framework governs chemical composition disclosures for adhesive and substrate materials, shaping formulation choices for suppliers seeking market access. The Ruhr industrial cluster hosts engineering teams specifying multilayer systems for hydrogen infrastructure.
China
Dual carbon goals and LNG import infrastructure expansion are accelerating procurement of composite insulation systems. The Ministry of Ecology and Environment enforces emissions thresholds for liquefaction facility equipment. Yangtze River Delta manufacturing clusters are developing domestic metallized substrate deposition capacity to reduce import dependency.
Japan
METI's hydrogen roadmap and satellite constellation deployment timelines are bifurcating demand between energy infrastructure and aerospace applications. JIS standards for cryogenic vessel insulation provide baseline thermal performance benchmarks. Osaka-based industrial gas networks are sourcing specialized polyethylene film grades for helium containment systems.
India
The PLI scheme for clean hydrogen production is creating virgin demand for cryogenic containment materials without incumbent supplier relationships. BIS standards for industrial gas equipment are evolving to address hydrogen liquefaction scale-up. Gujarat industrial corridors are attracting preliminary supplier qualification activity for hydrogen hub development.
Cryogenic Insulation Films Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue aerogel-infused architectures and digital procurement platform integration. The vendor base stratifies across integrated chemical conglomerates with captive polymerization capacity, specialized laminators with precision deposition equipment, and materials science firms with extreme-temperature formulation expertise. Three archetypes dominate: scale-driven manufacturers controlling cost structures, technology leaders commanding premium positions in space-constrained installations, and regional fabricators serving industrial gas network relationships. Competitive moves concentrate on strategic partnerships with EPC contractors and capacity expansion for metallized substrate deposition.
Within the technology-leader archetype, Aspen Aerogels exemplifies premium positioning through aerogel technology leadership in extreme-duty applications. Among integrated chemical conglomerates, Mitsubishi Chemical Corporation and Saint-Gobain occupy positions spanning specialized film grades and manufacturing scale respectively. DuPont de Nemours Inc represents the diversified materials science tier with polymer formulation capabilities extending into cryogenic performance specifications.
| Leading Market Players |
|---|
| Aspen Aerogels |
| Mitsubishi Chemical Corporation |
| Saint-Gobain |
| Polyplex |
| DuPont de Nemours Inc |
| CryoWorks |
| Dunmore Corporation |
| Linde plc |
| BASF |
| Others |
Value Chain & Pricing Dynamics
LNG terminal operators and hydrogen liquefaction project consortia concentrate procurement authority, anchoring contract-based long-term offtake pricing with EPC contractors incentivized toward first-cost minimization. This buyer concentration fragments pricing power across project finance structures rather than centralized corporate engineering departments.
Pricing Analysis
Volume throughput concentrates in standard polyethylene film grades for LNG infrastructure, while margin capture clusters in composite multilayer configurations for hydrogen and helium applications. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade against ISO 23953 baselines and thermal conductivity performance thresholds. Cost compression in standard polyester variants intensifies because fluoropolymer resin prices fluctuate with semiconductor industry demand cycles. EPC contractors with project-financed procurement mandates exhibit highest price sensitivity; aerospace qualification-intensive segments demonstrate lowest sensitivity due to performance-critical specifications.
Supply Chain Analysis
Metallized substrate supply rests on integrated chemical conglomerates with captive aluminum deposition capacity clustering in Germany, Japan, and the United States. Raw material dependencies center on specialized fluoropolymer resins, low-conductivity adhesives, and silica aerogel precursors. Single-source vulnerability concentrates in metallized film deposition equipment where specialized vacuum chamber manufacturing limits supplier diversification. Distribution runs through industrial gas network relationships and direct EPC contractor specifications rather than merchant distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cryogenic insulation films market sits in a technology-transition phase where aerogel-infused composite architectures displace conventional metallized polyester stacks in premium hydrogen infrastructure applications.
For Market Incumbents: Extend aerogel technology leadership into space-constrained installations through precision deposition capacity expansion, while anchoring manufacturing scale positions in medium-thickness polyethylene grades for standardized LNG terminal procurement. EPC contractor procurement fragmentation threatens margin capture; backward integration into metallized substrate deposition reduces input bottlenecks from specialized aluminum coating suppliers. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for cold-chain equipment material upgrades, creating virgin specification opportunities without incumbent supplier lock-in. Target India's PLI scheme for clean hydrogen production where hydrogen hub development lacks established containment material relationships. Lead with digital procurement platform integration to unbundle specification-grade film sourcing from legacy bundled industrial gas service contracts. For Investors and Strategic Acquirers: The window for entry favors materials science firms with extreme-temperature formulation expertise and precision deposition equipment capabilities. Long-term viability hinges on qualification timelines for hydrogen liquefaction scale-up rather than near-term aerospace volume. Watch EPC contractor procurement incentive structures as the inflection indicator—shift from first-cost minimization toward lifecycle thermal performance mandates would revalue premium composite film suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Metallized Substrate Deposition | Captive aluminum coating capacity insulates against input bottlenecks from integrated chemical conglomerates. |
| Strategic Partnership with EPC Contractors | Direct specification relationships bypass fragmented procurement authority in German hydrogen liquefaction projects. |
| Technology Licensing for Aerogel Interlayer Integration | Silica aerogel formulation expertise commands premium positioning in space-constrained hydrogen containment. |
| Long-term Supply Agreement with Industrial Gas Networks | Mitsubishi Chemical Corporation's model anchors volume throughput across Asian industrial gas distribution. |
| Green Certification Program for REACH Compliance | ECHA chemical disclosure pre-qualification marginalizes marginal entrants lacking formulation transparency. |
Study Parameters
Multi-period observation of LNG liquefaction capacity buildouts, hydrogen hub development timelines, and aerospace launch cadence anchored the trend analysis, supplemented by interviews with EPC contractor procurement leads, industrial gas network sourcing managers, cryogenic vessel engineering directors, and polymer formulation R&D heads. Secondary validation drew from EPA Clean Air Act enforcement records, ECHA REACH registration databases, ISO 23953 certification registries, and customs trade data for metallized film imports. Bottom-up segment sizing triangulated against top-down energy infrastructure capex forecasts.
Input-output matrix framing connected hydrogen liquefaction project pipelines to thickness specification demand, LNG terminal expansion schedules to polyethylene film volume, and satellite constellation deployment to thin-film aerospace procurement. Segmentation dimensions modeled encompassed film type composition, end-use industry concentration, thickness configuration, and regional regulatory framework clusters. CAGRs were derived from installation capacity buildouts cross-referenced with thermal performance upgrade cycles and boil-off gas penalty structures.
Caveats apply where hydrogen liquefaction scale-up delays, metallized substrate supply disruptions, or EPC contractor incentive misalignments could materially shift the outlook. Forecasts reflect assumptions around regulatory leakage threshold enforcement and qualification timeline compression. A small set of named triggers—EPA emissions threshold tightening, EU F-Gas Regulation phase-down acceleration, and ISO 23953 benchmark revision—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Packaging Barrier Films Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
USA Barrier Coated Paper Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
PET Release Liner Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Anti-Static Packaging Film Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Tray Liners Market
Packaging Barrier Films
Europe Barrier Films Market