
 Transparent Barrier Packaging Films Market | 2026-2036
Transparent Barrier Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Transparent Barrier Packaging Films Market Outlook
Market Context
Capital-intensity divergence between coextrusion-equipped multinationals and regional converters is bifurcating competitive dynamics in transparent barrier packaging films. Amcor plc leverages integrated resin-to-film operations across European pharma corridors, sustaining margin capture from ethylene vinyl alcohol supply chains. Toray Industries anchors Asia-Pacific demand through biaxially oriented polyester capacity, while Berry Global Inc. competes in North American food packaging via blown film lines optimized for polyethylene barrier blends.
Technical Definition and Segment Structure
Transparent barrier packaging films are multi-layer or surface-coated flexible substrates engineered to block oxygen, moisture, and aroma transmission while maintaining optical clarity, typically achieving oxygen transmission rates below 1 cc/m²/day through vacuum-deposited aluminum oxide or silicon oxide layers. These films preserve shelf stability in modified-atmosphere food packs and protect moisture-sensitive pharmaceuticals from degradation. Metallized films dominate value pools due to capital barriers in vacuum deposition equipment, though composite films incorporating ethylene vinyl oxygen barriers represent the fastest-growing material architecture as brand owners seek recyclable mono-material alternatives to multi-polymer laminates. Plastic films remain the volume base across food packaging applications where cost thresholds constrain material experimentation.
Regulatory Framework and Outlook
The EU's Packaging and Packaging Waste Regulation and REACH chemical compliance frameworks are reshaping material specifications, compelling converters to validate barrier performance in reduced-polymer structures. FDA food-contact notification requirements and EMA pharmaceutical packaging guidelines create dual compliance burdens for suppliers serving transatlantic pharma accounts. Stakeholders must monitor evolving extended-producer-responsibility fee structures and decide between retrofitting existing coextrusion assets or investing in novel bio-based barrier chemistries.
Market Dynamics
Mono-material barrier structures are displacing multi-polymer laminates as the EU's Packaging and Packaging Waste Regulation tightens recyclability mandates, forcing converters to re-engineer ethylene vinyl alcohol and silicon oxide deposition processes without sacrificing oxygen transmission performance.
Growth Catalysts
- Cold-chain biologics expansion:Pharmaceutical packaging adoption accelerates as temperature-sensitive biologics require oxygen and moisture protection throughout distribution networks.
- REACH chemical compliance frameworks:Regulatory pressure in Europe compels material innovation in reduced-polymer structures, validating barrier performance in recyclable formats.
- German packaging clusters:Specialized film consumption concentrates in Germany where food and pharma packaging corridors drive technical specifications and volume demand.
Market Restraints
- Capital barriers in vacuum deposition:Metallized film production requires specialized aluminum oxide and silicon oxide equipment that limits new market entry.
- Dual compliance burdens:FDA food-contact notification requirements and EMA pharmaceutical packaging guidelines create validation complexity for transatlantic suppliers.
- Ethylene vinyl alcohol supply concentration:Resin availability constraints and pricing volatility affect barrier film cost structures.
Strategic Opportunities
- Extended-producer-responsibility fee structures:Evolving EPR frameworks create first-mover advantages for converters with validated mono-material barrier platforms.
- Bio-based barrier chemistries:Novel renewable feedstocks offer differentiation paths as brand owners seek carbon footprint reductions in packaging portfolios.
- Modified-atmosphere food packaging:Fresh protein and ready-meal segments in Western Europe present underpenetrated demand for high-clarity barrier substrates.
Industry Challenges
- Vacuum deposition technician scarcity:Specialized metallization and oxide layer expertise shortages constrain capacity expansion timelines.
- Retrofit versus greenfield capex decisions:Converters face capital allocation complexity when deciding between upgrading existing coextrusion assets or investing in novel deposition technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transparent Barrier Packaging Films Market |
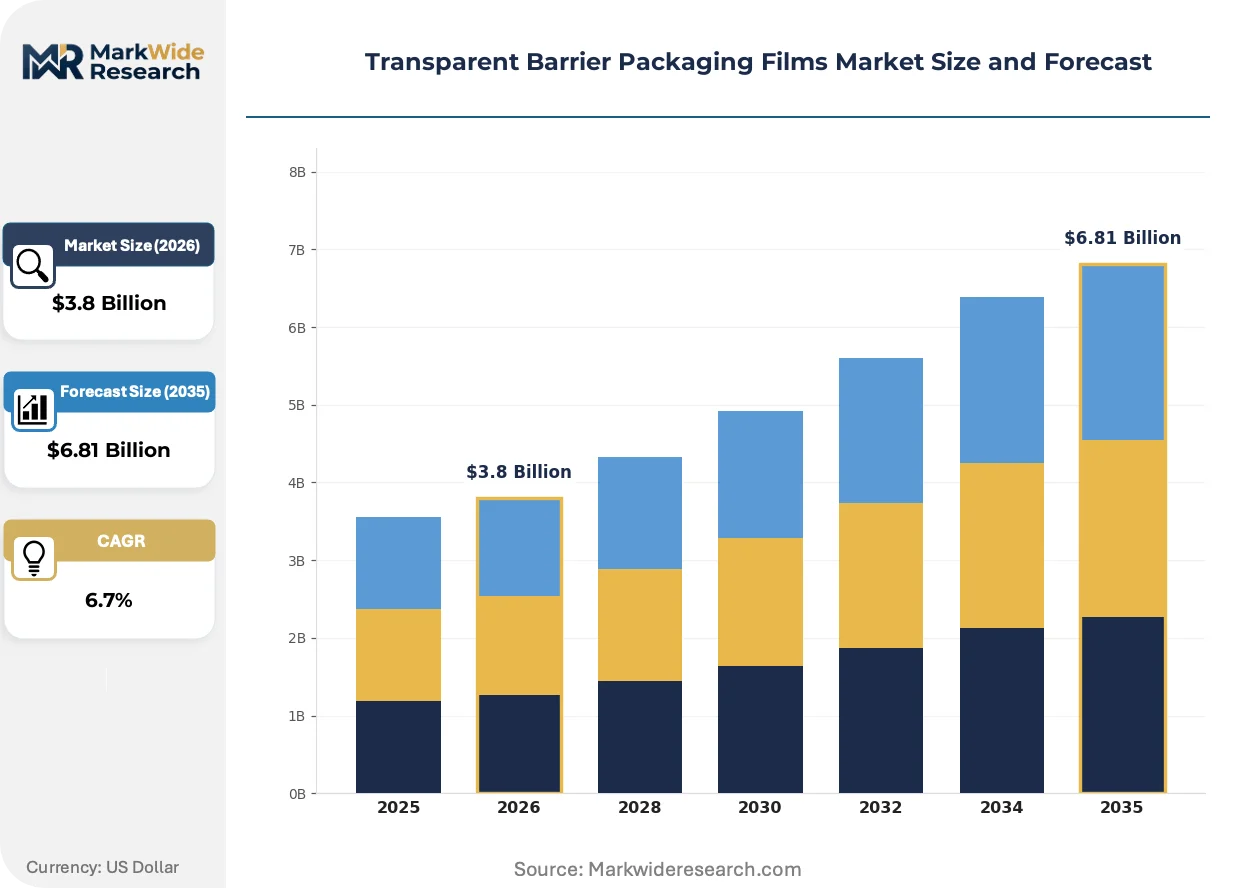
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Films, Composite Films, Paper Films, Metallized Films Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Ethylene Vinyl Alcohol Application: Food Packaging, Pharmaceutical Packaging, Consumer Goods, Industrial Packaging End User: Food Industry, Healthcare Sector, Cosmetics Industry, Electronics Manufacturers |
| Companies Covered | Mondi Group, 3M, Amcor plc, Toray Industries, Sonoco Products Company, Berry Global Inc., TOPPAN Inc., WINPAK Ltd, Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transparent Barrier Packaging Films Market Strategic Shifts
Barrier film technology is pivoting toward surface-engineered mono-materials as regulatory deadlines compress development cycles and brand owners demand optical clarity without multi-polymer complexity.
Silicon oxide and aluminum oxide vacuum deposition is bifurcating competitive positioning in high-performance transparent barriers. Pharmaceutical packagers and premium food brands are adopting these ceramic-coated films at accelerated rates. The technology is bifurcating value pools between capital-intensive metallized specialists and emerging composite film producers.
REACH chemical compliance frameworks are forcing material requalification across European converter networks. Substance restriction lists now exclude certain adhesion promoters and slip agents common in legacy barrier laminates. Pharmaceutical packaging suppliers serving EMA-regulated markets are accelerating validation programs for alternative chemistries.
Brand owner sustainability scorecards are reshaping procurement criteria for barrier film suppliers. Major food retailers in Germany and France now mandate recyclability certifications that disqualify conventional multi-polymer structures. Technical buyers are consolidating supplier bases toward converters with validated mono-material barrier platforms and transparent chain-of-custody documentation.
Transparent Barrier Packaging Films Market Segmentation
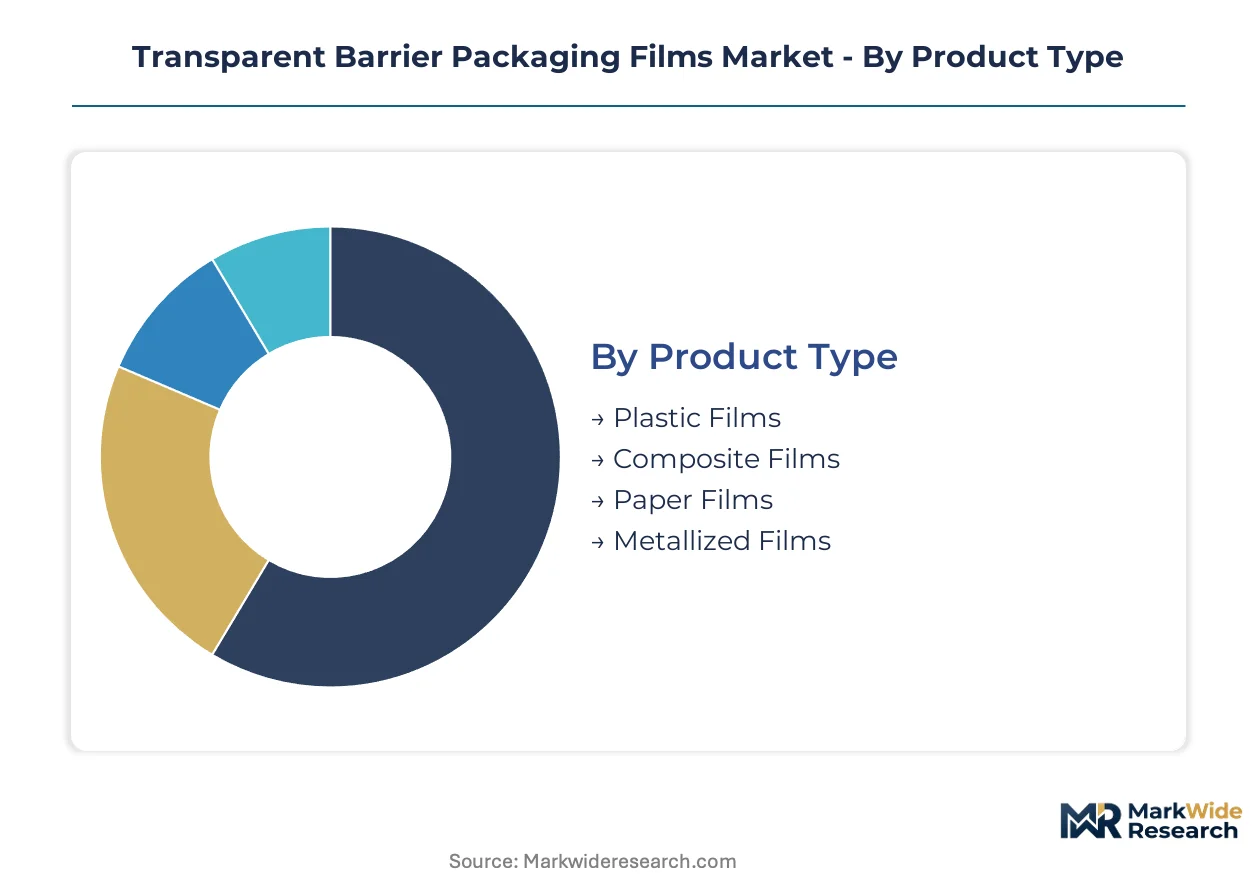
Transparent barrier packaging films serve divergent technical requirements across food preservation, pharmaceutical stability, and industrial protection. Segment boundaries reflect material science capabilities, regulatory compliance burdens, and end-use performance specifications that reshape procurement patterns.
Product Type:
Domestic consumption patterns in Germany and France favor metallized and composite formats, while export-oriented converters in Asia-Pacific ship plastic film volumes to North American food processors.
- Metallized Films:Vacuum-deposited aluminum oxide layers achieve oxygen transmission rates below 0.5 cc/m²/day. German pharmaceutical corridors and French premium food brands drive specialized demand for silicon oxide variants that maintain optical clarity.
- Composite Films:Multi-layer structures incorporating ethylene vinyl alcohol barriers dominate modified-atmosphere meat and cheese packaging. REACH compliance deadlines are accelerating converter migration toward recyclable mono-material alternatives to conventional laminates.
- Plastic Films:Polyethylene and polypropylene base layers serve cost-constrained fresh produce segments across Southern European retail chains.
- Paper Films:Fiber-based substrates with barrier coatings target sustainability-focused confectionery and dry goods applications in Nordic markets.
Metallized films hold the largest share; momentum sits with composite films as recyclability mandates tighten.
Material:
Cost tiers separate commodity polyolefins from specialty oxygen barriers, with ethylene vinyl alcohol commanding premium positioning in pharmaceutical and high-performance food applications.
- Ethylene Vinyl Alcohol:Copolymer resin delivers exceptional oxygen barrier performance at low humidity conditions. Cold-chain biologics expansion across German and Swiss pharmaceutical manufacturing clusters sustains specialized resin demand despite supply concentration risks.
- Polyethylene:Blown and cast film grades anchor volume consumption in fresh produce and frozen food segments where moisture barrier requirements dominate over oxygen exclusion.
- Polypropylene:Biaxially oriented structures provide stiffness and clarity for snack food and bakery applications across Italian and Spanish retail markets.
- Polyvinyl Chloride:Shrink film formats persist in specific meat packaging applications though regulatory pressure from ECHA substance evaluations constrains growth trajectories.
Polyethylene dominates volume; ethylene vinyl alcohol claims the steepest expansion trajectory from pharma specialization.
Application:
Customer type stratification separates price-sensitive commodity food packagers from validation-intensive pharmaceutical suppliers serving EMA-regulated markets.
- Food Packaging:Modified-atmosphere applications for fresh protein and ready-meal segments demand high-clarity barriers across German and French retail supply chains. Retailer sustainability scorecards now mandate recyclability certifications that disqualify legacy multi-polymer structures.
- Pharmaceutical Packaging:Blister packs and cold-chain distribution materials require validated oxygen and moisture protection. FDA food-contact notification requirements and EMA pharmaceutical packaging guidelines create dual compliance burdens for transatlantic suppliers.
- Consumer Goods:Barrier films for cosmetics and personal care applications emphasize aroma retention and shelf appeal in premium positioning strategies.
- Industrial Packaging:Electronics and chemical protection applications utilize metallized formats where static dissipation and moisture exclusion converge.
Food packaging holds the largest share; pharmaceutical packaging is gaining share fastest from biologics expansion.
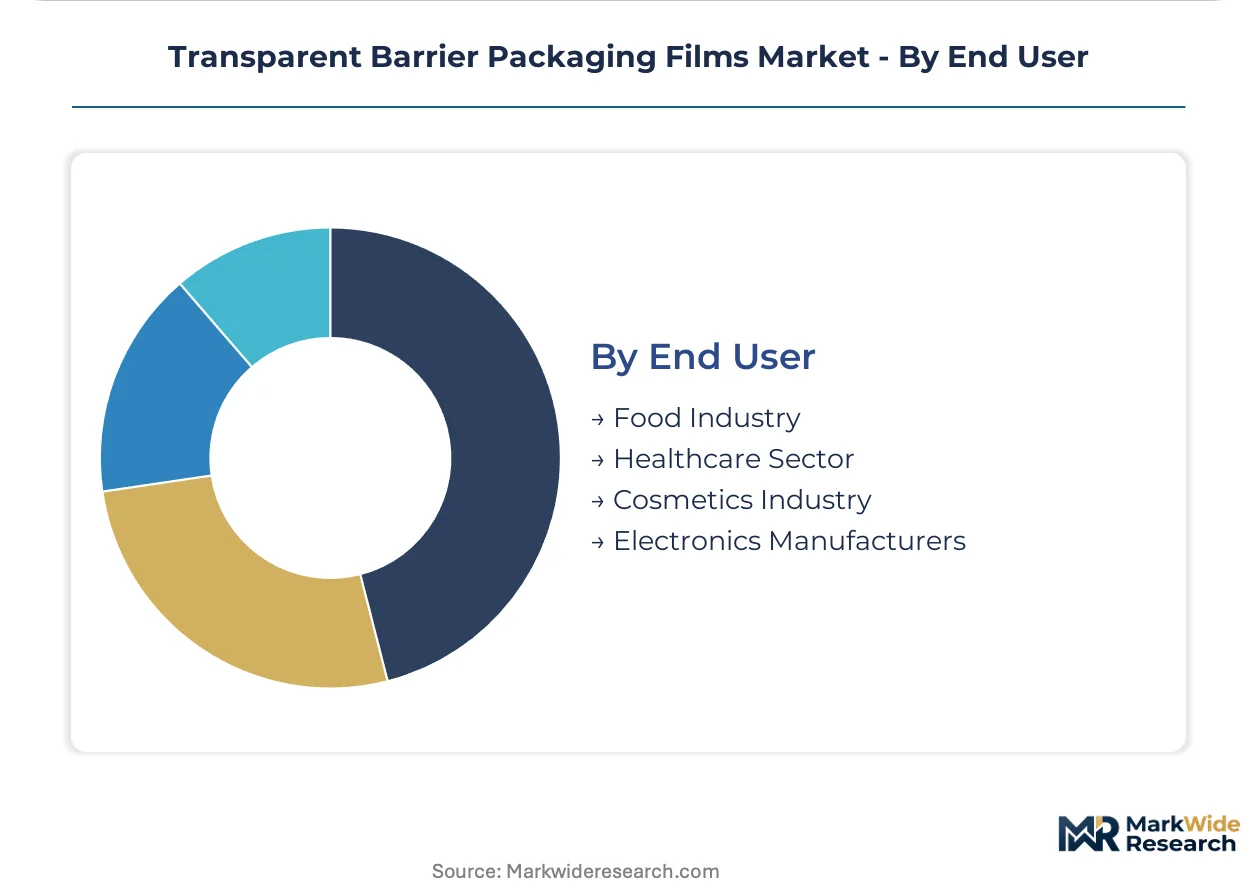
End User:
Supply concentration aligns with geographic clustering — German food and pharma packaging corridors drive technical specifications that propagate across European converter networks.
- Food Industry:Meat processors, dairy cooperatives, and bakery chains across Germany, France, and Italy constitute the foundational demand base. Extended-producer-responsibility fee structures in these markets reward converters with validated mono-material barrier platforms.
- Healthcare Sector:Pharmaceutical manufacturers and contract packaging organizations require batch-level traceability and barrier validation documentation. Swiss and German pharma clusters sustain specialized film consumption despite capital barriers in vacuum deposition equipment.
- Cosmetics Industry:Premium skincare and fragrance brands prioritize optical clarity and shelf differentiation in Western European urban markets.
- Electronics Manufacturers:Semiconductor and display producers utilize metallized barrier films for moisture-sensitive component protection, concentrated in German and Dutch industrial corridors.
The food industry holds the largest share; the healthcare sector shows the strongest momentum from cold-chain biologics requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a structural trade surplus in specialized barrier films, exporting high-value metallized and ceramic-coated substrates to Swiss pharmaceutical corridors and French food packaging clusters while importing commodity polyethylene base films from Dutch and Belgian resin converters.
Germany
Modified-atmosphere meat packaging and cold-chain biologics distribution drive specialized film consumption across Bavarian and North Rhine-Westphalian industrial zones. The EU's Packaging and Packaging Waste Regulation forces converters in the Düsseldorf-Cologne corridor to re-engineer multi-layer structures toward mono-material recyclability without sacrificing oxygen barrier performance below 1 cc/m²/day.
Switzerland
Pharmaceutical blister packs and temperature-sensitive biologics packaging sustain premium demand for silicon oxide-coated films in the Basel-Zurich manufacturing belt. Swissmedic guidelines on primary packaging materials compel validation-intensive documentation from film suppliers serving Novartis and Roche contract packaging networks.
France
Premium cheese and ready-meal segments in Île-de-France and Auvergne-Rhône-Alpes retail chains prioritize high-clarity barriers with extended shelf-life performance. ANSM pharmaceutical packaging standards create compliance overlap with EMA requirements, complicating film qualification for converters supplying both domestic and export pharma accounts.
United States
Frozen food and snack packaging processors in the Midwest and Southeast consume polyethylene barrier blends at scale, though FDA food-contact notification requirements delay new material adoption. Berry Global's blown film operations in Evansville and Charlotte anchor regional supply chains for modified-atmosphere applications.
Japan
Biaxially oriented polyester capacity in the Chubu and Kansai regions serves electronics moisture-barrier and precision food packaging demand. METI's resource circulation policies accelerate converter investment in thin-film deposition technologies that reduce aluminum oxide material intensity per square meter.
Transparent Barrier Packaging Films Market Competitive Environment
Concentration sits with integrated resin-to-film multinationals that command vacuum deposition equipment and ethylene vinyl alcohol supply chains. Regional converters without metallization assets compete on polyethylene barrier blends and coextrusion flexibility for cost-sensitive food segments. Two strategic archetypes dominate: capital-intensive metallized specialists with captive oxide deposition capacity, and composite film innovators engineering recyclable mono-material alternatives. Competitive moves center on retrofitting existing coextrusion lines versus greenfield investment in silicon oxide deposition, alongside strategic partnerships with brand owners seeking validated chain-of-custody documentation.
Among integrated packaging conglomerates, Amcor plc and Toray Industries exemplify divergent geographic anchoring strategies. Amcor's European pharma corridor presence leverages backward integration into ethylene vinyl alcohol resin supply chains. Toray's Chubu-region polyester operations capture Asia-Pacific electronics and precision food demand through biaxial orientation scale. Berry Global Inc. occupies a position in North American blown film conversion, serving food processors with polyethylene barrier expertise. Mondi Group represents the European diversified paper and film archetype, while 3M sits within the specialty materials tier with surface-coating technology heritage.
| Leading Market Players |
|---|
| Mondi Group |
| 3M |
| Amcor plc |
| Toray Industries |
| Sonoco Products Company |
| Berry Global Inc. |
| TOPPAN Inc. |
| WINPAK Ltd |
| Sealed Air |
| Others |
Value Chain & Pricing Dynamics
Capital utilization rates above 85% in German vacuum deposition facilities create asymmetric pricing power for metallized film specialists, compressing margin capture for regional converters lacking oxide coating capacity while elevating ethylene vinyl alcohol resin procurement as the dominant cost variable across all barrier film tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across pharmaceutical and premium food packaging corridors. Pricing stratifies across EVOH-rich pharmaceutical grades, mid-tier modified-atmosphere food laminates, and commodity polyethylene base films for fresh produce. Cost compression in standard-tier polyethylene barriers is intensifying because Dutch and Belgian resin converters are expanding blown film capacity. Food processors in Southern European retail chains exhibit highest price sensitivity, while Swiss pharmaceutical manufacturers accept premium positioning for validated silicon oxide documentation.
Supply Chain Analysis
Strategic stockpile preferences dominate ethylene vinyl alcohol procurement as Japanese and German resin suppliers operate on 90-day order cycles with limited spot availability. Raw material flows draw from Saudi ethylene feedstock, Japanese copolymer resin operations, and German metallization equipment fabrication. Single-source vulnerability concentrates in silicon oxide deposition chambers sourced from Chubu-region precision engineering clusters. Distribution runs through converter-direct relationships with Bavarian pharmaceutical packagers and French dairy cooperatives, bypassing traditional chemical distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mono-material barrier platforms are emerging as interoperability standards across EU extended-producer-responsibility frameworks, creating winner-take-most dynamics for converters whose deposition chemistries validate seamlessly across German, French, and Swiss regulatory filing systems.
For Market Incumbents: Fortify captive ethylene vinyl alcohol supply arrangements through backward integration into copolymer resin operations or exclusive offtake agreements with Japanese suppliers. Prioritize certification investment for REACH-compliant adhesion promoters ahead of substance restriction list expansions. Defend margin position by retrofitting existing coextrusion assets for mono-material barrier production rather than greenfield silicon oxide deposition capacity. For New Entrants and Emerging Players: Anchor in Nordic paper-based barrier coating segments where sustainability-focused confectionery brands lack validated supplier alternatives. Target dry goods applications with fiber substrates carrying aluminum oxide vapor-deposited layers as the most penetrable white-space. Pursue direct technical partnerships with German retailer sustainability procurement teams seeking transparent chain-of-custody documentation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with validated mono-material barrier platforms over metallized film specialists facing stranded asset risk from recyclability mandates. Long-term viability rests on EPR fee structure arbitrage and brand owner sustainability scorecard consolidation. The acquisition target archetype combines coextrusion flexibility with in-house barrier coating validation capabilities. Watch for Swissmedic or EMA guidance revisions on primary packaging material recyclability as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Validation | EU Packaging and Packaging Waste Regulation compliance secures EPR fee advantages for German converters. |
| Backward Integration into EVOH Resin | Captive copolymer supply insulates margin capture from Japanese supplier pricing volatility. |
| Silicon Oxide Deposition Capacity | Pharmaceutical blister pack demand from Basel-Zurich manufacturing belt sustains premium positioning. |
| REACH-Compliant Chemistry Requalification | Alternative adhesion promoter validation prevents exclusion from EMA-regulated pharma supply chains. |
| Retailer Sustainability Partnership | Direct technical collaboration with French and German retail procurement teams locks in volume commitments. |
Study Parameters
Cross-validation between converter production data and brand owner procurement disclosures anchors the qualitative findings in this analysis. Primary interviews with vacuum deposition equipment engineers, pharmaceutical packaging technical directors, food industry sustainability procurement leads, and EVOH resin supply planners informed capacity utilization and technology adoption assessments. Secondary validation drew from ECHA substance restriction notifications, EU Packaging and Packaging Waste Regulation impact assessments, SEC filings of integrated packaging conglomerates, and German packaging industry association production surveys. Bottom-up segment sizing triangulated against top-down macroeconomic demand indicators across the analysis window.
Sensitivity analysis around ethylene vinyl alcohol resin price scenarios and EPR fee structure implementations shaped the forecast framework. Segmentation dimensions modeled include product type architecture, material chemistry tier, application performance specifications, and end-user industry vertical across regional production clusters. CAGRs were derived from fitted growth curves calibrated to historical adoption patterns in modified-atmosphere food packaging and cold-chain biologics distribution. Industry-specific inputs incorporated REACH compliance timeline acceleration and Swissmedic packaging guideline revision probabilities.
Decision-makers should treat outputs as directional under base assumptions of sustained EU regulatory stringency and stable pharmaceutical cold-chain investment; material deviation would warrant model refresh. Forecasts embed assumptions regarding ethylene vinyl alcohol supply concentration and vacuum deposition technician availability. Revision becomes warranted when EMA primary packaging recyclability guidance crosses implementation thresholds or when Japanese resin supplier capacity expansion announcements alter feedstock availability assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Nano Sealers Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Meat Packaging Films Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Global High Barrier Packaging Films Market
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Hydrocolloid Coating Market
Packaging Barrier Films
Barrier Coated Carton Market