
 High Barrier Lidding Film Market | 2026-2036
High Barrier Lidding Film Market Size, Share, and Industry Trends Forecast 2026-2036
High Barrier Lidding Film Market Analysis
Subscription-based technical service and preventive maintenance contracts is consolidating revenue streams beyond resin and film tonnage. Amcor Limited leverages its global converting footprint to anchor multi-year supply agreements with protein processors. Huhtamäki Oyj sustains competitive positioning through specialized lidding lines tuned to retort and microwave applications. Sealed Air Corporation dominates modified-atmosphere packaging configurations with proprietary barrier coating know-how.
High barrier lidding film denotes a multilayer flexible structure, typically combining ethylene vinyl alcohol copolymers or polyamide with polyolefin sealant layers through coextrusion or lamination, engineered to maintain oxygen transmission rates below one cubic centimeter per square meter per day. The film serves primarily to preserve organoleptic quality and microbial safety in preformed trays and cups across refrigerated and shelf-stable distribution chains. Metallized films capture margin pools in premium meat and cheese applications where light and oxygen exclusion justify material cost premiums over transparent alternatives. Laminated technology leads volume throughput due to its versatility in bonding dissimilar functional layers, while extruded structures gain ground in pharmaceutical blister lidding where thickness uniformity and seal integrity carry regulatory weight.
The US FDA governs food contact substance notifications and migration thresholds, directly shaping resin selection and additive packages for lidding films sold into American retail channels. EFSA and REACH collectively constrain monomer and additive chemistries across European converters, accelerating substitution toward bio-based and recyclable barrier architectures. China's SAMR enforces GB standards for composite food packaging materials, creating compliance thresholds for imported film structures. Stakeholders must monitor evolving extended producer responsibility frameworks and recyclability certifications as these criteria increasingly gate retail shelf access and brand procurement decisions.
Market Dynamics
Retailer consolidation across North American and European grocery channels is compressing supplier margins while demanding extended shelf-life performance from lidding film specifications. Protein processors now mandate oxygen transmission rates below one cubic centimeter per square meter per day as a baseline procurement threshold.
Growth Catalysts
- EFSA Migration Limits:European Food Safety Authority thresholds on plastic food contact materials push converters toward compliant coextruded structures with enhanced barrier properties.
- Fresh Food Tray Adoption:North American retailers seek extended shelf stability for prepackaged proteins, driving specification upgrades across refrigerated distribution chains.
- Metallized Film Performance:Light and oxygen exclusion capabilities in premium meat and cheese applications justify material cost premiums over transparent alternatives.
Market Restraints
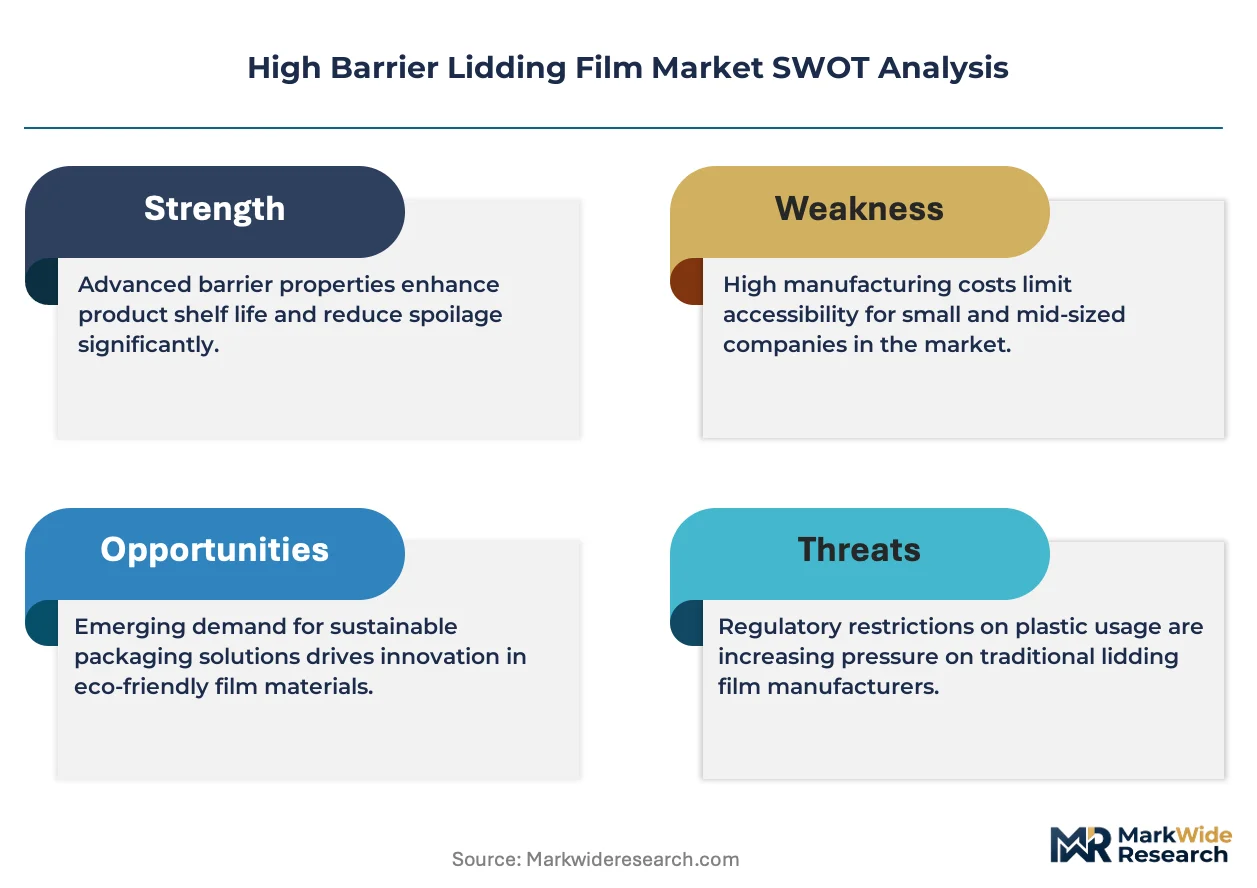
- Resin Cost Volatility:Ethylene vinyl alcohol copolymer and polyamide feedstock prices fluctuate with crude oil and natural gas benchmarks, compressing converter margins.
- Supply Concentration Risk:Barrier coating know-how and specialized lidding line capacity cluster among a limited set of European and North American equipment suppliers.
- Technical Thickness Limitations:Pharmaceutical blister lidding demands sub-50-micron uniformity that extruded structures struggle to achieve consistently at commercial scale.
Strategic Opportunities
- Underpenetrated Dairy Applications:German processed cheese and yogurt cup segments show latent demand for retort-capable lidding with microwave venting features.
- Regulatory Tailwinds:China's SAMR enforcement of GB standards for composite food packaging materials creates compliance thresholds favoring imported film structures with certified barrier architectures.
- Technology Convergence:Modified-atmosphere packaging integrates with smart label indicators, opening premium positioning in protein traceability applications.
Industry Challenges
- Coextrusion Engineering Talent Scarcity:Multilayer die design and rheology optimization skills concentrate among aging specialists in Germany and the United States.
- Recyclability Certification Timelines:Extended producer responsibility frameworks and recyclability certifications increasingly gate retail shelf access, requiring 18-24 month validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Barrier Lidding Film Market |
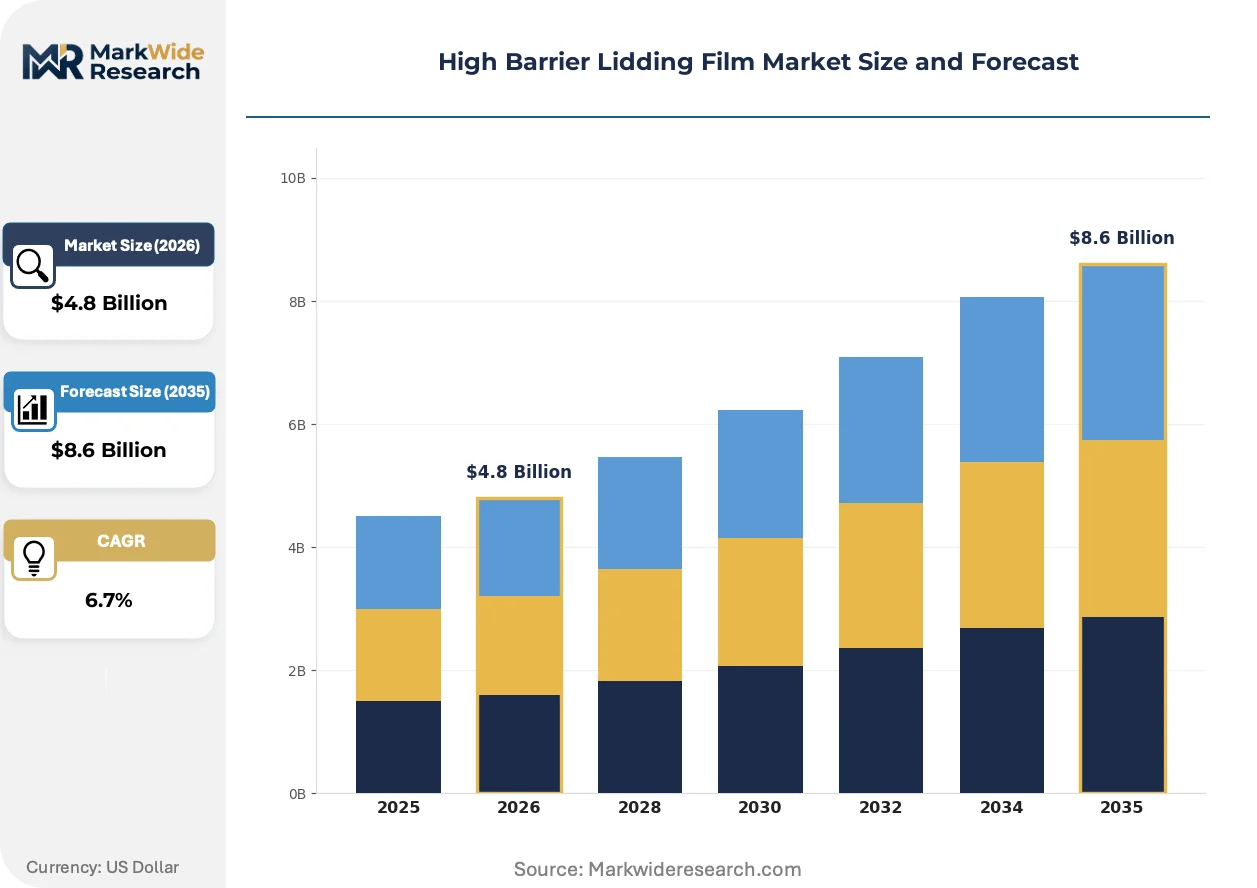
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent, Metallized, Aluminum Foil, Paper-Based End User: Food Packaging, Pharmaceutical, Electronics, Cosmetics Technology: Printed, Coated, Laminated, Extruded Application: Sealing, Wrapping, Protection, Storage |
| Companies Covered | Constantia Flexibles Group GmbH, Huhtamäki Oyj, Amcor Limited, Coveris Holdings S.A., Mondi plc, Sealed Air Corporation, Sonoco Products Company, Winpak Ltd., Berry Global Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Barrier Lidding Film Market Emerging Trajectories
Barrier film architecture is pivoting toward mono-material compatibility as mechanical recycling infrastructure matures across European collection systems. Converters now engineer polyolefin-dominant structures that maintain oxygen exclusion without EVOH or PA layers.
Mono-material polyolefin barrier films are absorbing technical development resources previously directed toward complex multilayer laminates. Major protein processors in Germany and the Netherlands now specify these structures for fresh meat trays to satisfy retailer recyclability mandates. The shift is absorbing capital from traditional coextrusion lines and redirecting it toward plasma-enhanced chemical vapor deposition coating systems.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated barrier coatings from European food contact applications by 2025. Converters must reformulate with silicon oxide or aluminum oxide alternatives that achieve comparable water vapor transmission rates. Ready-meal and seafood packaging segments face the steepest reformulation curves as existing shelf-life claims depend on legacy fluorinated chemistries.
Buying committees at major retail chains now unbundle technical service contracts from resin tonnage agreements, creating standalone procurement categories for preventive maintenance and line optimization. This behavior concentrates purchasing power among converters with captive technical service organizations. The pattern is most pronounced in French and British supermarket chains where centralized packaging specification teams negotiate multi-year performance contracts.
High Barrier Lidding Film Market Segmentation
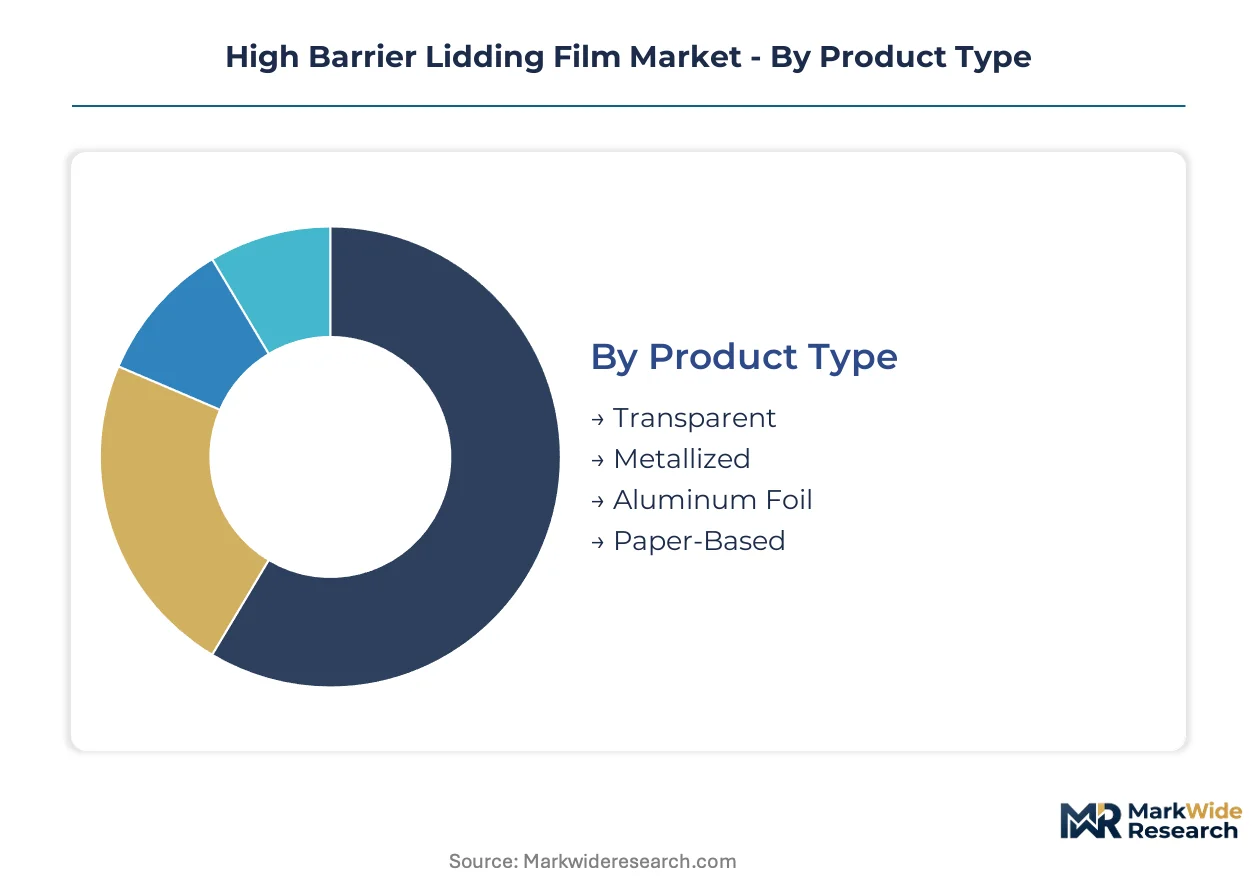
Segmentation in high barrier lidding film reveals how technical specifications map to price-performance trade-offs across protein, dairy, and pharmaceutical applications. Buyers select structures based on oxygen transmission thresholds, seal temperature windows, and downstream recyclability mandates.
Product Type:
Transparent films dominate tonnage throughput while metallized variants command premium positioning in shelf-life-sensitive categories.
- Transparent:Multilayer coextruded structures combining EVOH or polyamide cores with polyolefin sealants achieve sub-one cc/m²/day oxygen transmission. German processed meat processors specify these for refrigerated tray applications where visual product inspection drives consumer preference.
- Metallized:Vacuum-deposited aluminum layers on oriented substrates deliver near-zero oxygen and light transmission. Premium cheese and cured meat applications in France and Italy absorb these films where extended distribution cycles justify material cost premiums.
- Aluminum Foil:Dead-fold laminates with heat-seal coatings serve retort pouch and pharmaceutical blister applications demanding absolute barrier integrity.
- Paper-Based:Fiber substrates with extruded barrier layers address emerging recyclable packaging mandates in Nordic retail channels.
Mature deployment sits with Transparent films. Newer deployment is concentrated in Paper-Based structures.
End User:
Food packaging absorbs the majority of volume while pharmaceutical specifications drive the most stringent technical requirements.
- Food Packaging:Modified-atmosphere configurations for fresh proteins and dairy dominate procurement volumes. North American retailers now mandate oxygen transmission below one cc/m²/day as a baseline threshold for refrigerated distribution.
- Pharmaceutical:Blister lidding for solid dose medications demands sub-50-micron thickness uniformity and validated seal integrity. FDA food contact substance notifications and EMA compliance documentation shape resin selection for these applications.
- Electronics:Static-dissipative barrier films protect moisture-sensitive components during semiconductor assembly and distribution.
- Cosmetics:High-barrier lidding for single-serve masks and serums leverages metallized structures to prevent oxidative degradation of active ingredients.
Food Packaging captures the highest volume concentration. Pharmaceutical represents the steepest expansion trajectory as serialization and unit-dose compliance accelerate.
Technology:
Laminated constructions retain versatility leadership while extruded structures gain ground in thickness-critical pharmaceutical applications.
- Printed:Gravure and flexographic decoration layers applied to barrier substrates enable brand differentiation and regulatory labeling compliance.
- Coated:Silicon oxide and aluminum oxide vapor deposition replaces fluorinated chemistries under REACH restrictions, achieving comparable water vapor transmission without PFAS.
- Laminated:Adhesive and extrusion lamination bonds dissimilar functional layers—barrier, structural, and sealant—into customized performance stacks. This technology leads volume throughput due to its flexibility in matching film properties to specific tray and cup formats.
- Extruded:Coextrusion through multilayer dies produces thickness-uniform structures with integral barrier and sealant layers. Pharmaceutical blister applications favor this approach where gauge control directly impacts seal integrity and child-resistance performance.
Capability concentration clusters with Laminated technology. Extruded structures are gaining technical investment as mono-material compatibility requirements intensify.
Application:
Sealing functions dominate equipment line utilization while protection specifications carry the highest performance premiums.
- Sealing:Heat-activated sealant layers bond lidding to preformed trays and cups across form-fill-seal and thermoforming lines. Peelable and weld-seal variants match specific protein and dairy processing requirements.
- Wrapping:Overwrap configurations for bulk meat cuts and cheese wheels employ barrier films to extend case-ready distribution timelines.
- Protection:Oxygen, moisture, and light exclusion preserves organoleptic quality and microbial safety. This application commands the highest material specifications and corresponding margin pools.
- Storage:Secondary barrier layers in distribution totes and warehouse shelving systems prevent cross-contamination and environmental degradation.
Sealing absorbs the greatest installed equipment base. Protection commands the highest specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and the United States while consumption concentrates in retail-dense corridors across France, Japan, and Brazil. Converter investments in multilayer extrusion lines lag demand growth in emerging protein packaging markets.
United States
Fresh protein tray specifications drive specification upgrades across refrigerated distribution chains. The FDA governs food contact substance notifications and migration thresholds for lidding films sold into American retail channels. Chicago and Milwaukee anchor Midwest converter clusters where coextrusion capacity serves national meat processor contracts.
Germany
Processed meat and dairy corridors sustain demand for retort-capable lidding with microwave venting features. REACH restrictions on per- and polyfluoroalkyl substances eliminate fluorinated barrier coatings from food contact applications by 2025. Bavaria's film converting belt around Munich and Nuremberg hosts specialized lidding lines tuned to pharmaceutical blister specifications.
France
Premium cheese and cured meat applications absorb metallized films where extended distribution cycles justify material cost premiums. EFSA thresholds on plastic food contact materials push converters toward compliant coextruded structures. The Lyon-Grenoble corridor concentrates barrier coating know-how among equipment suppliers serving modified-atmosphere packaging configurations.
China
SAMR enforcement of GB standards for composite food packaging materials creates compliance thresholds favoring imported film structures with certified barrier architectures. Yangtze River Delta protein processors mandate oxygen transmission below one cubic centimeter per square meter per day as baseline procurement thresholds. Shanghai converter parks absorb technical development resources previously directed toward export markets.
Japan
Ready-meal and seafood packaging segments face steep reformulation curves as existing shelf-life claims depend on legacy fluorinated chemistries. METI guidelines shape resin selection for pharmaceutical blister applications demanding sub-50-micron thickness uniformity. Osaka-Kobe industrial zones concentrate multilayer die design and rheology optimization skills among aging specialist engineers.
High Barrier Lidding Film Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the high barrier lidding film value chain. The vendor base separates between integrated resin-to-film converters and specialized lidding line operators. Three archetypes dominate: multinational packaging conglomerates with captive technical service organizations, regional converters with deep vertical integration into barrier coating deposition, and equipment-agnostic toll manufacturers serving spot demand. Competitive moves concentrate on multi-year supply agreement anchoring and preventive maintenance contract unbundling from resin tonnage sales.
Within the multinational tier, Amcor Limited, Huhtamäki Oyj, and Sealed Air Corporation represent archetypal positioning. Amcor exemplifies global converting footprint leverage for protein processor anchoring. Huhtamäki occupies a specialized position in retort and microwave application tuning. Sealed Air anchors modified-atmosphere packaging configuration dominance through proprietary barrier coating know-how. These three exemplify how subscription-based technical service contracts consolidate revenue streams beyond resin and film tonnage.
| Leading Market Players |
|---|
| Constantia Flexibles Group GmbH |
| Huhtamäki Oyj |
| Amcor Limited |
| Coveris Holdings S.A. |
| Mondi plc |
| Sealed Air Corporation |
| Sonoco Products Company |
| Winpak Ltd. |
| Berry Global Group, Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up converter specialists in Germany and the United States have consolidated coextrusion capacity while maintaining disciplined pricing on retort-capable lidding specifications, creating margin buffers against resin volatility that family-owned mid-caps in France and Italy struggle to replicate.
Pricing Analysis
Cost-down pressure on standard transparent films accelerates because North American retailers now unbundle technical service contracts from resin tonnage agreements. Three-tier pricing structure across premium metallized, standard coextruded, and economy-grade laminated tiers reflects oxygen transmission performance and certification grade. Margin tightening in the economy tier traces to ethylene vinyl alcohol copolymer feedstock volatility. Protein processors show lowest price sensitivity for pharmaceutical-grade extruded structures; private-label dairy converters absorb highest pressure.
Supply Chain Analysis
Domestic-content mandates in China's Yangtze River Delta and SAMR enforcement of GB standards are reshaping sourcing toward certified imported barrier architectures with traceable resin pedigrees. Supply concentrates in Germany, the United States, and China. Feedstock draws from ethylene vinyl alcohol copolymer producers in Japan, polyamide resin specialists in Germany, and metallized substrate converters in Italy. Single-source vulnerability clusters in multilayer die engineering talent concentrated among aging specialists in Bavaria and Ohio. Distribution runs through protein processor central procurement hubs and retail chain specification committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized lidding line capacity acts as the binding constraint propping pricing power for converters with installed multilayer extrusion assets, while demand growth in Chinese protein packaging outpaces equipment supplier lead times.
For Market Incumbents: Acquire plasma-enhanced chemical vapor deposition coating systems to anchor mono-material barrier film production as REACH fluorinated chemistry bans eliminate legacy coating alternatives. Consolidate coextrusion engineering talent in Germany and the United States through targeted hiring from aging specialist pools. Backward integration into ethylene vinyl alcohol copolymer resin supply buffers margin compression from feedstock volatility. For New Entrants and Emerging Players: Silicon oxide vapor deposition technology-first wedge opens white-space in Japanese ready-meal and seafood packaging segments facing steep reformulation curves from fluorinated barrier coating elimination. Target underpenetrated German processed cheese and yogurt cup segments demanding retort-capable lidding with microwave venting features. Lead with certified barrier architecture compliance for SAMR GB standard enforcement in China's Yangtze River Delta. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional converters with captive barrier coating deposition capability in France and Italy where premium cheese and cured meat applications justify material cost premiums. Five-to-ten-year viability hinges on mono-material recyclability certification completion timelines. Watch extended producer responsibility framework implementation in Nordic retail channels as inflection indicator for paper-based structure demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Film Development | Plasma-enhanced chemical vapor deposition systems satisfy EFSA migration limits and retailer recyclability mandates. |
| Coextrusion Engineering Talent Acquisition | Multilayer die design specialists in Germany and Ohio enable pharmaceutical-grade thickness uniformity. |
| Preventive Maintenance Contract Unbundling | Standalone technical service agreements with French and British supermarket chains consolidate revenue streams. |
| REACH-Compliant Coating Reformulation | Silicon oxide and aluminum oxide alternatives replace fluorinated chemistries in European food contact applications. |
| Multi-Year Supply Agreement Anchoring | Long-term contracts with North American protein processors secure volume against resin cost volatility. |
Methodological Framework
Independent corroboration across converter plant managers, protein processor procurement leads, retail category buyers, and multilayer equipment engineers underwrites the qualitative findings in this study. Primary interviews with technical R&D directors at barrier coating deposition specialists and distribution channel partners in Germany, France, and the United States combined with secondary validation from customs and trade data, EFSA compliance documentation, and SEC filings from publicly traded packaging conglomerates. Bottom-up resin tonnage estimates and top-down retail shelf-space analysis triangulate market sizing.
Comparable-period anchoring to historical oxygen transmission specification upgrades and modified-atmosphere packaging adoption curves structured the forecast window. Segmentation modeling across product type, end user, technology, and application dimensions plus regional regulatory cluster variations shaped volume and value outputs. CAGRs derived from trend extrapolation of EVOH and polyamide feedstock pricing, retailer consolidation patterns, and extended producer responsibility framework rollout schedules.
Several conditions sit outside the modeled scope, including abrupt REACH enforcement acceleration, unanticipated fluorinated chemistry ban delays, and raw material supply disruptions from geopolitical conflict. Forecasts reflect documented assumptions about mechanical recycling infrastructure maturation and protein processor specification stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Global Adhesive Films Market
Packaging Barrier Films
Oxygen Barrier Films and Coatings for Dry Food Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Transparent Barrier Packaging Films Market
Packaging Barrier Films
Biodegradable Plastic Films Market
Packaging Barrier Films
PET Release Liner Market
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Barrier Materials Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Thailand Plastic Packaging Films Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
North America Protective Films Market
Packaging Barrier Films
Child-Resistant Foil Packaging Market
Packaging Barrier Films
Global Stretch and Shrink Film Market