
 Microwavable Barrier Films Market | 2026-2036
Microwavable Barrier Films Market Size, Share, and Industry Trends Forecast 2026-2036
Microwavable Barrier Films Market Foresight
The EU Packaging and Packaging Waste Regulation is pivoting converter investment toward recyclable mono-material barrier structures. Berry Global Inc leverages its North American blown film capacity to supply retail-ready lidding for frozen entree brands. Amcor plc anchors European demand through thermoformable coextruded lines certified for extended shelf-life applications. Sealed Air Corporation competes with vacuum-skinned barrier webs targeting premium protein segments.
Microwavable barrier films are multilayer polymer structures engineered to block oxygen and moisture ingress while withstanding thermal stress above 120°C, typically constructed from coextruded polyethylene, polypropylene, or polyamide substrates with metallized or ceramic coating layers. Their primary commercial purpose is to preserve organoleptic quality and microbial safety of prepackaged foods during frozen distribution and microwave rethermalization. Laminated films dominate value pools where ethylene vinyl alcohol copolymers deliver sub-1 cc/m²/day oxygen transmission rates for shelf-stable ready meals. Flexible films sustain volume leadership across single-serve pouch formats for institutional foodservice channels.
The FDA regulates indirect food contact substances under 21 CFR 177, while the EU F-Gas Regulation constrains fluorinated gas use in certain barrier manufacturing processes, and Japan's METI enforces positive list compliance for imported packaging materials. These frameworks collectively elevate compliance costs for non-domestic suppliers while rewarding localized certification investments. Stakeholders must monitor evolving extended producer responsibility schemes that will recalibrate cost structures for multi-material versus mono-material barrier constructions.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing converters to abandon multi-material laminates in favor of mono-material recyclable barrier structures, fundamentally restructuring R&D priorities and capital allocation across the value chain.
Growth Catalysts
- EU Green Deal packaging targets:Mandatory recyclability quotas by 2030 are pulling investment toward coextruded mono-material films with ceramic oxide barriers.
- Centralized retail procurement:German retail chains specify advanced oxygen-barrier specifications for private-label frozen food lines, concentrating demand in high-performance segments.
- Blown film line expansion:North American producers are scaling high-oxygen-barrier capacity to serve ready-to-eat meal brands.
Market Restraints
- Ethylene vinyl alcohol supply concentration:Asian suppliers dominate EVOH resin production, exposing converters to input cost volatility and freight risk.
- Metallization equipment capex:Vacuum deposition lines require substantial capital outlay, limiting barrier film production to well-capitalized processors.
- EU F-Gas Regulation constraints:Fluorinated gas restrictions in plasma-enhanced chemical vapor deposition processes add compliance friction for ceramic barrier manufacturers.
Strategic Opportunities
- Japan METI positive list compliance:Certified barrier film suppliers gain preferential access to Japanese food packaging import channels.
- Single-serve institutional formats:Foodservice channels are adopting flexible pouch formats for healthcare and correctional facility feeding programs.
- Thermoformable coextrusion convergence:Integration of barrier layers with form-fill-seal automation is opening premium protein packaging segments.
Industry Challenges
- Multi-layer delamination expertise:Mono-material recyclability requires retraining polymer scientists in compatibilizer chemistry and layer adhesion control.
- Extended producer responsibility timelines:EU member state implementation schedules for packaging fee modulation remain fragmented, complicating investment planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microwavable Barrier Films Market |
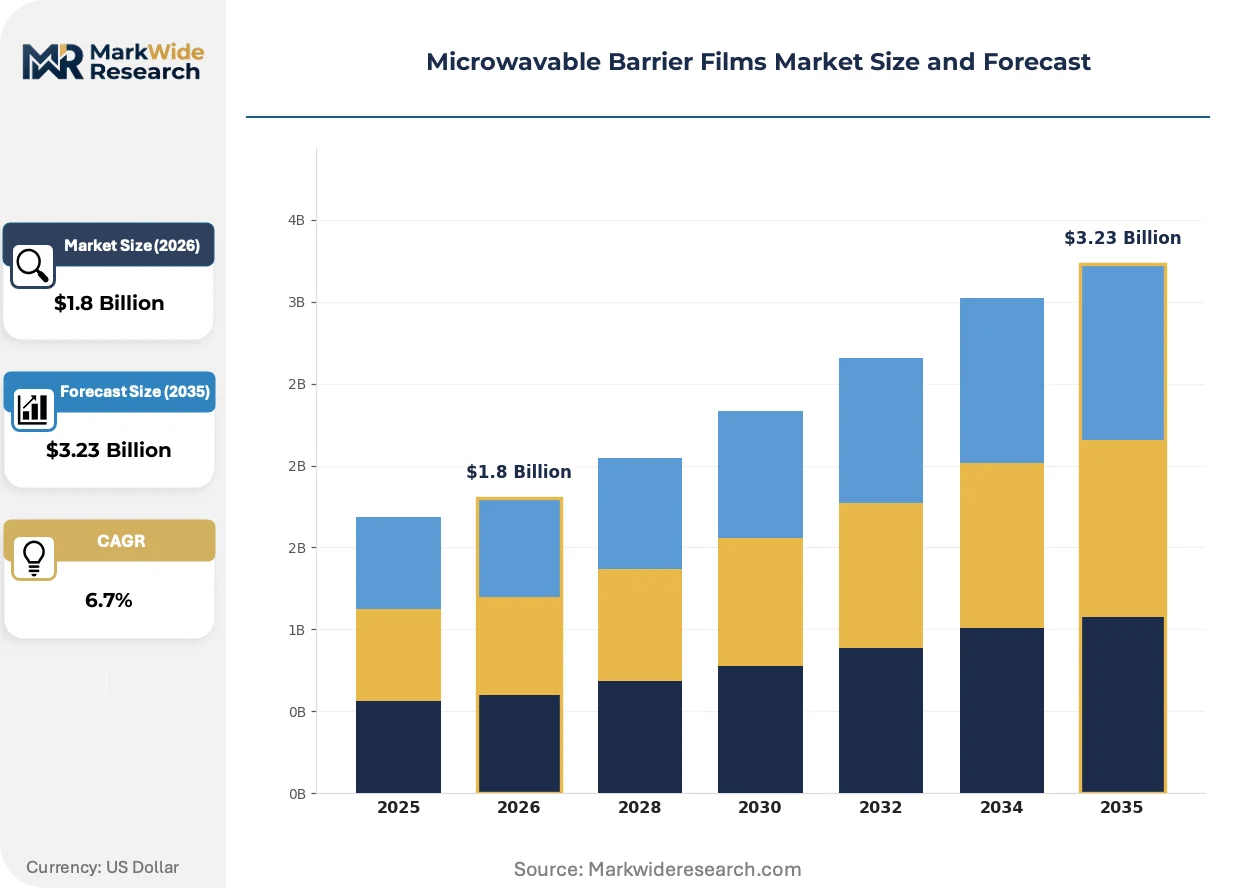
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Films, Rigid Films, Coated Films, Laminated Films End Use Industry: Food Packaging, Medical Packaging, Cosmetic Packaging, Industrial Packaging Material: Polyethylene, Polypropylene, Polyester, Polyamide Thickness: Thin Gauge, Medium Gauge, Heavy Gauge, Ultra-Thin |
| Companies Covered | Berry Global Inc, Amcor plc, Sealed Air Corporation, Toppan Printing Co., Ltd, Coveris, FlexFilms, Elite Packaging, KM Packaging Services Ltd., TCL Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microwavable Barrier Films Market Shifts & Advancements
Active barrier coating technologies and regulatory compliance automation are compressing product development cycles while reshaping competitive differentiation in microwaveable food packaging.
Plasma-enhanced chemical vapor deposition is automating the application of silicon oxide and aluminum oxide nanolayers onto polypropylene substrates. Frozen entree manufacturers in North America are qualifying these ceramic-coated films at accelerated rates. The technology is automating quality control throughput while reducing metallized film dependency in high-barrier applications.
REACH authorization procedures for chromium trioxide in metallized barrier manufacturing are tightening substance restrictions across EU converter operations. Industrial consequence includes accelerated migration toward vacuum-deposited aluminum alternatives and ceramic oxide coatings. Thermoformable lidding applications for extended shelf-life ready meals face the steepest reformulation timelines.
Retail chain private-label consolidation is compressing supplier qualification cycles and standardizing barrier specification sheets across frozen food categories. Smaller regional converters are losing access to centralized procurement panels as buyer concentration intensifies. German discount and premium retail banners are driving this specification harmonization most aggressively.
Microwavable Barrier Films Market Segmentation
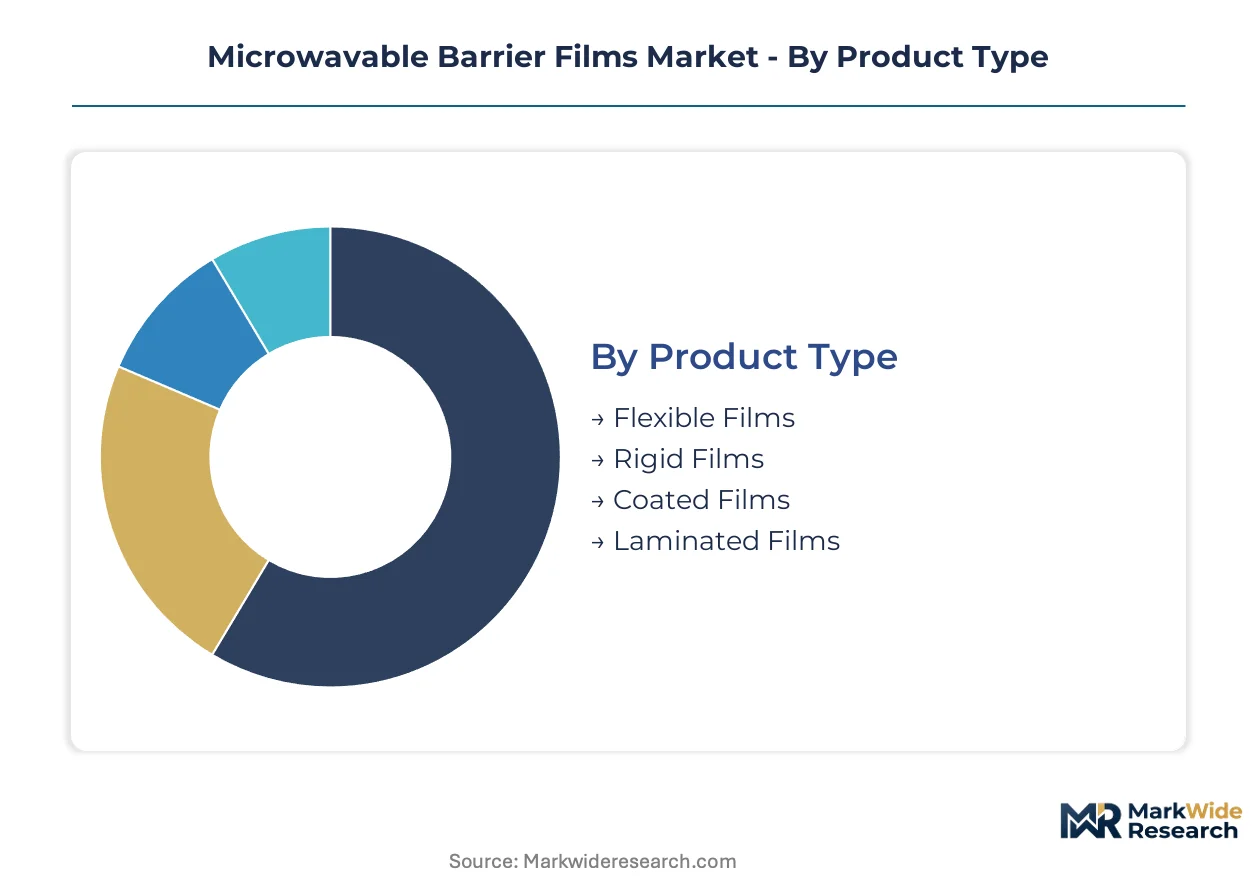
Segmentation in microwavable barrier films determines both manufacturing investment and procurement specifications. Buyers select structures based on thermal performance requirements, recyclability mandates, and automation compatibility with form-fill-seal lines.
Product Type:
Cost tier separates commodity converters from specialty barrier suppliers in this category.
- Laminated Films:Multi-layer constructions incorporating ethylene vinyl alcohol copolymers achieve sub-1 cc/m²/day oxygen transmission rates. German retail chains specify these structures for private-label frozen entree lines requiring extended shelf stability.
- Flexible Films:Single-serve pouch formats dominate foodservice procurement for healthcare and correctional feeding programs, with coextruded polyethylene structures capturing institutional volume.
- Coated Films:Silicon oxide and aluminum oxide nanolayers applied via plasma-enhanced chemical vapor deposition are displacing metallized alternatives in North American frozen entree qualification trials.
- Rigid Films:Thermoformable coextruded sheets serve premium protein vacuum-skin packaging where dimensional stability during microwave rethermalization is mandatory.
Flexible films lead volumes today; coated films are gaining share fastest.
End Use Industry:
Application maturity determines specification standardization versus custom development cycles.
- Food Packaging:Ready-to-eat meal producers drive demand for high-oxygen-barrier structures, with blown film line expansions in North America targeting retail-ready lidding formats for frozen entree brands.
- Medical Packaging:Sterile barrier requirements combine with microwave sterilization compatibility for field hospital nutrition products, creating dual-certification procurement criteria.
- Cosmetic Packaging:Microwaveable mask and treatment sachets represent a niche premium segment with limited standardization.
- Industrial Packaging:Chemical-resistant barrier films for microwave-curable adhesives and sealants occupy a specialized technical niche.
Food packaging dominates revenue concentration; medical packaging is expanding most quickly.
Material:
Supply concentration shapes converter sourcing strategies and geographic manufacturing footprints.
- Polyethylene:Blown film capacity expansions across North American producers target coextruded structures for retail chain private-label consolidation.
- Polypropylene:Ceramic oxide coating compatibility makes this substrate central to EU recyclability mandates, with German converters investing in plasma deposition line integration.
- Polyamide:High-temperature dimensional stability supports premium protein vacuum-skin applications where thermal stress exceeds 120°C.
- Polyester:Thermoformable lidding for extended shelf-life ready meals requires reformulation timelines accelerated by REACH chromium trioxide restrictions.
Polyethylene leads installed capacity; polypropylene is climbing the fastest.
Thickness:
Volume scale separates high-throughput commodity production from precision specialty manufacturing.
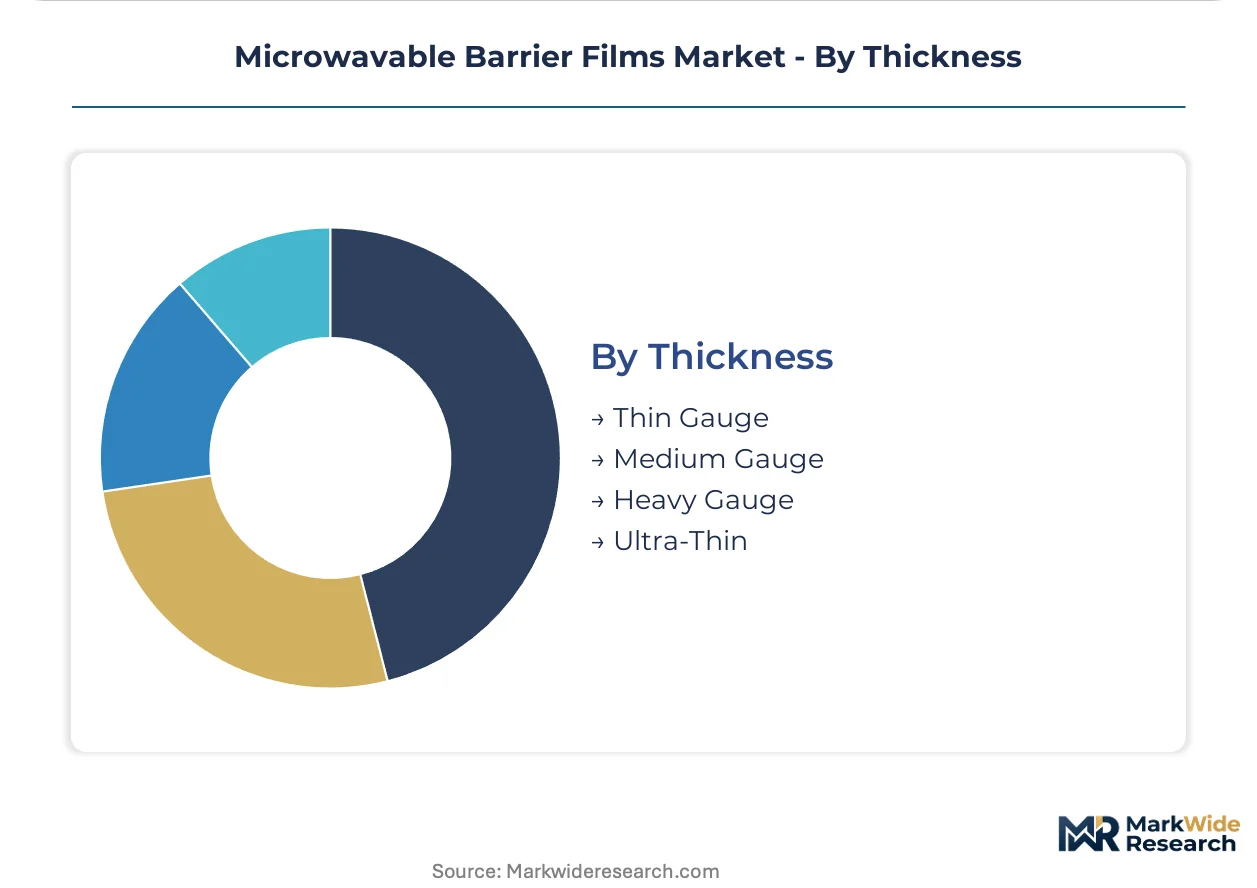
- Medium Gauge:Standard frozen entree lidding specifications balance barrier performance with material efficiency, capturing the largest procurement volumes from centralized retail chains.
- Thin Gauge:Single-serve institutional pouches minimize material cost per unit while maintaining oxygen barrier integrity for foodservice distribution.
- Heavy Gauge:Deep-draw thermoforming for premium protein trays requires structural rigidity during microwave rethermalization cycles.
- Ultra-Thin:Emerging cosmetic sachet formats test deposition technology limits for barrier uniformity at reduced caliper.
Medium gauge commands the largest volume position; thin gauge shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The microwavable barrier films industry traces its commercial scale to post-war United States food processing automation, with subsequent European and Asian industrialization creating distributed manufacturing footprints across Germany, Japan, and China.
United States
Frozen entree brands and ready-to-eat meal producers drive specification demand for high-oxygen-barrier blown film structures. FDA 21 CFR 177 governs indirect food contact substance compliance across converter operations. Midwest manufacturing clusters around Chicago and Minneapolis-St. Paul host blown film line expansions targeting retail chain private-label consolidation.
Germany
Centralized retail chains specify advanced oxygen-barrier requirements for private-label frozen food lines, concentrating procurement volume. EU Packaging and Packaging Waste Regulation mandates accelerate converter migration toward mono-material recyclable formats. The Rhine-Ruhr industrial corridor anchors plasma-enhanced chemical vapor deposition investment for ceramic oxide barrier integration.
Japan
Premium protein vacuum-skin packaging segments demand thermoformable coextruded sheets with dimensional stability above 120°C. METI enforces positive list compliance for imported packaging materials, elevating certification barriers for non-domestic suppliers. The Kanto region around Tokyo hosts barrier film qualification laboratories serving foodservice and healthcare channels.
China
Domestic frozen food processors scale pouch format adoption for single-serve institutional distribution. GB standards and SAMR oversight shape food contact material compliance frameworks. The Yangtze River Delta manufacturing belt concentrates coextruded polyethylene capacity expansion for regional food packaging converters.
Microwavable Barrier Films Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the microwavable barrier films value chain. The market structure consolidates around integrated polymer converters with captive resin sourcing and specialized coating equipment, while smaller regional processors serve fragmented local food packaging demand. Three archetypes dominate: multinational diversified packaging conglomerates, mid-cap film specialists with ceramic deposition expertise, and regional blown film converters serving institutional channels. Competitive dynamics center on capacity expansion in high-barrier coextrusion and strategic partnerships with retail chain procurement panels.
Among North American-based diversified packaging conglomerates, Berry Global Inc and Sealed Air Corporation exemplify scale-driven archetypes with integrated blown film and metallization capabilities. Amcor plc represents the multinational converter model with thermoformable coextrusion lines positioned for EU recyclability compliance. Japanese specialists Toppan Printing Co., Ltd occupy positions within precision deposition technology tiers, anchoring ceramic oxide barrier development for premium protein segments.
| Leading Market Players |
|---|
| Berry Global Inc |
| Amcor plc |
| Sealed Air Corporation |
| Toppan Printing Co., Ltd |
| Coveris |
| FlexFilms |
| Elite Packaging |
| KM Packaging Services Ltd. |
| TCL Packaging |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up film specialists in North America and Europe have consolidated regional blown film capacity, tightening supply discipline while anchoring contract pricing to EVOH resin cost pass-through mechanisms. This ownership pattern concentrates pricing power among processors with captive metallization lines, forcing smaller converters toward spot-market polyethylene sourcing with compressed margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ceramic-coated barrier films from metallized alternatives from commodity coextruded structures. Price differentiation rests on oxygen transmission rate certification and volume commitment scale, with German retail chains least sensitive due to specification mandates while institutional foodservice buyers drive cost compression in thin-gauge pouch formats. Pricing pressure stems from Asian EVOH supply concentration and freight volatility, squeezing mid-tier converters without backward integration into resin sourcing.
Supply Chain Analysis
Polymer scientist and plasma deposition technician shortages in Germany's Rhine-Ruhr corridor and the US Midwest constrain capacity expansion timelines for ceramic barrier lines. Manufacturing concentrates in Germany, the United States, and China, with converters drawing from Asian EVOH resin, domestic polyethylene, and vacuum deposition equipment imports. Single-source vulnerability runs through Japanese and Korean metallization equipment suppliers. Distribution feeds through centralized retail procurement panels and foodservice distribution cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microwavable barrier films constitute a late-cycle quality story as EU recyclability mandates and North American retail consolidation concentrate procurement among converters with certified mono-material capabilities. Demand is shifting toward premium ceramic-coated specifications that command sustained margin premiums over metallized alternatives.
For Market Incumbents: Acquire plasma-enhanced chemical vapor deposition equipment lines to secure ceramic barrier capacity ahead of REACH chromium trioxide restrictions. Consolidate regional blown film competitors in the US Midwest to anchor polyethylene supply cost positions against EVOH volatility. Defensive priority centers on locking German retail chain qualification status before specification harmonization closes supplier panels. For New Entrants and Emerging Players: Smaller regional foodservice distributors represent the most penetrable buyer archetype as centralized retail procurement excludes non-integrated converters. Target single-serve institutional pouch formats for healthcare and correctional feeding programs where specification flexibility persists. Go-to-market angle emphasizes rapid custom development cycles and localized coextrusion service against multinational lead times. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap film specialists with ceramic deposition expertise but incomplete retail chain certification coverage. Long-term viability favors converters with demonstrated EU mono-material compliance and North American blown film integration. Signal to watch is German discount retailer private-label award announcements as inflection points for volume concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Barrier Capacity Expansion | Plasma deposition line investment captures share as REACH restricts chromium trioxide in metallized films. |
| Mono-Material Certification Investment | EU Packaging and Packaging Waste Regulation compliance secures access to German retail procurement panels. |
| Backward Integration into EVOH Sourcing | Captive resin supply hedges Asian production concentration and freight cost volatility. |
| Foodservice Channel Partnership | Institutional feeding program contracts provide volume stability amid retail consolidation. |
| Thermoformable Coextrusion Convergence | Integration with form-fill-seal automation opens premium protein vacuum-skin packaging segments. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's converter operations and downstream procurement channels. Primary interviews combined film extrusion plant managers, retail chain packaging specification directors, foodservice distribution procurement leads, and polymer R&D directors with secondary validation from customs trade data, FDA 21 CFR 177 filings, EU REACH authorization registers, and SEC 10-K disclosures from listed packaging conglomerates. Bottom-up capacity and demand modeling triangulated against top-down market sizing from trade association aggregates.
Rate-of-change decomposition separated volume growth from value mix shift across the projection horizon. Segmentation dimensions modeled include product type, material substrate, end-use industry, thickness gauge, and geographic regulatory cluster. CAGRs derived from layered growth accounting across installed capacity expansion, specification upgrade trajectories, and substitution elasticities between metallized and ceramic barrier technologies. Forecast inputs incorporated EU member state extended producer responsibility implementation schedules and North American retail private-label consolidation timelines.
Underlying measurement precision varies by segment; laminated films and German retail channel demand carry tighter precision than emerging coated film formats and Asian institutional foodservice adoption. Forecasts reflect assumptions around regulatory implementation pace, resin supply continuity, and equipment lead time stability. Material deviation in EU packaging fee modulation schedules, Asian EVOH supply disruptions, or German retail merger activity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
Global Silicone Release Liner Market
Packaging Barrier Films
Perforated Packaging Film Market
Packaging Barrier Films
Special Effects Laminate Films Market
Packaging Barrier Films
High Barrier Lidding Film Market
Packaging Barrier Films
Global Shrink Films Market
Packaging Barrier Films
Biobased Anti-Blocking Agents for Flexible Packaging Films Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Collation Shrink Films Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market