
 Decorative Films and Foils Market | 2026-2036
Decorative Films and Foils Market Size, Share, and Industry Trends Forecast 2026-2036
Decorative Films and Foils Market Outlook
Digital printing and laser-etching compatibility is reshaping how decorative films integrate into mass-customization workflows. Avery Dennison Corporation leverages its adhesive science portfolio to sustain leadership in architectural and automotive channels. Eastman Chemical Company anchors high-performance PET and polyester substrate supply for premium window film tiers. 3M Company differentiates through optical clarity patents and channel control in consumer electronics finishing.
Decorative films and foils are thin-gauge polymer substrates—typically 12–250 micrometers in polyester, PVC, or polycarbonate—engineered with pressure-sensitive adhesives, release liners, and surface coatings for bonding to rigid or flexible surfaces in automotive, furniture, and electronics applications. Window films and adhesive films command the largest volume pools, with vinyl wraps representing the fastest-expanding segment as vehicle personalization and fleet branding demand accelerates. Architectural design applications concentrate margin in anti-reflective and energy-control coatings, while furniture and consumer electronics segments compete on color-matching precision and scratch-resistance specifications.
EPA regulates VOC emissions from adhesive formulations under Clean Air Act standards, while REACH restricts phthalate plasticizers in PVC decorative foils across Europe. FDA maintains indirect food-contact limits for films used in retail display and packaging-adjacent consumer goods applications. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as PFAS-free coating transitions threaten incumbent supply chains and create qualification windows for reformulated product lines.
Market Dynamics
Automotive OEMs are consolidating interior surface finishing specifications around pressure-sensitive adhesive films, compressing traditional paint-and-trim supply chains while forcing tier-1 suppliers to qualify film-based alternatives at vehicle-platform scale.
Growth Catalysts
- REACH phthalate restrictions:European PVC reformulation mandates are accelerating PET and TPU substrate adoption, opening qualification windows for non-plasticized film suppliers.
- Automotive interior customization programs:OEMs in Germany and the United States are expanding build-to-order surface finishing options, pulling film volume into final assembly lines.
- Laser-etching compatibility:Digital surface patterning technologies are enabling mass-customization workflows without retooling costs, penetrating furniture and consumer electronics channels.
Market Restraints
- Petrochemical feedstock volatility:Polyester and polycarbonate resin prices track crude oil and purified terephthalic acid spot markets, compressing converter margins during upstream spikes.
- Solvent-based formulation dependence:High-performance pressure-sensitive adhesives still rely on toluene and xylene carriers, exposing producers to EPA Clean Air Act enforcement and state-level VOC caps.
- China supply concentration:Appliance and electronics-grade decorative foil substrate production clusters in Zhejiang and Guangdong provinces, creating single-source vulnerability for European and North American laminators.
Strategic Opportunities
- PFAS-free coating transitions:ECHA restrictions on per- and polyfluoroalkyl substances are forcing incumbent fluoropolymer coaters to reformulate, creating first-mover advantage for silicone and ceramic-based alternatives.
- Fleet branding acceleration:Commercial vehicle wrap demand is outpacing consumer personalization in the United States, pulling volume toward wider-format vinyl and cast film grades.
- Energy-control architectural films:Anti-reflective and solar-control coatings are penetrating commercial glazing retrofits in Singapore and Australia, where building energy codes mandate thermal performance upgrades.
Industry Challenges
- Adhesive formulation chemist scarcity:Solvent-to-waterborne transition expertise concentrates at legacy tape and label converters, limiting new entrant scale-up speed.
- Dual-certification timelines:Films destined for automotive and food-adjacent retail display must simultaneously satisfy FDA indirect food-contact limits and OEM interior emissions protocols, extending qualification cycles.
- Release liner waste regulations:German and French packaging waste directives are forcing converters to collect and recycle silicone-coated paper liners, adding logistics cost without material recovery value.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decorative Films and Foils Market |
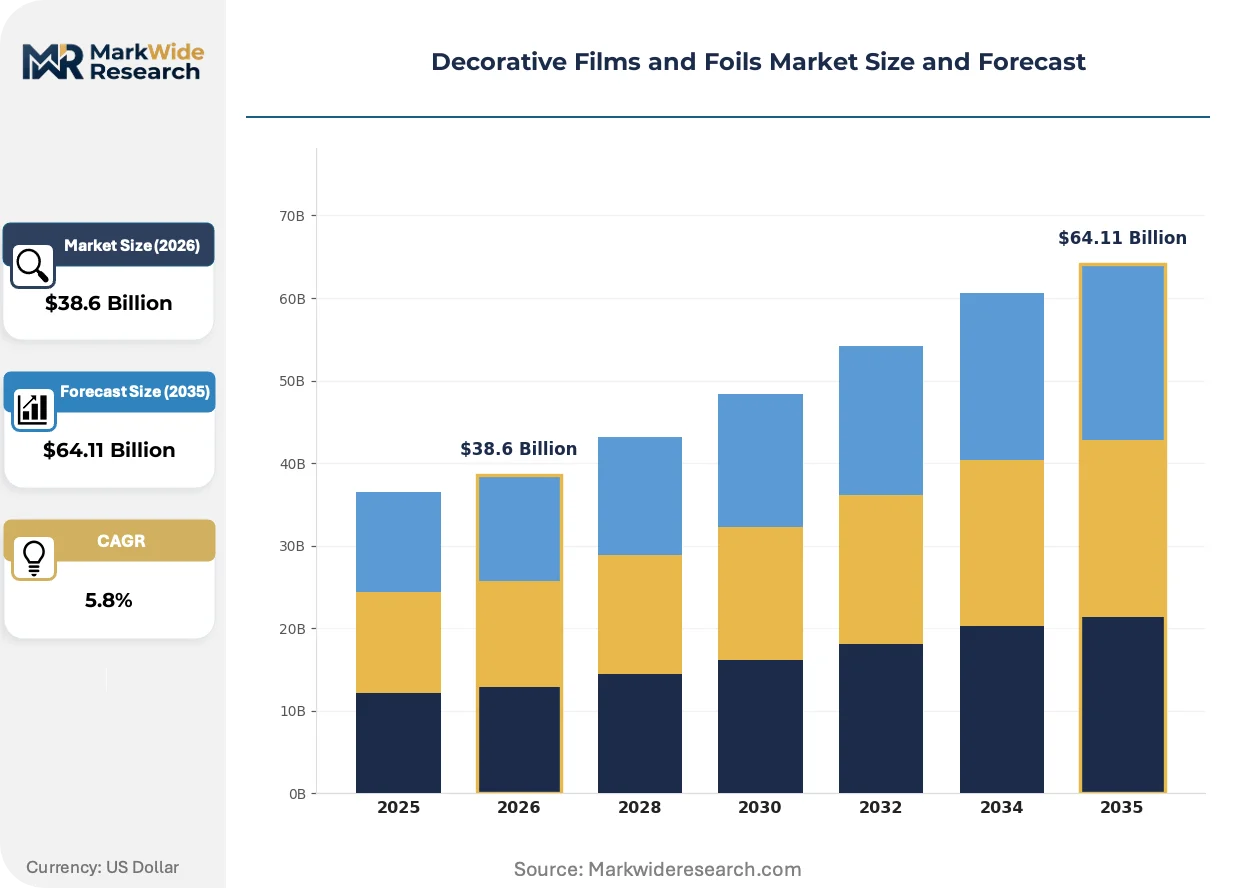
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Window Films, Adhesive Films, Vinyl Wraps, Decorative Foils Application: Automotive Interiors, Architectural Design, Consumer Electronics, Furniture Material: Polyester, Polycarbonate, PVC, PET End User: Retail, Construction, Automotive, Consumer Goods |
| Companies Covered | LG Hausys, Avery Dennison Corporation, Eastman Chemical Company, OMNOVA Solutions, Klöckner Pentaplast, 3M Company, RENOLIT, Madico, LINTEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decorative Films and Foils Market Strategic Shifts
Digital production workflows and regulatory chemistry shifts are fragmenting traditional film specification hierarchies, enabling smaller converters to compete on customization velocity rather than volume scale.
Thin-film digital printing systems are virtualizing traditional gravure and screen-printing infrastructure. Automotive trim suppliers in Stuttgart and Detroit are adopting UV-curable inkjet lines for prototype and short-run interior finishes. This technology is virtualizing the economics of mass customization, collapsing minimum order quantities from thousands of linear meters to hundreds without cylinder engraving costs.
EPA's evolving VOC thresholds under Clean Air Act standards are tightening solvent-based adhesive formulations across the United States. Converter operations in Ohio and Michigan face state implementation plan enforcement that limits toluene storage and recovery system specifications. Architectural film segments are responding fastest, shifting specification sheets toward waterborne acrylic and UV-curable pressure-sensitive platforms ahead of automotive qualification.
Fleet procurement departments are consolidating vehicle wrap sourcing through national account structures, bypassing traditional sign-shop distribution. Logistics and last-mile delivery operators in Texas and California are specifying color-matched vinyl across thousands of vehicles, compressing the specification cycle from months to weeks. This concentration is most visible in commercial vehicle channels, where procurement teams now demand direct converter relationships with color-matching laboratories and same-day sample turnaround.
Decorative Films and Foils Market Segmentation
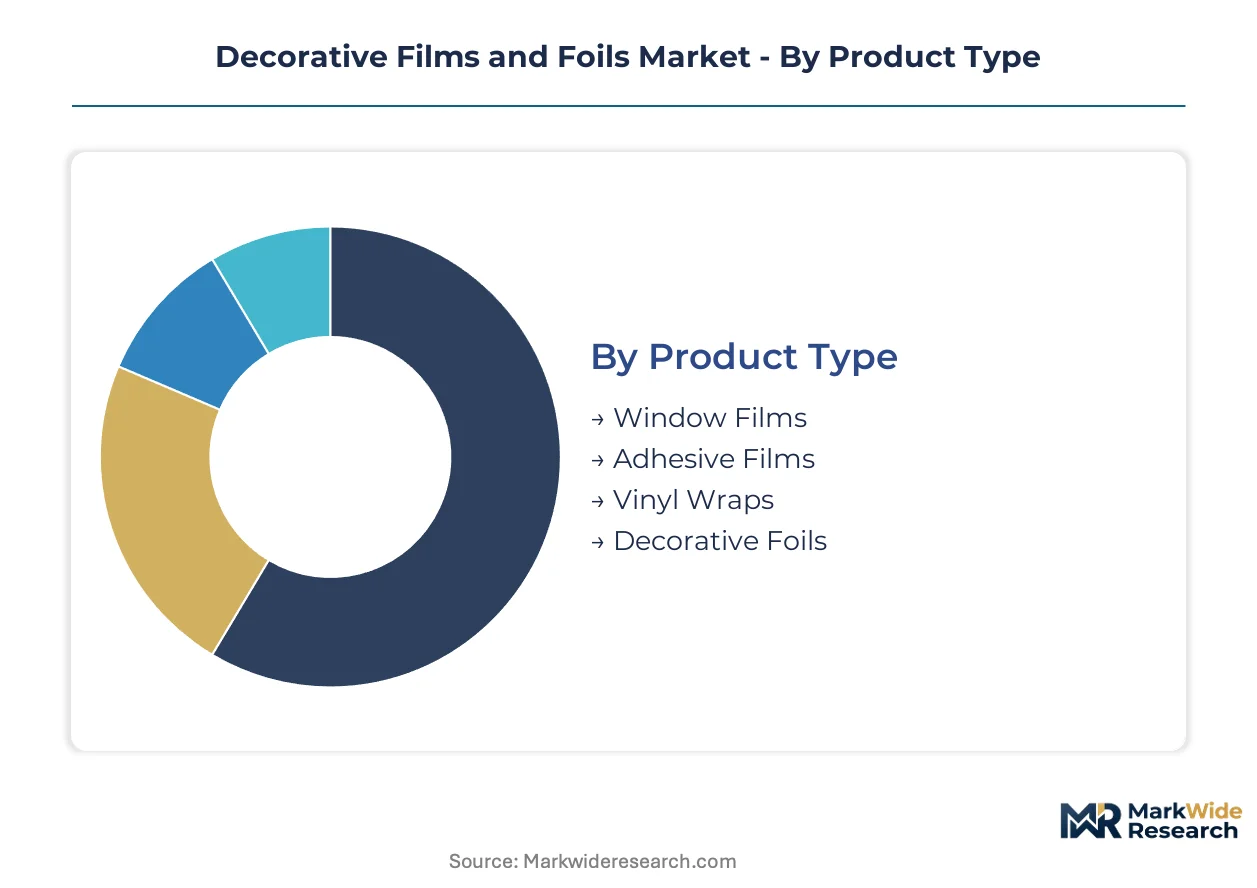
Segmentation in decorative films and foils reveals how substrate chemistry, bonding technology, and surface engineering specifications diverge across end-use durability requirements. Manufacturers configure production lines around these divides because automotive interior films demand OEM qualification protocols that consumer electronics finishing simply does not require.
Product Type:
Mature pressure-sensitive adhesive platforms dominate volume, while emerging cast-film and digital-print-compatible grades reshape specification hierarchies.
- Window Films:Multi-layer PET or polyester constructions with sputtered metal or ceramic coatings for solar control and shatter resistance. Demand concentrates in Singapore and Australia commercial glazing retrofits, where building energy codes mandate thermal performance upgrades and anti-reflective specifications.
- Adhesive Films:Pressure-sensitive laminates with solvent-based or waterborne acrylic adhesives, release liners, and topcoats for bonding to rigid substrates. Automotive OEMs in Germany and the United States are pulling these films into final assembly lines for interior surface finishing, compressing traditional paint-and-trim supply chains.
- Vinyl Wraps:Calendered or cast PVC and TPU films for vehicle personalization and fleet branding. Logistics operators in Texas and California specify color-matched vinyl across thousands of vehicles, compressing procurement cycles from months to weeks.
- Decorative Foils:Thin-gauge polymer substrates with printed or embossed surface patterns for furniture and appliance finishing. Appliance manufacturers in Zhejiang and Guangdong provinces source these foils at scale for surface finishing operations.
Adhesive Films retain volume leadership; Vinyl Wraps hold the steepest expansion curve.
Application:
Cost-tier stratification separates specification-intensive automotive and electronics channels from price-sensitive furniture and mass architectural segments.
- Automotive Interiors:Pressure-sensitive films for dashboard, door panel, and trim finishing with OEM emissions and scratch-resistance protocols. Build-to-order customization programs in Stuttgart and Detroit are expanding film-based surface options at vehicle-platform scale.
- Architectural Design:Solar-control, anti-reflective, and decorative glazing films for commercial and residential buildings. Energy-control coatings are penetrating Singapore and Australia retrofits where thermal performance upgrades are code-mandated.
- Consumer Electronics:Optical-grade films with precision color-matching and scratch-resistance for device finishing. Laser-etching compatibility is enabling mass-customization workflows without retooling costs in electronics manufacturing.
- Furniture:Decorative foils and edgebanding films for panel and component surfacing with abrasion and moisture resistance. Digital printing systems are virtualizing traditional gravure infrastructure, collapsing minimum order quantities for furniture producers.
Automotive Interiors command specification premiums; Consumer Electronics shows the fastest technology turnover.
Material:
Supply concentration in purified terephthalic acid and petrochemical feedstocks creates margin volatility that favors integrated resin producers.
- Polyester:PET and copolyester films with dimensional stability and optical clarity for window and electronics applications. Eastman Chemical Company anchors high-performance substrate supply for premium window film tiers.
- Polycarbonate:High-impact, thermoformable films for automotive interior components requiring deep-drawing and heat resistance. REACH phthalate restrictions are accelerating adoption as PVC alternatives in European automotive programs.
- PVC:Plasticized vinyl films for cost-sensitive wrapping and decorative applications with established printability. ECHA restrictions on phthalate plasticizers are forcing reformulation across European supply chains.
- PET:Biaxially oriented polyester with superior tensile strength and chemical resistance for adhesive film carriers and release liners. Feedstock prices track crude oil spot markets, compressing converter margins during upstream spikes.
PET retains substrate volume leadership; Polycarbonate gains share fastest on regulatory displacement.
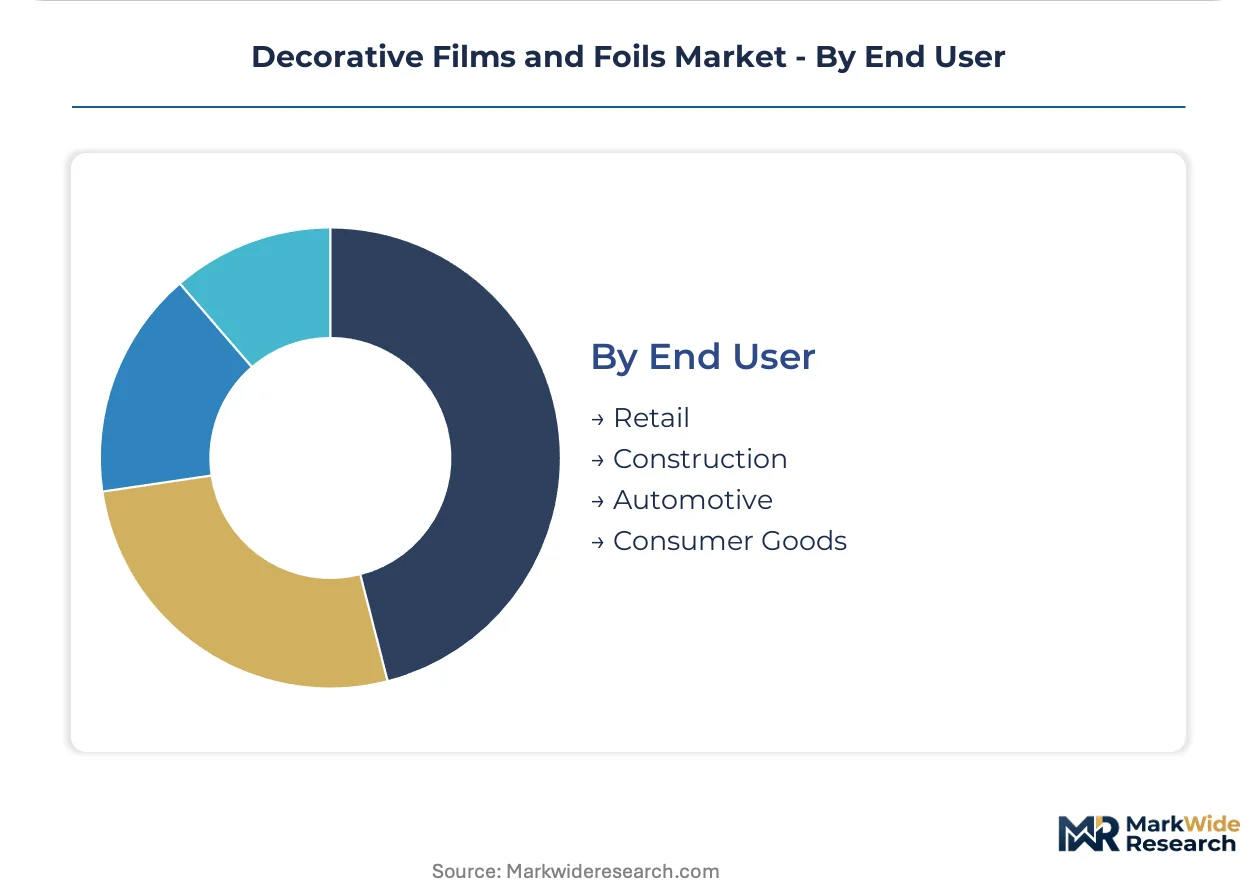
End User:
Customer-type fragmentation separates national fleet procurement structures from fragmented sign-shop distribution and retail specification.
- Retail:Films for point-of-sale displays, fixture finishing, and packaging-adjacent applications with FDA indirect food-contact compliance requirements. Dual-certification timelines extend qualification cycles for films serving both retail display and automotive channels.
- Construction:Architectural window films and decorative surfacing for commercial glazing and interior fit-out. Building energy codes in Singapore and Australia mandate thermal performance upgrades that pull solar-control film volume.
- Automotive:OEM and aftermarket films for interior finishing, vehicle wrapping, and protective applications with emissions and durability protocols. Fleet procurement departments are consolidating wrap sourcing through national account structures, bypassing traditional distribution.
- Consumer Goods:Electronics, appliance, and furniture manufacturers sourcing decorative foils and films for product finishing. Appliance and electronics-grade substrate production clusters in Chinese provinces create single-source vulnerability for European and North American laminators.
Automotive commands the highest specification barriers; Construction shows the steepest regulatory-driven expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese decorative foil substrate producers in Zhejiang and Guangdong provinces supply laminators across Germany, the United States, and Japan, creating a trade-flow corridor where Asian manufacturing feeds Western automotive and electronics finishing demand.
United States
Fleet branding procurement from logistics operators in Texas and California compresses vinyl wrap specification cycles from months to weeks. EPA Clean Air Act enforcement in Ohio and Michigan limits toluene storage for solvent-based adhesive converters. Detroit automotive trim suppliers adopt UV-curable inkjet lines for prototype interior finishes.
Germany
Stuttgart OEMs expand build-to-order interior surface finishing programs at vehicle-platform scale. REACH phthalate restrictions accelerate PET and TPU substrate adoption across European automotive supply chains. Bavarian film converters face German packaging waste directives mandating silicone-coated paper liner collection and recycling.
China
Appliance and electronics manufacturers in Zhejiang and Guangdong provinces source decorative foils for surface finishing at industrial scale. MEE enforcement of dual carbon goals pressures petrochemical feedstock costs for polyester resin production. Shanghai and Shenzhen electronics finishing clusters drive laser-etching compatible film qualification.
Japan
Precision electronics manufacturers in Kansai and Chubu regions demand optical-grade films with scratch-resistance specifications. METI industrial standards shape pressure-sensitive adhesive performance benchmarks for consumer device finishing. Nagoya automotive suppliers integrate film-based trim alternatives into platform-scale production.
Australia
Commercial glazing retrofits in Sydney and Melbourne pull solar-control and anti-reflective architectural film volume. Building energy codes mandate thermal performance upgrades that accelerate energy-control coating penetration. Local distributors source premium window film tiers from integrated polyester substrate producers.
Decorative Films and Foils Market Competitive Environment
Channel-controlling players compete with product-specialist players across specification tiers. The market structure consolidates around adhesive science portfolios and substrate supply integration, with tier-1 automotive qualification creating entry barriers for unproven converters. Three archetypes dominate: integrated resin-to-film producers, adhesive-specialist laminators, and regional wrap-fabrication distributors. Competitive moves concentrate on PFAS-free coating reformulation and fleet-procurement direct relationships that bypass traditional sign-shop channels.
Among integrated chemical producers, Eastman Chemical Company and 3M Company exemplify substrate-to-film control archetypes. Avery Dennison Corporation occupies a position within the adhesive-specialist tier. These three entities represent divergent strategic positions: chemical integration versus adhesive science specialization versus optical clarity patent portfolios. Their collective presence shapes how qualification protocols, VOC compliance pathways, and digital-print compatibility standards propagate through automotive, architectural, and electronics channels.
| Leading Market Players |
|---|
| LG Hausys |
| Avery Dennison Corporation |
| Eastman Chemical Company |
| OMNOVA Solutions |
| Klöckner Pentaplast |
| 3M Company |
| RENOLIT |
| Madico |
| LINTEC Corporation |
| Others |
Value Chain & Pricing Dynamics
Zhejiang and Guangdong substrate producers anchor global decorative foil supply, concentrating margin capture in polyester resin conversion while European and North American laminators absorb feedstock volatility through inventory buffers and contract hedging.
Pricing Analysis
Solvent-based adhesive formulations carry a 15-20% premium over waterborne equivalents due to performance durability, while next-generation UV-curable platforms command OEM qualification premiums before volume scale. Three-tier pricing structure across premium optical-grade, standard industrial-grade, and economy calendered vinyl separates specification-intensive automotive channels from price-sensitive furniture segments. Cost compression in economy vinyl wraps is intensifying because logistics fleet procurement departments consolidate national accounts and squeeze converter margins. Consumer electronics finishing shows the least price sensitivity due to color-matching precision requirements, while mass architectural glazing remains the most price-elastic segment.
Supply Chain Analysis
Extended payment terms from automotive OEMs in Stuttgart and Detroit now stretch to 90-120 days, forcing mid-tier converters to rely on supply-chain finance facilities backed by resin producers. Geographic concentration centers on China for polyester substrate, Germany for polycarbonate film extrusion, and the United States for pressure-sensitive adhesive coating. Raw material dependencies include purified terephthalic acid from petrochemical complexes, plasticizer formulations facing REACH restrictions, and ceramic nanoparticles for solar-control coatings. Single-source vulnerability in Zhejiang decorative foil production creates systemic risk for European appliance manufacturers. Distribution runs through national fleet procurement structures that bypass traditional sign-shop channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive production cycles and petrochemical feedstock cost waves position decorative films and foils in early-stage recovery, with OEM interior customization programs providing the cyclical lift.
For Market Incumbents: Entrench adhesive formulation expertise by acquiring solvent-to-waterborne transition chemists from legacy tape converters, while locking multi-year PET supply agreements with Eastman Chemical Company before feedstock volatility returns. PFAS-free coating mandates from ECHA threaten fluoropolymer-based product lines; accelerate silicone and ceramic alternative qualification to defend specification position in European automotive channels. For New Entrants and Emerging Players: Mid-market commercial glazing retrofits in Singapore and Australia represent the most penetrable entry point, as building energy code mandates create demand without incumbent lock-in. Fleet branding procurement departments in Texas and California offer direct converter relationships that bypass traditional sign-shop distribution. Target UV-curable inkjet-compatible film grades for prototype and short-run automotive interior finishing in Detroit and Stuttgart. For Investors and Strategic Acquirers: Capital is best deployed toward adhesive-specialist laminators with active PFAS-free reformulation programs and established automotive qualification protocols. Long-term viability over a multi-year horizon hinges on regulatory chemistry transitions rather than volume scale. The signal to watch is ECHA enforcement intensity on per- and polyfluoroalkyl substance restrictions, which would accelerate incumbent displacement and create acquisition windows for reformulated product lines.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Reformulation | ECHA restrictions on fluoropolymers force silicone and ceramic alternative qualification ahead of enforcement deadlines. |
| Fleet Procurement Direct Relationships | Logistics operators in Texas and California now consolidate vinyl wrap sourcing through national account structures. |
| UV-Curable Inkjet Line Adoption | Automotive trim suppliers in Stuttgart deploy digital printing to collapse prototype minimum order quantities. |
| Backward Integration into PET Substrate | Converters secure purified terephthalic acid supply agreements to buffer margin against crude oil volatility. |
| Laser-Etching Compatibility Investment | Consumer electronics manufacturers in Shenzhen demand mass-customization workflows without retooling costs. |
Study Parameters
The analysis maps window films, adhesive films, vinyl wraps, and decorative foils, each validated through procurement managers at automotive OEMs, technical directors at film converters, regulatory affairs leads at chemical suppliers, and category buyers at appliance manufacturers. Primary interviews triangulated against secondary sources including EPA Clean Air Act enforcement records, ECHA restriction dossiers, SEC filings from integrated resin producers, and customs data on polyester substrate trade flows. Bottom-up volume estimates from end-use consumption patterns reconciled with top-down petrochemical feedstock demand models.
Assumptions held fixed include REACH phthalate restriction timelines, EPA VOC threshold evolution, and dual carbon goal enforcement intensity in China; variables tested across scenarios included crude oil price bands and automotive production recovery rates. Segmentation dimensions modeled encompass substrate chemistry, bonding technology, surface engineering specification, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to qualified volume estimates, with cross-validation against adhesive formulation capacity expansion announcements and OEM interior customization program rollouts.
Macroeconomic conditions sit as an overlay; deviation in crude oil spot prices, automotive platform launch schedules, or ECHA enforcement cadence would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation timelines and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Global Metalized Barrier Films Market
Packaging Barrier Films
Cling Films Market
Packaging Barrier Films
Perforated Packaging Market
Packaging Barrier Films
Transport Protection Film Market
Packaging Barrier Films
Bio-Based Sealant Films Market
Packaging Barrier Films
Bonding Films Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
PET Release Liner Market
Packaging Barrier Films
Transparent Barrier Films Market
Packaging Barrier Films
Release Liners Market
Packaging Barrier Films
USA Stretch Hood Films Market
Packaging Barrier Films
Perforated Packaging Film Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Barrier Shrink Films Market