
 Waterproof Packaging Market | 2026-2036
Waterproof Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Waterproof Packaging Market Analytics
Asian flexible film production is hardening as regional converters expand blown-film extrusion lines for barrier-grade polyethylene. Amcor leverages integrated resin-to-film operations across Southeast Asian plants to sustain cost leadership in pouch formats. Sealed Air Corporation anchors North American demand through automated bagging systems tied to e-commerce fulfillment networks. Mondi Group competes with kraft-paper-based waterproof alternatives that target brand owners seeking fiber-primary packaging.
Waterproof packaging denotes engineered enclosures—typically multilayer films, coated papers, or sealed rigid structures—designed to maintain internal dryness under specified hydrostatic pressure or humidity exposure, measured by water-vapor transmission rate and Mullen burst thresholds. These systems protect moisture-sensitive goods through transit, storage, and retail display across pharmaceutical, electronics, and food supply chains. Polyethylene films dominate volume due to cost-efficient extrusion and heat-seal compatibility, though polypropylene pouches capture premium margin pools in pharmaceutical serialization applications where clarity and barrier performance command price premiums. Paper-based waterproof boxes remain niche but grow in European retail channels where fiber-based claims influence shelf positioning.
The FDA enforces moisture-barrier standards for pharmaceutical primary packaging under USP <671>, directly shaping film specification requirements for drug stability. EMA's Annex 1 revision on sterile manufacturing extends contamination-control logic to outer transit packaging, tightening waterproofing documentation for cross-border shipments. China's SAMR implements GB standards for food-contact plastics that include migration limits affecting multilayer film construction. Stakeholders must monitor regulatory divergence between recyclability mandates and barrier-performance requirements, as compliance in one jurisdiction increasingly conflicts with circular-economy targets in another.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing a structural pivot in multilayer film design, as recyclability mandates collide with barrier-performance requirements inherited from pharmaceutical cold-chain protocols.
Growth Catalysts
- Pharmaceutical serialization mandates:EMA's Annex 1 revision on sterile manufacturing extends contamination-control documentation to outer transit packaging, accelerating demand for certified moisture barriers in cross-border drug shipments.
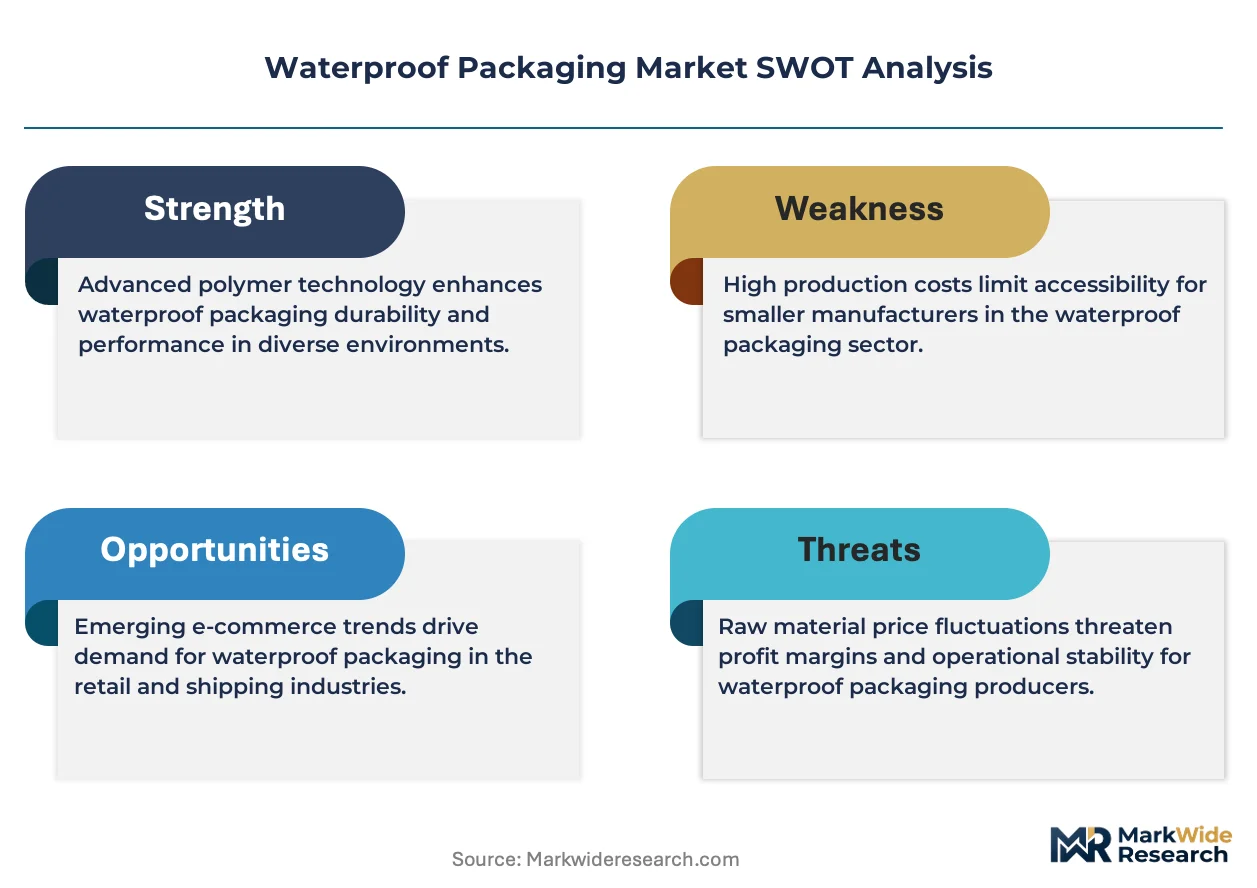
- Blown-film extrusion expansion:Regional converters across Southeast Asia are hardening flexible film production capacity, lowering unit costs for barrier-grade polyethylene pouches serving e-commerce fulfillment networks.
- Automotive component protection standards:German automotive exporters require certified moisture protection for precision electronics, concentrating specification authority with Tier 1 suppliers specifying MIL-PRF-131K compliant materials.
Market Restraints
- Resin cost volatility:Ethylene feedstock price swings compress converter margins on polyethylene film contracts, forcing quarterly price renegotiation clauses that destabilize long-term supply agreements.
- Multilayer recyclability friction:The EU Green Deal's circular-economy targets conflict with current adhesive lamination chemistries, creating compliance dead-ends for existing barrier film architectures.
- Paper-based substitution threat:Mondi Group's kraft-paper waterproof alternatives capture brand owners seeking fiber-primary packaging claims, pressuring synthetic film share in European retail channels.
Strategic Opportunities
- Indian pharmaceutical export corridors:CDSCO's alignment with ICH stability guidelines creates demand for USP <671>-compliant barrier films in Mumbai-Ahmedabad cold-chain hubs serving African and Latin American markets.
- Mono-material barrier innovation:Convergence of metallocene catalyst technology and machine-direction orientation lines enables polyethylene-only structures that satisfy both MVTR targets and single-stream recyclability.
- Automated bagging system integration:Sealed Air Corporation's North American e-commerce fulfillment networks create specification pull-through for pre-qualified pouch formats that reduce line changeover downtime.
Industry Challenges
- Migration testing timeline compression:China's SAMR GB standards for food-contact plastics require extended extraction studies that delay new multilayer film launches by 8-14 months.
- Adhesive lamination skill scarcity:Solventless polyurethane bonding expertise concentrates among aging technicians in German and Japanese converter operations, constraining quality consistency at greenfield Southeast Asian plants.
- Legacy heat-seal line retrofit costs:Pharmaceutical pouch converters face seven-figure capex burdens to upgrade impulse sealing stations for new mono-material structures with narrower processing windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterproof Packaging Market |
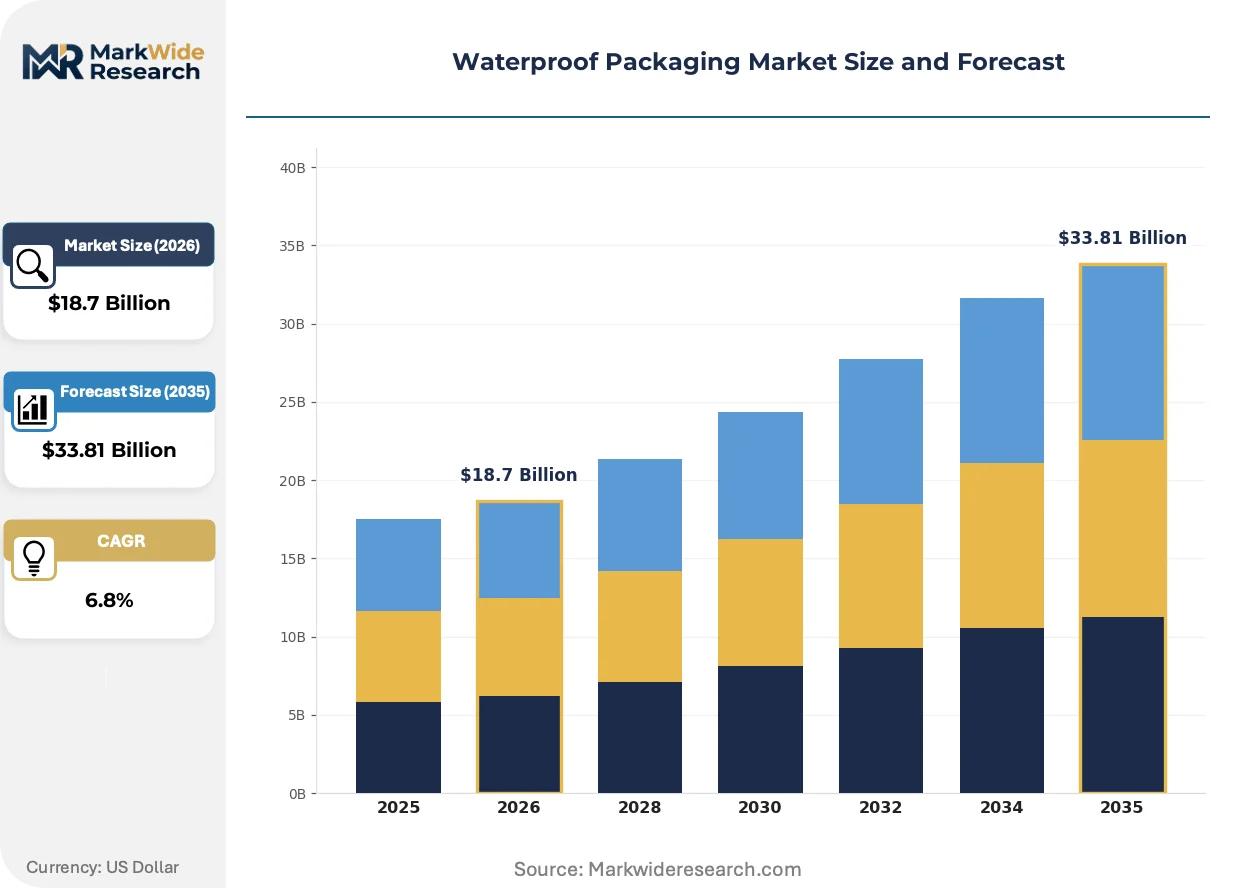
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polyethylene, Polypropylene, PVC, Paper Product Type: Bags, Boxes, Pouches, Films End User: Food & Beverage, Pharmaceuticals, Electronics, Cosmetics Application: Catering, Retail, Export, Storage |
| Companies Covered | Amcor, Sealed Air Corporation, Mondi Group, Smurfit Kappa, Berry Global, Sonoco Products, Constantia Flexibles, WestRock, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterproof Packaging Market Evolving Landscape
Barrier-grade film chemistry is absorbing sustainability pressures that previously favored rigid alternatives, while regulatory divergence between jurisdictions fragments specification standards.
Metallocene-grade polyethylene films with enhanced crystallinity are absorbing moisture-barrier functions previously reserved for ethylene-vinyl alcohol copolymers. Pharmaceutical contract packagers in Germany and Switzerland are adopting these structures at pilot scale for non-critical drug stability applications. The technology is absorbing cost premiums from EVOH-dependent architectures while complicating heat-seal parameter windows.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer coatings from food-contact waterproof papers across EU member states. Coated paper converters are pivoting to bio-based wax emulsions and plasma-deposited silica barriers that meet grease-resistance without PFAS chemistry. Premium chocolate and confectionery brands in Belgium and the Netherlands are absorbing 12-18% material cost increases to maintain shelf-appeal claims.
Serialization-driven procurement consolidation is compressing supplier rosters among pharmaceutical primary packaging buyers. Large molecule drug manufacturers are mandating integrated film-to-pouch qualification packages that disqualify standalone resin or film vendors. This concentration is most visible in Massachusetts and North Carolina biotech clusters, where three-converter approved-vendor lists have displaced open specification bidding.
Waterproof Packaging Market Segmentation
Waterproof packaging procurement splits across material chemistry, product format, and end-use compliance requirements. Buyers prioritize barrier performance against total cost of ownership, with regulatory mandates fragmenting specification standards across pharmaceutical and food-contact applications.
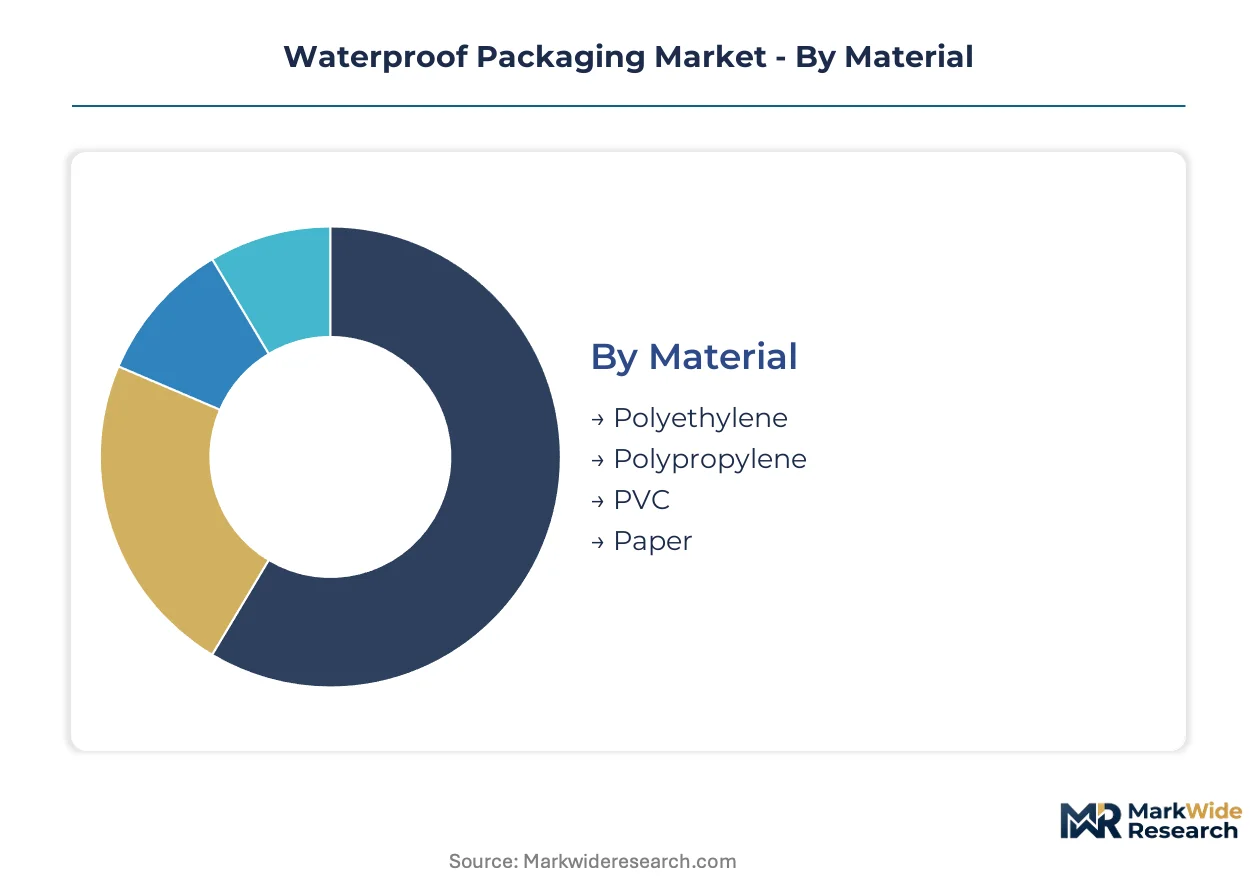
Material:
Cost-performance tradeoffs dominate resin selection, with recyclability mandates now constraining multilayer architectures previously optimized for moisture-vapor transmission rates.
- Polyethylene:Blown-film extrusion of high-density and linear-low-density grades delivers cost-efficient moisture barriers with heat-seal compatibility. German automotive component exporters specify MIL-PRF-131K compliant polyethylene pouches for precision electronics transit, absorbing modest premiums for certified lot traceability.
- Polypropylene:Cast and biaxially oriented films achieve optical clarity and dimensional stability for pharmaceutical serialization applications. Swiss and German contract packagers favor polypropylene where EMA Annex 1 documentation requirements intersect with shelf-appeal demands for visible dosage forms.
- PVC:Calendered and extruded films retain niche presence in medical device blister formats where thermoform depth and seal integrity outweigh recyclability concerns.
- Paper:Coated and laminated kraft structures satisfy fiber-primary packaging claims in Belgian and Dutch retail channels, with bio-based wax emulsions replacing REACH-restricted fluoropolymer chemistries.
Polyethylene leads on scale; paper gains share fastest on sustainability positioning.
Product Type:
Format selection tracks automation compatibility and line-speed requirements, with e-commerce fulfillment networks driving standardization around pre-qualified pouch dimensions.
- Bags:Side-seal and bottom-gusseted configurations dominate high-volume e-commerce outbound operations. Sealed Air Corporation's automated bagging systems specify dimension-toleranced polyethylene bags that minimize line changeover downtime in North American fulfillment centers.
- Pouches:Three-side-seal and stand-up formats capture pharmaceutical primary packaging where USP 671 moisture-barrier certification is mandatory. Mumbai-Ahmedabad cold-chain hubs source pre-qualified pouches for Indian pharmaceutical exports to African markets.
- Boxes:Corrugated structures with extrusion-coated liners serve automotive and electronics OEMs requiring stack strength combined with humidity protection during ocean transit.
- Films:Rollstock formats feed form-fill-seal lines across food and beverage contract packaging, with metallocene-grade polyethylene absorbing barrier functions previously reserved for ethylene-vinyl alcohol copolymers.
Films dominate volume throughput; pouches command the steepest price premiums.
End User:
Compliance intensity varies sharply across sectors, with pharmaceutical and food-contact applications subject to migration testing timelines that delay new material qualifications.
- Pharmaceuticals:Primary and secondary packaging for drug stability demands USP 671-compliant moisture barriers with documented water-vapor transmission rates. CDSCO alignment with ICH guidelines in India creates specification pull-through for barrier-grade films in export corridors.
- Food & Beverage:China's SAMR GB standards impose extended extraction studies on multilayer films, delaying launches by 8-14 months for converters serving frozen and chilled distribution.
- Electronics:German automotive Tier 1 suppliers specify desiccant-integrated pouches for control modules and sensors, with humidity indicator cards mandated for traceability.
- Cosmetics:Premium positioning drives adoption of metallized and holographic barrier films where shelf differentiation justifies material cost premiums over functional requirements.
Pharmaceuticals anchor specification authority; food and beverage delivers volume scale.
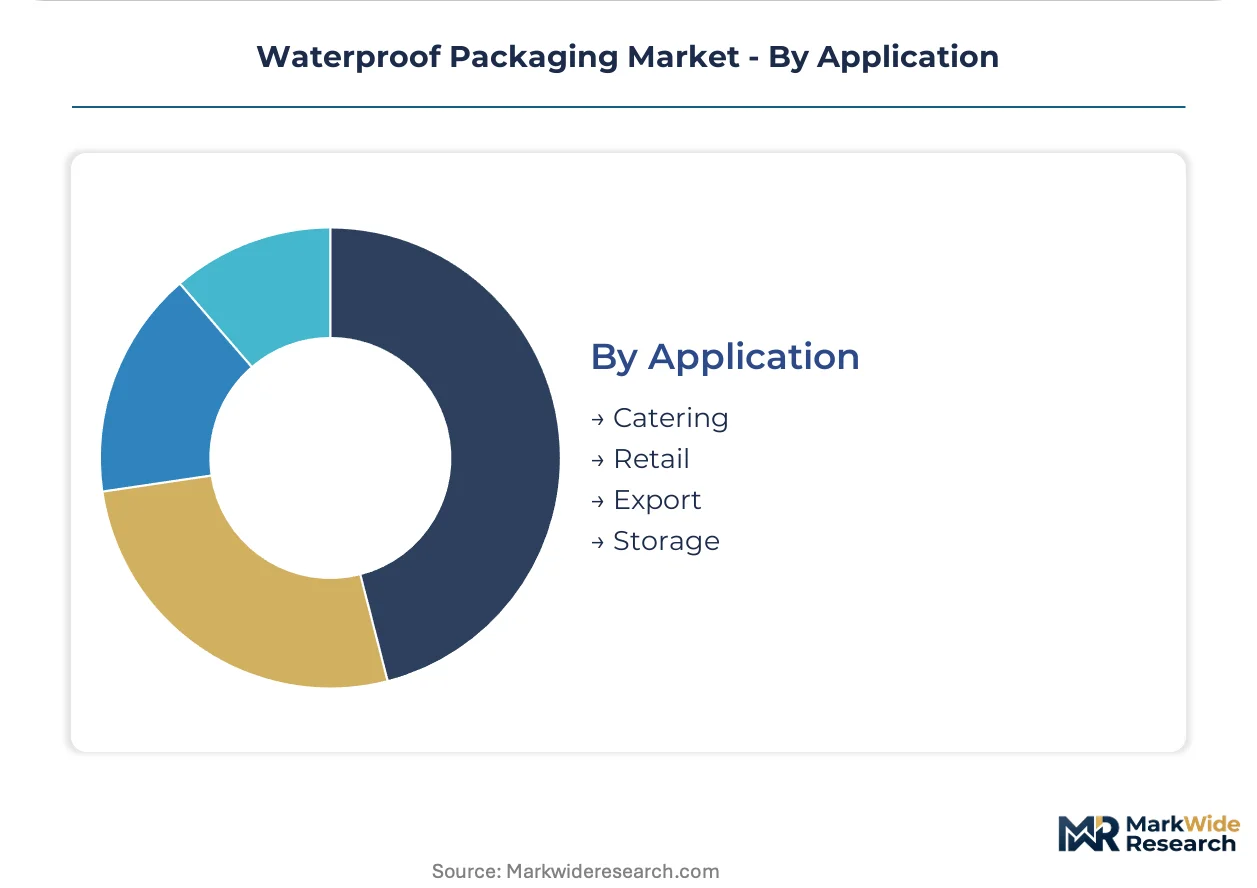
Application:
Use-case durability requirements segment demand between single-trip disposable formats and reusable systems for closed-loop logistics.
- Export:Ocean and air freight corridors require compliance with destination-country regulations including EMA Annex 1 for sterile pharmaceuticals and FDA USP 671 for US-bound drug shipments. Multilayer films with desiccant integration dominate cross-border pharmaceutical logistics.
- Storage:Long-duration humidity protection for spare parts and archival materials favors heat-sealed pouches with oxygen scavengers, particularly in German and Japanese industrial supply chains.
- Retail:Shelf-ready formats in European channels absorb kraft-paper waterproof alternatives where fiber-primary claims influence positioning.
- Catering:Single-use insulated bags for meal delivery balance cost minimization against temporary thermal and moisture protection.
Export commands the most stringent certification requirements; retail shows the fastest format innovation cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production maps as converters migrate toward jurisdictions with lower compliance burdens for multilayer barrier films. Cost-of-compliance gaps between REACH-regulated Europe and emerging Asian manufacturing hubs are accelerating capacity relocation decisions.
United States
Pharmaceutical serialization mandates from the FDA under USP 671 specifications drive demand for certified moisture-barrier pouches in Massachusetts and North Carolina biotech clusters. E-commerce fulfillment networks anchored by automated bagging systems concentrate specification authority with pre-qualified pouch formats. The Southeast's growing contract packaging base absorbs volume from cold-chain logistics serving Latin American export corridors.
Germany
Automotive Tier 1 suppliers in Bavaria and Baden-Württemberg specify MIL-PRF-131K compliant desiccant-integrated pouches for precision electronics transit. The EU Packaging and Packaging Waste Regulation forces structural pivots in multilayer film design as recyclability mandates collide with barrier-performance requirements. Hamburg and North Rhine-Westphalia host solventless lamination expertise concentrated among aging technician pools.
China
SAMR's GB standards for food-contact plastics impose extended migration testing timelines that delay new film launches by 8-14 months. Yangtze River Delta and Pearl River Delta converters expand blown-film extrusion capacity for barrier-grade polyethylene serving domestic e-commerce fulfillment. The country's dual carbon goals are pressuring resin-intensive packaging architectures toward mono-material alternatives.
India
CDSCO alignment with ICH stability guidelines creates specification pull-through for USP 671-compliant barrier films in Mumbai-Ahmedabad pharmaceutical export corridors. Domestic cold-chain infrastructure gaps concentrate demand for desiccant-integrated transit packaging serving African and Latin American markets. Gujarat and Maharashtra host emerging converter capacity targeting regional pharmaceutical contract packaging.
Switzerland
Swissmedic documentation requirements intersect with EMA Annex 1 sterile manufacturing protocols to elevate waterproofing standards for cross-border pharmaceutical shipments. Basel and Zurich contract packagers favor polypropylene clarity for visible dosage forms where shelf-appeal demands meet contamination-control logic. The country's precision manufacturing heritage supports premium positioning in barrier-film specification authority.
Waterproof Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fiber-primary and mono-material alternatives that satisfy circular-economy targets. The market structure stratifies across three tiers: integrated resin-to-film operators with captive polyethylene supply, specialized pharmaceutical pouch converters with USP 671 qualification depth, and paper-based barrier innovators targeting European retail sustainability claims. Dominant competitive moves include backward integration into resin compounding and strategic partnerships with automated bagging system OEMs to lock in specification pull-through.
Within the integrated-film tier, Amcor exemplifies geographic diversification across Southeast Asian resin-to-pouch operations. Sealed Air Corporation anchors North American positioning through fulfillment network integration. Mondi Group occupies the fiber-primary vector with kraft-paper waterproof alternatives targeting Belgian and Dutch retail channels. These three represent distinct strategic archetypes: vertical resin control, automation ecosystem capture, and sustainability-driven material substitution.
| Leading Market Players |
|---|
| Amcor |
| Sealed Air Corporation |
| Mondi Group |
| Smurfit Kappa |
| Berry Global |
| Sonoco Products |
| Constantia Flexibles |
| WestRock |
| ProAmpac |
| Others |
Value Network & Pricing Analysis
Pharmaceutical serialization mandates from the FDA and EMA are forcing converters to absorb certification costs for USP 671-compliant barrier films, compressing margins on standard-grade polyethylene pouches while concentrating pricing power with qualified suppliers in Germany and Switzerland.
Pricing Analysis
Distributor margins on pharmaceutical-grade pouches absorb 15-20 point spreads between resin converters and contract packagers, with three-tier pricing structure across premium, standard, and economy levels separating MIL-PRF-131K certified lots from uncertified commodity film. Price differentiation hinges on lot traceability documentation and EMA Annex 1 compliance depth. Pricing pressure stems from ethylene feedstock volatility forcing quarterly renegotiation clauses. Automotive Tier 1 buyers show lowest price sensitivity; e-commerce fulfillment networks exhibit highest.
Supply Chain Analysis
Ethylene feedstock supply rests on Gulf Coast petrochemical complexes, with blown-film extrusion capacity concentrating in China, Germany, and Thailand. Raw material dependencies include metallocene catalysts from Japanese specialty chemical producers, adhesive laminating resins from German formulators, and desiccant substrates from domestic mineral processors. Single-source vulnerability concentrates in solventless polyurethane bonding expertise aging out of German and Japanese technician pools. Distribution runs through converter-direct relationships with pharmaceutical OEMs and automated bagging system OEMs for e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The waterproof packaging market functions as a regulatory compounder, with the EU Packaging and Packaging Waste Regulation's recyclability mandates creating structural demand for mono-material barrier innovation that satisfies both MVTR targets and circular-economy compliance.
For Market Incumbents: Lock in specification authority by qualifying mono-material polyethylene structures with Mumbai-Ahmedabad pharmaceutical exporters before CDSCO's ICH alignment hardens supplier rosters. Capture backward integration into metallocene resin compounding to defend margin position against Asian converter cost leadership. Prioritize automated bagging system partnerships with Sealed Air Corporation's fulfillment network integration to secure pull-through demand. For New Entrants and Emerging Players: Mid-sized Indian pharmaceutical contract packagers represent an underserved buyer archetype seeking USP 671-compliant barrier films without minimum order thresholds imposed by integrated multinationals. White-space targets include kraft-paper waterproof alternatives for Belgian and Dutch retail channels where REACH-restricted fluoropolymer coatings have created substitution demand, and desiccant-integrated pouches for German automotive electronics Tier 2 suppliers. Go-to-market angle: fiber-primary packaging claims with bio-based wax emulsion barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized pharmaceutical pouch converters possessing USP 671 qualification depth and existing EMA Annex 1 documentation infrastructure, as serialization-driven procurement consolidation compresses approved-vendor lists. Long-term viability over the next decade hinges on mono-material barrier R&D pipelines and solventless lamination technician training programs. Signal to watch: FDA enforcement actions on moisture-barrier documentation gaps that accelerate supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier R&D Investment | Metallocene-grade polyethylene structures satisfy both MVTR targets and EU recyclability mandates. |
| Automated Bagging System Partnership | Sealed Air Corporation's North American fulfillment networks create specification pull-through for pre-qualified formats. |
| Solventless Lamination Capacity Buildout | German and Japanese technician expertise scarcity constrains quality at Southeast Asian greenfield plants. |
| Pharmaceutical Export Corridor Qualification | CDSCO's ICH alignment in Mumbai-Ahmedabad hubs creates first-mover advantage in African and Latin American markets. |
| Fiber-Primary Packaging Repositioning | Mondi Group's kraft-paper alternatives capture Belgian and Dutch retail channels under REACH PFAS restrictions. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with pharmaceutical contract packaging directors, automotive Tier 1 procurement leads, blown-film extrusion plant managers, and regulatory affairs specialists at EMA-notified bodies. Secondary validation draws from FDA USP 671 guidance documents, EMA Annex 1 revision drafts, SAMR GB standard filings, customs trade data on polyethylene film shipments, and SEC 10-K disclosures from integrated packaging producers. Bottom-up capacity assessments and top-down demand modeling were triangulated to cross-verify volume estimates.
Rate-of-change decomposition across the analysis window isolates volume drivers by material chemistry, product format, and end-use compliance tier, with CAGRs derived from segment-level growth trajectories rather than aggregate extrapolation. Segmentation dimensions modeled include barrier performance grade, regulatory certification depth, automation compatibility, and regional production hub clustering. Industry-specific forecast inputs incorporate pharmaceutical serialization mandate implementation timelines and EU Green Deal recyclability enforcement phases.
Underlying measurement precision varies by segment; pharmaceutical and food-contact applications carry tighter precision than retail and catering formats due to documented regulatory filing requirements. Forecasts reflect assumptions on resin cost stability, adhesive lamination skill migration, and mono-material barrier adoption curves. A small set of triggers warrants ongoing watch: EMA Annex 1 enforcement intensity, REACH PFAS restriction expansion, and CDSCO inspection capacity for ICH guideline alignment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
Aluminum Oxide Coated Films Market
Packaging Barrier Films
Cryogenic Insulation Films Market
Packaging Barrier Films
USA Barrier Coated Paper Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Global Stretch and Shrink Film Market
Packaging Barrier Films
High Barrier Packaging Films for Pharmaceuticals Market
Packaging Barrier Films
Barrier Packaging Market
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
Special Effects Laminate Films Market
Packaging Barrier Films
Release Liners Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Transparent Barrier Films Market