
 Food Packaging Robotics Market | 2026-2036
Food Packaging Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Food Packaging Robotics Market Analysis
German food equipment manufacturing is consolidating as producers scale output for pan-European dairy and bakery automation. ABB leverages its Nordic engineering heritage to sustain dominance in high-speed palletizing systems for chilled supply chains. FANUC anchors its position through in-house servo motor production that controls cost structures across Asian and European install bases. KUKA competes via automotive-derived precision architectures now adapted for washdown food environments.
Food packaging robotics encompasses articulated mechanical systems engineered to IP69K washdown standards, executing pick-place-seal cycles within 0.3-second tolerances for sanitary product handling. Robotic arms and collaborative robots lead installed capacity, though autonomous mobile robots represent the fastest-expanding category as facilities integrate warehouse-to-line logistics. Machine vision technology commands premium positioning within the technology stack, while carton packaging applications absorb the largest share of new capital expenditure across beverage end users.
EU machinery directives and FDA food contact substance regulations jointly determine ingress protection ratings and lubricant chemistry for equipment sold into regulated markets. ISO 10218 safety standards and CE marking requirements shape product development roadmaps, particularly for collaborative robot deployments in open production floors. Stakeholders must monitor evolving EU AI Act classifications that could reclassify vision-guided packaging systems as high-risk automated decision systems.
Market Dynamics
IP69K washdown-rated articulated systems are displacing pneumatic pick-and-place units as dairy and ready-meal processors face intensifying EU hygiene directive enforcement and FDA food contact substance scrutiny.
Growth Catalysts
- EU AI Act Classification Pressure:High-risk system designations for vision-guided packaging are accelerating investment in compliant machine vision architectures before enforcement deadlines tighten.
- China Smart Factory Mandates:Eastern coastal provinces now require automated packaging lines for export certification, forcing food manufacturers to deploy robotic carton filling systems.
- Aseptic Processing Expansion:Dairy processors in Northern Europe are retrofitting lines with washdown-capable articulated arms to meet EFSA hygiene benchmarks for extended-shelf-life products.
Market Restraints
- Stainless Steel Supply Concentration:Japanese and German specialty steel mills control premium 316L supply for IP69K robot construction, creating input cost volatility during alloy price spikes.
- REACH Compliance Friction:Lubricant chemistry restrictions for food-contact robotics extend product development cycles by 8-14 months for CE-marked equipment.
- Cobalt Servo Magnet Dependency:Rare earth processing concentration in China creates supply risk for high-torque collaborative robot motor assemblies.
Strategic Opportunities
- Autonomous Mobile Robot Integration:Warehouse-to-line logistics convergence with packaging cells offers white space in beverage distribution centers seeking unified automation platforms.
- US IRA Clean Manufacturing Credits:Domestic production incentives for energy-efficient robotics are reshaping sourcing decisions for North American food processing equipment.
- Collaborative Robot Washdown Gap:IP69K-rated cobot architectures remain underdeveloped for open-floor bakery environments, creating premium positioning for compliant entrants.
Industry Challenges
- ISO 10218 Safety Integration:Collaborative deployments in mixed human-robot production floors require extensive risk assessment cycles that compress installation timelines.
- Machine Vision Calibration Drift:High-speed seal verification systems demand continuous retraining protocols that strain in-house automation engineering capacity at mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Packaging Robotics Market |
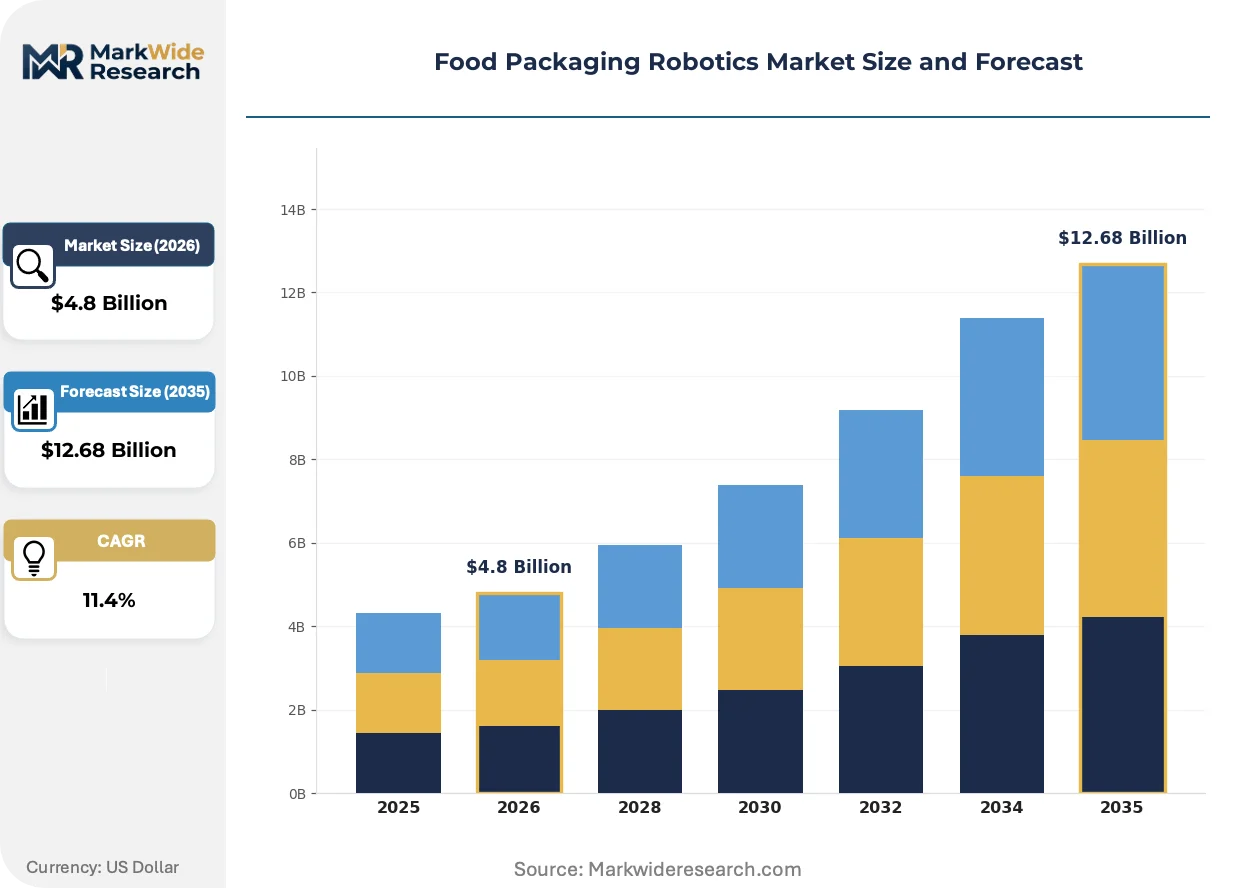
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Robotic Arms, Autonomous Mobile Robots, Palletizing Robots, Collaborative Robots Application: Flexible Packaging, Carton Packaging, Bottling, Canning End User: Beverage Industry, Bakery Sector, Dairy Products, Confectionery Technology: Artificial Intelligence, Machine Vision, Sensor Technology, Control Systems |
| Companies Covered | Universal Robots, Mitsubishi Electric, ABB, OMRON, Midea Group, FANUC, KUKA, Stäubli, Yaskawa Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Packaging Robotics Market Emerging Trajectories
Active compliance architecture is displacing passive certification as the dominant design philosophy. Equipment vendors now embed regulatory foresight into hardware roadmaps rather than retrofitting for delayed enforcement.
Machine vision-guided adaptive gripping is consolidating control over previously manual handling tasks in irregular-product packaging. Bakery and confectionery processors in Belgium and the Netherlands are deploying force-torque sensing arrays at pace. This convergence of vision and haptic feedback is consolidating supplier power among integrated platform vendors while marginalizing standalone vision component producers.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant leak detection integration into chilled supply chain robotics. Compressor-sealed robotic cells for ice cream and frozen dough handling now require continuous monitoring architectures. German equipment manufacturers are absorbing these sensor costs into base configurations to preempt CE marking delays.
Food manufacturers are unbundling after-sales service from capital contracts and contracting directly with regional integration specialists. This procurement fragmentation is most visible in China's Yangtze River Delta, where smart factory mandates have created a dense field of third-party automation service providers. OEMs are responding with subscription-based remote monitoring to retain recurring revenue attachment.
Food Packaging Robotics Market Segmentation
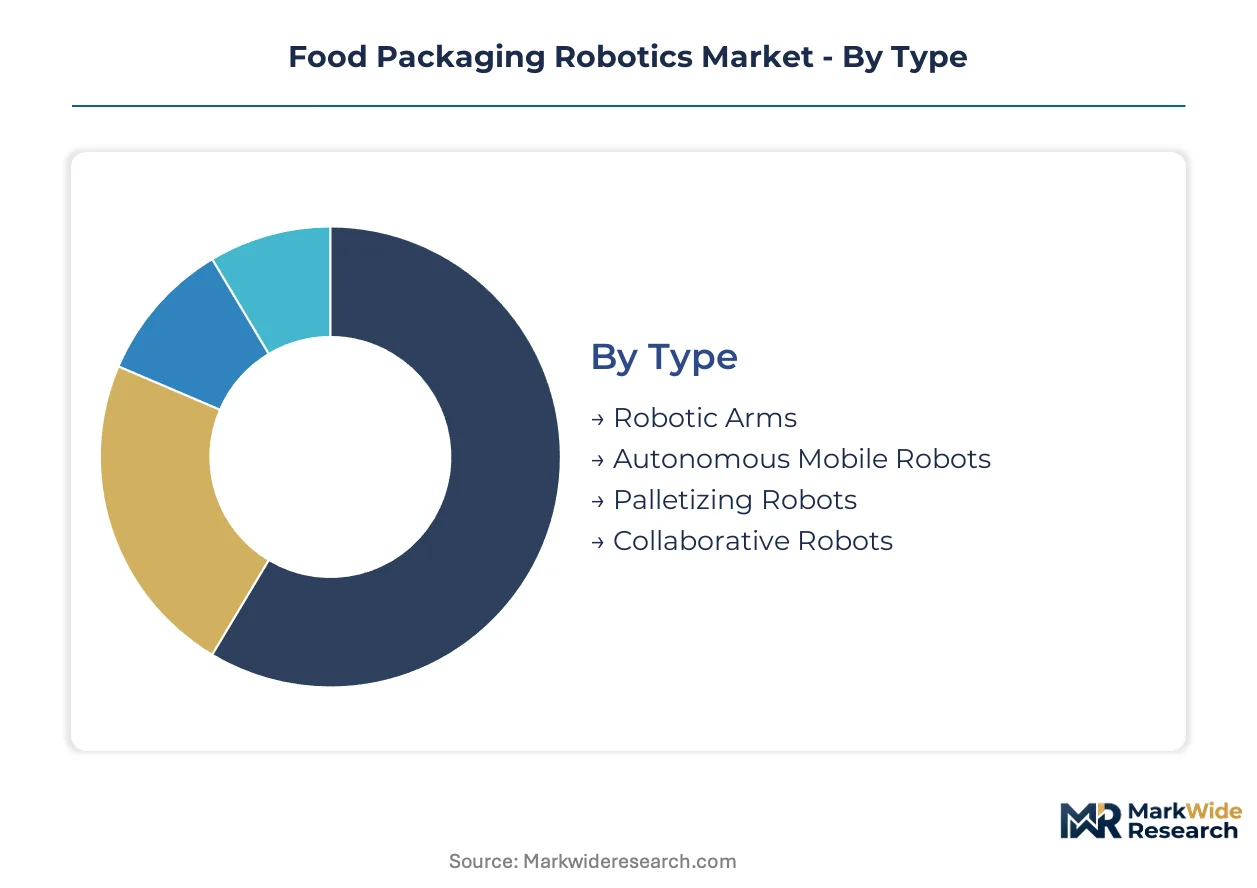
Equipment certification requirements fragment procurement strategies across robot architectures. Dairy processors prioritize IP69K washdown ratings while beverage bottlers emphasize throughput velocity. Understanding segment-specific regulatory burdens clarifies why certain technologies command premium positioning.
Type:
CE marking complexity varies sharply by mechanical architecture, with washdown-rated systems demanding extended validation cycles under EU machinery directives.
- Robotic Arms:Articulated six-axis systems engineered to IP69K ingress protection standards execute pick-place-seal cycles within 0.3-second tolerances. Demand concentrates in German dairy processing facilities retrofitting lines under EFSA hygiene benchmarks for extended-shelf-life products. FDA food contact substance regulations add parallel compliance layers for equipment exported to North American markets.
- Autonomous Mobile Robots:Warehouse-to-line logistics platforms integrate with packaging cells through fleet management software. China's Yangtze River Delta smart factory mandates accelerate deployments as export certification requires automated material handling. These systems expand most quickly as beverage distribution centers seek unified automation platforms.
- Palletizing Robots:High-speed gantry and articulated systems handle case-stacking at chilled supply chain endpoints.
- Collaborative Robots:Force-limited cobot architectures remain underdeveloped for open-floor bakery environments, creating premium positioning for IP69K-compliant entrants.
Leading the category by volume: Robotic Arms. Expanding most quickly: Autonomous Mobile Robots.
Application:
Capital allocation patterns diverge by packaging format complexity, with aseptic liquid handling commanding the highest specification premiums.
- Carton Packaging:Aseptic filling systems for UHT dairy and juice products require continuous sterilization architectures. Eastern coastal Chinese provinces mandate automated carton lines for export-ready food manufacturing certification. EFSA hygiene directives and FDA 21 CFR Part 113 regulations jointly determine validation protocols.
- Flexible Packaging:Form-fill-seal integration for snack foods and ready meals demands adaptive gripping with force-torque sensing arrays. Belgian and Dutch bakery processors deploy these systems at pace to consolidate control over irregular-product handling. REACH compliance friction extends development cycles for lubricant chemistry approvals.
- Bottling:High-speed rotary filling with vision-guided quality inspection dominates beverage end-user procurement.
- Canning:Retort-compatible handling systems serve shelf-stable protein and vegetable processing segments.
Dominant by installed base: Carton Packaging. Steepest expansion trajectory: Flexible Packaging.
End User:
Customer concentration and margin profiles vary substantially across food processing verticals, with chilled supply chains absorbing premium automation.
- Dairy Products:Extended-shelf-life and aseptic processing requirements drive specification intensity. Northern European processors retrofit lines with washdown-capable articulated arms under EU hygiene directive enforcement. F-Gas Regulation phase-down schedules accelerate refrigerant leak detection integration into robotic cells.
- Beverage Industry:Carbonated and still drink bottlers prioritize throughput velocity over adaptive handling complexity. China's smart factory mandates concentrate demand in automated packaging lines for export certification. Machine vision calibration requirements strain in-house engineering capacity at mid-scale processors.
- Bakery Sector:Irregular product geometries and open-floor production environments create cobot deployment challenges.
- Confectionery:High-speed wrapping and seasonal volume spikes favor flexible automation with rapid changeover capability.
Highest specification intensity: Dairy Products. Fastest automation penetration: Beverage Industry.
Technology:
Software and sensing layers determine competitive differentiation as hardware commoditizes across mechanical platforms.
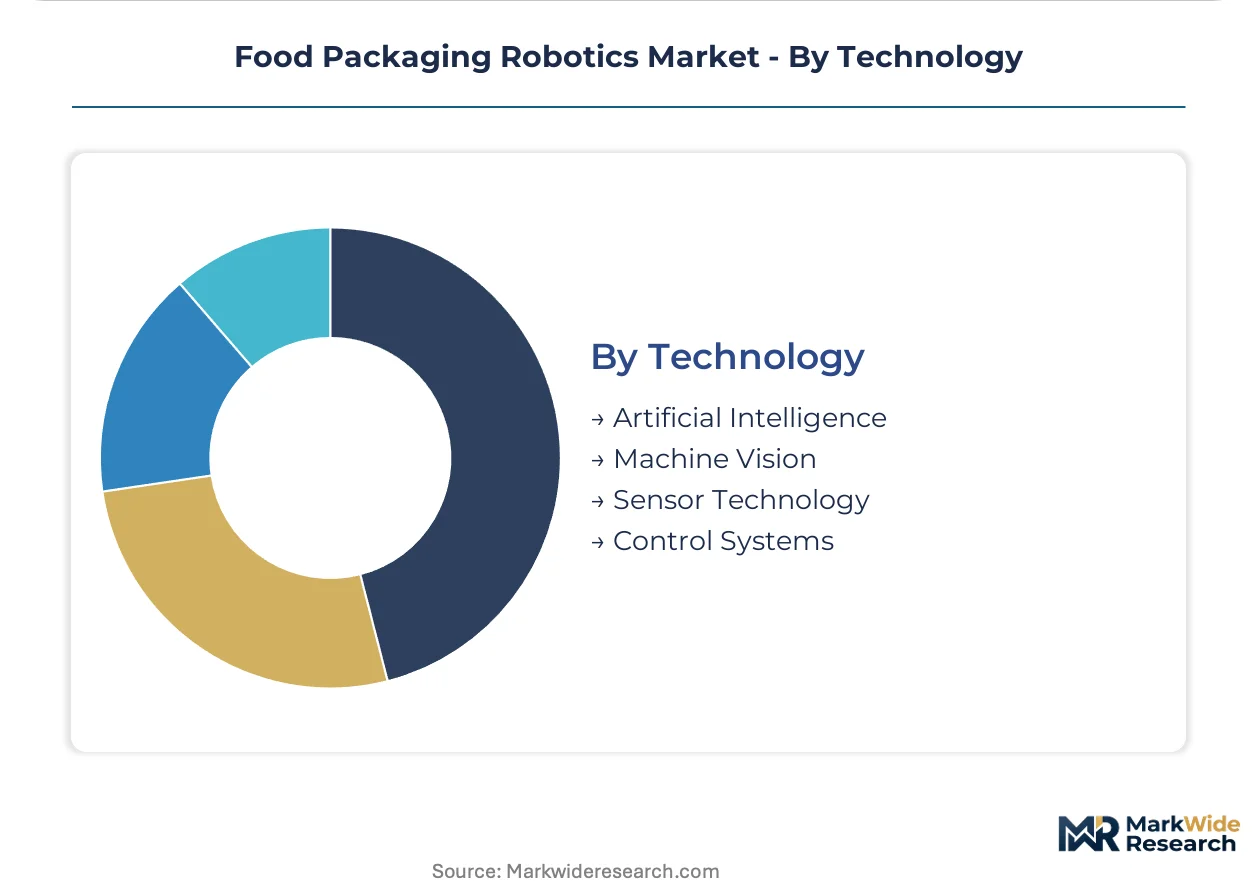
- Machine Vision:Seal verification and defect detection systems command premium positioning within the technology stack. EU AI Act high-risk system designations accelerate investment in compliant architectures before enforcement deadlines tighten. Continuous retraining protocols strain mid-scale processor engineering capacity.
- Artificial Intelligence:Predictive maintenance and adaptive gripping algorithms embed regulatory foresight into hardware roadmaps. Vision-guided packaging systems face potential reclassification under evolving automated decision system definitions. Active compliance architecture displaces passive certification as dominant design philosophy.
- Sensor Technology:Force-torque and proximity arrays enable collaborative deployment in mixed human-robot production floors.
- Control Systems:Real-time motion planning and safety-rated monitored stop functions anchor ISO 10218 compliance.
Premium positioning leader: Machine Vision. Gaining share fastest: Artificial Intelligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty stainless steel mills in Germany and Japan supply the 316L alloys essential for IP69K-rated robot construction, anchoring procurement networks that extend into dairy processing clusters across Northern Europe and precision manufacturing zones in East Asia.
Germany
Dairy processors in Bavaria and Lower Saxony retrofit aseptic filling lines with washdown-capable articulated arms under EFSA hygiene benchmarks. The EU F-Gas Regulation accelerates refrigerant leak detection integration into robotic cells for extended-shelf-life products. Equipment manufacturers around Stuttgart absorb sensor costs into base configurations to preempt CE marking delays.
China
Smart factory mandates in Jiangsu and Zhejiang provinces require automated packaging lines for export certification, concentrating demand in the Yangtze River Delta. MIIT dual carbon goals reshape energy efficiency specifications for robotic installations. Third-party automation service providers in Shanghai and Suzhou fragment after-sales procurement away from OEM contracts.
United States
Clean Manufacturing Credits under the IRA reshape sourcing decisions for energy-efficient robotics in dairy and beverage processing. FDA food contact substance regulations determine lubricant chemistry for equipment deployed across Midwest dairy cooperatives. California's Central Valley processors deploy machine vision systems under state-level food safety protocols.
Japan
METI industrial automation roadmaps prioritize collaborative robot deployments in mixed human-robot production floors. Rare earth processing concentration creates supply risk for high-torque servo motor assemblies manufactured in Nagoya and Osaka industrial zones. JIS standards for food-contact robotics extend product validation cycles for domestic and export markets.
Netherlands
Bakery and confectionery processors in North Brabant deploy force-torque sensing arrays for irregular-product handling at pace. REACH compliance friction for lubricant chemistry extends development cycles for equipment bound for pan-European distribution. The Eindhoven Region anchors vision-guided adaptive gripping integration across Benelux food manufacturing networks.
Food Packaging Robotics Market Vendor Landscape
Global majors compete with regional champions across certification complexity and servo motor integration depth. Market structure consolidates around three tiers: integrated platform vendors controlling machine vision and haptic feedback convergence, automotive-derived precision specialists adapting washdown architectures, and in-house component producers managing cost structures across install bases. Strategic moves center on active compliance architecture embedding regulatory foresight into hardware roadmaps, and subscription-based remote monitoring to retain recurring revenue attachment as procurement fragments toward regional integration specialists.
Among Nordic engineering heritage groups, ABB occupies a position exemplifying high-speed palletizing dominance for chilled supply chains. FANUC and KUKA sit within the automotive-derived precision tier, with the former representing in-house servo motor production archetypes and the latter exemplifying washdown adaptation from precision manufacturing origins. Universal Robots anchors the collaborative robot segment where IP69K-rated architectures remain underdeveloped for open-floor bakery environments.
| Leading Market Players |
|---|
| Universal Robots |
| Mitsubishi Electric |
| ABB |
| OMRON |
| Midea Group |
| FANUC |
| KUKA |
| Stäubli |
| Yaskawa Electric |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between IP69K washdown-rated systems and standard industrial configurations manifests in both pricing stratification and supply chain sourcing patterns. Premium-tier equipment draws from Japanese and German specialty steel mills for 316L alloys, while economy-tier alternatives source from broader Asian metal suppliers, creating parallel procurement networks with divergent lead time and cost structures.
Pricing Analysis
Warranty and service bundling unbundling is reshaping contract structures as food manufacturers fragment procurement toward regional integration specialists. Three-tier pricing structure across premium, standard, and economy levels reflects IP certification intensity and servo motor torque specifications. Cost compression in mid-tier articulated arms is intensifying because Chinese smart factory mandates are forcing volume deployments. Mid-scale dairy processors exhibit highest price sensitivity, while aseptic beverage bottlers prioritize specification compliance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for critical servo motor magnets are forcing buyers to qualify both Chinese and Japanese rare earth processors. Supply draws from Germany, Japan, and China for specialty stainless steel, high-torque servo assemblies, and machine vision components respectively. Single-source vulnerability concentrates in cobalt magnet processing. Distribution runs through OEM-direct channels for large dairy cooperatives and third-party automation integrators for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained with Japanese and German specialty steel mills controlling premium 316L alloy capacity, propping pricing power for washdown-certified equipment tiers.
For Market Incumbents: Cement dominance in high-speed palletizing through captive supply of servo motor components, insulating against rare earth price volatility. Deepen backward integration into machine vision software stacks to capture margin migrating from hardware toward sensing layers. Emerging cobot specialists from East Asia threaten mid-tier positioning.
For New Entrants and Emerging Players: Mid-scale bakery processors in open-floor environments represent an underserved buyer archetype lacking IP69K-rated collaborative options. White space concentrates in force-torque sensing arrays for irregular-product handling and subscription-based remote monitoring for fragmented after-sales procurement. Go-to-market through regional automation service providers in China's Yangtze River Delta bypasses OEM channel control.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated platform vendors controlling vision-haptic convergence given EU AI Act enforcement tightening. Long-term viability favors suppliers embedding regulatory foresight into hardware roadmaps rather than retrofitting compliance. Watch machine vision system reclassification under automated decision system definitions as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | FANUC's captive magnet supply insulates margin against Chinese rare earth processing concentration. |
| IP69K Cobot Architecture Development | Universal Robots' washdown gap creates premium positioning for compliant entrants in bakery automation. |
| Machine Vision Platform Acquisition | ABB's Nordic engineering heritage consolidates control over seal verification and defect detection layers. |
| Subscription-Based Remote Monitoring Launch | KUKA's automotive-derived precision architectures now embed recurring revenue attachment amid procurement fragmentation. |
| CE Marking Preemptive Sensor Integration | German equipment manufacturers absorb F-Gas leak detection costs to preempt validation cycle delays. |
Methodological Framework
Independent corroboration across plant engineers at dairy processing facilities, procurement leads at beverage OEMs, and aftermarket service heads at automation integrators underwrites the qualitative findings. Secondary validation draws from EU machinery directive filings, FDA food contact substance registrations, SEC equipment manufacturer disclosures, and customs data for 316L stainless steel trade flows. Bottom-up installation counts triangulate against top-down capital expenditure estimates across food processing verticals.
Comparable-period anchoring to historical robot deployment cycles in automotive manufacturing informed the projection horizon calibration. Segmentation modeling spans robot architecture type, packaging application format, end-user vertical, and technology layer across the analysis window. CAGRs derive from equipment shipment trajectories weighted by regional smart factory mandate intensity and hygiene directive enforcement schedules. Forecast inputs incorporate rare earth magnet price volatility assumptions and REACH lubricant chemistry approval timelines.
Revisions become necessary when EU AI Act enforcement timelines accelerate, Chinese dual carbon goals reshape energy efficiency specifications, or specialty steel alloy supply disruptions materialize. Deviation in cobalt magnet processing concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Automation
Automatic Strapping Machines Market
Packaging Automation
Automatic Powder Filling Machines Market
Packaging Automation
Automatic Labeling Machine Market
Packaging Automation
Fully Automatic Round Bottle Labeling Machine Market
Packaging Automation
Packaging Automation Solutions Market
Packaging Automation
Europe Packaging Automation Market
Packaging Automation
APAC Packaging Automation Market
Packaging Automation
Pre-Assembled Packaging Market
Packaging Automation
North America Contract Packaging Market
Packaging Automation
Packaging Automation Market
Packaging Automation
Automatic Capping Machine Market
Packaging Automation
Automatic Die Cutting Machines Market
Packaging Automation
Middle East and Africa Packaging Automation Market
Packaging Automation
Automatic Glue Machine Market
Packaging Automation
Automated Tray Fill and Seal Machines Market
Packaging Automation
Automated Label Inspection Machines Market