
 Super Barrier Coated Film Market | 2026-2036
Super Barrier Coated Film Market Size, Share, and Industry Trends Forecast 2026-2036
Super Barrier Coated Film Market Analytics
Single-source dependence on Asian vacuum metallization houses is rebalancing toward regional multi-source strategies among European and North American converters. Toray Industries anchors Asia-Pacific supply through captive polymer and deposition capabilities. Amcor leverages its healthcare packaging footprint to qualify alternative oxide-coated substrates at FDA-audited plants. Berry Global competes on thermoformable barrier structures for protein and dairy formats.
Super barrier coated film denotes a flexible substrate—typically polyethylene, polypropylene, or polyester—bearing nanometer-scale ceramic or metallic layers deposited via plasma-enhanced chemical vapor deposition or physical vapor deposition to achieve oxygen transmission rates below 0.1 cc/m²/day and water vapor transmission rates under 0.1 g/m²/day, primarily serving shelf-life extension for oxygen- and moisture-sensitive contents. Polyethylene dominates food packaging volumes where cost and heat-seal compatibility matter, while polyester leads pharmaceutical applications demanding optical clarity and dimensional stability during cold-form processing. Nylon occupies niche industrial and electronics packaging where puncture resistance and barrier synergy prove critical.
FDA enforces stringent extractables and leachables protocols for pharmaceutical contact films, while the EU Green Deal and REACH constrain per- and polyfluoroalkyl substance use in barrier coatings, compelling reformulation toward halogen-free chemistries. EMA's evolving guidance on primary packaging stability is elevating documentation burdens for film suppliers seeking European market access. Stakeholders must monitor regulatory divergence between FDA and EMA on acceptable barrier technologies while building qualification data packages that satisfy both jurisdictions without duplicative testing regimes.
Market Dynamics
Pharmaceutical packaging specifications for ultra-low oxygen and moisture transmission are forcing converters to qualify alternative ceramic-coated substrates as fluorinated chemistries face regulatory phase-out.
Growth Catalysts
- EU F-Gas Regulation:Tightening restrictions on fluorinated barrier technologies are accelerating migration toward silicon oxide and aluminum oxide deposition methods among European pharmaceutical contract packagers.
- Cold-form blister demand:Moisture-sensitive biologic drug delivery formats require polyester-based super barrier films with dimensional stability during deep-draw thermoforming.
- Frankfurt-Munich corridor:Concentrated pharmaceutical packaging clusters in southern Germany are specifying ultra-high-barrier specifications that propagate across European converter networks.
Market Restraints
- Deposition equipment scarcity:Vacuum metallization and plasma-enhanced chemical vapor deposition systems face 18-24 month lead times from specialized German and Japanese equipment suppliers.
- Aluminum oxide precursor volatility:Organoaluminum compound supply concentrates among limited specialty chemical producers, creating input cost instability.
- Extractables documentation burden:FDA and EMA divergent testing protocols for pharmaceutical contact films force redundant qualification studies that extend commercialization timelines.
Strategic Opportunities
- Cell-cultured protein packaging:Emerging alternative meat producers require thermoformable barrier structures with extended shelf-life performance currently met by oxide-coated nylon-polyethylene laminations.
- India pharmaceutical export growth:CDSCO-registered contract packaging facilities near Hyderabad and Ahmedabad are qualifying imported super barrier films for EU and US-bound drug shipments.
- Digital printing convergence:Integration of high-barrier base films with inkjet-compatible topcoats enables short-run pharmaceutical serialization without secondary labeling operations.
Industry Challenges
- Plasma deposition technician shortage:Specialized expertise in PECVD process optimization and defect control remains concentrated among veteran operators at established European and Japanese converters.
- Multi-jurisdiction qualification timelines:Simultaneous FDA Type III drug master file and EMA variation submission requirements create parallel regulatory pathways that strain documentation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Super Barrier Coated Film Market |
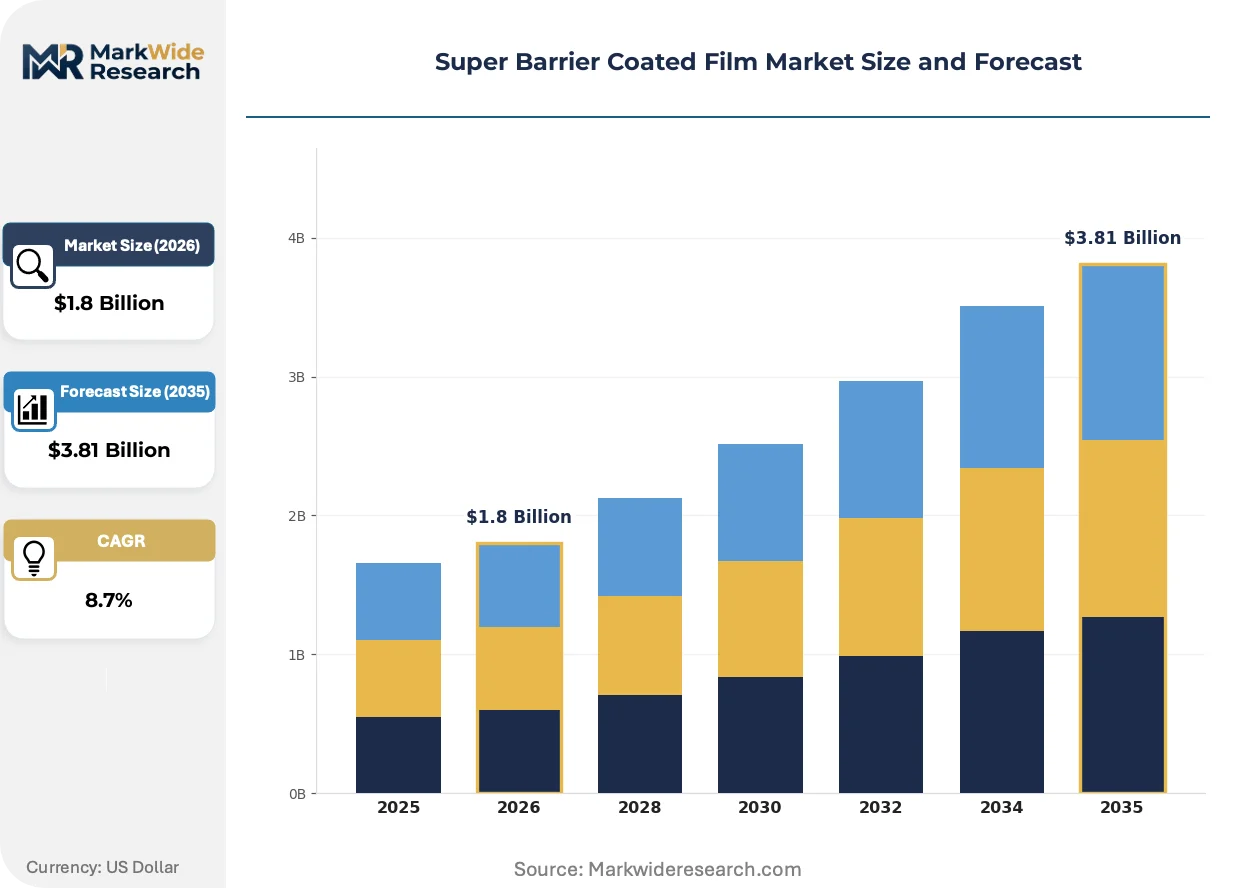
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyester, Nylon Application: Food Packaging, Pharmaceutical Packaging, Industrial Packaging, Electronics Packaging End User: Consumer Goods, Healthcare, Electronics, Automotive Distribution Channel: Direct Sales, Retail, E-commerce, Distributors |
| Companies Covered | UFlex Limited, Cosmo Films, Toray Industries, Tekni-Plex, Vibac Group, Berry Global, Amcor, Sigma Technologies Int'l, Syensqo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Super Barrier Coated Film Market Evolving Landscape
Barrier coating technologies are pivoting from legacy metallized films toward ceramic oxide architectures as regulatory pressure and pharmaceutical performance requirements intensify simultaneously.
Silicon oxide coatings applied via plasma-enhanced chemical vapor deposition are absorbing volume share from aluminum metallization in pharmaceutical blister applications. European converters serving Frankfurt-based contract packagers are adopting these chemistries at accelerated rates to preempt F-Gas compliance deadlines. The shift is absorbing capital investment that previously flowed toward conventional vacuum metallization capacity.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer barrier coatings from pharmaceutical packaging specifications. The EU Green Deal's chemical sustainability roadmap is compressing the transition timeline, forcing reformulation toward halogen-free ceramic alternatives. German pharmaceutical packaging clusters are responding by pre-qualifying oxide-coated polyester substrates ahead of formal regulatory deadlines.
Buyer consolidation among multinational pharmaceutical contract packagers is compressing supplier qualification cycles and favoring converters with multi-site FDA and EMA audit histories. Direct material specification authority is migrating from regional procurement offices to central technical teams at headquarters locations. This concentration is most visible in Germany, where three major contract packaging groups now dictate barrier film standards across their European facility networks.
Super Barrier Coated Film Market Segmentation
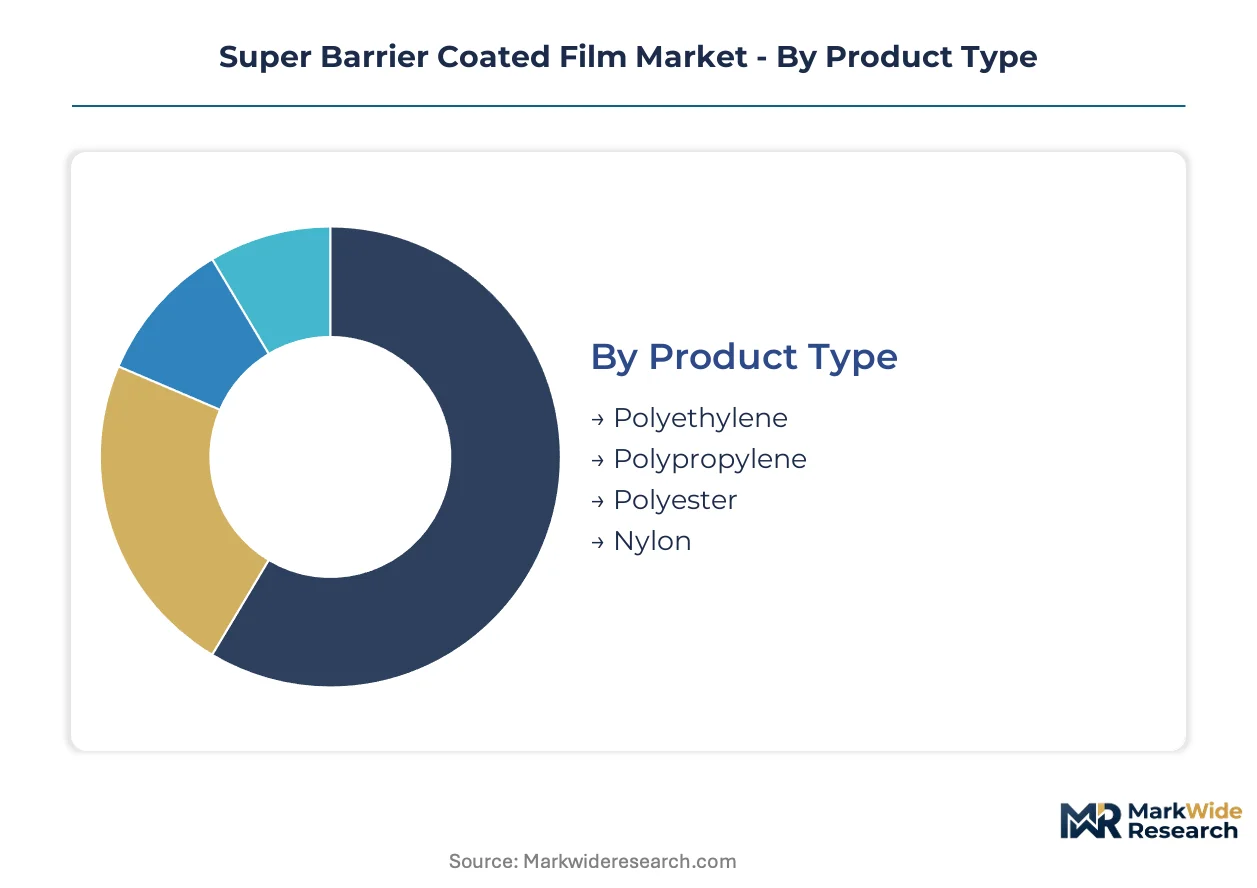
Segmentation in super barrier coated films reveals how substrate chemistry, application performance requirements, and channel economics create distinct competitive arenas. Each axis exposes different margin structures, qualification barriers, and buyer concentration patterns that shape supplier strategy.
Product Type:
Substrate selection hinges on heat-seal compatibility, optical clarity needs, and mechanical performance during forming operations.
- Polyethylene:Linear low-density and metallocene grades dominate food packaging laminations where hermetic sealing and cost efficiency matter. German dairy converters specify oxide-coated PE structures for extended shelf-life cheese formats under EFSA migration limits.
- Polyester:Biaxially oriented PET provides dimensional stability and optical clarity for cold-form pharmaceutical blisters. Frankfurt-based contract packagers pre-qualify silicon oxide-coated PET for moisture-sensitive biologic drugs facing EMA stability documentation requirements.
- Polypropylene:Cast and oriented PP grades serve retort and microwaveable applications requiring thermal resistance. Japanese converters favor PP for convenience food formats demanding barrier plus heat tolerance.
- Nylon:Polyamide substrates deliver puncture resistance and oxygen barrier synergy for industrial and electronics packaging. Niche demand concentrates in precision component shipping where mechanical abuse resistance is non-negotiable.
Polyethylene leads on scale; polyester leads on momentum.
Application:
Performance specifications diverge sharply between shelf-life extension for perishables and regulatory compliance for pharmaceuticals.
- Food Packaging:Modified atmosphere and vacuum structures for protein, dairy, and snack formats drive volume. US meat processors specify ultra-low oxygen transmission films under USDA inspection protocols.
- Pharmaceutical Packaging:Blister, sachet, and strip pack formats for moisture-sensitive drugs command premium positioning. CDSCO-registered facilities in Hyderabad import oxide-coated films for EU-bound generic exports.
- Industrial Packaging:Barrier films for chemicals, agrochemicals, and lubricants emphasize chemical resistance. Applications span drum liners to flexible intermediate bulk containers.
- Electronics Packaging:Static-dissipative barrier structures protect semiconductors and displays from moisture and oxygen damage. Cleanroom-compatible formats serve Korean and Taiwanese semiconductor assembly operations.
Food packaging anchors volume throughput; pharmaceutical packaging captures margin expansion.
End User:
Buyer sophistication and qualification intensity vary dramatically across sector verticals.
- Consumer Goods:Food, beverage, and personal care brand owners drive standardization toward cost-efficient barrier solutions. Procurement teams at multinational CPGs consolidate specifications across regional manufacturing networks.
- Healthcare:Pharmaceutical manufacturers and contract packagers impose the most stringent extractables documentation and audit requirements. FDA Type III drug master file submissions dominate supplier qualification timelines.
- Electronics:Semiconductor and display manufacturers specify barrier performance alongside cleanroom compatibility. Japanese and Korean electronics assemblers maintain approved vendor lists with narrow technical tolerances.
- Automotive:Battery and sensor packaging for electric vehicles creates emerging demand for moisture and oxygen exclusion. German automotive suppliers are qualifying barrier films for lithium-ion cell shipment protection.
Healthcare commands the steepest qualification barriers; electronics is climbing the fastest.
Distribution Channel:
Channel choice reflects order scale, technical support needs, and geographic proximity to converting operations.
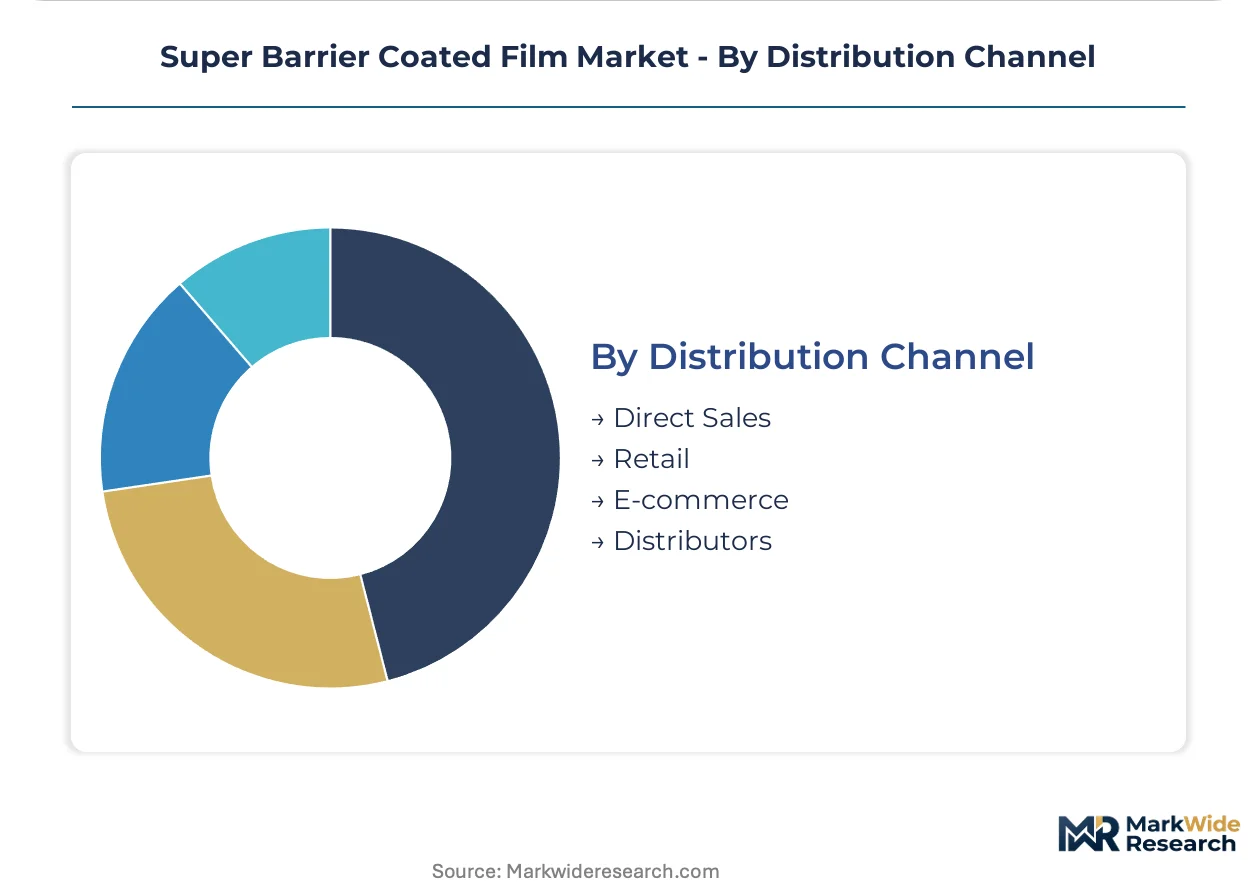
- Direct Sales:Large converters and multinational packagers negotiate frame contracts with film manufacturers for volume commitments and technical service access. Direct relationships dominate pharmaceutical and electronics segments.
- Distributors:Regional stocking distributors serve mid-tier converters requiring smaller lot sizes and faster delivery. European industrial packaging buyers rely on distributor networks for just-in-time inventory.
- Retail:Limited penetration; primarily specialty film sales to small-scale converters through packaging supply retailers.
- E-commerce:Emerging channel for sample quantities and standard grades; pharmaceutical qualification requirements limit adoption for regulated applications.
Direct sales captures the highest value contracts; distributors extend geographic reach most efficiently.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Munich pharmaceutical packaging corridor anchors European demand for ultra-high-barrier films, with specification authority concentrating among three major contract packaging groups that dictate standards across their facility networks.
Germany
Pharmaceutical contract packaging clusters around Frankfurt and Munich specify silicon oxide-coated polyester for moisture-sensitive biologic drugs. The EU F-Gas Regulation accelerates migration from fluorinated barrier chemistries toward ceramic oxide alternatives. CDMO technical teams at headquarters locations now control direct material specification authority across European networks.
United States
FDA Type III drug master file requirements dominate qualification timelines for pharmaceutical contact films serving generic and innovator drug manufacturers. USDA inspection protocols govern ultra-low oxygen transmission specifications for meat processing applications. Vacuum metallization capacity concentrates around Midwest converting hubs supplying protein packagers.
India
CDSCO-registered contract packaging facilities near Hyderabad and Ahmedabad qualify imported oxide-coated films for EU and US-bound generic drug shipments. Domestic converters face documentation burdens from divergent FDA and EMA testing protocols. Pharmaceutical export growth drives specification alignment with Western regulatory standards.
Japan
Converters favor polypropylene substrates for convenience food formats requiring barrier plus microwave tolerance. PMDA stability documentation requirements elevate supplier qualification intensity for pharmaceutical applications. Captive polymer and deposition capabilities anchor Asia-Pacific supply security.
South Korea
Electronics assemblers specify static-dissipative barrier structures for semiconductor and display protection in cleanroom environments. MFDS pharmaceutical regulations create parallel qualification pathways for drug packaging materials. Korean semiconductor packaging demand absorbs specialized high-barrier film capacity.
Super Barrier Coated Film Market Competitive Landscape
Global majors compete with regional champions across qualification-intensive pharmaceutical segments and cost-sensitive food packaging tiers. Market structure consolidates around converters with multi-site FDA and EMA audit histories, while mid-tier players serve industrial and electronics applications with lower documentation burdens. Three archetypes dominate: integrated polymer-to-film manufacturers, specialized deposition technology licensors, and diversified packaging conglomerates. Competitive moves concentrate on strategic partnerships for deposition equipment access and portfolio diversification into halogen-free barrier chemistries.
Within the integrated manufacturing tier, Toray Industries and UFlex Limited exemplify contrasting geographic anchoring strategies. Toray represents Japanese captive supply chain models spanning polymer production through oxide deposition. UFlex occupies a position among South Asian converters scaling pharmaceutical qualification capabilities for export markets. Amcor sits within the diversified packaging conglomerate archetype, leveraging healthcare packaging footprints to qualify alternative substrates. Berry Global exemplifies thermoformable barrier specialists competing on protein and dairy format innovation.
| Leading Market Players |
|---|
| UFlex Limited |
| Cosmo Films |
| Toray Industries |
| Tekni-Plex |
| Vibac Group |
| Berry Global |
| Amcor |
| Sigma Technologies Int'l |
| Syensqo |
| Others |
Value Network & Pricing Analysis
The EU Green Deal and REACH restrictions on fluorinated chemistries gate qualified supply for pharmaceutical-grade barrier films, concentrating premium-tier pricing access among converters with pre-qualified oxide-coated substrate capabilities and multi-jurisdiction audit histories.
Pricing Analysis
Input-cost pass-through from organoaluminum precursor volatility and specialized PECVD equipment scarcity shapes contract structures. Three-tier pricing structure across premium, standard, and economy levels separates FDA-audited pharmaceutical grades from food packaging volumes and industrial tiers. Pricing pressure stems from buyer consolidation among multinational contract packagers compressing supplier margins. Food packaging converters exhibit highest price sensitivity; pharmaceutical buyers prioritize qualification security over unit cost.
Supply Chain Analysis
EMA and FDA certification requirements gate supply chain participation, filtering raw material and deposition capacity toward audited converters. Germany, Japan, and the United States anchor specialized equipment and qualified film production. Raw material dependencies center on organoaluminum compounds, silicon precursors, and biaxially oriented polyester substrates. Single-source vulnerability concentrates in German and Japanese PECVD equipment suppliers. Distribution runs through direct frame contracts for pharmaceutical volumes and regional distributors for industrial tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Super Barrier Coated Film Market functions as a stable compounder, with regulatory-mandated fluorinated chemistry phase-out driving steady substrate replacement demand across pharmaceutical packaging networks.
For Market Incumbents: Hedge fluorinated coating obsolescence by accelerating silicon oxide qualification pipelines at FDA-audited plants. Secure deposition equipment slots with German and Japanese suppliers before lead time extensions. Backward integration into organoaluminum precursor supply buffers input cost volatility threatening margin stability. For New Entrants and Emerging Players: Capture cell-cultured protein packaging white space where thermoformable barrier specifications remain unsettled. Target CDSCO-registered facilities near Hyderabad seeking Western-qualified film imports for generic export growth. Lead with digital printing-compatible topcoat integration as a technical differentiation wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier converters with single-site FDA histories and underdeveloped EMA capabilities. Long-term viability favors assets with dual-jurisdiction qualification infrastructure and captive polymer supply. Watch EMA variation submission backlogs as an inflection signal for qualification capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Halogen-Free Barrier Reformulation | REACH compliance deadlines force ceramic oxide migration ahead of fluorinated phase-out timelines. |
| Dual-Jurisdiction Qualification Investment | Simultaneous FDA Type III DMF and EMA variation capabilities capture consolidated buyer procurement. |
| Deposition Equipment Partnership | Long-term offtake agreements with German PECVD suppliers lock scarce capacity against 24-month lead times. |
| Cell-Cultured Protein Format Development | Thermoformable nylon-PE laminations address emerging alternative meat shelf-life requirements. |
| Digital Printing Topcoat Integration | Inkjet-compatible barrier films enable pharmaceutical serialization without secondary labeling operations. |
Research Methodology
Multiple input streams — primary interviews with pharmaceutical packaging engineers, regulatory affairs directors, and vacuum deposition technicians; secondary validation through FDA drug master file databases, EMA submission records, and customs trade data; plus SEC filings from listed converters — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from contract packaging procurement leads to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include substrate chemistry, application performance tier, end-user qualification intensity, and regional regulatory cluster. CAGRs were derived from slope analysis of qualified film adoption curves and pharmaceutical packaging capacity expansion plans.
Regulatory deadline acceleration, deposition equipment delivery delays, and raw material supply disruption are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in EU F-Gas Regulation enforcement timelines or EMA stability documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Middle East and Africa Airless Packaging Market
Packaging Barrier Films
Global Air Bubble Film Machines Market
Packaging Barrier Films
Cross-Linked Shrink Films Market
Packaging Barrier Films
Barrier Tube Packaging Market
Packaging Barrier Films
Barrier Packaging Market
Packaging Barrier Films
Meat Packaging Films Market
Packaging Barrier Films
North America Barrier Films Market
Packaging Barrier Films
Collation Shrink Films Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
Barrier Coatings for Packaging Market
Packaging Barrier Films
Global High Barrier Packaging Films Market
Packaging Barrier Films
Transparent Barrier Films Market
Packaging Barrier Films
Barrier Materials Market