
 North America Packaging Design Services Market | 2026-2036
North America Packaging Design Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Packaging Design Services Market Analytics
Multi-source outsourcing among mid-market consumer brands is expanding as packaging complexity outpaces in-house creative capacity. SmashBrand leverages its vertical specialization in food and beverage packaging to sustain repeat engagement from national grocery chains. Dd.nyc® anchors premium positioning through structural innovation for beauty and spirits clients. Deal Design competes on speed-to-shelf, occupying a niche in rapid-turnaround prototyping for emerging CPG launches.
Packaging design services encompass the creative and engineering discipline of developing protective, communicative, and brand-differentiated containers using substrate specifications, closure mechanics, and print reproduction parameters to achieve retail performance and supply-chain functionality. Structural design and sustainable packaging represent the fastest-expanding service categories, as brands confront resin reduction mandates and e-commerce damage-rate thresholds. Graphic design retains the largest margin pool due to recurring brand-refresh cycles, while prototyping gains share as digital print and 3D mock-up technologies compress development timelines.
The US FDA enforces strict label accuracy and allergen disclosure rules that shape design workflows for food and healthcare clients, while the EPA's recycled content guidelines and Canada's extended producer responsibility frameworks push service providers to document material provenance in every design brief. California's SB 54 plastic pollution reduction law and New York's packaging reduction mandates add state-level compliance layers that design firms must navigate. Stakeholders should monitor how forthcoming federal packaging standard harmonization affects the cost structure of cross-border design execution between US and Canadian markets.
Market Dynamics
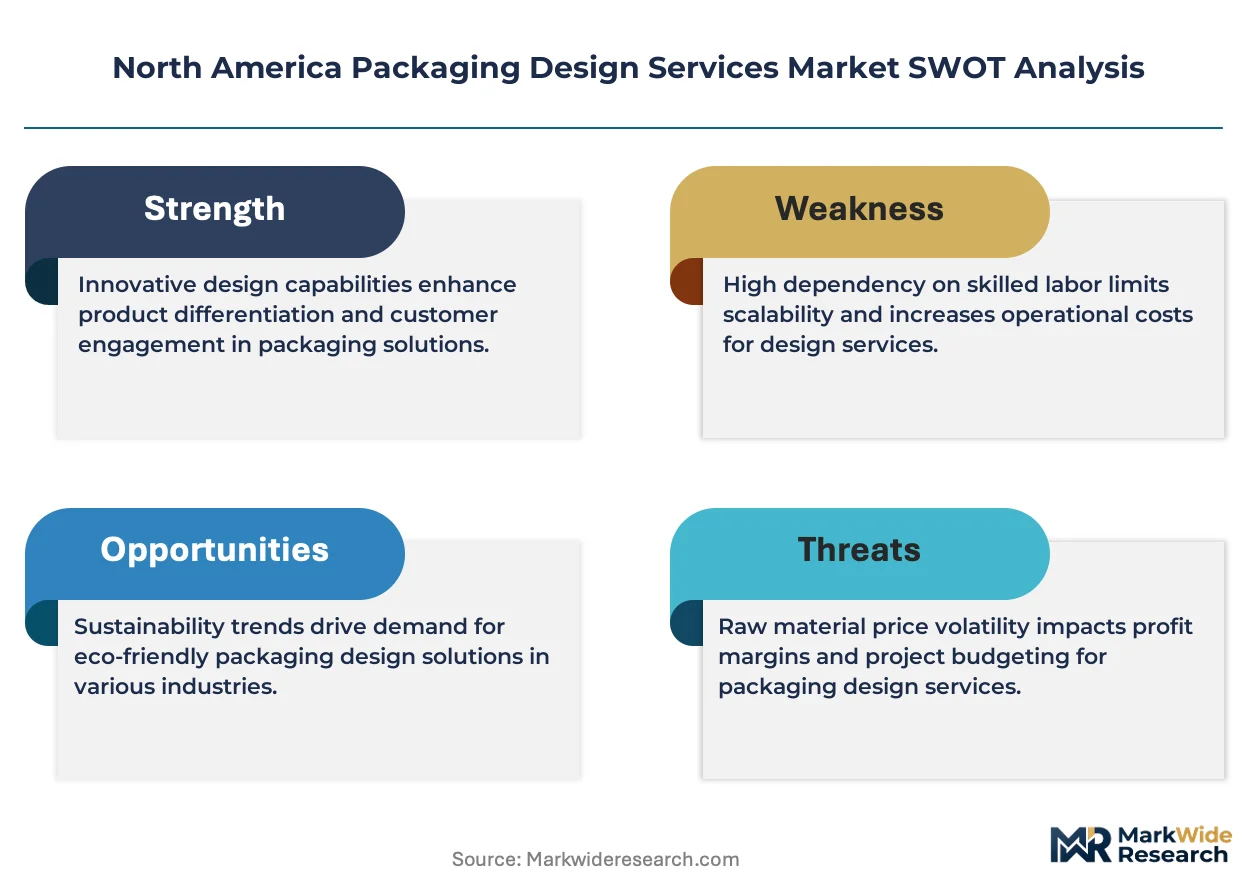
California's SB 54 plastic pollution reduction law and New York's packaging reduction mandates are forcing design firms to restructure creative workflows around material provenance documentation and resin reduction targets, compressing project timelines while elevating technical specification requirements.
Growth Catalysts
- Extended Producer Responsibility frameworks:Canada's provincial EPR programs mandate design-for-recyclability, compelling brands to engage specialized packaging engineers early in concept development.
- E-commerce damage-rate thresholds:Online retail fulfillment networks impose strict performance standards on protective packaging, driving structural innovation investment from food and electronics brands.
- Mid-market CPG headquarters clustering:Concentration of consumer packaged goods firms in California and New York creates localized demand density for premium design services.
Market Restraints
- Recycled substrate cost volatility:Post-consumer resin pricing fluctuations compress margins on sustainable packaging briefs, particularly for emerging CPG brands with fixed marketing budgets.
- Pre-press technical talent scarcity:Shortage of specialists proficient in both structural engineering and print reproduction parameters limits service capacity expansion.
- Cross-border regulatory friction:Divergent US FDA and Health Canada labeling requirements increase compliance overhead for brands operating in both markets.
Strategic Opportunities
- US-Mexico nearshoring corridors:Manufacturing relocation to Mexico creates demand for bilingual packaging specifications serving dual-market distribution.
- Digital print convergence with 3D mock-up technologies:Compressed prototyping timelines enable rapid-turnaround service tiers for emerging brand launches.
- US EPA recycled content guidelines:Federal procurement standards create certified-design service premiums for healthcare and institutional foodservice clients.
Industry Challenges
- Structural-graphics hybrid skill gaps:Few designers possess integrated expertise in both engineering mechanics and brand visual systems, forcing costly team staffing.
- Legacy ERP integration friction:Design workflow software often fails to connect with client material resource planning systems, creating data reconciliation delays.
- State-level compliance fragmentation:Patchwork of California, New York, and Canadian provincial mandates multiplies documentation burden without harmonized federal standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Packaging Design Services Market |
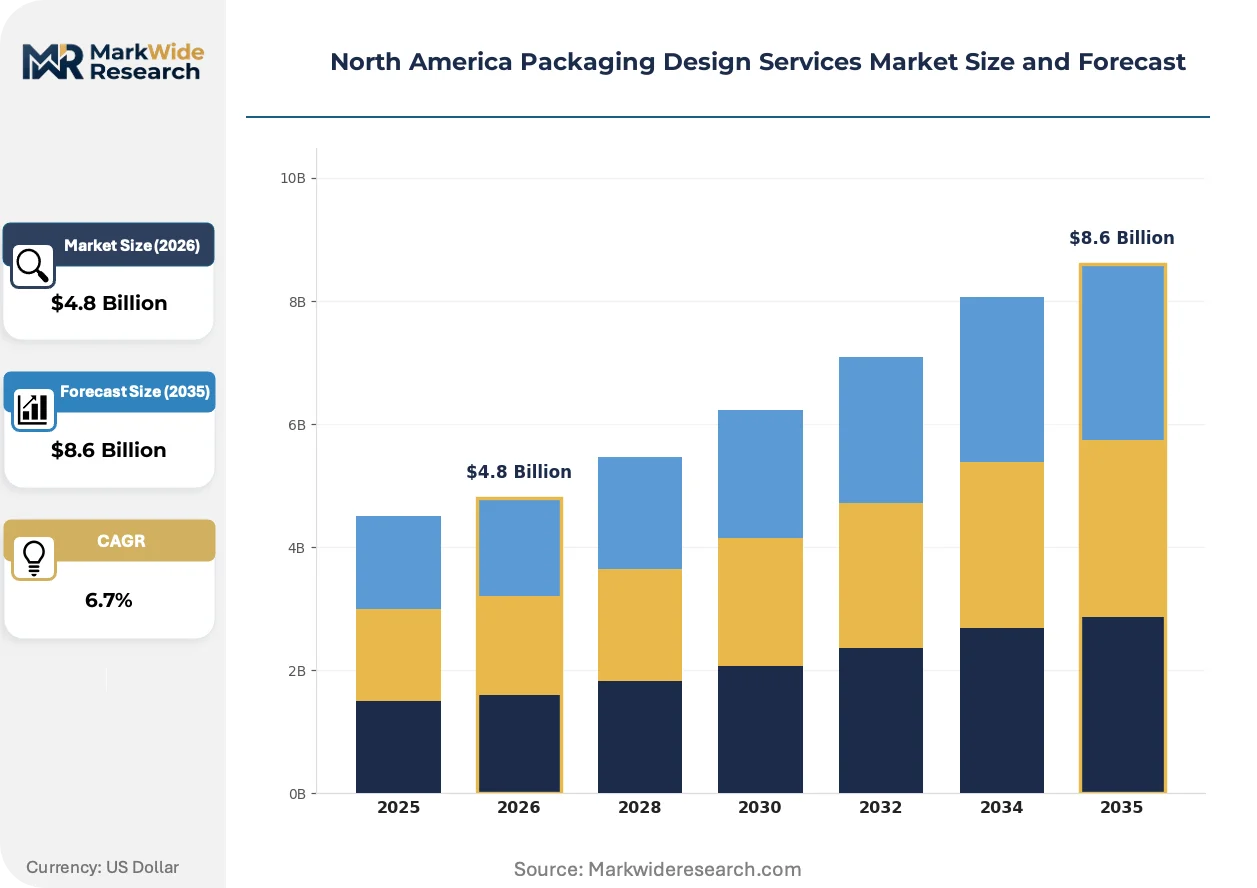
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Graphic Design, Structural Design, Prototyping, Market Research Industry Vertical: Food & Beverage, Personal Care, Consumer Electronics, Healthcare Packaging Type: Flexible Packaging, Rigid Packaging, Labels, Sustainable Packaging Delivery Model: In-House, Outsourced, Freelance, Hybrid |
| Companies Covered | Dd.nyc®, Designed.co, Deal Design, SmashBrand, Bex Brands, DEI Creative, Arhue, Murmur Creative, Ruckus Marketing, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Packaging Design Services Market Evolving Landscape
Generative design algorithms and substrate simulation software are compressing the concept-to-prototype cycle, while regulatory pressure on material provenance is embedding compliance documentation directly into creative workflows.
AI-powered structural optimization is consolidating multiple design iterations into single-pass engineering outputs. Food and beverage brands with high-SKU portfolios are adopting these tools to accelerate seasonal packaging refreshes. The technology is consolidating previously separate graphic and engineering review stages into unified approval workflows, reducing revision cycles by eliminating handoff friction between creative and technical teams.
The US FDA's updated Nutrition Facts label format and serving-size disclosure rules are mandating larger panel real estate for regulatory content. This industrial consequence forces brands to sacrifice brand messaging space or expand package dimensions, directly affecting material cost and shelf presence. Healthcare and functional food categories are responding by adopting extended-label formats and peel-back constructions that preserve regulatory compliance without compromising brand visibility.
Retailer-specific sustainability scorecards are altering how CPG brands select design partners. Walmart's packaging sustainability playbook and Target's preferred material guidelines now function as de facto procurement filters, displacing pure aesthetic criteria with documented lifecycle metrics. This behavior shift concentrates design spending among service providers with certified material databases and third-party validation capabilities, with California and Pacific Northwest retail corridors showing the earliest adoption intensity.
North America Packaging Design Services Market Segmentation
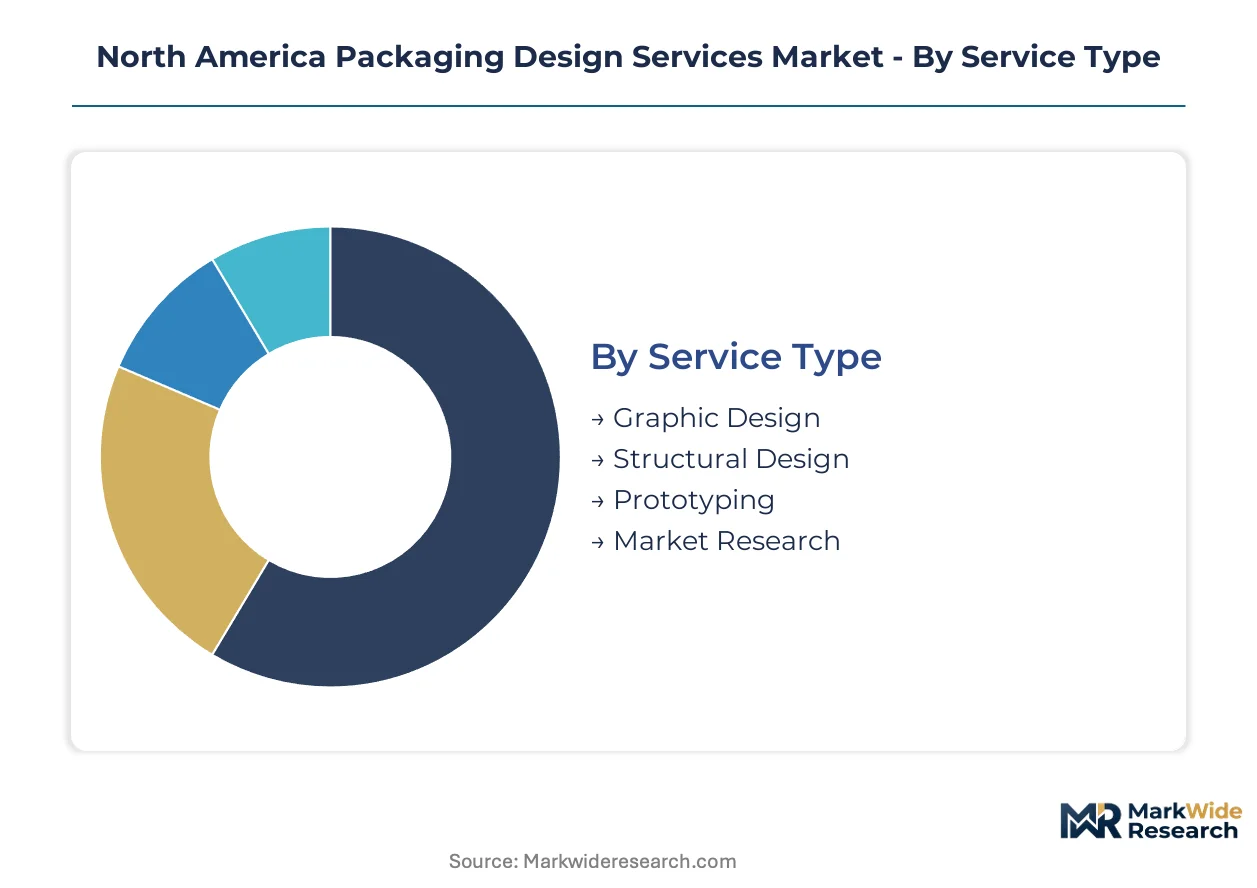
Packaging design services fragment across four operational dimensions that determine resource allocation, margin capture, and client retention. Each segmentation axis reveals distinct competitive dynamics: service type governs technical staffing ratios, industry vertical shapes regulatory compliance intensity, packaging type dictates material science capabilities, and delivery model defines client relationship economics.
Service Type:
Supply concentration in graphic design services anchors revenue stability for established studios, while structural design commands premium pricing through scarce engineering talent.
- Graphic Design:Visual identity systems, color reproduction protocols, and brand asset management constitute the core deliverable. California CPG headquarters and New York beauty clusters sustain recurring refresh cycles. FDA label format updates force panel reconfigurations that preserve design firm relevance through compliance-driven revisions.
- Structural Design:Engineering mechanics, substrate specification, and closure systems integration define this technical tier. E-commerce damage-rate thresholds from Amazon and Target fulfillment networks drive demand for protective geometry innovation. Canada's EPR frameworks mandate early-stage recyclability engineering that only structural specialists can document.
- Prototyping:3D mock-up production and digital print sampling compress development timelines for emerging brand launches.
- Market Research:Shelf-impact testing and consumer eye-tracking studies inform design briefs prior to creative execution.
Graphic design absorbs the bulk of installed capacity; structural design is expanding most quickly.
Industry Vertical:
Cost tier differentiation separates premium healthcare compliance work from high-volume food and beverage production cycles.
- Food & Beverage:SKU-intensive portfolios with seasonal refresh demands dominate procurement volume. FDA Nutrition Facts label mandates and allergen disclosure rules consume substantial design panel real estate. SmashBrand and comparable specialists build repeat engagement through vertical expertise in national grocery chain requirements.
- Healthcare:Regulatory stringency elevates documentation burdens and extends approval timelines. FDA device labeling and Health Canada medical device regulations require specialized compliance workflows that generalist studios cannot execute. Extended-label formats and peel-back constructions preserve brand visibility under strict disclosure mandates.
- Personal Care:Aesthetic differentiation drives premium positioning for beauty and spirits categories.
- Consumer Electronics:Protective packaging performance standards align with e-commerce fulfillment damage thresholds.
Food and beverage commands the deepest client roster; healthcare is climbing the fastest as regulatory complexity intensifies.
Packaging Type:
Application requirements dictate whether brands prioritize barrier properties, structural integrity, or circularity credentials in design briefs.
- Sustainable Packaging:Material provenance documentation and resin reduction targets now embed directly into creative workflows. California SB 54 mandates and New York reduction laws force substrate substitution analysis at concept stage. Walmart and Target sustainability scorecards filter vendor selection toward certified material databases.
- Flexible Packaging:Film substrates and pouch geometries serve food and personal care with lightweight distribution economics.
- Rigid Packaging:Bottle, jar, and container engineering concentrates in healthcare and premium spirits segments.
- Labels:Pressure-sensitive and shrink-sleeve formats retain distinct pre-press technical requirements.
Flexible packaging retains the largest production volume; sustainable packaging shows the steepest expansion trajectory as EPR frameworks mature.
Delivery Model:
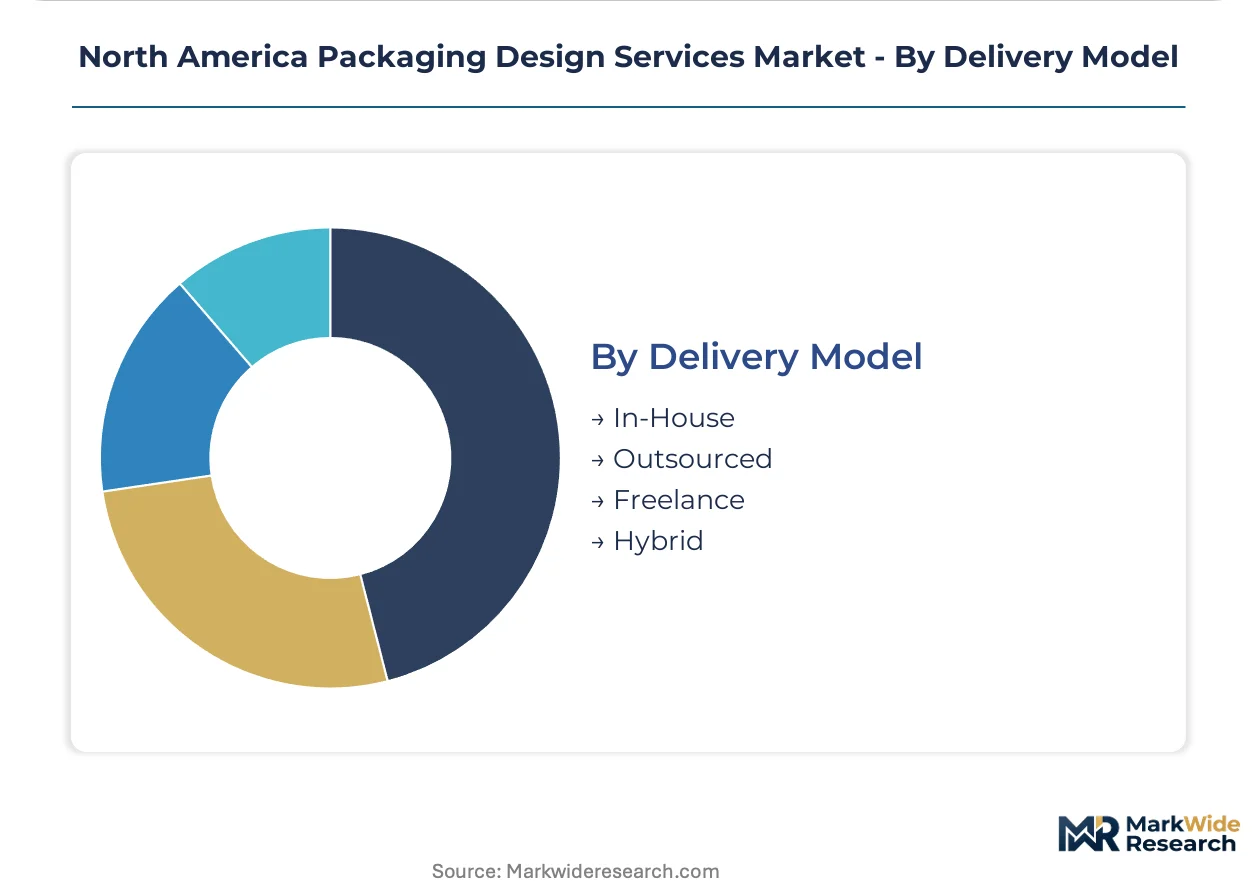
Customer type and project scale determine whether brands maintain captive studios, engage agency retainers, or deploy contingent talent.
- Outsourced:Specialized agencies like Dd.nyc® and Deal Design capture premium and speed-tier positioning respectively. National CPG brands with limited internal engineering capacity rely on external partners for structural innovation and regulatory navigation.
- In-House:Large beverage and personal care conglomerates maintain captive studios for core brand stewardship.
- Freelance:Independent designers serve emerging CPG launches with limited procurement authority.
- Hybrid:Blended staffing models combine strategic agency oversight with contingent execution capacity.
Outsourced delivery captures the majority of specialized structural and sustainable design spending; hybrid models are gaining share fastest as brands seek flexibility without full agency overhead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Post-consumer resin supply chains concentrate in the Great Lakes and Gulf Coast corridors, anchoring packaging design demand near material processing infrastructure. The United States and Canada dominate regional procurement, with Mexico emerging as a nearshoring destination reshaping cross-border specification workflows.
United States
CPG headquarters clustering in California and New York generates concentrated demand for premium design services. FDA Nutrition Facts label mandates and California's SB 54 plastic pollution reduction law force substrate substitution analysis at concept stage. Los Angeles and New York City host the deepest agency ecosystems serving national grocery and beauty brand portfolios.
Canada
Provincial Extended Producer Responsibility programs mandate design-for-recyclability documentation that only specialized engineers can execute. Health Canada labeling requirements diverge from FDA standards, increasing compliance overhead for cross-border brands. Toronto and Montreal anchor the national design capacity serving healthcare and foodservice clients.
Mexico
Manufacturing relocation from Asia creates demand for bilingual packaging specifications serving dual-market distribution. The country's federal consumer protection agency enforces labeling transparency rules that align with US trade compliance frameworks. Nuevo León and Mexico City concentrate design support services for export-oriented maquiladora operations.
North America Packaging Design Services Market Competitive Landscape
Vertical specialization dominates the current landscape as agencies carve defensible positions around industry expertise and regulatory navigation. The vendor base organizes into three functional tiers: full-service studios with structural engineering depth, boutique creative shops competing on speed-to-shelf, and hybrid models blending strategic oversight with contingent execution. Strategic archetypes include compliance-forward specialists serving healthcare and food clients, sustainability-certified practices capturing EPR-driven procurement, and rapid-turnaround prototyping shops targeting emerging CPG launches. M&A activity and certified material database investments represent the dominant competitive moves as scale and validation capabilities separate winners from generalists.
Within the vertical specialization tier, SmashBrand exemplifies food and beverage focus through repeat engagement patterns with national grocery chains, while Dd.nyc® anchors premium positioning through structural innovation capabilities. Deal Design occupies a distinct velocity niche, competing on compressed prototyping timelines for emerging brand launches. These three entities represent the strategic diversity—vertical depth, premium engineering, and speed—that defines current competitive positioning across the North American market.
| Leading Market Players |
|---|
| Dd.nyc® |
| Designed.co |
| Deal Design |
| SmashBrand |
| Bex Brands |
| DEI Creative |
| Arhue |
| Murmur Creative |
| Ruckus Marketing |
| Others |
Value Network & Pricing Analysis
National grocery chain procurement teams concentrate design spending among certified providers, anchoring a project-based pricing model that stratifies across premium engineering, standard creative, and economy prototyping tiers. California SB 54 compliance documentation and resin reduction mandates compress margins on sustainable briefs while elevating technical specification premiums.
Pricing Analysis
Warranty-style compliance guarantees now bundle regulatory validation with base creative fees, leaving material prototyping and rush revisions as unbundled add-ons. Three-tier pricing structure across premium structural engineering, standard graphic design, and economy digital prototyping reflects certification grade and vertical specialization depth. Pricing pressure stems from recycled substrate cost volatility squeezing fixed-budget emerging CPG clients. Mid-market food brands show highest price sensitivity; healthcare and spirits clients demonstrate lowest.
Supply Chain Analysis
Reverse-logistics flows for mock-up returns and prototype refurbishment concentrate in Los Angeles and New York City studio networks, with digital print waste streams feeding regional recycling cooperatives. Post-consumer resin supply draws from Great Lakes and Gulf Coast processing corridors. Design workflow software dependencies rest on Adobe Creative Cloud and specialized CAD platforms vulnerable to licensing cost escalation. Distribution runs through direct client-agency relationships supplemented by freelance platform intermediaries for contingent talent.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around certified material database capabilities, with California and New York regulatory fragmentation forcing generalist studios toward acquisition or exit.
For Market Incumbents: Acquire certified material database assets and third-party validation partnerships to defend against sustainability-scorecard procurement filters at Walmart and Target. Build bilingual specification capabilities for US-Mexico nearshoring corridors before manufacturing relocation accelerates. Lock structural engineering talent through equity participation given pre-press technical scarcity. For New Entrants and Emerging Players: The gap between premium structural engineering rates and economy graphic design pricing opens white space in rapid-turnaround prototyping for emerging CPG launches. Target Pacific Northwest retail corridors where sustainability mandates concentrate earliest adoption intensity. Enter through digital print convergence partnerships that compress concept-to-mock timelines without full engineering overhead. For Investors and Strategic Acquirers: The window for entry favors vertical specialists with documented EPR compliance workflows and repeat national grocery chain engagement. Long-term viability hinges on regulatory navigation capabilities deepening across federal and state-level mandate proliferation. Monitor Health Canada-FDA labeling harmonization negotiations as inflection signal for cross-border execution cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Material Database Investment | Walmart and Target sustainability scorecards now filter vendor selection toward validated lifecycle metrics providers. |
| Structural Engineering Talent Acquisition | Scarce pre-press specialists proficient in both engineering mechanics and print reproduction limit service capacity expansion. |
| Bilingual Specification Capability Buildout | US-Mexico nearshoring corridors create demand for dual-market packaging documentation serving maquiladora operations. |
| Digital Print Convergence Partnership | 3D mock-up technologies compress development timelines and enable rapid-turnaround service tiers for emerging brands. |
| Extended Producer Responsibility Compliance Integration | Canada's provincial EPR programs mandate design-for-recyclability documentation that only specialized engineers execute. |
Research Methodology
Document review covered FDA labeling guidance documents, EPA recycled content guidelines, California SB 54 regulatory filings, and Canadian provincial EPR program specifications, complemented by interviews with packaging design firm principals, CPG brand managers, retail sustainability procurement leads, and pre-press technical specialists. Secondary sources included customs records, SEC filings from publicly traded design holding companies, and Nielsen retail audit data. Bottom-up service provider capacity estimates triangulated against top-down CPG marketing spend allocations.
Market sizing and growth projections derived from segment-level modeling across service type, industry vertical, packaging type, and delivery model dimensions, with additional stratification by US state and Canadian province regulatory clusters. CAGRs were computed from historical spending patterns and projected compliance-driven refresh cycles. Forecast inputs incorporated e-commerce damage-rate threshold evolution and generative design algorithm adoption curves.
Inputs from FDA and Health Canada regulatory databases were available through the study window; gaps in real-time CPG procurement contract terms introduce uncertainty bands around outsourced delivery model share estimates. Forecasts reflect assumptions regarding sustained state-level regulatory fragmentation and federal harmonization timeline delays. Practitioners should monitor forthcoming EPA packaging standard proposals and US-Mexico trade compliance framework updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Foam Labels Market
Packaging
Strap Dispenser Market
Packaging
Plastic T-Shirt Bags Market
Packaging
Hydrocolloid Coating Market
Packaging
Congo Container Glass Market
Packaging
Global Wrapping Machine Market
Packaging
Toilet Roll Converting Lines Market
Packaging
Tape Stretching Line Market
Packaging
Tray and Sleeve Packing Machines Market
Packaging
Metal Pails Market
Packaging
Plastic Ready Meal Trays Market
Packaging
Light Density Polyethylene (LDPE) Bottles Market
Packaging
Pallet Shippers Market
Packaging
Hygiene Packaging Films Market
Packaging
Dispensing Carboy Market
Packaging
Plastic Vials and Ampoules Market