
 Packaging Barrier Films Market | 2026-2036
Packaging Barrier Films Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Barrier Films Market Intelligence
Development of recyclable mono-material barrier structures is rewriting competitive positioning for film converters. Amcor plc leverages its extensive global manufacturing footprint to supply consistent specifications to multinational food and beverage clients. Toray Industries Inc. specializes in advanced polymer science, particularly for high-performance electronics and medical applications. Meanwhile, Mondi Group differentiates with an integrated portfolio that includes both flexible plastic and paper-based barrier solutions, addressing diverse sustainability targets.
Packaging barrier films are flexible or semi-rigid structures engineered to control the transmission of elements like oxygen, water vapor, and aroma. These films often incorporate specialized layers, such as Ethylene Vinyl Alcohol (EVOH) or metallized coatings, to achieve specific Oxygen Transmission Rate (OTR) and Water Vapor Transmission Rate (WVTR) targets. While multilayer film constructions remain dominant in volume, innovations in coated films are gaining traction. The food and beverage application represents the largest end-use market, whereas the pharmaceuticals segment demands the highest performance and strictest quality control.
Regulatory frameworks such as the US FDA's requirements for food-contact substances and the EU's REACH regulation directly influence material selection and product design. These standards mandate rigorous testing for chemical migration and overall safety, shaping the polymers and additives used by manufacturers. Balancing the need for high-barrier performance against the growing imperative for material simplification and recyclability is the central strategic challenge for film developers and converters.
Market Dynamics
The central dynamic shaping the packaging barrier films market is the structural tension between the need for high-performance, multi-material constructions for product protection and the regulatory and consumer pressure for simplified, recyclable mono-material solutions.
Growth Catalysts
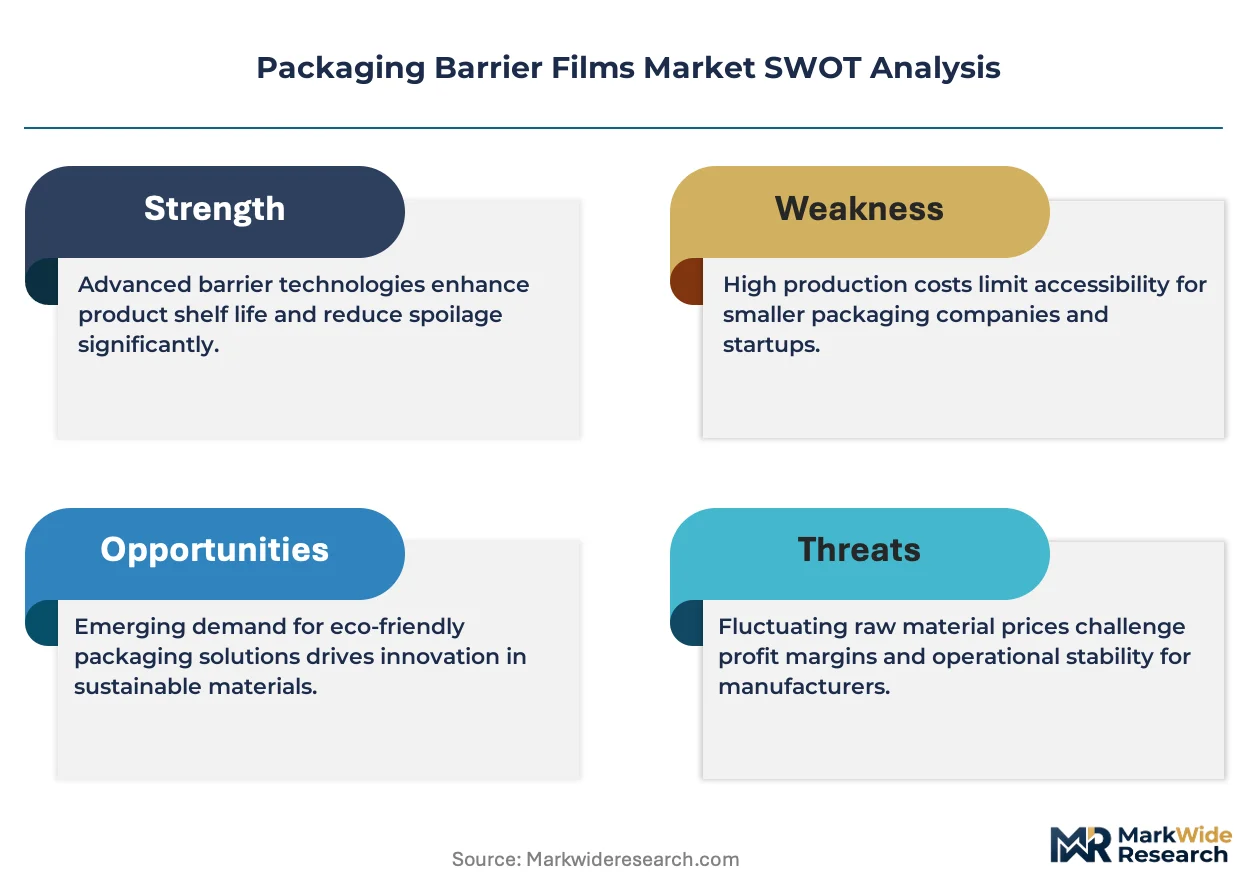
- Regulatory Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) accelerates investment in mono-material films as companies seek to improve their reported recyclability metrics and meet circular economy targets.
- Pharmaceutical Demand:The global pharmaceuticals industry requires advanced barrier films to extend drug shelf life and protect sensitive biologics, driving innovation in high-performance materials compliant with strict regulatory standards.
- Food Sector Expansion:Rapid growth in the food and beverage processing sectors across Southeast Asian countries, including Vietnam and Indonesia, expands the addressable market for flexible packaging films.
Market Restraints
- Performance Trade-Offs:Mono-material films inherently struggle to replicate the superior oxygen and moisture barrier properties of traditional multi-layer structures, limiting their use in the most demanding applications.
- Raw Material Volatility:Price fluctuations and supply chain concentration for key barrier polymers, such as Ethylene Vinyl Alcohol (EVOH), create cost instability for film converters and their customers.
- Recycling Infrastructure Gaps:The lack of widespread, standardized collection and sorting infrastructure for flexible plastic films impedes the development of a truly circular economy, even for technically recyclable materials.
Strategic Opportunities
- Advanced Coating Technologies:Developing transparent barrier coatings like silicon oxide (SiOx) or aluminum oxide (AlOx) allows converters to enhance the performance of recyclable mono-material films, bridging the performance gap.
- Electronics Packaging:There is a significant opportunity to develop specialized barrier films for packaging sensitive electronic components, offering protection from moisture, oxygen, and electrostatic discharge during shipping and storage.
- Bio-based Polymers:Formulating barrier films from renewable, bio-based polymers offers a path to reduce carbon footprint and appeal to sustainability-focused brand owners, particularly in European markets.
Industry Challenges
- Capital Investment Cycles:The high capital expenditure needed to retool manufacturing lines from co-extrusion to advanced coating or mono-material film production presents a significant financial hurdle for many converters.
- Regulatory Fragmentation:Navigating divergent food-contact safety regulations and chemical migration testing protocols between jurisdictions, such as the US FDA and the European Food Safety Authority (EFSA), adds complexity and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Barrier Films Market |
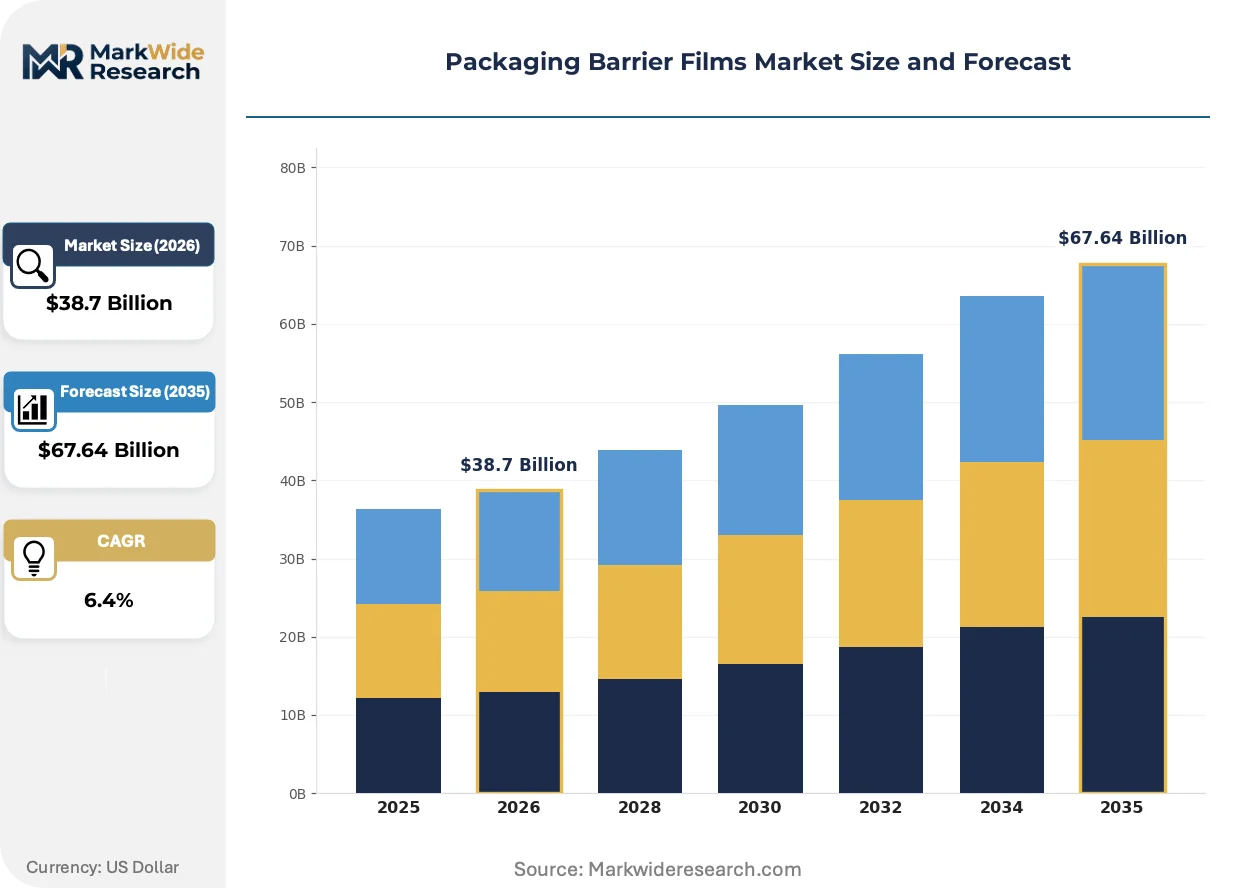
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Multilayer, Metallized, Coated, Extruded, Laminate Material: Polyethylene Terephthalate, Polyvinylidene Chloride, Polyethylene, Ethylene Vinyl Alcohol, Polypropylene Application: Food & Beverage, Personal Care, Pharmaceuticals, Electronics, Chemicals End User Industry: Fast-Moving Consumer Goods, Cosmetics Manufacturers, Drug Formulators, Electronic Devices Assemblers, Specialty Chemicals Producers |
| Companies Covered | Amcor plc, Berry Global Inc., Sealed Air Corporation, Mondi Group, Huhtamaki Group, Uflex Ltd., Toray Industries Inc., Toppan Printing Co. Ltd., Winpak Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Barrier Films Market Strategic Shifts & Innovations
Material science innovation is focused on resolving the conflict between barrier performance and end-of-life recyclability. This pursuit defines the development pipeline and dictates which technologies gain commercial traction in a sustainability-conscious market.
Advanced coating technologies, such as plasma-deposited silicon oxide (SiOx), provide an ultra-thin, transparent barrier layer. Food and pharmaceutical brand owners are adopting these solutions to meet recyclability commitments without compromising product integrity. The market's core material science is migrating from complex multi-layer laminates toward functionalized mono-material substrates that are compatible with existing recycling streams.
The European Union's REACH regulation governs the use of chemical substances, directly influencing the polymers and additives available to film manufacturers. This framework compels producers to validate the safety of all inputs and seek alternatives for any substances of very high concern (SVHCs). The food packaging segment is most affected, as converters must ensure full compliance and traceability to supply multinational CPG clients operating in the EU.
Brand owners are altering their procurement criteria, prioritizing certified recyclable structures over solutions based purely on cost or barrier function. This shift disrupts legacy supply chains, favoring converters who can provide end-to-end documentation on material composition and compatibility with regional recycling systems. This trend is most visible in the consumer goods sectors of North America and Europe, where corporate sustainability pledges are a primary purchasing driver.
Packaging Barrier Films Market Segmentation
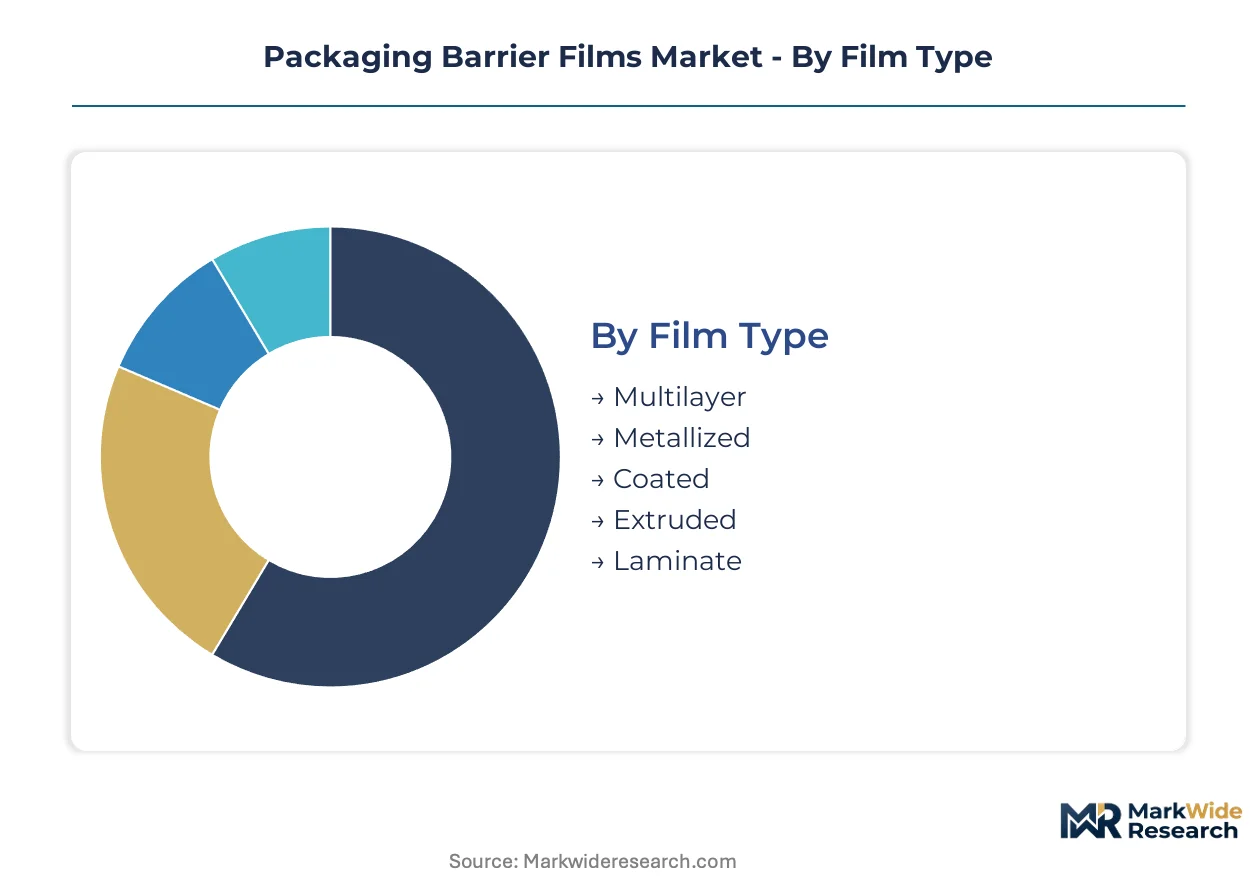
The packaging barrier films market exhibits diverse segmentation, reflecting the varied functional requirements across numerous end-use applications. Understanding these distinct segments is crucial for manufacturers to tailor product development and market strategies effectively.
Film Type:
The spectrum of film constructions addresses diverse product protection requirements across the market.
- Multilayer:These films combine multiple polymer layers to achieve superior barrier properties against oxygen and moisture. Demand concentrates in the global food and beverage sector, driven by extended shelf life requirements for perishable goods.
- Coated:Coated films feature a thin, functional layer applied to a base substrate, often enhancing barrier performance or recyclability. Pharmaceutical packaging increasingly adopts these solutions to protect sensitive drug formulations while meeting sustainability targets.
- Metallized:Metallized films incorporate a vacuum-deposited metal layer, typically aluminum, providing excellent oxygen and light barrier.
- Extruded:Extruded films are produced by forcing molten polymer through a die, forming continuous sheets or tubes for general packaging.
- Laminate:Laminate films bond two or more flexible substrates together, creating composite structures with enhanced strength and barrier.
Established volume favors Multilayer films; emerging adoption favors Coated films.
Material:
Supply concentration for barrier film materials reflects both established commodity volumes and specialized high-performance polymers.
- Polyethylene:Polyethylene is a widely used thermoplastic polymer, offering flexibility, moisture barrier, and heat sealability for various packaging applications. Its significant volume in the food packaging sector, particularly across Southeast Asian countries, underpins broad market demand.
- Ethylene Vinyl Alcohol:EVOH provides exceptional oxygen barrier properties, critical for preserving oxygen-sensitive products like processed meats and dairy. Strict regulatory standards for pharmaceuticals drive its specialized use in protective blister packs and sachets.
- Polyethylene Terephthalate:PET offers good clarity, stiffness, and moderate barrier, frequently used in rigid and semi-rigid packaging.
- Polyvinylidene Chloride:PVDC delivers high barrier to oxygen and water vapor, although its use faces scrutiny due to end-of-life concerns.
- Polypropylene:PP provides good heat resistance and stiffness, finding applications in snack packaging and retort pouches.
Commodity materials like Polyethylene maintain significant market presence, while specialized polymers such as Ethylene Vinyl Alcohol command premium applications.
Application:
Customer demand for packaging barrier films spans critical sectors, each with distinct performance and regulatory requirements.
- Food & Beverage:This application segment represents the largest end-use market, requiring films to extend shelf life, prevent spoilage, and maintain product freshness. Rapid growth in processing capabilities across Vietnam and Indonesia significantly boosts demand for these films.
- Pharmaceuticals:The pharmaceuticals segment demands the highest barrier performance and strictest quality control to protect sensitive drug formulations from degradation. Stringent US FDA and European EMA regulations drive innovation in specialized high-barrier films.
- Personal Care:Personal care products utilize barrier films to protect cosmetics and toiletries from moisture, oxygen, and light exposure.
- Electronics:Electronics packaging employs barrier films to shield sensitive components from moisture, static, and physical damage during transit.
- Chemicals:The chemicals sector uses barrier films for safe containment and transport of various industrial and specialty chemical products.
The Food & Beverage application dominates volume, while Pharmaceuticals represents the fastest-growing trajectory in terms of performance innovation.
End User Industry:
The maturity of end-user industries dictates their procurement scale and their specific needs for advanced barrier packaging solutions.
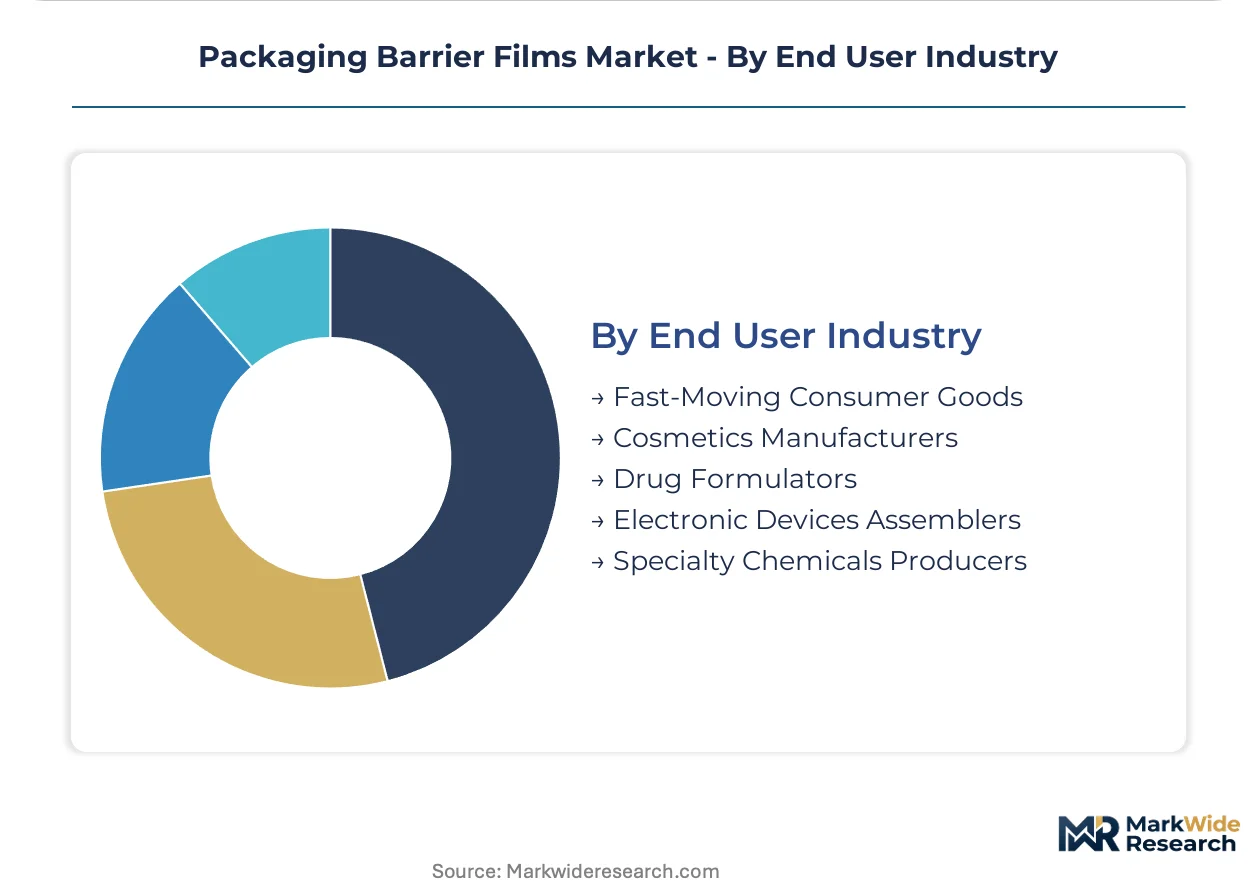
- Fast-Moving Consumer Goods:FMCG companies require high-volume, cost-effective barrier films for packaging everyday products across food, beverage, and personal care categories. Their global supply chains necessitate consistent film specifications from manufacturers like Amcor plc.
- Drug Formulators:Drug formulators demand highly specialized barrier films that ensure drug stability, prevent contamination, and comply with strict regulatory standards. Their focus on product integrity drives investment in advanced materials and rigorous testing protocols.
- Cosmetics Manufacturers:Cosmetics manufacturers utilize barrier films to preserve product efficacy and extend shelf life for beauty and skincare items.
- Electronic Devices Assemblers:These assemblers rely on barrier films for protective packaging of sensitive electronic components during manufacturing and shipping.
- Specialty Chemicals Producers:Specialty chemicals producers use barrier films for safe and compliant packaging of diverse chemical compounds.
Established players in Fast-Moving Consumer Goods drive significant film volumes, whereas Drug Formulators prioritize specialized, high-performance solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The packaging barrier films market exhibits varying demand elasticity, with pharmaceutical applications commanding premium pricing and consumer goods segments demonstrating greater price sensitivity. Regional market dynamics reflect diverse regulatory landscapes and differing levels of investment in circular economy infrastructure.
United States
Demand for advanced barrier films in the United States stems from pharmaceutical and specialized food packaging needs. The US FDA mandates rigorous testing for food-contact substances and drug packaging. Major pharmaceutical clusters in states like New Jersey and California drive innovation in high-performance materials. These regions prioritize solutions that extend shelf life for sensitive products.
Germany
European demand for barrier films focuses on sustainable solutions for food and beverage applications. Germany's REACH regulation directly influences polymer and additive selection for packaging materials. Industrial centers like those in North Rhine-Westphalia are developing mono-material recyclable film technologies. This region emphasizes compliance with circular economy targets.
China
China's expanding food processing sector fuels significant demand for packaging barrier films across various categories. The NMPA regulates food-contact materials and pharmaceutical packaging within the country. Manufacturing hubs in the Yangtze River Delta are scaling up production for both domestic and export markets. This concentration supports rapid market expansion.
India
India's pharmaceutical industry requires high-performance barrier films for drug stability and shelf life. The CDSCO sets standards for pharmaceutical packaging materials in the country. Cities like Hyderabad and Ahmedabad, with their strong pharma presence, are key consumption centers. These areas drive specialized film procurement.
Southeast Asia
The rapid growth of food and beverage processing across Southeast Asian countries, particularly Vietnam and Indonesia, drives extensive film demand. Local regulations from ministries of health guide food packaging safety standards. Industrial parks near Ho Chi Minh City and Jakarta are increasing flexible packaging production. This regional expansion offers significant market opportunities.
Packaging Barrier Films Market Key Industry Players
Vertically integrated manufacturers and specialized film converters split the market for packaging barrier films. Large-scale global players often leverage extensive manufacturing footprints, while niche innovators focus on advanced material science. Dominant competitive moves include strategic partnerships for sustainability initiatives and continuous investment in research and development for next-generation barrier technologies. The market structure favors both broad portfolio providers and highly specialized solution providers.
Within the global packaging sector, Amcor plc exemplifies a multinational player with an extensive manufacturing presence, serving diverse end-use markets. Toray Industries Inc. represents a materials science innovator, specializing in advanced polymer technologies for high-performance applications. Meanwhile, Mondi Group occupies a position as an integrated provider, offering a balanced portfolio of both plastic and paper-based barrier solutions. These companies anchor different strategic archetypes within the industry.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Sealed Air Corporation |
| Mondi Group |
| Huhtamaki Group |
| Uflex Ltd. |
| Toray Industries Inc. |
| Toppan Printing Co. Ltd. |
| Winpak Ltd. |
| Others |
Cost & Logistics Intelligence
Trans-Pacific freight routes' cost dynamics directly influence the pricing of specialty barrier polymers, connecting supply concentration in Asia to downstream price differentiation for packaging films globally. This interconnectedness shapes manufacturers' margins and end-user procurement strategies.
Pricing Analysis
Technical support services for film integration and regulatory compliance represent a critical after-sales revenue tier, enhancing the lifetime value of barrier film solutions for brand owners. The dominant pricing model is contract-based long-term offtake, particularly for large-volume customers. Price differentiation stems from certification levels, such as US FDA food-contact approval, and the degree of customization required for specific barrier performance. Pricing pressure stems from the push for more cost-effective mono-material solutions, while raw material volatility introduces upward cost instability. Fast-Moving Consumer Goods (FMCG) segments exhibit the highest price sensitivity, while pharmaceutical clients prioritize performance and regulatory compliance over cost.
Supply Chain Analysis
The EU's REACH regulation, acting as a form of restricted-technology control, limits the use of certain chemical substances, directly influencing material flows for barrier film components into European markets. Geographic supply concentration for base polymers like polyethylene centers in Southeast Asia, while specialized materials such as Ethylene Vinyl Alcohol (EVOH) are primarily sourced from Japan and the United States. Raw material dependencies include both commodity polymers and advanced barrier coatings like silicon oxide (SiOx). A significant supply chain risk is commodity price volatility for key polymer inputs. Distribution often runs through direct sales channels to large film converters and brand owners, supplemented by regional distributors for smaller-volume applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The packaging barrier films market is experiencing high-growth disruption, primarily driven by the EU's Corporate Sustainability Reporting Directive (CSRD) accelerating the shift towards recyclable mono-material solutions.
For Market Incumbents:Harden investment in advanced R&D for next-generation mono-material barrier films that meet stringent performance criteria. Secure long-term supply contracts for specialized barrier resins to mitigate raw material price volatility. Expand manufacturing capabilities in strategic regions like Southeast Asia to serve expanding food and beverage processing sectors. This defends against emerging niche innovators offering specialized sustainable solutions.
For New Entrants and Emerging Players:Build out specialized coating technologies, such as plasma-deposited SiOx, to enhance the barrier properties of recyclable films. Target the pharmaceuticals and electronics packaging segments, which demand high performance and are less price-sensitive. Leverage bio-based polymers and certified compostable solutions to penetrate European markets, where sustainability pledges are a primary purchasing driver.
For Investors and Strategic Acquirers:Specialized film converters with proprietary coating intellectual property present attractive acquisition targets for long-term value creation within the sustainability-driven packaging market. These firms offer differentiated technology that bridges the performance gap for mono-materials. A key signal to watch is increased M&A activity involving companies with patents in transparent barrier coatings or advanced bio-polymer formulations, indicating accelerated industry consolidation around these technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Enhances brand reputation and meets circular economy targets for multinational FMCG clients. |
| R&D Investment in Mono-Materials | Develops high-performance recyclable films, addressing the core tension between barrier and sustainability. |
| Strategic Partnership with Bio-Polymer Producers | Secures access to renewable materials, reducing carbon footprint for packaging solutions. |
| Capacity Expansion in Southeast Asia | Captures extensive film demand from the rapidly growing food and beverage processing sectors. |
| Regulatory Approval Pathway Acceleration | Ensures new barrier film materials comply with US FDA and EU REACH standards for critical applications. |
Research Approach
Initial hypotheses were tested against primary input from R&D directors, procurement managers, regulatory affairs specialists, and brand owners across the packaging value chain, and refined through iterative feedback. This involved combining insights from in-depth interviews with rigorous secondary validation. Secondary data sources included SEC 10-K filings of major packaging companies, EU REACH compliance documents, US FDA guidance for food-contact substances, and reports from global packaging trade associations. Both bottom-up and top-down triangulation methods were employed to ensure data consistency.
The analytical framework modeled the demand-supply balance for packaging barrier films across the analysis window, integrating various market forces. Segmentation dimensions modeled included film type, material, application, end-user industry, and regional regulatory compliance. Compound Annual Growth Rates (CAGRs) were derived from historical growth patterns and future projections, incorporating insights from industry experts. Key forecast inputs included projected polymer prices, regulatory timelines for plastic reduction mandates, and regional economic growth forecasts impacting end-user industries.
Stress conditions across raw material cost spikes, major regulatory shifts, and geopolitical instability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements in barrier coatings and the pace of circular economy infrastructure development. Material shifts in global trade policies or widespread new plastic bans would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Europe Barrier Coated Paper Market
Packaging Barrier Films
Collation Shrink Films Market
Packaging Barrier Films
Modified Atmosphere Packaging (MAP) Market
Packaging Barrier Films
Volatile Corrosion Inhibitors (VCI) Packaging Market
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
Stretch Films Packaging Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Insulation Film Market
Packaging Barrier Films
Non Heat Sealable Film Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Ultra-High Barrier Films Market
Packaging Barrier Films
Hydrocolloid Coating Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Transparent Barrier Films Market
Packaging Barrier Films
Pan Liners Market
Packaging Barrier Films
High Barrier Lidding Film Market