
 Barrier Shrink Bags Market | 2026-2036
Barrier Shrink Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Barrier Shrink Bags Market Analysis
Multilayer coextrusion with ethylene vinyl alcohol is tilting the performance benchmark for oxygen transmission rates in fresh protein packaging. Amcor plc leverages its global film manufacturing footprint to sustain supply consistency across European protein processors. KUREHA CORPORATION anchors its position through polyvinylidene chloride expertise and controlled-atmosphere packaging chemistry. Sealed Air Corporation differentiates via Cryovac shrink technologies that dominate high-throughput red meat operations.
Barrier shrink bags are multilayer flexible films engineered to combine oxygen and moisture barriers with heat-shrinkable conformability, typically incorporating ethylene vinyl alcohol or polyamide layers within polyethylene matrices to achieve oxygen transmission rates below 5 cm³/m²/day. Their primary purpose is to preserve protein quality, suppress microbial growth, and maintain visual appeal through vacuum skin-tight packaging in fresh meat, processed meat, and cheese applications. Polyethylene formulations lead volume due to cost efficiency and recyclability alignment, while nylon-reinforced structures capture premium margin pools in extended shelf-life applications. Food Packaging dominates end-use demand, though Pharmaceuticals represents a faster-growing segment driven by sterile barrier requirements for medical device kits.
EFSA migration testing protocols and EU Packaging and Packaging Waste Regulation targets for recyclability are reshaping material selection and layer simplification strategies across European converters. FDA food contact substance notifications govern U.S. import eligibility and dictate compliance documentation burdens for offshore film suppliers. REACH substance restrictions on perfluorinated compounds and emerging state-level extended producer responsibility laws in California and New York are adding compliance layers that favor mono-material polyethylene developments. Stakeholders must monitor regulatory divergence between EU harmonized standards and fragmented U.S. state mandates when allocating R&D and capital deployment across regional production assets.
Market Dynamics
Mono-material polyethylene structures are displacing multilayer laminates as EFSA migration limits and EU Packaging and Packaging Waste Regulation recyclability mandates force converters to strip out incompatible barrier layers. This material simplification drive is compressing oxygen barrier performance while demanding new EVOH coextrusion geometries.
Growth Catalysts
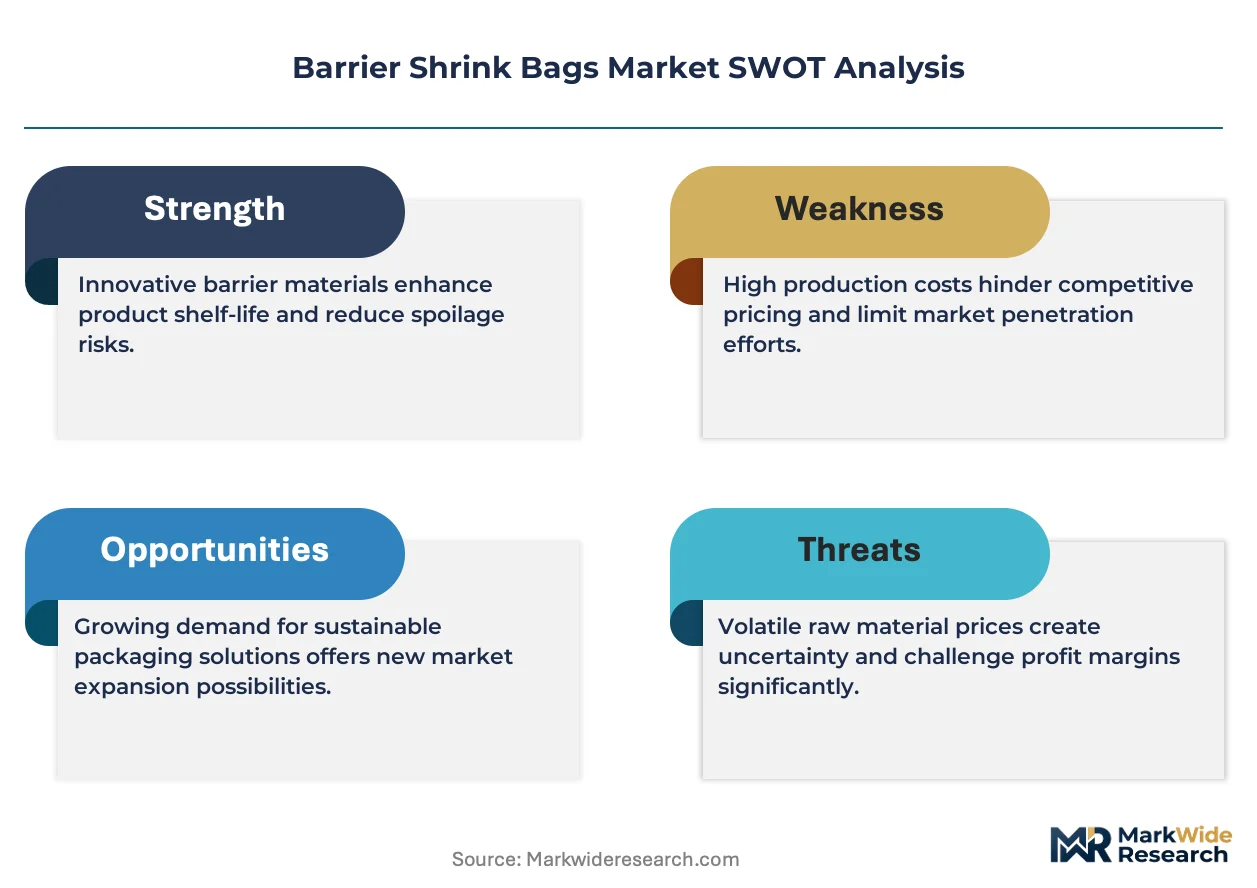
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are pulling converters toward mono-material PE shrink bags with compatible barrier layers, creating retrofit demand across German and French meat processing clusters.
- Fresh protein shelf-life extension:Vacuum skin-tight packaging with sub-5 cm³/m²/day oxygen transmission rates is penetrating premium retail channels for aged beef and charcuterie.
- Centralized meat processing in Germany:Export-oriented slaughterhouse consolidation is standardizing high-barrier shrink formats for intercontinental cold chain distribution.
Market Restraints
- Ethylene vinyl alcohol resin concentration:Three Asian petrochemical suppliers control over 70% of global EVOH supply, exposing European converters to feedstock volatility and force majeure risk.
- Multilayer delamination in mechanical recycling streams:Legacy PA/PE/EVOH structures contaminate polyethylene regrind pools, triggering sortation facility rejections and compliance documentation burdens.
- PVdC substitution pressure:KUREHA CORPORATION's polyvinylidene chloride chemistry faces REACH substance scrutiny and retailer blacklisting, narrowing high-barrier options for cured meat applications.
Strategic Opportunities
- Pharmaceutical sterile barrier kits:Medical device manufacturers are qualifying shrink bags for ethylene oxide sterilization cycles, opening margin pools above food packaging commoditization.
- Bio-based EVOH feedstocks:Braskem's sugarcane-derived polyethylene integration with bio-ethylene vinyl alcohol is creating carbon-accounted packaging tiers for Nordic retail chains.
- California SB 54 implementation:Extended producer responsibility mandates are accelerating mono-material adoption ahead of federal US standards, favoring early-mover converter investments.
Industry Challenges
- Barrier layer thickness optimization:Converters must maintain oxygen transmission performance while thinning EVOH layers below 3 microns to meet mechanical recycling purity thresholds, demanding precision coextrusion die recalibration.
- Migration testing protocol fragmentation:EFSA's updated specific migration limits for primary aromatic amines require batch-level analytical validation, extending new product qualification timelines by 8-14 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barrier Shrink Bags Market |
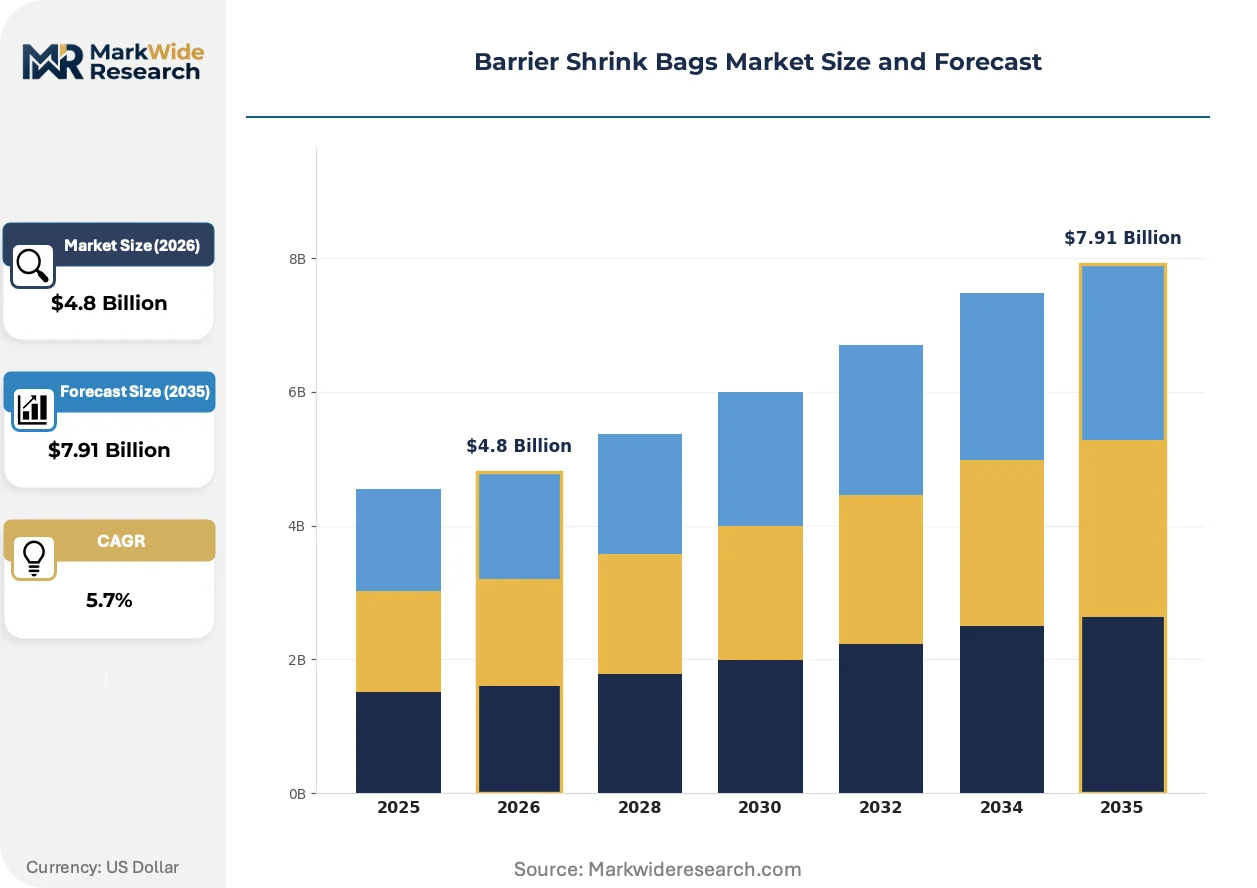
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polyvinyl Chloride, Polypropylene, Nylon Application: Food Packaging, Pharmaceuticals, Electronics, Industrial Supplies Size: Small, Medium, Large, Custom End User: Retailers, Manufacturers, Food Processors, Distributors |
| Companies Covered | Sealed Air Corporation, Amcor plc, WINPAK LTD., KUREHA CORPORATION, FLEXOPACK S.A., Viscofan Group, Coveris, Mondi Group, Schur Flexibles Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barrier Shrink Bags Market Emerging Trajectories
Active barrier technologies and digital printing integration are redefining value capture in shrink bag manufacturing. The competitive frontier is shifting from passive oxygen exclusion to intelligent shelf-life communication.
Plasma-enhanced chemical vapor deposition of silicon oxide onto polyethylene substrates is rendering obsolete aluminum oxide metallization for high-barrier meat packaging. Premium beef exporters in the Netherlands are piloting SiOx-coated mono-material structures at 15% cost premiums. The technology is rendering obsolete dual-chamber vacuum systems by enabling single-step skin-tight conformability with equivalent barrier performance.
REACH restrictions on perfluorinated compounds are eliminating grease-resistant coatings from cheese packaging applications. German dairy processors are retrofitting extrusion lines for polyethylene-ionic copolymer alternatives ahead of 2025 enforcement deadlines. The cured meat segment faces the steepest compliance curve, as PVdC replacement candidates must match 24-month shelf-life specifications.
Retailer-driven blockchain traceability mandates are compressing supplier qualification cycles. French hypermarket chains now require lot-level digital passports for vacuum-packed proteins, forcing converters to integrate QR-printed shrink surfaces. The shift is most visible in Iberian pork export corridors, where Chinese import documentation demands real-time cold chain verification through bag-embedded sensors.
Barrier Shrink Bags Market Segmentation
Segmentation in barrier shrink bags reveals how material chemistry, application requirements, and end-user scale create distinct competitive arenas. Each dimension shapes procurement patterns, technical specifications, and margin structures differently across protein packaging, medical sterilization, and industrial logistics channels.
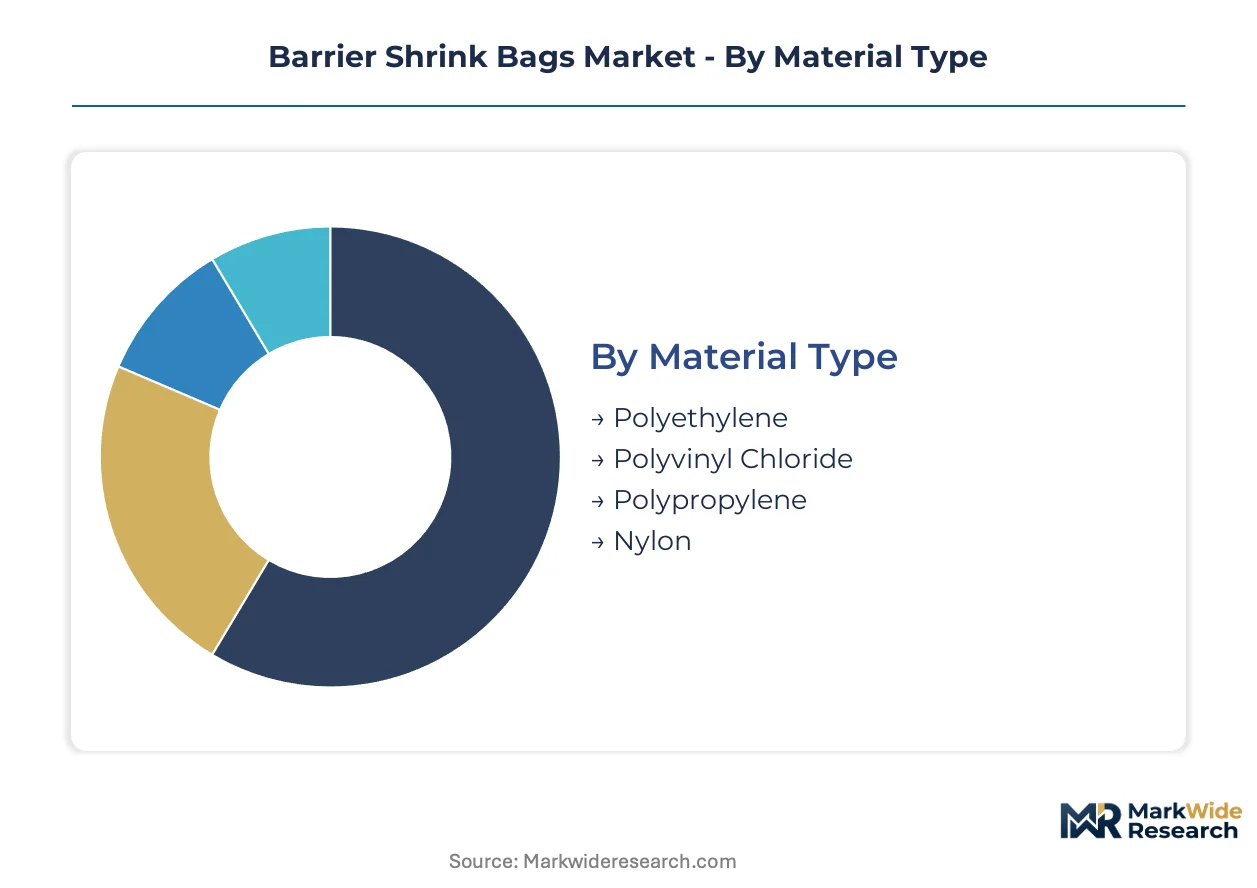
Material Type:
The maturity spectrum spans commodity thermoplastics to engineered barrier polymers, with recyclability mandates accelerating substitution dynamics.
- Polyethylene:Linear low-density and high-density grades dominate mono-material shrink bag production, achieving sub-5 cm³/m²/day oxygen transmission through EVOH coextrusion. German meat processors are standardizing PE structures to meet EU Packaging and Packaging Waste Regulation recyclability targets ahead of enforcement deadlines.
- Nylon:Polyamide 6 and 6/6 layers reinforce puncture resistance for bone-in meat applications and extended distribution cycles. Demand concentrates in premium aged beef and charcuterie segments where shelf-life requirements exceed 90 days and mechanical abuse resistance justifies material cost premiums.
- Polyvinyl Chloride:Plasticized PVC retains niche position in low-temperature shrink applications where clarity and conformability outweigh barrier performance requirements.
- Polypropylene:Cast and oriented PP structures serve high-temperature shrink tunnels and retort-compatible formats for ready-meal protein packaging.
Polyethylene handles the majority of throughput; Nylon is the fastest mover on share.
Application:
Application segmentation tracks how oxygen sensitivity and regulatory scrutiny vary across end-use environments.
- Food Packaging:Vacuum skin-tight formats for fresh and processed proteins represent the volume anchor, with EFSA migration limits dictating layer chemistry and qualification protocols. Dutch beef exporters are piloting SiOx-coated mono-material structures at cost premiums to replace metallized barriers.
- Pharmaceuticals:Ethylene oxide sterilizable shrink bags for medical device kits command margin pools above food commoditization, with FDA food contact substance notifications governing import eligibility and documentation burdens.
- Electronics:Moisture barrier variants protect sensitive components through global distribution, with static-dissipative grades serving semiconductor packaging requirements.
- Industrial Supplies:Heavy-gauge shrink formats secure machinery and automotive parts for ocean freight, prioritizing puncture resistance over oxygen exclusion.
Food Packaging absorbs the dominant share of resin throughput; Pharmaceuticals is expanding most quickly as sterile barrier qualification cycles compress.
Size:
Size segmentation reflects automation compatibility and product geometry constraints across processing scales.
- Large:Side-seal and bottom-seal configurations accommodate whole primal cuts and subprimal portions for industrial meat processing, with bag dimensions calibrated to automated vacuum chamber specifications.
- Custom:Die-cut and pre-formed shapes serve irregular protein geometries and premium retail presentations, with French hypermarket chains requiring lot-level digital passport integration on bespoke formats.
- Medium:Standard retail case-ready portions dominate supermarket distribution, balancing machine throughput with shelf-space efficiency.
- Small:Single-serve and portion-control formats penetrate convenience retail and foodservice channels, with thinner gauge requirements challenging barrier performance maintenance.
Large formats carry the bulk of industrial volume; Custom sizes are climbing the fastest as retailer differentiation demands intensify.
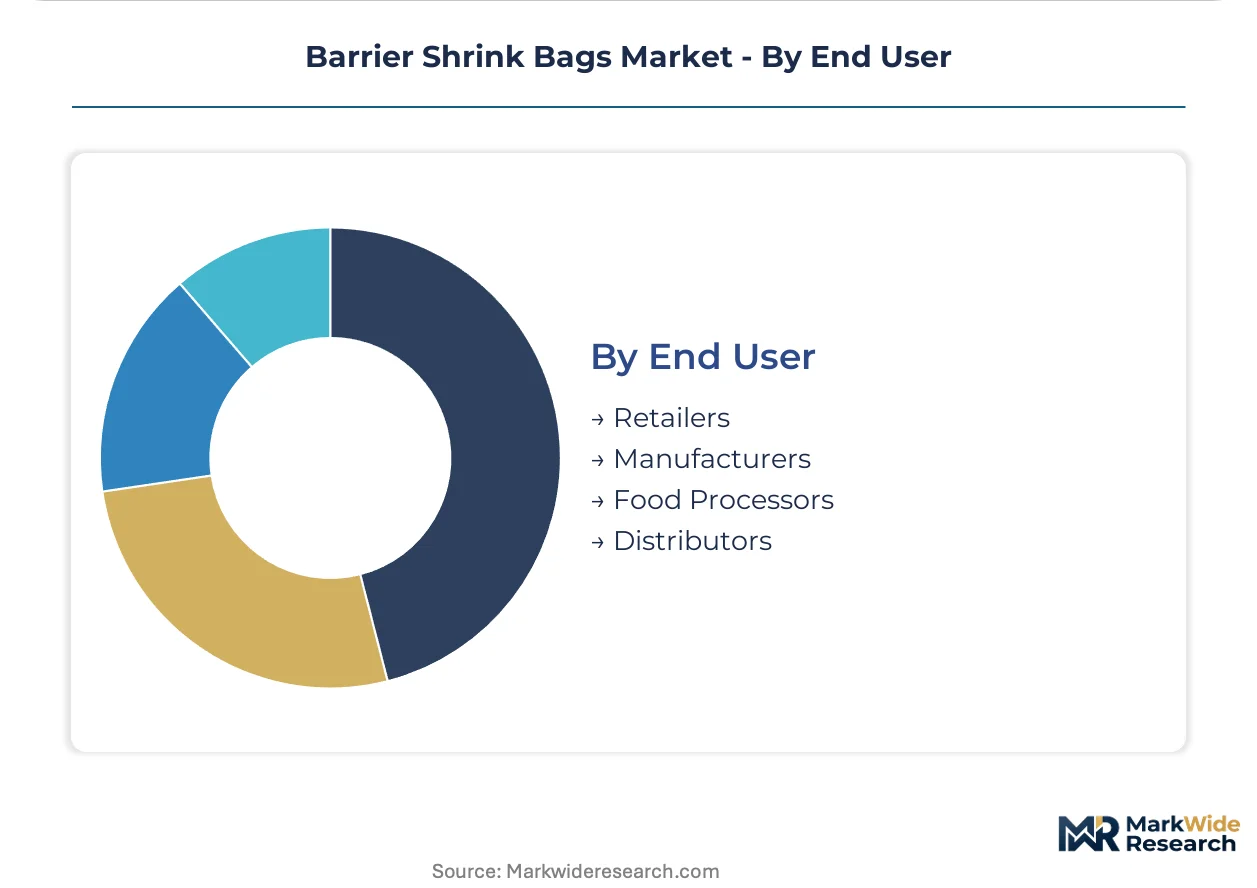
End User:
End-user segmentation distinguishes between value-capture positions in the packaging value chain, from specification authority to procurement execution.
- Food Processors:Slaughterhouse and further-processing operations specify barrier performance and seal integrity standards, with centralized German meat processing driving standardization for export-oriented cold chains.
- Retailers:Hypermarket and specialty chains are imposing blockchain traceability mandates and digital passport requirements, compressing converter qualification cycles and favoring integrated printing capabilities.
- Manufacturers:Medical device and electronics producers qualify shrink bags for sterilization compatibility and cleanroom handling, with documentation burdens favoring established supplier relationships.
- Distributors:Third-party logistics providers procure standard formats for consolidated shipments, with price sensitivity and availability driving sourcing decisions.
Food Processors command specification authority over the largest volume; Retailers are gaining share fastest through private-label and traceability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German meat processors export vacuum-packed proteins to Asian retail chains, driving standardization of high-barrier shrink formats across intercontinental cold chains. This trade corridor anchors demand for sub-5 cm³/m²/day oxygen transmission specifications.
United States
California SB 54 extended producer responsibility mandates accelerate mono-material polyethylene adoption ahead of federal standards. FDA food contact substance notifications govern import eligibility for offshore film suppliers. Chicago-area meatpacking clusters are retrofitting extrusion lines to meet state-level recyclability thresholds.
Germany
Centralized slaughterhouse consolidation in Lower Saxony and North Rhine-Westphalia standardizes export-oriented packaging for intercontinental distribution. EFSA migration limits and EU Packaging and Packaging Waste Regulation recyclability targets force layer simplification strategies. The Ruhr industrial corridor hosts converter retrofitting programs for compatible barrier coextrusion.
Netherlands
Premium beef exporters in Gelderland pilot silicon oxide-coated mono-material structures at cost premiums to replace metallized barriers. REACH substance restrictions on perfluorinated compounds eliminate legacy grease-resistant coatings. Rotterdam logistics hubs coordinate cold chain verification systems for Chinese import documentation.
France
French hypermarket chains impose blockchain traceability mandates requiring lot-level digital passports on vacuum-packed proteins. ANSM and CNIL data governance frameworks shape sensor-embedded packaging requirements. The Brittany pork processing belt integrates QR-printed shrink surfaces for real-time cold chain verification.
China
Domestic protein processors qualify imported shrink bags for ethylene oxide sterilization cycles in medical device kit applications. SAMR food contact material standards and GB technical regulations govern local production licensing. Yangtze River Delta converters are scaling EVOH coextrusion capacity to reduce import dependency.
Barrier Shrink Bags Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base clusters around three strategic archetypes: diversified packaging conglomerates with global film manufacturing footprints, regional converters with coextrusion specialization, and materials-science firms with barrier polymer expertise. Consolidation pressure favors backward integration into resin supply and captive EVOH distribution arrangements.
Among diversified packaging conglomerates, Sealed Air Corporation and Amcor plc exemplify channel-control positioning through Cryovac shrink technology platforms and global manufacturing scale respectively. KUREHA CORPORATION occupies a specialist tier anchored in polyvinylidene chloride chemistry expertise. These three entities represent distinct competitive vectors: equipment-integrated solutions, geographic supply consistency, and high-performance barrier materials.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Amcor plc |
| WINPAK LTD. |
| KUREHA CORPORATION |
| FLEXOPACK S.A. |
| Viscofan Group |
| Coveris |
| Mondi Group |
| Schur Flexibles Group |
| Others |
Supply Flow & Price Mechanics
The Ruhr industrial corridor's converter retrofitting programs for EVOH coextrusion capacity determine downstream pricing power across European protein packaging channels. Capacity constraints at these German facilities transmit directly to contract negotiations with Dutch beef exporters and French hypermarket chains.
Pricing Analysis
Prior-generation metallized barrier films command 15% cost premiums against emerging silicon oxide-coated mono-material structures. Three-tier pricing structure across premium SiOx-coated, standard EVOH coextruded, and economy-grade polyethylene tiers reflects oxygen transmission performance and recyclability certification. Cost compression in standard tiers intensifies because Asian petrochemical suppliers control over 70% of global EVOH resin supply. Small-format retail portions exhibit highest price sensitivity due to thinner gauge requirements challenging barrier maintenance.
Supply Chain Analysis
Export-control scrutiny on advanced coextrusion die technologies limits equipment flows to Yangtze River Delta converters attempting EVOH capacity buildouts. Supply concentrates in Germany, Japan, and South Korea for precision barrier film manufacturing. Raw material dependencies center on ethylene vinyl alcohol resin, linear low-density polyethylene feedstock, and silicon oxide deposition precursors. Single-source vulnerability permeates the EVOH layer given three Asian suppliers dominate global production. Distribution runs through converter-direct relationships with centralized German meat processors and Rotterdam logistics hubs coordinating cold chain verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation recyclability mandates constitute a high-growth disruption, forcing €4.8 billion in installed capacity toward mono-material retrofitting. This regulatory inflection compresses qualification timelines while opening margin pools for compliant barrier technologies.
For Market Incumbents: Pre-empt PVdC substitution pressure by accelerating bio-based EVOH partnerships ahead of REACH substance restrictions. Sealed Air Corporation and Amcor plc must defend Cryovac equipment-integrated positions against regional coextrusion specialists capturing German retrofit demand. Backward integration into captive EVOH distribution arrangements anchors supply security against Asian petrochemical volatility.
For New Entrants and Emerging Players: Pharmaceutical sterile barrier kits for ethylene oxide sterilization cycles represent the most penetrable entry point above food packaging commoditization. California SB 54 implementation creates first-mover advantage for mono-material polyethylene specialists ahead of federal US standards. Medical device manufacturer qualification partnerships offer the strongest go-to-market angle given FDA documentation burdens favoring established supplier relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-integrated packaging conglomerates with captive film manufacturing footprints. Long-term viability across the analysis window rests on regulatory compliance bandwidth and EVOH supply security rather than commodity resin scale. Acquisition targets should demonstrate precision coextrusion die recalibration capabilities below 3-micron EVOH layers. Watch for force majeure declarations from Asian petrochemical suppliers as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Resin Supply | Captive feedstock security insulates German converters from Asian supplier force majeure risk. |
| SiOx Coating Technology Licensing | Dutch premium beef exporters pilot mono-material structures replacing metallized barriers at cost premiums. |
| Pharmaceutical Sterile Barrier Qualification | FDA food contact substance notifications govern medical device kit import eligibility and documentation. |
| Blockchain Traceability Platform Partnership | French hypermarket chains mandate lot-level digital passports compressing converter qualification cycles. |
| Bio-Based Feedstock Joint Venture | Braskem's sugarcane-derived polyethylene integration creates carbon-accounted tiers for Nordic retail chains. |
Methodological Framework
A spread of perspectives from film manufacturing plant managers, meat processor procurement leads, pharmaceutical packaging engineers, and EVOH resin technical directors converged on the working assumptions. Primary interview insights combined with secondary validation from EFSA migration testing protocols, EU Packaging and Packaging Waste Regulation documentation, FDA food contact substance notification databases, and customs trade data for barrier film imports. Bottom-up resin throughput estimates and top-down end-use demand assessments triangulated volume figures.
Demand-supply balance dynamics across material type, application, and end-user segments anchored the analytical framework over the projection horizon. Segmentation dimensions modeled encompass polyethylene versus nylon versus emerging SiOx-coated structures, food packaging versus pharmaceutical versus electronics applications, and food processor versus retailer versus manufacturer procurement authority. CAGRs derived from installed capacity utilization rates and regulatory-driven retrofit acceleration curves. Industry-specific forecast inputs incorporated EVOH resin price volatility indices and centralized German slaughterhouse consolidation patterns.
Macroeconomic conditions sit as an overlay; deviation in energy feedstock costs, ocean freight rates, and currency exchange volatility would shift the trajectory. Forecasts reflect documented assumptions regarding EFSA enforcement timelines and REACH substance restriction implementation. Material shifts in Asian petrochemical supplier consolidation or EU recyclability mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Lining Market
Packaging Barrier Films
Thailand Plastic Packaging Films Market
Packaging Barrier Films
Moisture Barrier Bags Market
Packaging Barrier Films
Barrier Materials Market
Packaging Barrier Films
Super Barrier Coated Film Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Disposable Barrier Sleeves Market
Packaging Barrier Films
Barrier Coated Flexible Paper Packaging Market
Packaging Barrier Films
Saudi Arabia Plastic Packaging Films Market
Packaging Barrier Films
North America Protective Films Market
Packaging Barrier Films
Breathable Lidding Film Packaging Market
Packaging Barrier Films
Clear Barrier Films Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Cold Seal Plastic Films Market
Packaging Barrier Films
Sterile Barrier Packaging Market