
 Transport Protection Film Market | 2026-2036
Transport Protection Film Market Size, Share, and Industry Trends Forecast 2026-2036
Transport Protection Film Market Analytics
The EU Green Deal is expanding compliance obligations for transport packaging materials across European automotive and electronics supply chains. Chargeurs SA leverages its textile-to-film manufacturing heritage to serve luxury automotive logistics with specialized surface protection solutions. Polifilm Group anchors Central European supply through vertically integrated polyethylene extrusion and conversion capabilities. Tesa SE competes on adhesive chemistry expertise, sustaining premium positioning in precision electronics handling applications.
Transport protection film denotes a temporary, removable polymer layer applied to surfaces during handling, transit, and assembly operations, typically manufactured through blown or cast extrusion of polyethylene, polypropylene, or polyvinyl chloride resins at thicknesses ranging from 25 to 150 micrometers. Its primary purpose is to prevent abrasion, contamination, and UV-induced degradation of finished goods prior to end-use installation. Adhesive films command the dominant value share due to clean-removal requirements in automotive paint protection and electronics display guarding, while stretch films lead volume throughput in palletized logistics. Polyethylene formulations represent the mature, cost-optimized baseline, though polypropylene grades are gaining traction in high-temperature automotive underhood applications where thermal stability thresholds exceed 120 degrees Celsius.
The European Chemicals Agency enforces REACH substance restrictions on plasticizer chemistries used in flexible PVC protection films, compelling reformulation toward non-phthalate alternatives. In the United States, the EPA oversees volatile organic compound emission limits during solvent-based adhesive coating processes, shaping regional manufacturing technology choices. China's Ministry of Ecology and Environment implements dual carbon goals that pressure domestic extruders to adopt recycled content quotas and energy-efficient blown film lines. Stakeholders must monitor evolving extended producer responsibility frameworks and material certification requirements to secure supply chain access across divergent regulatory jurisdictions.
Market Dynamics
Extended producer responsibility frameworks under the EU Green Deal are forcing automotive OEMs and electronics manufacturers to requalify their entire protection film supply chains around recyclability metrics and carbon accounting disclosures.
Growth Catalysts
- Recyclable polyethylene formulations:German automotive OEMs are mandating post-consumer recycled content thresholds in paint protection films to comply with tightening EU Packaging and Packaging Waste Regulation obligations.
- REACH substance restrictions:ECHA enforcement against phthalate plasticizers in flexible PVC protection films is accelerating reformulation toward bio-based adhesive chemistries across European supply chains.
- East Asian electronics clusters:Display panel and semiconductor fabrication facilities in Taiwan and South Korea are expanding surface protection specifications to prevent sub-micron contamination during high-value component transit.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene price swings directly compress polyethylene and polypropylene film margins, with limited pass-through elasticity in long-term automotive supply contracts.
- Blown film line concentration:Central European extrusion capacity clusters in Germany and Poland create geographic supply vulnerability to regional energy price shocks and logistics disruptions.
- Thermal stability ceiling:Standard polyethylene formulations degrade above 85 degrees Celsius, excluding them from underhood automotive applications where polypropylene commands premium positioning.
Strategic Opportunities
- India automotive manufacturing:PLI scheme incentives for domestic vehicle production are attracting protection film converters to establish local compounding and slitting operations near Chennai and Pune assembly plants.
- Closed-loop collection systems:EU Green Deal circular economy mandates are creating service-revenue opportunities for film suppliers offering take-back and regranulation programs tied to OEM sustainability reporting.
- UV-curable adhesive convergence:Solvent-free coating technologies are eliminating volatile organic compound emissions while enabling faster line speeds than thermal drying systems.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise in pressure-sensitive adhesive design for clean-removal applications remains concentrated among a narrow cohort of specialized compounders.
- Multi-jurisdiction certification timelines:Simultaneous compliance with REACH substance restrictions, FDA indirect food contact approvals, and China GB standards extends product qualification cycles by 18-24 months.
- Legacy coating asset stranding:Solvent-based adhesive lines face accelerated obsolescence as EPA emission limits tighten, requiring capital-intensive conversion to aqueous or hot-melt systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transport Protection Film Market |
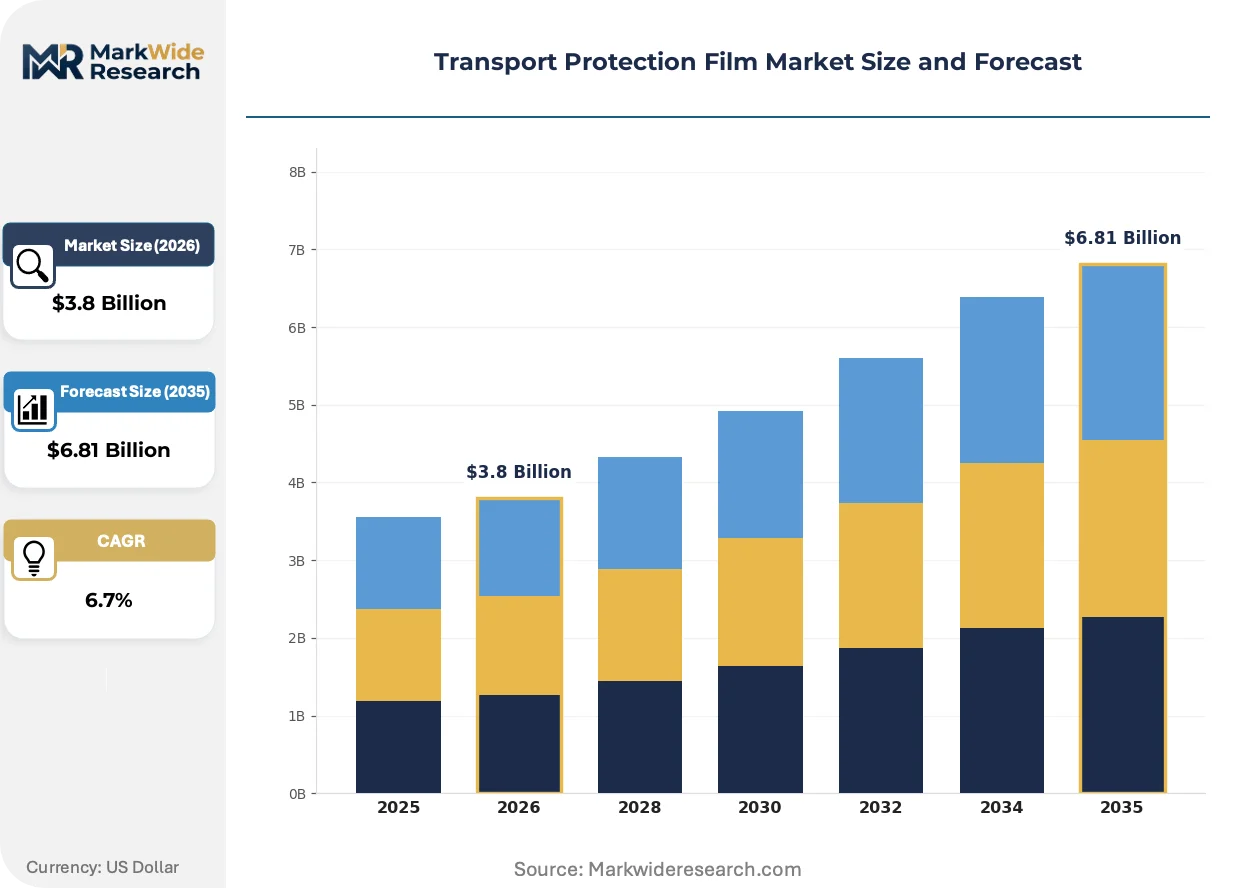
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Film, Non-Adhesive Film, Stretch Film, Shrink Film End User: Aerospace, Automotive, Electronics, Furniture Application: Surface Protection, Wrapping, Packaging, Holding Material: Polyethylene, Polyvinyl Chloride, Polypropylene, Others |
| Companies Covered | Chargeurs SA, Polifilm Group, Pregis LLC, Nitto Denko Corporation, Tesa SE, 3M, Avery Dennison Corporation, Eastman Chemical Company, XPEL Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transport Protection Film Market Evolving Landscape
Active reformulation of adhesive chemistries and extrusion processes is compressing the technical gap between commodity polyethylene films and performance-grade alternatives while embedding compliance capabilities directly into material specifications.
Multi-layer coextrusion technology is integrating discrete functional layers—UV barriers, anti-static coatings, and controlled-adhesion skins—into single-pass blown film structures. Japanese automotive logistics providers are qualifying these constructions for luxury vehicle ocean transit where salt spray and solar exposure risks compound. This integration is enabling standard polyethylene substrates to displace higher-cost polypropylene in moderate-temperature applications previously reserved for premium grades.
China's Ministry of Ecology and Environment dual carbon goals are mandating recycled content quotas and energy consumption benchmarks for domestic extrusion operations. Domestic compounders are responding by installing solar-powered blown film lines and certifying post-industrial polyethylene regrind streams for electronics protection applications. The policy is reshaping export competitiveness as Chinese suppliers absorb compliance costs that foreign competitors avoid only through geographic exemption.
Automotive OEMs are consolidating protection film procurement under single-source master agreements that bundle specification development, inventory management, and sustainability reporting. Tier-1 logistics providers in Germany and Japan are displacing fragmented spot purchasing with multi-year contracts tied to carbon footprint reduction targets. This concentration is most visible in battery electric vehicle programs where supply chain traceability requirements exceed internal combustion vehicle standards.
Transport Protection Film Market Segmentation

Transport protection film procurement decisions hinge on the interplay between surface sensitivity requirements, thermal exposure limits, and removal cleanliness specifications. End-users segment their sourcing strategies across adhesive performance tiers, material thermal thresholds, and application-specific contamination risks.
Product Type:
Clean-removal requirements in high-value finished goods determine whether buyers specify pressure-sensitive adhesives or rely on mechanical tension-based systems.
- Adhesive Film:Pressure-sensitive formulations with controlled peel strength prevent residue transfer onto automotive paint systems and electronics display panels. German luxury OEMs mandate silicone-acrylate hybrid chemistries for ocean transit protection of battery electric vehicle bodies.
- Stretch Film:Linear low-density polyethylene formulations achieve 200-300% elongation through molecular orientation, securing palletized loads without surface contact. Demand concentrates in intra-factory logistics across Taiwanese electronics assembly campuses where rapid throughput outweighs surface sensitivity.
- Non-Adhesive Film:Static cling or mechanically secured polyethylene sheets serve temporary dust barriers in furniture manufacturing and construction finishing.
- Shrink Film:Biaxially oriented constructions heat-seal around irregular contours for unitized protection of aerospace composite components.
Stretch film leads on scale; adhesive film leads on momentum.
End User:
Thermal stability thresholds and contamination sensitivity create divergent material specifications across manufacturing sectors.
- Automotive:Paint protection films must withstand 120°C curing oven exposures while releasing cleanly from clearcoat surfaces. Japanese OEMs are expanding procurement of recyclable polyethylene formulations under extended producer responsibility frameworks.
- Electronics:Display panel and semiconductor wafer transit demands anti-static, ultra-clean adhesive films with sub-micron particle exclusion. South Korean fabrication facilities specify ionic contamination levels below 10 parts per billion for wafer-level protection.
- Aerospace:Carbon fiber composite protection during autoclave curing requires polyimide or high-temperature polypropylene substrates.
- Furniture:Cost-optimized polyethylene films prevent scratch damage during final mile delivery of polished wood and lacquered surfaces.
Electronics commands premium pricing; automotive drives volume expansion.
Application:
The physical interface between film and protected surface dictates adhesive chemistry, thickness calibration, and removal protocol design.
- Surface Protection:Temporary barriers against abrasion, UV degradation, and chemical exposure during manufacturing and transit. German automotive logistics providers specify 80-150 micrometer polyethylene constructions with UV absorber additives for outdoor storage protection.
- Wrapping:Conformable films secure irregular geometries without adhesive contact, prevalent in furniture and appliance distribution.
- Packaging:Unitization and cushioning functions for component-level shipment protection.
- Holding:Temporary fixation of parts during assembly operations, requiring controlled tack and clean release.
Surface protection dominates value capture; wrapping sustains volume throughput.
Material:
Polymer selection balances cost position, thermal performance ceiling, and regulatory compliance burden across supply chains.
- Polyethylene:Blown and cast extrusion of low-density and linear low-density grades delivers cost-optimized protection for ambient-temperature applications. China's Ministry of Ecology and Environment mandates recycled content quotas and energy consumption benchmarks for domestic extrusion operations.
- Polypropylene:Higher crystallinity enables 120-140°C service temperatures for automotive underhood and paint shop applications. Japanese compounders are qualifying post-industrial regrind streams for closed-loop electronics protection programs.
- Polyvinyl Chloride:Flexible formulations with non-phthalate plasticizers serve specialized conformability requirements; ECHA REACH restrictions accelerate reformulation toward bio-based alternatives.
- Others:Polyimide, polyester, and bio-based films address niche high-temperature or sustainability-specified applications.
Polyethylene anchors volume scale; polypropylene gains share fastest in thermally demanding segments.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene extrusion for surface protection originated in post-war German chemical corridors before scaling through Japanese electronics supply chains and Chinese manufacturing clusters. Today's procurement geography reflects this diffusion pattern, with specialized compounding concentrated in industrial regions facing divergent regulatory pressures.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg mandate post-consumer recycled content thresholds for paint protection films. The EU Packaging and Packaging Waste Regulation drives requalification of entire supply chains around recyclability metrics. Stuttgart and Munich logistics hubs are consolidating procurement under single-source master agreements tied to carbon footprint reduction targets.
China
Domestic electronics manufacturing in the Yangtze River Delta and Pearl River Delta sustains massive polyethylene film consumption for display panel transit. The Ministry of Ecology and Environment enforces dual carbon goals mandating recycled content quotas and energy-efficient blown film lines. Suzhou and Shenzhen compounders are installing solar-powered extrusion capacity to absorb compliance costs.
United States
Automotive assembly in Michigan and Tennessee generates demand for high-temperature paint shop protection films. The EPA oversees volatile organic compound emission limits that shape regional adhesive coating technology choices. Detroit-area logistics providers are qualifying UV-curable adhesive systems to eliminate solvent-based process emissions.
Japan
Semiconductor fabrication facilities in Kyushu and the Tokyo periphery specify ultra-clean adhesive films with sub-micron particle exclusion. METI industrial policy supports closed-loop collection systems for post-industrial regrind streams. Osaka-based compounders are expanding qualification of recyclable polyethylene formulations for luxury automotive ocean transit.
South Korea
Display panel production near Seoul and semiconductor clusters in Gyeonggi Province drive premium surface protection specifications. The national carbon neutrality framework pressures domestic extruders toward energy-efficient manufacturing. Incheon logistics campuses are expanding anti-static film inventories for wafer-level transit protection.
Transport Protection Film Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology vectors. The market structures around three tiers: integrated resin-to-film compounders with captive polyethylene extrusion, specialized adhesive coaters purchasing substrate from merchant suppliers, and regional converters slitting master rolls to finished dimensions. Strategic moves concentrate on backward integration into resin compounding and geographic expansion toward emerging automotive assembly clusters.
Within the European integrated tier, Polifilm Group anchors Central European supply through in-house polyethylene extrusion and conversion capabilities. Tesa SE occupies a position on adhesive chemistry expertise, sustaining premium positioning in precision electronics handling applications. Chargeurs SA exemplifies textile-to-film manufacturing heritage applied to luxury automotive logistics with specialized surface protection solutions.
| Leading Market Players |
|---|
| Chargeurs SA |
| Polifilm Group |
| Pregis LLC |
| Nitto Denko Corporation |
| Tesa SE |
| 3M |
| Avery Dennison Corporation |
| Eastman Chemical Company |
| XPEL Inc. |
| Others |
Value Network & Pricing Analysis
Specialized polymer chemist concentration in Germany's Rhine-Ruhr chemical corridor widens pricing-tier spreads between premium silicone-acrylate adhesive formulations and commodity polyethylene grades, as labor-cost differentials compound raw material volatility across European automotive supply chains.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between German automotive OEMs and extrusion compounders, with price differentiation resting on REACH compliance certification and volume scale commitments. Cost compression in standard polyethylene grades is intensifying because Chinese domestic suppliers absorb dual carbon compliance costs that foreign competitors avoid through geographic exemption. Tier-1 automotive logistics providers exhibit lowest price sensitivity due to bundled sustainability reporting requirements, while furniture distributors and construction finishing contractors remain most price-sensitive.
Supply Chain Analysis
Freight cost differentials between Central European extrusion clusters and East Asian electronics manufacturing hubs are reshaping regional sourcing patterns for display panel protection films. Supply concentrates in Germany, China, and Japan, with raw material dependencies on ethylene and propylene feedstocks from integrated petrochemical complexes. Single-source vulnerability to regional energy price shocks in German and Polish blown film corridors creates structural risk. Distribution runs through Tier-1 logistics providers consolidating procurement under multi-year master agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme incentives for domestic automotive manufacturing attract protection film converters seeking to bypass China's dual carbon compliance cost absorption.
For Market Incumbents: Extend backward integration into post-industrial regrind compounding to secure closed-loop collection revenue streams under EU Green Deal circular economy mandates. Accelerate conversion from solvent-based adhesive coating lines to UV-curable systems before EPA emission limits tighten further, stranding legacy assets. Threat substitution from bio-based adhesive chemistries demands preemptive formulation patent positioning. For New Entrants and Emerging Players: Enter via Chennai and Pune automotive assembly corridors where PLI scheme incentives reduce effective customer acquisition costs versus established European supply relationships. White-space targets include India domestic vehicle production protection film specifications and Southeast Asian electronics logistics campuses lacking specialized anti-static film inventories. Go-to-market angle emphasizes solar-powered extrusion capacity certification for carbon footprint reduction reporting. For Investors and Strategic Acquirers: Specialized adhesive coaters with silicone-acrylate hybrid chemistry expertise are the most active acquirer targets in this space, as automotive OEMs consolidate procurement under single-source agreements requiring bundled specification development capabilities. Long-term viability centers on qualification timelines compressing from 18-24 months as multi-jurisdiction certification burdens intensify. Watch for ECHA enforcement actions against phthalate plasticizers as inflection indicator for bio-based adhesive chemistry valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures margin from ethylene feedstock volatility while securing REACH-compliant formulation control. |
| UV-Curable Adhesive Line Conversion | Eliminates EPA volatile organic compound exposure while enabling faster throughput than thermal drying systems. |
| Closed-Loop Collection System Launch | Generates service revenue tied to OEM sustainability reporting under EU Green Deal extended producer responsibility. |
| Geographic Expansion to India PLI Corridors | Positions converters near Chennai and Pune assembly plants benefiting from domestic vehicle production incentives. |
| Multi-Layer Coextrusion Technology Investment | Integrates UV barrier and anti-static functional layers for Japanese automotive ocean transit qualification. |
Research Methodology
Direct dialogue with polymer chemists at specialized adhesive compounders, procurement directors at German automotive OEMs, plant managers at Chinese blown film extrusion facilities, and logistics operations heads at Taiwanese electronics assembly campuses grounded qualitative findings. Secondary validation drew from ECHA substance restriction databases, EPA emission limit filings, China Ministry of Ecology and Environment dual carbon policy documents, and customs trade data on polyethylene film imports. Bottom-up and top-down triangulation cross-checked extrusion capacity estimates against end-use demand aggregation.
Bottom-up modeling of polyethylene and polypropylene film consumption by automotive paint protection, electronics display guarding, and palletized logistics applications anchored volume projections across the analysis window. Segmentation dimensions included adhesive performance tier, material thermal threshold, and end-use contamination sensitivity. CAGRs were derived from trend extrapolation of procurement consolidation patterns and regulatory compliance cost absorption trajectories. Forecast inputs incorporated EU Packaging and Packaging Waste Regulation implementation timelines and China recycled content quota enforcement intensity.
Inputs from ECHA enforcement actions and China MEE compliance audits were available through the study window; gaps in real-time automotive OEM procurement contract terms introduce uncertainty bands around master agreement concentration assumptions. Forecasts reflect modeling assumptions on regulatory implementation pacing and feedstock price pass-through elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Global Silicone Release Liner Market
Packaging Barrier Films
Barrier Shrink Bags Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
Bonding Films Market
Packaging Barrier Films
Cling Films Market
Packaging Barrier Films
Aluminum Oxide Coated Films Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Flexible Barrier Films for Electronics Market
Packaging Barrier Films
Heat Seal Coating Market
Packaging Barrier Films
Barrier Films Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Barrier Packaging Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
Global Stretch and Shrink Film Market