
 Barrier Packaging Market | 2026-2036
Barrier Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Barrier Packaging Market Analysis
Premium barrier packaging is decoupling from commodity-grade alternatives as oxygen transmission rate specifications tighten and brand owners segregate supply chains by shelf-life requirements. Amcor plc leverages its global film extrusion network to sustain technical service relationships with pharmaceutical clients. Berry Global Inc. anchors North American flexible barrier capacity through multi-layer coextrusion platforms. Constantia Flexibles Group competes in European pharmaceutical blister lidding through aluminum-barrier specialization.
Barrier packaging denotes engineered multi-layer structures—typically incorporating ethylene vinyl alcohol copolymers, polyamide, or metallized films with oxygen transmission rates below 0.1 cc/m²/day—designed to prevent permeation of gases, moisture, and light to preserve product integrity. These structures are manufactured through coextrusion, lamination, or vacuum deposition processes and serve primarily to extend shelf life and ensure safety in sensitive packaged goods. Flexible packaging dominates volume flows in food and beverage applications where downgauging and format versatility reduce material intensity, while rigid barrier formats command margin pools in pharmaceutical primary packaging where child-resistance and moisture protection standards are non-negotiable. Oxygen barrier films represent the fastest-growing application segment as modified atmosphere packaging expands beyond red meat into ready-to-eat produce and plant-based proteins.
The FDA enforces stringent extractables and leachables testing for pharmaceutical barrier materials under container closure system guidelines, while the EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds that force converters to validate post-consumer feedstocks in multi-layer structures. EFSA safety assessments for recycled plastics in food-contact layers add compliance layers that favor vertically integrated recyclers with in-house decontamination capabilities. Stakeholders must monitor evolving extended producer responsibility fee structures and recycled content verification protocols to avoid stranded asset risk in extrusion capacity.
Market Dynamics
Pharmaceutical cold-chain logistics is compressing oxygen transmission rate tolerances and forcing converters to segregate production lines between commodity and certified barrier grades.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Minimum recycled content mandates in multi-layer structures are accelerating investment in decontamination-capable recycling infrastructure across converter networks.
- Ethylene vinyl alcohol copolymers:Downgauging initiatives in food applications are expanding EVOH deployment as brand owners pursue material intensity reductions without shelf-life compromise.
- Germany:Pharmaceutical packaging clusters around Düsseldorf and Hamburg are scaling flexible barrier R&D capacity to serve pan-European biologics distribution.
Market Restraints
- Aluminum price volatility:Metallized film and blister lidding costs fluctuate with London Metal Exchange aluminum contract movements, compressing converter margins on fixed-price pharmaceutical contracts.
- Polyamide supply concentration:European polyamide 6 capacity is consolidating around a limited number of large-scale polymer producers, creating feedstock vulnerability for regional coextrusion lines.
- Multi-layer recyclability:Current mechanical recycling infrastructure cannot separate EVOH tie layers from polyolefin substrates, limiting circular economy pathways for post-consumer flexible packaging.
Strategic Opportunities
- Plant-based protein packaging:Modified atmosphere packaging specifications for alternative meat products are creating demand for ultra-high-barrier films with sub-0.1 cc/m²/day oxygen transmission rates.
- EFSA recycled plastics pathway:Food-contact authorization for post-consumer polyolefins in barrier layers offers first-mover advantage to converters with validated decontamination processes.
- Biologics distribution:Cell and gene therapy cold-chain requirements are extending barrier film specifications into cryogenic temperature ranges previously served by rigid formats.
Industry Challenges
- Extractables and leachables validation:FDA container closure system guidelines require extensive analytical chemistry documentation for pharmaceutical barrier materials, extending qualification timelines by 18-24 months.
- Coextrusion technician scarcity:Operating precision multi-layer blown film lines demands specialized polymer rheology expertise that outpaces current vocational training program output.
- Legacy lamination asset stranding:Solvent-based adhesive laminators face obsolescence risk as brand owners mandate aqueous or solvent-free bonding for sustainability credentials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barrier Packaging Market |
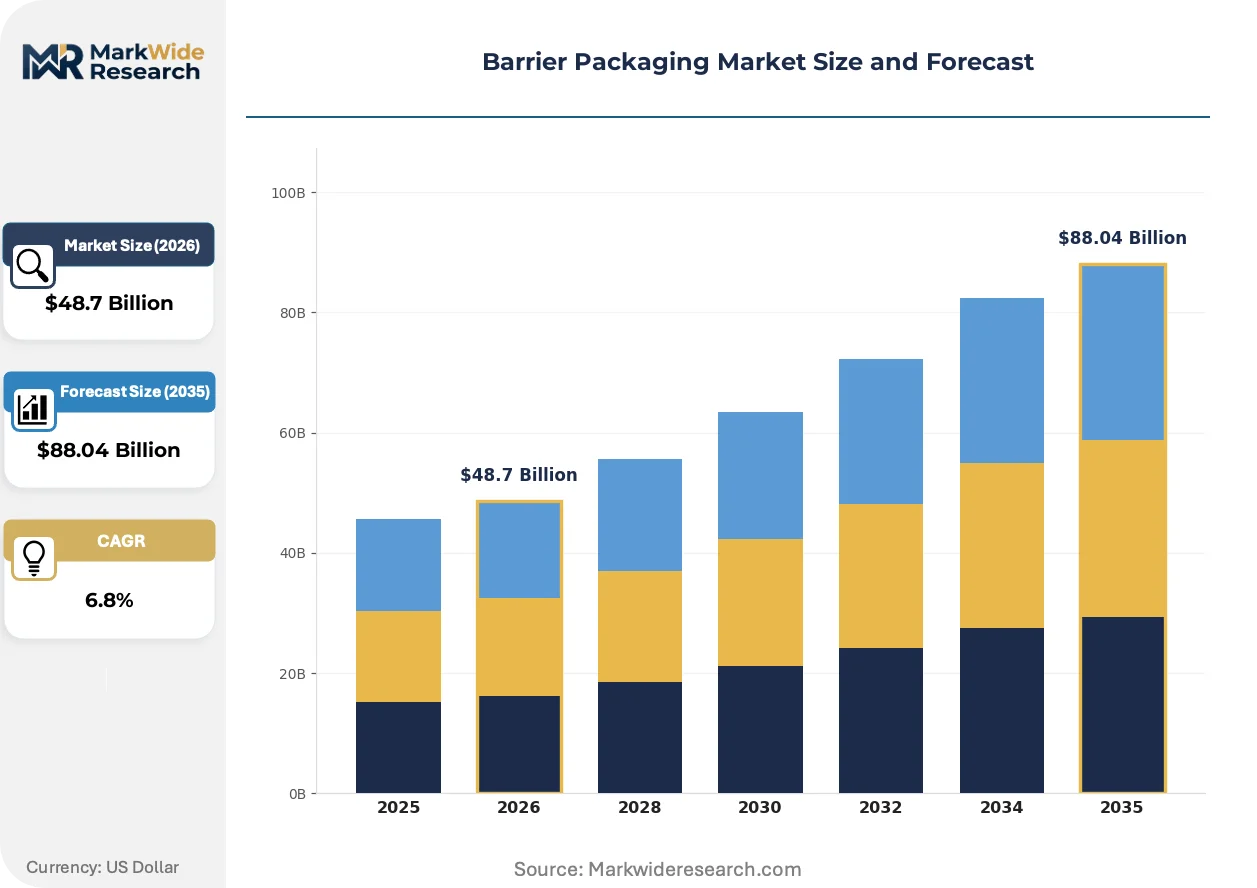
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Polyester, Nylon End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Packaging Type: Flexible Packaging, Rigid Packaging, Pouches, Films Application: Moisture Barrier, Oxygen Barrier, Gas Barrier, Light Barrier |
| Companies Covered | Mondi Group, Toray Plastics, Amcor plc, Uflex Limited, Huhtamaki Group, Sealed Air Corporation, Constantia Flexibles Group, TC Transcontinental, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barrier Packaging Market Emerging Trajectories
Barrier packaging innovation is bifurcating between incremental oxygen barrier improvements for food shelf-life extension and step-change performance requirements for pharmaceutical cold-chain integrity.
High-barrier metallized polyethylene terephthalate films are overtaking aluminum foil in pharmaceutical blister lidding as converters seek format flexibility and reduced material caliper. Biologics manufacturers are specifying metallized PET for temperature-sensitive products requiring moisture and light protection. This transition is compressing demand for rigid aluminum formats while expanding roll-fed flexible packaging capacity.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer-based grease barriers from food-contact flexible packaging by 2025. Converters are reformulating multi-layer structures with bio-based wax coatings and high-density polyethylene sealant layers to maintain oil resistance. Ready-to-eat snack producers in Germany and France are qualifying these alternative structures ahead of enforcement deadlines.
Brand owners are consolidating supplier relationships around converters with integrated recycling and EFSAsafety assessment capabilities. Pharmaceutical and food manufacturers are reducing qualified vendor lists from 15-20 to 5-8 strategic partners who can demonstrate post-consumer recycled content verification and extractables documentation. This concentration is most pronounced in Northern Europe, where extended producer responsibility fee structures reward material circularity.
Barrier Packaging Market Segmentation
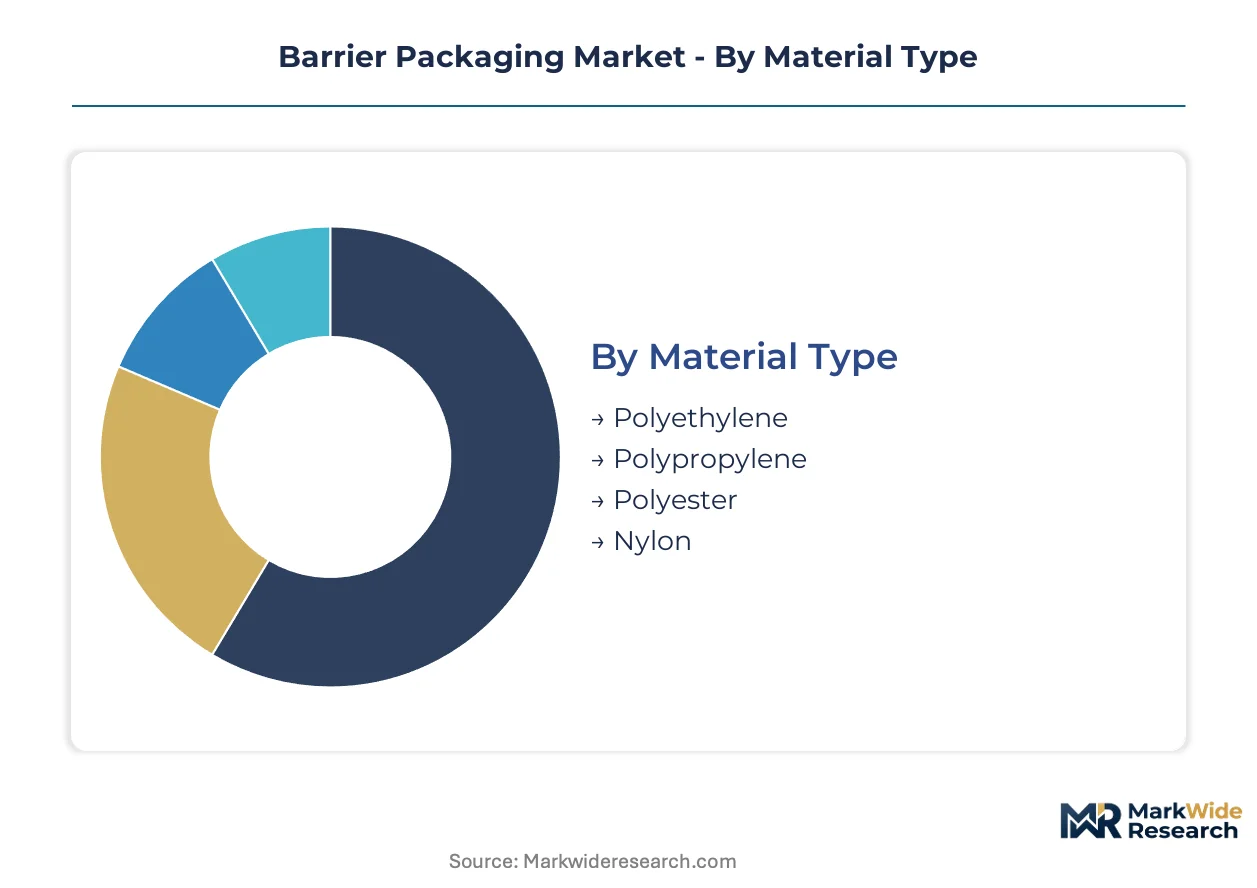
Barrier packaging segmentation reflects divergent technical requirements across pharmaceutical cold-chain logistics and food shelf-life extension. Material selection and barrier specification tiers map directly to end-use liability thresholds and regulatory compliance burdens.
Material Type:
Polymer feedstock concentration around large-scale petrochemical complexes in Germany, the Netherlands, and Belgium shapes converter sourcing strategies and working capital intensity.
- Polyethylene:Low-density and linear low-density grades dominate flexible food packaging through blown film extrusion. German retail chains specify downgauged PE structures to meet EU Packaging and Packaging Waste Regulation material intensity targets.
- Polypropylene:Biaxially oriented PP delivers stiffness and clarity for snack and confectionery lidding. Cast PP films are displacing metallized PET in modified atmosphere bread packaging across French and Italian bakeries.
- Polyester:Biaxially oriented polyethylene terephthalate provides dimensional stability and optical clarity for pharmaceutical blister lidding. Metallized PET variants are overtaking aluminum foil in moisture-sensitive biologics packaging.
- Nylon:Polyamide 6 and 6/6 copolymers supply puncture resistance and oxygen barrier in vacuum meat packaging. European polyamide supply consolidation around limited polymer producers creates feedstock vulnerability for regional coextrusion lines.
Polyethylene absorbs the bulk of installed capacity; nylon is expanding most quickly in high-performance pharmaceutical applications.
End User:
Customer procurement patterns split between price-sensitive food volume contracts and pharmaceutical qualification-driven supply relationships with 18-24 month onboarding timelines.
- Food & Beverage:Modified atmosphere packaging for red meat, ready-to-eat produce, and plant-based proteins drives oxygen barrier film specifications. German discount retailers are consolidating supplier lists around converters with EFSA-compliant recycled content verification.
- Pharmaceuticals:Primary packaging for biologics and cell therapies demands sub-0.1 cc/m²/day oxygen transmission rates plus extractables and leachables documentation under FDA container closure system guidelines. Cold-chain distribution networks around Düsseldorf and Hamburg are scaling flexible barrier R&D capacity.
- Consumer Goods:Cosmetic and personal care applications emphasize moisture barrier and aesthetic surface properties. Premium fragrance brands specify metallized films for light protection and shelf presence.
- Electronics:Static-dissipative barrier pouches protect semiconductors and components from moisture and electrostatic discharge during ocean freight. German automotive electronics clusters near Stuttgart drive demand for vacuum-sealed desiccant packaging.
Food and beverage commands the largest volume share; pharmaceuticals is climbing the fastest as biologics cold-chain requirements tighten.
Packaging Type:
Format selection trades off material efficiency and line speed against child-resistance, senior-friendliness, and automated dispensing compatibility.
- Flexible Packaging:Multi-layer coextruded films and laminates dominate food applications through downgauging and format versatility. Stand-up pouches with reclosure features are displacing rigid containers in German ready-to-eat meal segments.
- Rigid Packaging:Injection-molded and thermoformed barriers serve pharmaceutical primary packaging where moisture protection and child-resistance standards are non-negotiable. Blister packs with aluminum-barrier lidding remain the default for solid oral dose forms.
- Pouches:Pre-made and form-fill-seal pouch formats integrate spouts, fitments, and reclosure systems for liquid and semi-solid products. Retort pouches for shelf-stable pet food are gaining share in European superpremium segments.
- Films:Rollstock formats supply downstream converting operations and in-house forming at food processors. High-barrier metallized PET films are expanding in pharmaceutical roll-fed applications previously served by rigid aluminum.
Flexible packaging holds the majority of extrusion capacity; rigid formats maintain margin concentration in pharmaceutical primary packaging.
Application:
Barrier function specification determines polymer selection, layer structure complexity, and validation testing protocols.
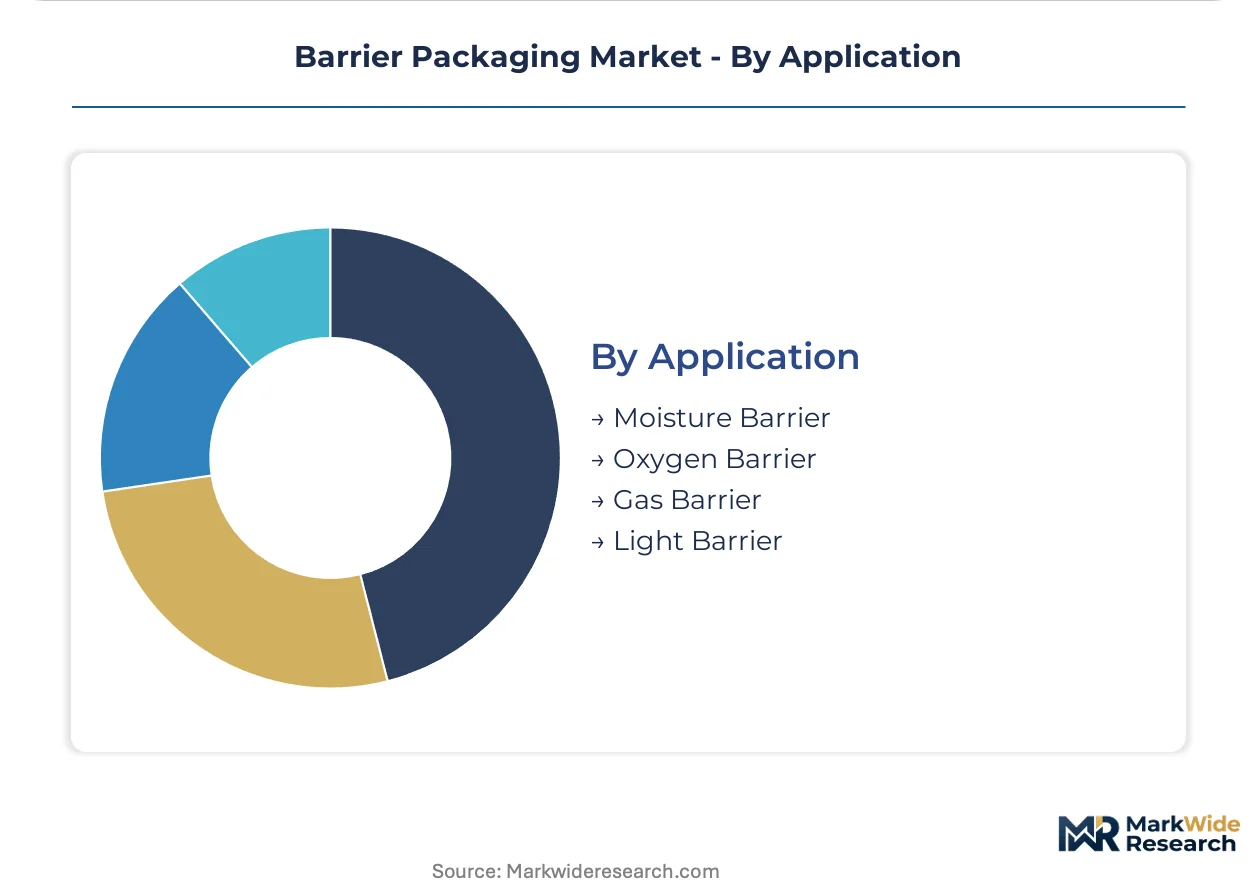
- Moisture Barrier:Aluminum foil, metallized films, and ethylene vinyl alcohol copolymers prevent water vapor transmission in pharmaceutical and dehydrated food applications. Hydrophilic pharmaceutical APIs require moisture vapor transmission rates below 0.5 g/m²/day.
- Oxygen Barrier:EVOH and polyamide tie layers within coextruded structures achieve sub-0.1 cc/m²/day transmission rates for modified atmosphere packaging. Plant-based protein packaging specifications are pushing oxygen barrier requirements beyond red meat benchmarks.
- Gas Barrier:Multi-layer structures incorporating aluminum oxide or silicon oxide coatings block carbon dioxide and flavor scalping in carbonated beverages and aromatic products. German mineral water brands specify gas barrier films for premium PET bottle labels.
- Light Barrier:Opaque or metallized layers protect photosensitive pharmaceuticals, vitamins, and dairy products from UV degradation. Amber-tinted and metallized formats are standard for light-sensitive biologics in cold-chain distribution.
Oxygen barrier applications absorb the bulk of EVOH and polyamide consumption; moisture barrier specifications are gaining share fastest in biologics packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf anchors European pharmaceutical barrier packaging capacity, with clusters expanding flexible film R&D to serve biologics cold-chain distribution across the continent.
Germany
Pharmaceutical packaging clusters around Düsseldorf and Hamburg scale flexible barrier R&D capacity for pan-European biologics distribution. The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds that force converters to validate post-consumer feedstocks. Bavarian coextrusion lines invest in decontamination-capable recycling infrastructure to meet EFSA safety assessments for food-contact layers.
United States
FDA container closure system guidelines enforce stringent extractables and leachables testing for pharmaceutical barrier materials, extending qualification timelines. Modified atmosphere packaging specifications for plant-based proteins drive oxygen barrier film demand beyond red meat benchmarks. Midwest flexible packaging converters around Chicago expand multi-layer blown film capacity to serve branded food manufacturers.
China
SAMR regulations on food-contact materials and dual carbon goals reshape converter investment priorities toward recyclable mono-material structures. Yangtze River Delta packaging hubs develop metallized PET alternatives to aluminum foil for moisture-sensitive pharmaceuticals. NMPA pharmaceutical packaging standards tighten oxygen transmission rate tolerances for domestic biologics manufacturers.
India
CDSCO pharmaceutical packaging regulations and FSSAI food-contact material standards create dual compliance burdens for multi-layer converters. Maharashtra flexible packaging clusters around Mumbai expand EVOH coextrusion capacity for modified atmosphere applications in ready-to-eat meals. PLI scheme incentives attract investment in high-barrier film manufacturing for export-oriented pharmaceutical clients.
Japan
METI circular economy roadmaps and JIS standards for packaging recyclability drive converter reformulation of multi-layer structures. Kanto region pharmaceutical manufacturers specify cryogenic barrier films for cell therapy cold-chain logistics. Osaka-based converters develop silicon oxide-coated films to replace fluoropolymer grease barriers ahead of 2025 enforcement deadlines.
Barrier Packaging Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification intensity and qualification timeline dimensions, with pharmaceutical-grade barrier specialists commanding structural advantages in extractables documentation and cold-chain validation. The vendor base organizes into three tiers: global film extrusion networks with integrated technical service capabilities, regional coextrusion specialists focused on food-grade modified atmosphere packaging, and aluminum-barrier pure-plays serving pharmaceutical blister lidding. Consolidation pressure concentrates around converters with validated EFSA recycling pathways and in-house decontamination assets. Capacity expansion and strategic partnership formation represent the dominant competitive moves as brand owners reduce qualified vendor lists from 15-20 to 5-8 strategic partners.
Within the global network tier, Amcor plc, Berry Global Inc., and Constantia Flexibles Group occupy positions that exemplify divergent specialization vectors. Amcor leverages its geographic footprint to sustain technical service relationships with pharmaceutical clients requiring extensive qualification documentation. Berry anchors North American flexible barrier capacity through multi-layer coextrusion platforms serving food and healthcare segments. Constantia competes in European pharmaceutical blister lidding through aluminum-barrier specialization, representing the pure-play model against integrated film extrusion alternatives. These three entities collectively illustrate how scale, regional concentration, and material-specific expertise partition competitive position.
| Leading Market Players |
|---|
| Mondi Group |
| Toray Plastics |
| Amcor plc |
| Uflex Limited |
| Huhtamaki Group |
| Sealed Air Corporation |
| Constantia Flexibles Group |
| TC Transcontinental |
| Berry Global Inc. |
| Others |
Supply Flow & Price Mechanics
Aluminum London Metal Exchange contract volatility cascades through metallized film converters into pharmaceutical blister lidding pricing tiers, compressing margins on fixed-price biologics contracts while rewarding converters with backward-integrated polymer extrusion assets.
Pricing Analysis
Oxygen transmission rate certification anchors value-based pricing across pharmaceutical barrier grades, with sub-0.1 cc/m²/day specifications commanding premiums over commodity food-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated extractables documentation from EFSA food-contact compliance and generic industrial grades. Pricing pressure stems from aluminum feedstock volatility and polyamide supply consolidation in European petrochemical corridors. Food discount retailers exhibit highest price sensitivity; biologics manufacturers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from pharmaceutical brand owners force converters to qualify redundant EVOH and polyamide feedstock streams across Germany, the Netherlands, and Belgium. Raw material dependencies center on ethylene vinyl alcohol copolymers, metallized polyethylene terephthalate substrates, and aluminum foil laminates. Single-source vulnerability concentrates in European polyamide 6 capacity around limited polymer producers. Distribution runs through converter direct-to-brand-owner channels with embedded technical service relationships, bypassing traditional distributor networks for qualified pharmaceutical grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation recycled content mandates are accelerating consolidation as smaller converters face stranded asset risk in non-decontamination-capable extrusion lines.
For Market Incumbents: Anchor pharmaceutical qualification relationships through captive extractables testing laboratories and cold-chain validation protocols. Defensive moves require EFSA-compliant recycling pathway investment and multi-layer coextrusion capacity expansion in Düsseldorf-Hamburg pharmaceutical clusters. Threat of brand owner vendor list compression from 15-20 to 5-8 strategic partners demands preemptive technical service deepening. For New Entrants and Emerging Players: Begin with plant-based protein modified atmosphere packaging specifications in German and French retail channels, where ultra-high-barrier film demand outpaces qualified converter supply. White-space targets include cryogenic barrier films for cell therapy distribution and silicon oxide-coated alternatives to fluoropolymer grease barriers. Go-to-market angle emphasizes rapid EFSA food-contact authorization alongside brand owner sustainability credential requirements. For Investors and Strategic Acquirers: Converter acquisition of decontamination-capable recycling infrastructure is the leading indicator that circular economy positioning is translating into defendable pharmaceutical vendor list placement. Long-term viability favors vertically integrated film extruders with in-house EVOH coextrusion and validated post-consumer feedstock streams. Signal to monitor: extended producer responsibility fee structure implementation across Northern European markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Coextrusion | Captive oxygen barrier capacity insulates margin from polyamide supply concentration in Belgian and Dutch petrochemical corridors. |
| EFSA Food-Contact Authorization Investment | Validated decontamination processes unlock first-mover advantage in EU-mandated recycled content multi-layer structures. |
| Pharmaceutical Cold-Chain Technical Service Expansion | Embedded extractables documentation support extends qualification timelines into 18-24 month switching costs for biologics clients. |
| Metallized PET Capacity Buildout | Flexible roll-fed formats displace rigid aluminum foil in moisture-sensitive pharmaceutical primary packaging segments. |
| Multi-Supplier Feedstock Qualification | Dual-sourcing compliance with pharmaceutical brand owner mandates reduces single-source polyamide vulnerability. |
Methodological Framework
Independent corroboration across converter operations executives, pharmaceutical packaging procurement directors, and polymer feedstock sourcing managers underwrites the qualitative findings. Secondary validation draws from EFSA safety assessments, FDA container closure system guidance documents, EU Packaging and Packaging Waste Regulation impact assessments, and trade data from German flexible packaging industry associations. Bottom-up capacity modeling triangulates against top-down demand segmentation across food, pharmaceutical, and industrial end-use categories.
Comparable-period anchoring to historical pharmaceutical qualification timelines and food packaging specification shifts structures the projection horizon. Segmentation dimensions span material type, barrier function specification tier, packaging format rigidity, and regional regulatory cluster intensity. CAGRs derive from installed extrusion capacity expansion announcements cross-referenced with brand owner vendor list consolidation patterns and EVOH consumption trajectories in modified atmosphere applications.
Underlying measurement precision varies by segment; pharmaceutical-grade barrier specifications carry tighter precision than commodity food-grade alternatives due to extractables documentation requirements. Forecasts reflect assumptions regarding EU recycled content mandate enforcement timing, aluminum price volatility persistence, and polyamide supply consolidation trajectories. Deviation in EFSA authorization timelines for post-consumer polyolefins would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Transparent Barrier Films Market
Packaging Barrier Films
High Barrier Lidding Film Market
Packaging Barrier Films
Liquid Masking Film Market
Packaging Barrier Films
Global Silicone Release Liner Market
Packaging Barrier Films
USA Barrier Coated Paper Market
Packaging Barrier Films
Stretch Hood Films Market
Packaging Barrier Films
Anti-Fog Lidding Films Market
Packaging Barrier Films
Metalized Barrier Film Packaging Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Flow Pack Films Market
Packaging Barrier Films
Collation Shrink Films Market
Packaging Barrier Films
Bio-Based Sealant Films Market
Packaging Barrier Films
Saudi Arabia Plastic Packaging Films Market
Packaging Barrier Films
Meat Packaging Films Market