
 Specialty Films Market | 2026-2036
Specialty Films Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Films Market Intelligence
Specialty film distribution through regional compounders and converter networks is reshaping how formulations reach end-users. Covestro AG leverages its polycarbonate film expertise to anchor European automotive and electronics supply chains. DuPont Teijin Films competes through biaxially oriented PET capacity that sustains high-barrier performance for photovoltaic backsheet and flexible electronics substrates. Toray Industries dominates Asian supply of polyimide and optical-grade films, extending its position through captive resin synthesis and precision coating capabilities.
Specialty films are engineered polymer substrates, typically between 12 and 250 micrometers in thickness, manufactured through controlled extrusion, orientation, and surface modification processes to deliver precise optical, barrier, thermal, or mechanical functions for demanding industrial applications. Polyester films lead in volume due to mature biaxial orientation infrastructure and broad compatibility with vapor-deposited barrier layers, while biodegradable formulations represent the fastest-expanding category as brand owners face mounting pressure to eliminate persistent plastic fractions from packaging streams. Barrier films command the strongest margin pools because multilayer co-extrusion and atomic layer deposition technologies create steep technical moats around oxygen and moisture transmission specifications.
REACH registration requirements and the EU Green Deal framework constrain phthalate plasticizer use and mandate recyclability disclosures, pushing converters toward verified bio-based feedstocks and monomaterial constructions. FDA food-contact notification rules and EPA per- and polyfluoroalkyl substance restrictions in the United States are eliminating fluorinated barrier chemistries from food packaging applications. Stakeholders must monitor regulatory divergence between jurisdictions and decide whether to standardize formulations globally or maintain region-specific product lines.
Market Dynamics
Specialty film manufacturers face mounting pressure from REACH registration requirements and the EU Green Deal framework, which constrain phthalate plasticizer use and mandate recyclability disclosures across European supply chains. This regulatory compression is forcing converters toward verified bio-based feedstocks and monomaterial constructions while reshaping competitive positioning among regional compounders.
Growth Catalysts
- Flexible packaging penetration:Food and pharmaceutical supply chains are accelerating adoption of high-barrier multilayer films to extend shelf life and reduce spoilage losses across cold-chain logistics networks.
- REACH compliance evolution:European substrate requirements are tightening around persistent organic pollutants, creating technical moats for converters with verified sustainable chemistry portfolios and circular material certifications.
- Electronics manufacturing clustering:China, India, and Germany are expanding domestic polymer processing capacity to serve photovoltaic backsheet and flexible electronics substrate demand from captive resin synthesis facilities.
Market Restraints
- Fluorinated chemistry phase-out:EPA per- and polyfluoroalkyl substance restrictions are eliminating fluorinated barrier chemistries from food packaging applications, forcing costly reformulation of oxygen and moisture transmission specifications.
- Optical-grade resin concentration:Polyimide and polycarbonate precursor supply concentrates among Asian petrochemical complexes, exposing European and North American converters to freight volatility and currency fluctuation risks.
- Atomic layer deposition capex barriers:Multilayer co-extrusion and vapor-deposited barrier layer equipment requires substantial capital commitment, limiting margin pool capture to well-capitalized integrated producers.
Strategic Opportunities
- Biodegradable formulation expansion:Brand owner pressure to eliminate persistent plastic fractions from packaging streams is opening margin pools for converters with certified compostable film portfolios and industrial composting infrastructure partnerships.
- Photovoltaic backsheet localization:Biaxially oriented PET capacity expansion in India and Southeast Asia creates white space for regional converters to displace imported high-barrier films in solar module manufacturing clusters.
- FDA food-contact notification alignment:Converters with pre-submitted food-contact material dossiers can capture share from competitors facing extended approval timelines under evolving United States notification rules.
Industry Challenges
- Precision coating talent scarcity:Surface modification process engineers with atomic layer deposition and plasma treatment expertise command premium compensation, constraining mid-cap converter expansion timelines.
- Regulatory divergence management:Stakeholders must maintain parallel formulation portfolios or accept margin compression from region-specific product line complexity across REACH, FDA, and evolving Asian chemical registration frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Films Market |
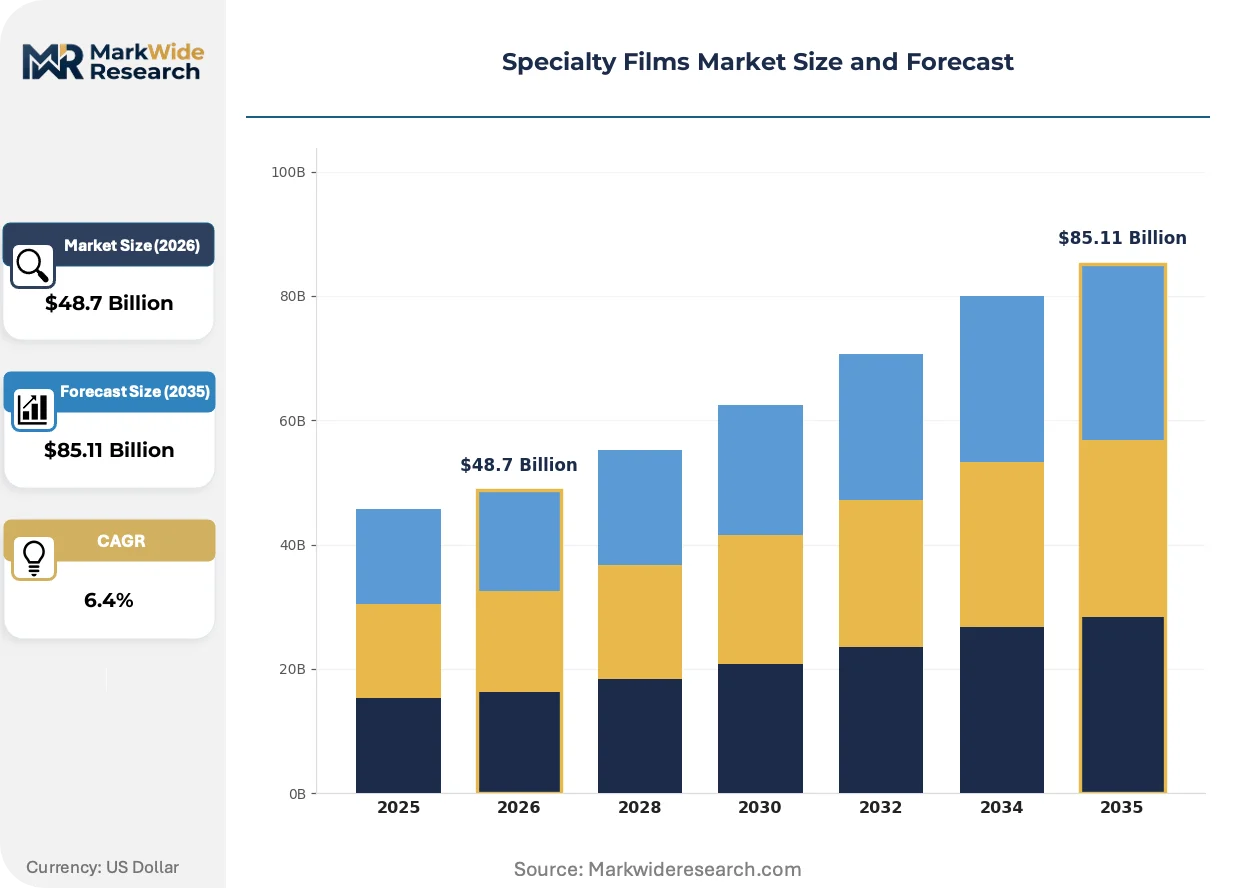
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polyethylene, Polypropylene, Biodegradable End User: Packaging, Agriculture, Electronics, Construction Technology: Cast Extrusion, Blown Film, Co-Extrusion, Layering Application: Flexible Packaging, Solar Control, Security Films, Barrier Films |
| Companies Covered | Covestro AG, DuPont Teijin Films, SABIC, 3M Company, Honeywell International Inc., Toray Industries, Inc., Saint-Gobain, Solvay S.A., Berry Global Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Films Market Strategic Shifts & Innovations
Barrier film technology is hybridizing with deposition processes to create substrate solutions that simultaneously address optical clarity, thermal stability, and environmental compliance requirements. Three active developments are compressing traditional material boundaries and reshaping how specifications reach end-users.
Atomic layer deposition is hybridizing with biaxially oriented polyester substrates to achieve sub-nanometer barrier precision for flexible electronics and organic photovoltaics. Display manufacturers in South Korea and Japan are qualifying these hybrid structures for foldable device encapsulation at accelerated timelines. The convergence is compressing market space for conventional multilayer co-extrusion in premium barrier applications.
The EU F-Gas Regulation and accompanying ECHA restrictions on perfluorinated compounds are eliminating legacy barrier chemistries from food-contact applications by mandated phase-out deadlines. European converters are responding by accelerating monomaterial construction development and bio-based feedstock verification through mass-balance certification schemes. North American suppliers serving export markets must parallel-track compliance or forfeit European pharmaceutical and premium food packaging contracts.
Regional compounder networks are consolidating procurement authority through converter consortium structures that bypass traditional distributor markups. German automotive and electronics clusters are piloting direct formulation partnerships with polycarbonate film specialists, disintermediating legacy chemical distribution channels. This channel compression is most visible in Bavaria and Baden-Württemberg, where just-in-time substrate delivery requirements favor localized compounding capacity over centralized import logistics.
Specialty Films Market Segmentation
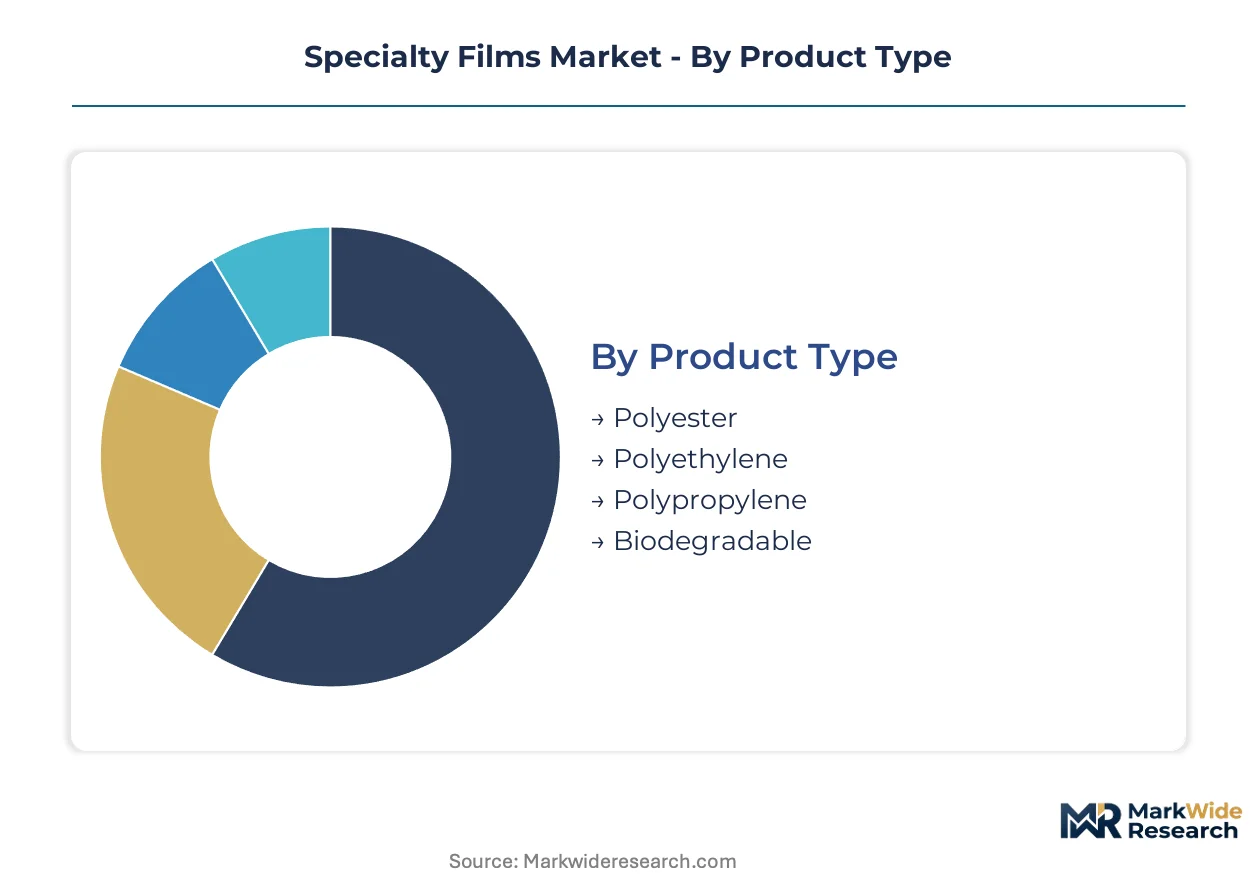
Specialty film specifications diverge sharply across end-use requirements, with thickness tolerances, barrier coefficients, and surface energy profiles determining formulation choices. Understanding how product families, manufacturing technologies, and application demands intersect reveals where margin pools concentrate and where technical moats form.
Product Type:
Material chemistry governs thermal stability, optical clarity, and compatibility with downstream processing such as metallization or coating.
- Polyester:Biaxially oriented polyethylene terephthalate dominates photovoltaic backsheet and flexible electronics substrates due to mature orientation infrastructure and vapor-deposited barrier layer adhesion. Demand clusters in Chinese solar module manufacturing corridors and German automotive clusters seeking high-temperature dimensional stability.
- Biodegradable:Polylactic acid and polyhydroxyalkanoate formulations are gaining formulation share as EU Green Deal mandates and brand owner commitments eliminate persistent plastic fractions from premium packaging streams. European converters with mass-balance certification capture price premiums in food-contact applications.
- Polyethylene:Linear low-density variants serve cost-sensitive agricultural mulch and industrial liner applications where moisture barrier suffices.
- Polypropylene:Oriented polypropylene films compete in snack food flexible packaging through clarity and heat-seal performance.
Polyester commands the established base. The steepest expansion runs through Biodegradable.
End User:
Customer verticals impose distinct certification regimes and performance specifications that reshape converter capabilities.
- Packaging:Food and pharmaceutical supply chains drive multilayer barrier film specifications with oxygen transmission rates below 0.1 cc/m²/day. FDA food-contact notification requirements and REACH compliance create qualification moats for converters with pre-submitted dossiers.
- Electronics:Display manufacturers in South Korea and Japan specify polyimide and optical-grade polycarbonate for foldable device substrates and OLED encapsulation. Atomic layer deposition hybridization with polymer films enables sub-nanometer barrier precision.
- Agriculture:Greenhouse and mulch films prioritize UV stabilization and mechanical durability over barrier performance.
- Construction:Architectural window films and protective membranes emphasize solar control and abrasion resistance.
Packaging absorbs the dominant volume share. Electronics delivers the fastest margin expansion.
Technology:
Process selection determines thickness uniformity, layer count, and capital intensity for converter operations.
- Co-Extrusion:Multilayer co-extrusion enables five-to-nine-layer structures combining tie layers, barrier resins, and sealants in single-pass production. The technology anchors high-barrier food packaging specifications requiring moisture and oxygen transmission control.
- Layering:Lamination and coating processes permit discrete functional layers such as vapor-deposited aluminum or silicon oxide for ultra-high barrier applications in pharmaceutical blister packs and organic photovoltaics.
- Cast Extrusion:Chill-roll casting delivers gauge uniformity for optical and graphic arts films.
- Blown Film:Tubular processes suit agricultural and industrial films where clarity is secondary to toughness.
Co-Extrusion retains the largest installed base. Layering posts the steepest capability investment.
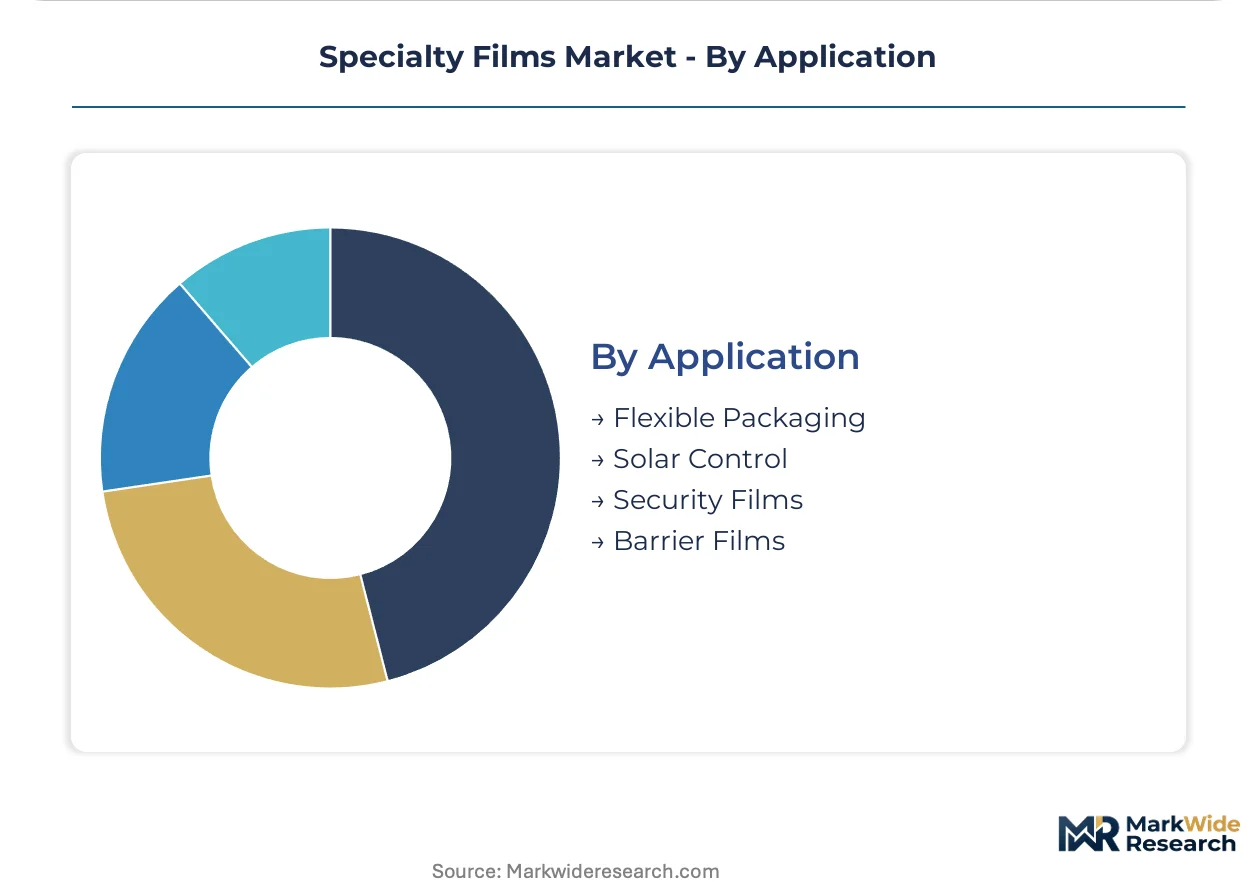
Application:
Functional requirements segment the market by performance tier and regulatory exposure.
- Barrier Films:Multilayer structures with atomic layer deposition or vapor-deposited coatings command premium pricing due to steep technical requirements for oxygen and moisture transmission. Applications span pharmaceutical cold-chain packaging and flexible electronics encapsulation where failure rates must approach zero.
- Flexible Packaging:Food and consumer goods converters specify high-clarity, heat-sealable films with tailored coefficient of friction for high-speed form-fill-seal lines. EU F-Gas Regulation phase-outs are eliminating fluorinated barrier chemistries, forcing monomaterial construction development.
- Solar Control:Architectural and automotive window films incorporate infrared-reflective coatings for energy efficiency compliance.
- Security Films:Tamper-evident and anti-counterfeiting layers serve government documents and high-value product authentication.
Flexible Packaging generates the broadest revenue base. Barrier Films capture the highest margin intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese converters extract pricing premiums from photovoltaic backsheet specifications while German automotive clusters absorb margin compression from REACH compliance costs. Indian domestic polymer processing capacity is displacing imported substrates across solar module manufacturing corridors. Japanese display manufacturers anchor optical-grade film demand through foldable device qualification timelines.
China
Yangtze River Delta solar module manufacturers drive biaxially oriented PET consumption for photovoltaic backsheet applications at scale. MIIT dual carbon goals accelerate domestic polymer processing capacity expansion across Jiangsu and Zhejiang provinces. Ningbo and Suzhou industrial clusters host captive resin synthesis facilities serving flexible electronics substrate demand.
Germany
Bavarian automotive OEMs specify polycarbonate films for high-temperature dimensional stability in electric vehicle battery enclosures. ECHA REACH registration requirements constrain phthalate plasticizer formulations across converter networks. Baden-Württemberg electronics clusters pilot direct formulation partnerships with regional compounders, bypassing legacy distribution channels.
India
Gujarat and Maharashtra polymer processors expand biaxially oriented PET capacity to serve domestic photovoltaic manufacturing under PLI scheme incentives. BIS certification requirements tighten substrate specifications for food-contact applications. Tamil Nadu solar module assembly corridors localize barrier film sourcing previously imported from East Asian suppliers.
United States
Midwest flexible packaging converters face FDA food-contact notification rule evolution and EPA per- and polyfluoroalkyl substance restrictions simultaneously. Michigan and Ohio industrial corridors reformulate oxygen barrier specifications without fluorinated chemistries. Southeast distribution hubs manage regional compounder procurement through converter consortium structures.
Japan
Kanto display manufacturers qualify polyimide substrates for foldable device encapsulation at accelerated timelines. METI industrial standards guide atomic layer deposition hybridization with polymer films for organic photovoltaics. Osaka-Kyoto precision coating clusters concentrate surface modification process engineering talent for sub-nanometer barrier applications.
Specialty Films Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream capturing margin from formulation IP and precision coating capabilities. The vendor base organizes around three strategic archetypes: integrated petrochemical producers with captive resin synthesis, regional compounders with converter network partnerships, and precision coating specialists with atomic layer deposition expertise. Consolidation pressure concentrates among mid-cap converters facing atomic layer deposition capex barriers. Capacity expansion and strategic partnerships represent the dominant competitive moves as players localize supply chains around Chinese solar manufacturing and German automotive clusters.
Within the integrated petrochemical tier, Covestro AG and Toray Industries occupy positions anchoring European and Asian supply chains respectively. DuPont Teijin Films exemplifies the precision-oriented archetype through biaxially oriented PET specialization. These three entities represent distinct geographic and technological positioning vectors without overlapping core competencies.
| Leading Market Players |
|---|
| Covestro AG |
| DuPont Teijin Films |
| SABIC |
| 3M Company |
| Honeywell International Inc. |
| Toray Industries, Inc. |
| Saint-Gobain |
| Solvay S.A. |
| Berry Global Group, Inc. |
| Others |
Cost & Logistics Intelligence
Polyimide and polycarbonate precursor concentration among Asian petrochemical complexes anchors margin pools downstream in European and North American converter networks. Freight volatility and currency fluctuation risks cascade through formulation costs, compressing returns for non-integrated compounders while rewarding captive resin synthesis operations.
Pricing Analysis
Configured-to-order pricing for barrier films with atomic layer deposition hybridization commands spreads of 40-60 percent above standard biaxially oriented PET commodity grades. Pricing stratifies across premium, standard, and economy tiers based on oxygen transmission certification levels and volume commitment scale. Cost compression in standard-grade polyester films is intensifying because Chinese capacity expansion outpaces regional demand absorption. Mid-cap converters serving agricultural and industrial liner segments exhibit highest price sensitivity, while pharmaceutical cold-chain packaging buyers prioritize barrier performance over unit economics.
Supply Chain Analysis
Export-control regimes restricting vapor-deposition equipment and atomic layer deposition technology flows from Japan and the United States constrain barrier film capability diffusion. Geographic supply concentration centers on China for biaxially oriented PET, Japan for polyimide precursor, and Germany for polycarbonate film. Raw material dependencies span purified terephthalic acid, dimethyl terephthalate, and dianhydride monomers. Single-source vulnerability around Japanese precision coating equipment creates chokepoint exposure for sub-nanometer barrier qualification. Distribution runs through regional compounder networks and converter consortium structures that bypass legacy chemical distribution markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty film markets increasingly reward formulation-as-a-service models where technical support and certification management generate recurring revenue streams expanding faster than substrate tonnage. Precision coating expertise subscriptions and regulatory dossier maintenance contracts represent the fastest-attaching revenue layers.
For Market Incumbents: Insulate barrier film margin pools through captive atomic layer deposition capacity expansion in Bavarian and Baden-Württemberg clusters. Deepen backward integration into optical-grade resin synthesis to offset Asian precursor price volatility. Accelerate REACH-compliant bio-based feedstock verification to preempt regulatory displacement of phthalate plasticizer formulations.
For New Entrants and Emerging Players: Establish a beachhead in Indian photovoltaic backsheet localization under PLI scheme incentives, where domestic biaxially oriented PET capacity expansion creates white space for regional converters. Target biodegradable formulation partnerships with European food-contact packaging brand owners facing EU Green Deal compliance deadlines. Lead with mass-balance certification and industrial composting infrastructure alliances as differentiated go-to-market positioning.
For Investors and Strategic Acquirers: Capital is best deployed toward precision coating specialists with atomic layer deposition expertise and existing FDA food-contact notification dossiers, given long-term viability through the next technology replacement cycle. Acquisition target archetypes include mid-cap converters facing capex barriers but holding converter network relationships in German automotive or Japanese display supply chains. Monitor Japanese METI industrial standards evolution for foldable device encapsulation as inflection indicator for polyimide substrate demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical-Grade Resin Synthesis | Covestro AG and Toray Industries reduce Asian precursor dependency through captive supply of polycarbonate and polyimide feedstocks. |
| Atomic Layer Deposition Capacity Expansion | DuPont Teijin Films captures sub-nanometer barrier specifications for South Korean foldable display manufacturers. |
| Mass-Balance Certification Investment | European converters with verified bio-based feedstock portfolios capture price premiums under EU Green Deal mandates. |
| Converter Consortium Procurement Structuring | German automotive clusters in Bavaria bypass legacy distribution channels through direct formulation partnerships with regional compounders. |
| FDA Food-Contact Notification Pre-Submission | Converters with pre-submitted dossiers capture share from competitors facing extended approval timelines under evolving United States notification rules. |
Research Approach
A spread of perspectives from extrusion plant managers, procurement leads at flexible packaging OEMs, distribution channel partners, and technical R&D directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, Cefic sector reports, SEC 10-K filings, and pharmaceutical packaging regulatory databases. Bottom-up capacity and consumption modeling triangulated against top-down value chain estimates.
Demand-supply balance dynamics across the analysis window anchored the quantitative framework, with segmentation dimensions spanning material chemistry grade, end-use industry vertical, barrier performance tier, and regional production hub cluster. CAGRs were derived from slope analysis of installed capacity expansion trajectories and end-use demand elasticity coefficients. Forecast inputs incorporated photovoltaic backsheet localization timelines, REACH registration compliance cost curves, and foldable device substrate qualification velocities.
Stress conditions across resin price volatility bands, regulatory phase-out deadlines, and equipment lead time extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology adoption curves and regional manufacturing cluster formation. Material shifts in EPA per- and polyfluoroalkyl substance enforcement intensity or EU F-Gas Regulation acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Decorative Films and Foils Market
Packaging Barrier Films
Heat Transfer Films Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
South America Solar Control Window Films Market
Packaging Barrier Films
Global Stretch and Shrink Film Market
Packaging Barrier Films
High Performance Barrier Films Market
Packaging Barrier Films
Global Peelable Lidding Films Market
Packaging Barrier Films
Polyethylene Vapor Barrier Films for Under Slab Market
Packaging Barrier Films
Anti-Static Packaging Film Market
Packaging Barrier Films
Heat Insulating Films Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
Global Air Bubble Film Machines Market
Packaging Barrier Films
Global Adhesive Films Market
Packaging Barrier Films
Biobased Anti-Blocking Agents for Flexible Packaging Films Market