
 Tray Liners Market | 2026-2036
Tray Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Tray Liners Market Analytics
Premium grease-resistant grades is reorganizing competitive dynamics in tray liners as quick-service restaurants and institutional foodservice operators upgrade specifications. Georgia-Pacific LLC leverages its integrated pulp-to-paperboard supply chain to sustain cost leadership in North American foodservice accounts. Hoffmaster Group, Inc. differentiates through specialized printed and custom-cut formats that anchor its position in catering and hospitality channels. Novolex Holdings, Inc. competes across both paper and plastic substrates, extending manufacturing scale into regional distribution networks.
Tray liners are single-use protective sheets placed beneath food items on serving trays, typically manufactured from bleached kraft paper, polyethylene-coated paper, or aluminum foil laminates with basis weights ranging from 20 to 40 pounds per ream to resist moisture and grease penetration. Their primary purpose is to maintain tray sanitation, absorb spills, and provide a printable surface for branding or nutritional messaging in commercial foodservice environments. Paper-based tray liners lead volume due to cost efficiency and recyclability alignment, while biodegradable alternatives represent the fastest-expanding category as operators respond to municipal composting mandates and corporate sustainability targets. Heavy-duty specifications command stronger margins in industrial and airline catering applications where durability requirements exceed standard foodservice thresholds.
The US FDA regulates food-contact substances under 21 CFR, while the EPA oversees recycling and waste management standards affecting end-of-life disposal pathways for disposable foodservice items. State-level legislation in California, New York, and Washington restricts single-use plastics and mandates post-consumer recycled content, directly shaping material selection and supplier qualification criteria. The EU's Packaging and Packaging Waste Regulation and REACH chemical compliance frameworks create parallel requirements for exporters serving European foodservice accounts. Stakeholders must monitor evolving extended producer responsibility schemes and substrate-specific bans to align product portfolios with jurisdictionally fragmented compliance landscapes.
Market Dynamics
Quick-service restaurant chains are consolidating procurement specifications around grease-resistant paperboard grades, forcing substrate suppliers to retool coating lines and bleaching sequences to meet unified performance thresholds across multi-state franchise networks.
Growth Catalysts
- State plastic bans:California, New York, and Washington restrictions on single-use plastics are accelerating conversions to paper-based tray liners in foodservice operations.
- Composting infrastructure:Municipal composting mandates in metropolitan areas are creating certified biodegradable liner demand from institutional catering contracts.
- Quick-service expansion:Drive-thru and delivery-optimized formats are multiplying tray touchpoints, expanding liner consumption per location.
Market Restraints
- Pulp cost volatility:Northern bleached softwood kraft pulp prices swing with energy and logistics inputs, compressing converter margins unpredictably.
- Coating chemical restrictions:PFAS limitations under EPA and state-level frameworks are eliminating legacy grease-barrier chemistries before replacements achieve cost parity.
- Aluminum foil substitution:Heavy-duty airline and industrial catering segments retain foil laminates where durability requirements exceed paper capabilities.
Strategic Opportunities
- Midwest manufacturing corridor:Underpenetrated regional quick-service chains in Ohio, Michigan, and Illinois present volume consolidation targets for integrated suppliers.
- Digital printing integration:Variable-data inkjet systems enable hyper-local promotional messaging, differentiating liner suppliers in regional franchise bidding.
- USDA BioPreferred program:Federal procurement preferences for biobased products create qualified supplier status advantages in school and military foodservice.
Industry Challenges
- PFAS remediation timelines:Food-contact material reformulation requires 18-24 month FDA notification cycles, delaying product launches.
- Legacy equipment retrofitting:Existing coating and drying assets require capital-intensive reconfiguration to handle water-based barrier chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tray Liners Market |
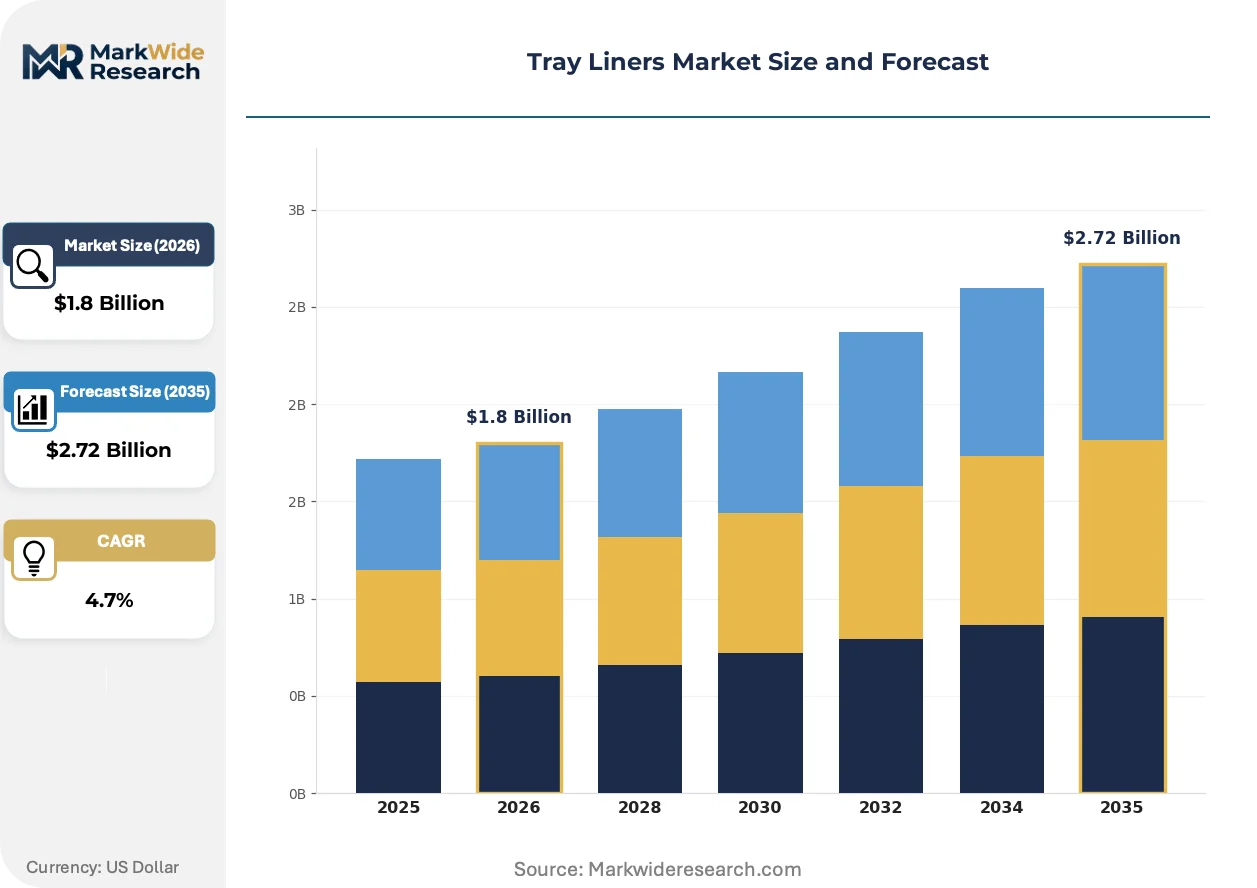
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paper, Plastic, Foil, Biodegradable Application: Food Service, Retail, Catering, Industrial Thickness: Thin, Standard, Heavy-Duty, Custom Distribution Channel: Online, Retail Stores, Wholesalers, Direct Sales |
| Companies Covered | Seaman Paper Company, Hoffmaster Group, Inc., Georgia-Pacific LLC, Novolex Holdings, Inc., International Paper Company, WestRock Company, Graphic Packaging International, LLC, Reynolds Consumer Products, Placon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tray Liners Market Evolving Landscape
Barrier coating chemistry is undergoing forced transition as regulatory pressure eliminates legacy performance additives, while digital production technologies are collapsing minimum order quantities and compressing design-to-delivery cycles.
Water-based and bio-wax barrier formulations are fragmenting the grease-resistance segment as quick-service chains accelerate PFAS phaseouts ahead of compliance deadlines. Chains with 500-plus unit counts are piloting these substitutes in regional test markets. The technology is fragmenting supplier consolidation by enabling smaller regional converters to meet performance specs previously locked by multinational chemical coating partnerships.
EPA's emerging PFAS reporting requirements under TSCA Section 8(a)(7) are compelling full supply chain disclosure of fluorinated chemistries in food-contact articles. Converters must now document coating compositions back to base resin suppliers. Quick-service franchisees in coastal states are responding fastest, demanding pre-certified substrate documentation to preempt liability exposure.
Consolidated procurement through franchise-level master agreements is displacing location-by-location purchasing, concentrating volume with suppliers capable of national distribution and unified specification compliance. Regional distributors are losing share to direct manufacturer relationships. This pattern is most visible in the Southeast, where multi-state franchise operators are centralizing liner specifications to simplify inventory management across Tennessee, Georgia, and Florida operations.
Tray Liners Market Segmentation
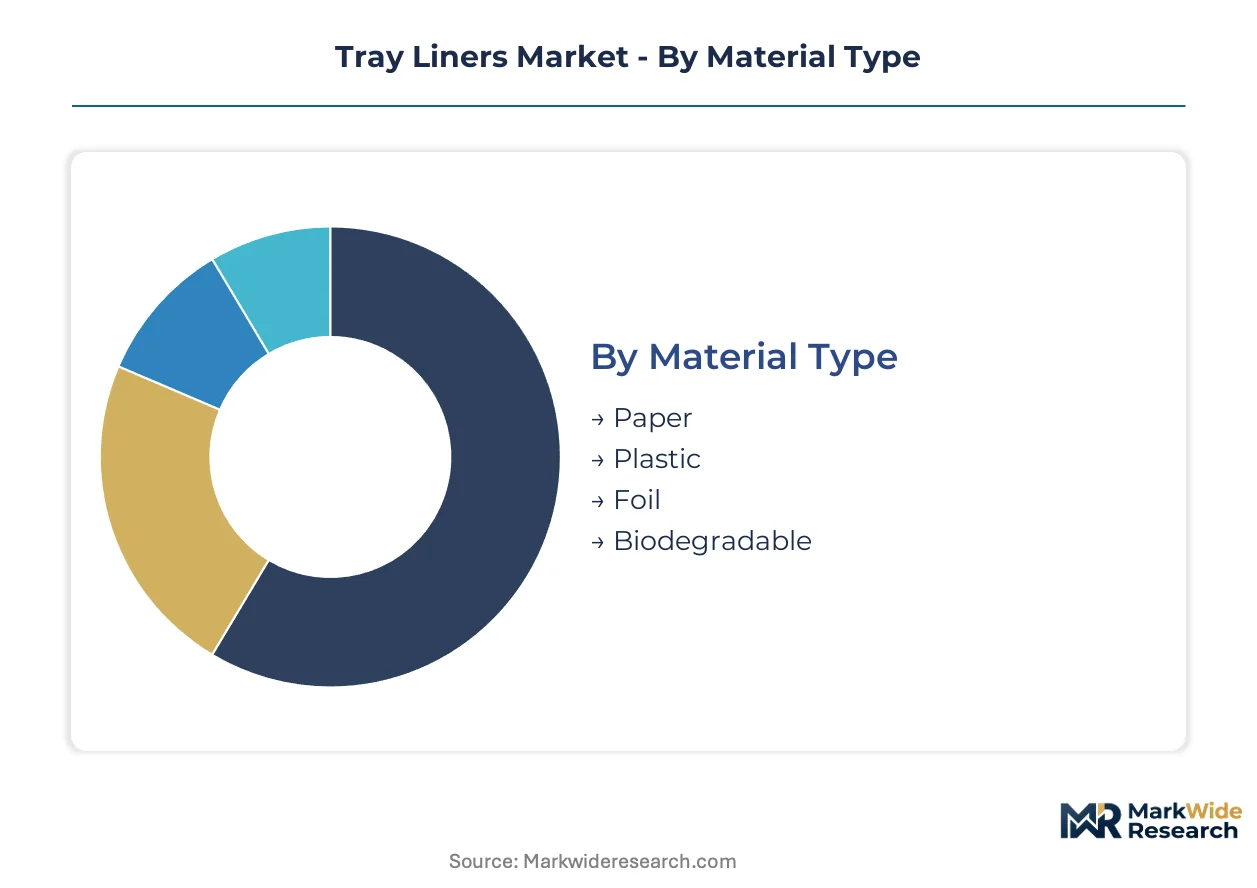
Tray liner procurement decisions pivot on material compliance, application durability, and distribution economics. Understanding how these dimensions intersect reveals where suppliers can defend margin and where substitution threats erode positioning.
Material Type:
Paper grades face the most acute substitution pressure as PFAS coating bans and plastic restriction laws force rapid formulation turnover across substrate categories.
- Paper:Bleached kraft and polyethylene-coated variants dominate quick-service restaurant specifications due to printability and cost position. Georgia-Pacific and Novolex are retooling coating lines to meet unified grease-resistance thresholds across multi-state franchise networks.
- Biodegradable:Certified compostable substrates from polylactic acid and bagasse blends are climbing the fastest as municipal composting mandates in California, New York, and Washington create qualified demand from institutional catering contracts.
- Plastic:Polypropylene and polyethylene liners retain footholds in healthcare and industrial segments where moisture barriers exceed paper capabilities, though state-level bans are compressing addressable market scope.
- Foil:Aluminum laminates anchor airline and heavy-duty industrial applications where thermal stability and puncture resistance justify premium positioning against paper alternatives.
Paper anchors the volume base while biodegradable grades gain share at the steepest rate.
Application:
Cost tier stratification separates commodity foodservice procurement from specification-driven industrial and catering contracts.
- Food Service:Quick-service restaurants and fast-casual chains drive the largest absolute volume, with grease-resistant paperboard specifications consolidating around national franchise master agreements that displace location-by-location purchasing.
- Catering:Event and institutional catering operators demand custom-printed formats with specialized cut dimensions, creating margin pools for suppliers with digital printing integration and rapid design-to-delivery cycles.
- Industrial:Manufacturing and logistics cafeterias prioritize heavy-duty specifications with extended durability requirements, often specifying foil laminates where spill containment and reuse cycles exceed standard foodservice thresholds.
- Retail:Grocery delis and prepared food counters represent fragmented demand with lower volume per account but higher SKU proliferation requirements.
Food service commands the volume base while catering applications expand most quickly through premium customization.
Thickness:
Customer type segmentation maps procurement authority structure, distinguishing centralized franchise specifications from decentralized independent operator purchasing.
- Standard:30-35 pound basis weight papers satisfy the majority of quick-service and fast-casual specifications, balancing grease absorption with material cost efficiency across high-volume tray touchpoints.
- Heavy-Duty:40-plus pound grades and foil laminates serve airline catering and industrial cafeterias where durability requirements exceed standard foodservice thresholds and justify premium positioning.
- Thin:Lightweight 20-25 pound specifications retain niche positioning in cost-constrained institutional settings with limited grease exposure and single-use disposal economics.
- Custom:Variable basis weights and specialized dimensions support branded hospitality and premium catering applications where differentiation justifies non-standard procurement minimums.
Standard thickness dominates volume while heavy-duty specifications capture the strongest margin expansion.
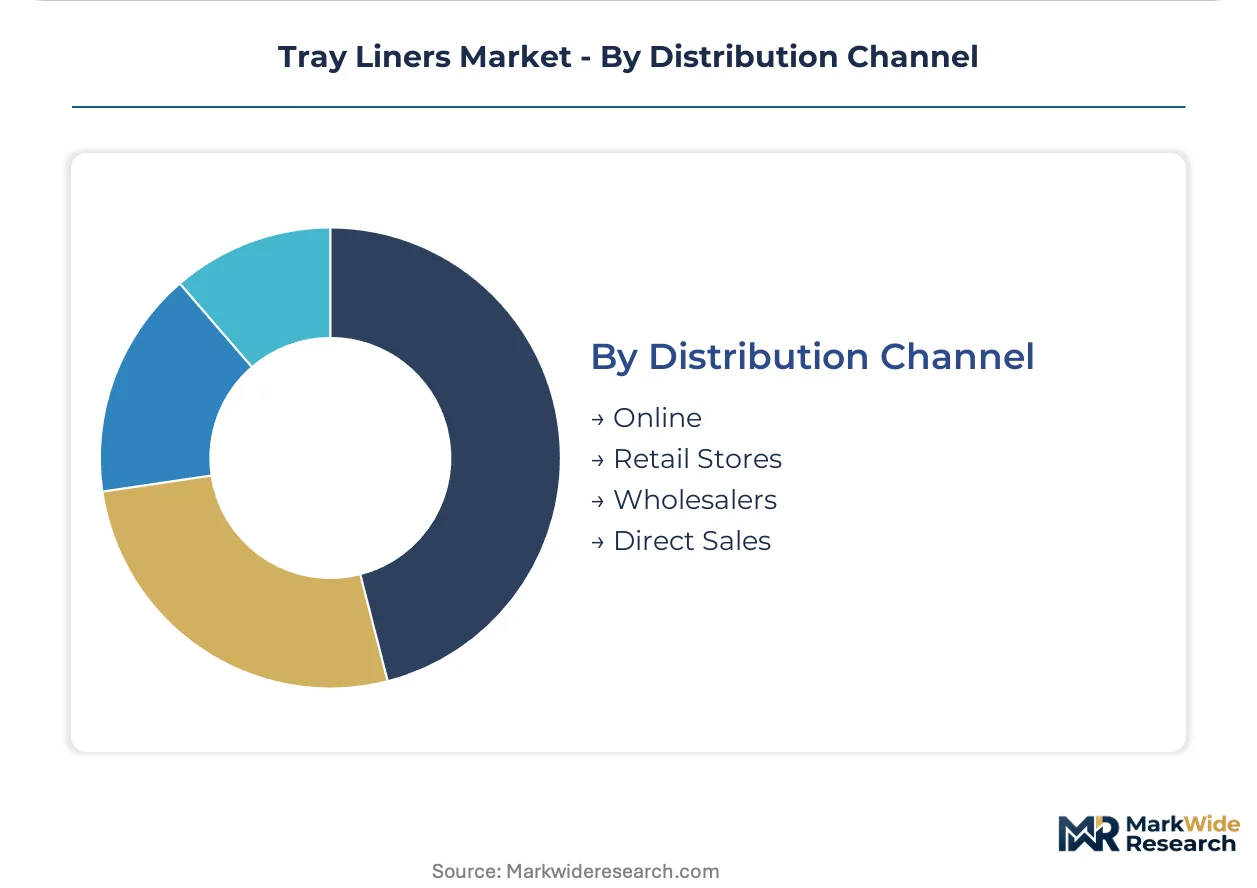
Distribution Channel:
Supply concentration patterns favor direct manufacturer relationships over intermediated distribution as franchise procurement centralizes.
- Direct Sales:National quick-service chains and multi-unit franchise operators are consolidating liner procurement through direct manufacturer agreements, bypassing regional distributors to secure unified specifications and volume pricing.
- Wholesalers:Broadline foodservice distributors retain relevance for independent restaurants and smaller chains lacking procurement scale to justify direct supplier relationships.
- Online:E-commerce platforms serve fragmented independent operators and specialty catering accounts with low minimum order quantities enabled by digital production technologies.
- Retail Stores:Cash-and-carry foodservice supply outlets capture emergency replenishment and small-format operators with immediate consumption requirements.
Direct sales channels concentrate volume while online platforms expand most rapidly through digital printing integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated pulp-to-converter operations cluster in the southeastern United States, where Georgia-Pacific and International Paper maintain captive fiber supply and coating capacity. This concentration shapes competitive cost positions across North American foodservice accounts.
United States
Quick-service restaurant chains drive tray liner specifications through consolidated franchise procurement, with California's SB 54 mandating post-consumer recycled content in food packaging. Georgia-Pacific operates integrated mills and converting facilities across Georgia and Alabama, supplying bleached kraft substrates to national restaurant networks.
Germany
Industrial catering and airline foodservice operators demand heavy-duty specifications that exceed standard foodservice thresholds. The EU Packaging and Packaging Waste Regulation shapes material compliance requirements for exporters. Converters in North Rhine-Westphalia specialize in foil-laminate formats for Lufthansa and institutional catering contracts.
China
Domestic quick-service expansion and export manufacturing capacity are climbing simultaneously. The country's national food safety regulator enforces GB standards for food-contact materials. Manufacturing clusters in the Yangtze River Delta produce polyethylene-coated papers for both domestic chains and North American private-label programs.
India
Institutional catering and quick-service penetration are expanding tray liner adoption beyond traditional hospitality. The Food Safety and Standards Authority of India regulates food-contact materials under packaging safety codes. Maharashtra-based converters supply printed formats to Mumbai's airline catering hubs and expanding quick-service networks.
Brazil
Quick-service franchise expansion and event catering are creating demand for both commodity and custom-printed formats. ANVISA oversees food-contact material safety for imported and domestically produced substrates. São Paulo state hosts the largest concentration of converting capacity serving Mercosur foodservice accounts.
Tray Liners Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated forest products companies with captive pulp supply anchor the cost-driven segment, while specialized converters with digital printing capabilities occupy the premium customization tier. Three archetypes define the field: integrated pulp-to-paperboard manufacturers, specialized foodservice converters with coating expertise, and diversified packaging conglomerates with multi-substrate portfolios. Capacity expansion and PFAS-compliant coating line retrofits represent the dominant competitive moves as suppliers respond to regulatory phaseout timelines.
Among integrated manufacturers, Georgia-Pacific LLC and International Paper Company exemplify the scale-driven archetype with backward integration into pulp supply. Hoffmaster Group, Inc. occupies a position within the specialized converter tier, representing the custom-format and digital-printing capability cluster. Novolex Holdings, Inc. sits within the diversified packaging conglomerate category, spanning multiple substrate technologies across regional distribution networks.
| Leading Market Players |
|---|
| Seaman Paper Company |
| Hoffmaster Group, Inc. |
| Georgia-Pacific LLC |
| Novolex Holdings, Inc. |
| International Paper Company |
| WestRock Company |
| Graphic Packaging International, LLC |
| Reynolds Consumer Products |
| Placon Corporation |
| Others |
Value Network & Pricing Analysis
Long-term master agreements between national quick-service chains and integrated manufacturers lock in both bleached kraft substrate access and grease-resistant coating price visibility across multi-year franchise procurement cycles. These contracts insulate volume buyers from Northern bleached softwood kraft pulp volatility while exposing regional converters to spot market swings.
Pricing Analysis
California's SB 54 mandates dictate the pricing tier structure across post-consumer recycled content thresholds. Three-tier pricing structure across premium certified compostable, standard PFAS-compliant paperboard, and economy polyethylene-coated grades separates quick-service specifications. Cost compression in standard grades is intensifying because Georgia-Pacific and Novolex are retooling coating lines to capture consolidated franchise volume. Independent restaurant operators show highest price sensitivity, while airline catering contracts demonstrate lowest sensitivity due to durability requirements.
Supply Chain Analysis
Inventory cycles stretching 60-90 days for imported coating chemicals create vulnerability windows during PFAS formulation transitions. Manufacturing concentrates in the United States, China, and Germany, with Georgia-Pacific operating integrated pulp-to-paperboard facilities across Georgia and Alabama. The supply chain draws from Northern bleached softwood kraft pulp, water-based barrier formulations, and bio-wax coatings. Single-source vulnerability sits with legacy fluorinated chemistry suppliers facing EPA TSCA Section 8(a)(7) disclosure requirements. Distribution runs through direct manufacturer relationships displacing regional wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tray liner demand tracks quick-service restaurant expansion cycles, with drive-thru format proliferation signaling recovery momentum after pandemic-era compression.
For Market Incumbents: Compound coating line retrofit investments to capture PFAS-compliant substrate share ahead of FDA notification cycle completions. Secure backward integration into water-based barrier chemical supply to defend margin position against specialty coating startups. Prioritize Georgia and Alabama capacity expansion to serve Southeast franchise consolidation. For New Entrants and Emerging Players: Differentiate on digital printing integration enabling hyper-local promotional messaging for regional franchise bidding. Target Ohio, Michigan, and Illinois quick-service chains where procurement remains fragmented across independent operators. Pursue USDA BioPreferred qualification to access federal school and military foodservice contracts. For Investors and Strategic Acquirers: Specialized converters with PFAS-compliant coating expertise and digital production assets present acquisition targets with technology differentiation. Long-term viability hinges on municipal composting mandate expansion accelerating certified biodegradable substrate adoption. Watch California, New York, and Washington enforcement timelines as inflection indicators for paper-based substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Compliant Coating Line Retrofit | EPA TSCA Section 8(a)(7) disclosure requirements eliminate legacy fluorinated chemistries from food-contact specifications. |
| Digital Printing Integration | Variable-data inkjet systems collapse minimum order quantities for regional franchise hyper-local promotional campaigns. |
| USDA BioPreferred Certification | Federal procurement preferences unlock qualified supplier status in school and military foodservice channels. |
| Backward Integration into Barrier Chemistry | In-house water-based and bio-wax formulation control reduces coating cost volatility and secures supply continuity. |
| Midwest Manufacturing Footprint Expansion | Underpenetrated Ohio, Michigan, and Illinois quick-service chains present volume consolidation targets for integrated suppliers. |
Research Methodology
Cross-validation between franchise procurement executives and coating line operators anchors the qualitative findings in operational reality. Primary interviews with quick-service chain purchasing directors, paperboard mill technical managers, foodservice distribution channel heads, and regulatory compliance officers combined with secondary validation against FDA 21 CFR filings, EPA TSCA disclosure databases, state-level plastic ban legislation, and SEC 10-K supply chain disclosures. Bottom-up and top-down triangulation reconciles converter capacity estimates with franchise location expansion data.
Sensitivity analysis across pulp price volatility scenarios and PFAS phaseout timelines tests projection robustness. The analytical framework models material type, application durability tier, thickness specification, and distribution channel segmentation across the projection horizon. CAGRs derive from franchise unit count expansion rates, municipal composting mandate adoption curves, and coating chemistry substitution elasticities. Quick-service drive-thru format multiplication and state-level recycled content mandates serve as key forecast inputs.
Material uncertainties — pulp cost swings, PFAS remediation timeline delays, and municipal composting infrastructure buildout gaps — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and franchise procurement centralization velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Barrier Packaging Market
Packaging Barrier Films
Pan Liners Market
Packaging Barrier Films
Water Resistant Packaging Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Specialty Films Market
Packaging Barrier Films
High Barrier Lidding Film Market
Packaging Barrier Films
Hygiene Packaging Films Market
Packaging Barrier Films
Waterproof Packaging Market
Packaging Barrier Films
Copper Coated Films Market
Packaging Barrier Films
Europe Barrier Films Market
Packaging Barrier Films
Barrier Bags Market
Packaging Barrier Films
Barrier Materials Market
Packaging Barrier Films
Cling Films Market
Packaging Barrier Films
Global Medical Packaging Films Market
Packaging Barrier Films
Dual Ovenable Lidding Films Market
Packaging Barrier Films
Heat Seal Coating Market