
 Middle East and Africa Airless Packaging Market | 2026-2036
Middle East and Africa Airless Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Airless Packaging Market Foresight
Asset-light leasing models for injection-molding equipment is reconfiguring competitive entry barriers across the Middle East and Africa airless packaging landscape. AptarGroup, Inc. leverages its pump technology leadership to anchor premium cosmetic contracts in the Gulf Cooperation Council states. HCP Packaging sustains manufacturing scale advantages through integrated toolmaking capabilities that serve multinational beauty brands. Quadpack Industries differentiates via design-led glass and plastic hybrid solutions targeting niche pharmaceutical applications.
Airless packaging in the Middle East and Africa comprises sealed dispensing systems that evacuate product through piston or bag-on-valve mechanisms without air intake, typically achieving oxygen exclusion below 0.5% residual headspace to preserve sensitive formulations. These systems employ multi-layer coextruded plastics or borosilicate glass with elastomeric seals to prevent oxidation and microbial contamination across extended shelf lives. Vacuum technology leads installed capacity due to its proven reliability in high-viscosity cosmetic creams, while compression technology represents the fastest-expanding segment as pharmaceutical manufacturers adopt precise dose-control pumps for topical drug delivery. Plastic dominates material consumption given its cost efficiency and decoration flexibility, though glass commands concentrated margin pools in prestige fragrance and dermocosmetic channels.
South Africa's National Regulator for Compulsory Specifications and the Saudi Food and Drug Authority enforce polymer migration limits and barrier-performance standards that shape material selection and testing protocols across regional supply chains. The UAE's Emirates Authority for Standardization and Metrology mandates recyclability disclosures that accelerate mono-material pump development. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between localized compounding investments or imported resin partnerships.
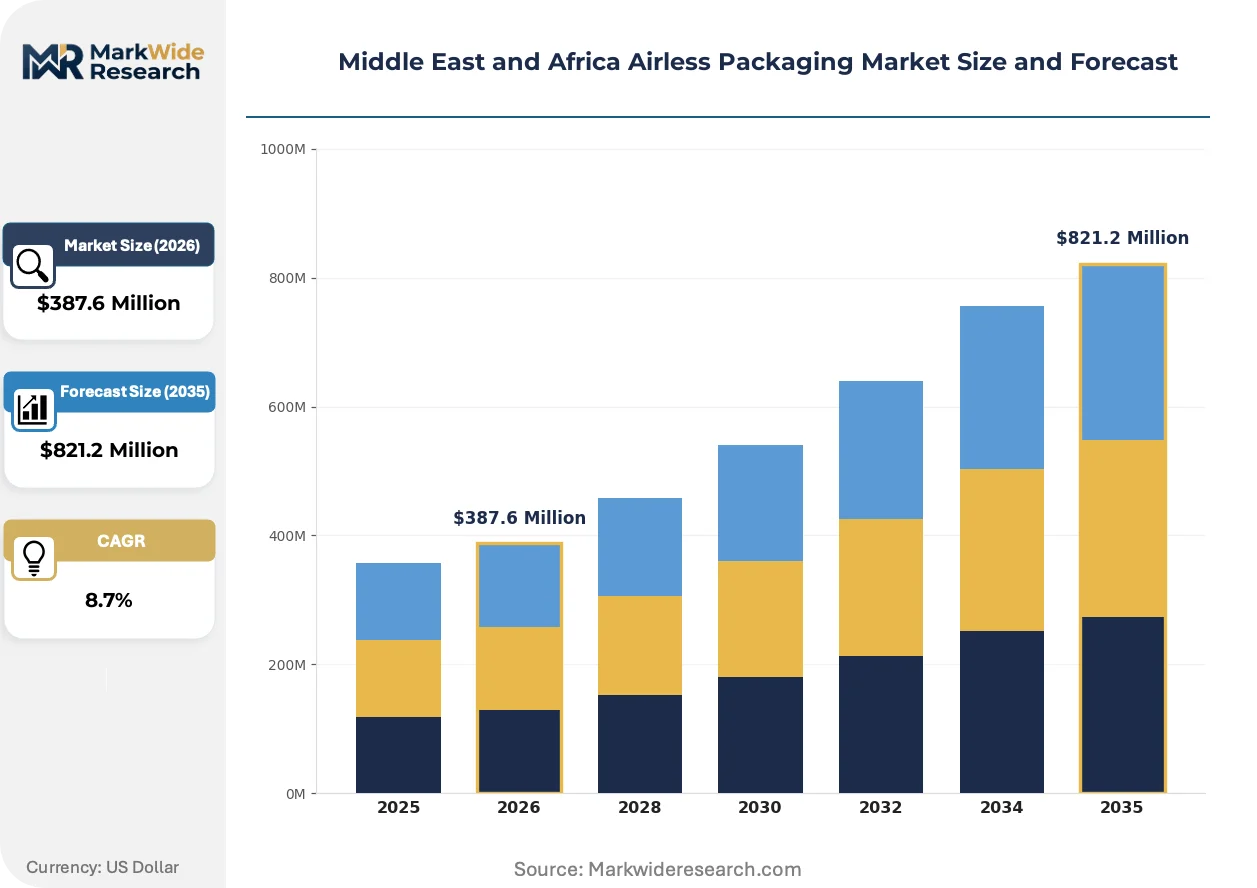
Market Dynamics
Asset-light leasing models for injection-molding equipment are reconfiguring competitive entry barriers across the Middle East and Africa airless packaging landscape, enabling mid-tier converters to scale capacity without balance-sheet strain.
Growth Catalysts
- UAE Emirates Authority for Standardization and Metrology recyclability mandates:These disclosure requirements accelerate mono-material pump development and reward early compliance with preferential shelf placement in Dubai's retail clusters.
- Pharmaceutical dose-precision requirements:Topical drug manufacturers across Saudi Arabia are specifying compression-technology pumps to meet SFDA stability guidelines for sensitive formulations.
- South Africa's polymer safety enforcement:The National Regulator for Compulsory Specifications elevates barrier-performance standards that filter out low-grade imports and strengthen domestic converter margins.
Market Restraints
- Specialty resin import dependency:Multi-layer coextruded barrier films rely on European and Asian resin supply, exposing converters to freight cost volatility and currency mismatch risks.
- Technical limitation in high-temperature sterilization:Plastic airless systems face performance degradation above 121°C, restricting penetration into sterile pharmaceutical segments where glass maintains dominance.
- Saudi Food and Drug Authority polymer migration testing protocols:Extended approval timelines for new material formulations delay product launches by 8-14 months versus Gulf Cooperation Council neighbors.
Strategic Opportunities
- Egypt's underpenetrated dermocosmetic channel:Cairo's expanding middle-class consumption and limited local airless converter presence create first-mover advantages for integrated toolmakers.
- Bag-on-valve technology convergence with connected dispensing:Smart pumps integrating dose-counters and NFC authentication are capturing pharmaceutical contracts in the UAE's free-zone manufacturing hubs.
- South African extended producer responsibility frameworks:Pending regulations will mandate post-consumer collection infrastructure, rewarding converters with backward integration into recycling operations.
Industry Challenges
- Toolmaking skill scarcity:Precision mold design for piston-based airless systems requires capabilities concentrated in European and East Asian technical institutes, constraining regional talent pipelines.
- Legacy equipment integration friction:Converters retrofitting conventional injection lines for multi-shot molding face downtime costs and yield degradation during changeover periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Airless Packaging Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray Bottles, Pumps, Jars, Tubes Material: Plastic, Glass, Metal, Paper End User: Cosmetics, Pharmaceuticals, Food & Beverages, Household Technology: Compression Technology, Vacuum Technology, Aerosol Technology, Others |
| Companies Covered | HCP Packaging, Quadpack Industries, AptarGroup, Inc., Gerresheimer, Lumson, Silgan Dispensing Systems, Berry Global, APC Packaging, Albea Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Airless Packaging Market Shifts & Advancements
Material science advances and regulatory disclosure mandates are compressing development cycles across the Middle East and Africa airless packaging value chain, forcing simultaneous innovation in barrier performance and end-of-life design.
Glass-plastic hybrid construction is hybridizing aesthetic and functional properties for prestige cosmetic applications. Borosilicate glass bodies paired with polymer pump mechanisms deliver oxygen exclusion below 0.5% residual headspace while enabling decoration flexibility. Dubai-based beauty brands are specifying these formats for serum and eye-care lines, compressing pure-glass lead times and expanding addressable volume for converters with dual-material capabilities.
South Africa's National Regulator for Compulsory Specifications and Saudi Arabia's SFDA are tightening polymer migration limits in parallel, creating a regional compliance convergence. Industrial consequence includes accelerated substitution of polycarbonate with cyclic olefin copolymer in pump cylinder applications. Pharmaceutical manufacturers in Riyadh and Johannesburg are responding with joint material qualification programs to amortize testing costs across both jurisdictions.
Direct procurement relationships between multinational beauty brands and regional converters are displacing traditional distributor intermediaries in the UAE. Dubai's retail cluster concentration enables volume aggregation that justifies dedicated production lines and technical service co-location. This pattern is most visible in prestige skincare, where Sephora and regional duty-free operators are mandating supplier transparency and compressed lead times that distributor networks cannot match.
Middle East and Africa Airless Packaging Market Segmentation
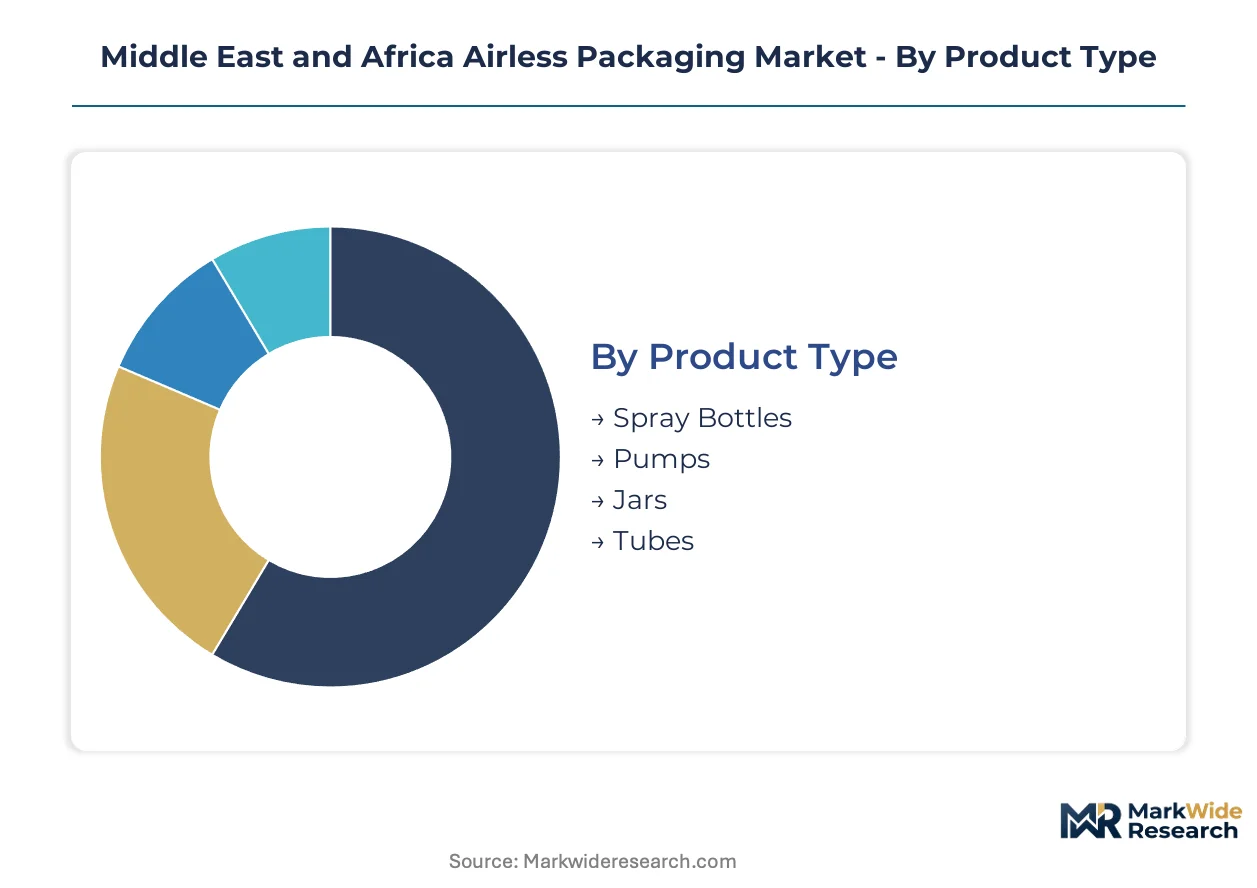
Segmentation reveals how airless packaging demand fragments across distinct performance requirements and regulatory tolerances in the Middle East and Africa. Each dimension—product format, material substrate, end-use application, and evacuation mechanism—carries divergent margin profiles and compliance burdens that reshape converter investment priorities.
Product Type:
Mature formats dominate procurement volumes in Dubai's beauty retail cluster, while emerging configurations gain traction in pharmaceutical compliance environments.
- Pumps:These precision-machined dispensers combine piston mechanisms with elastomeric seals to achieve sub-0.5% residual headspace. Demand concentrates in the UAE's prestige skincare segment, where Dubai-based duty-free operators mandate supplier transparency and compressed lead times that favor dedicated production lines.
- Jars:Wide-mouth containers with integrated airless closures accommodate high-viscosity creams and balms. South African cosmetics brands are expanding procurement for premium skincare lines, though the National Regulator for Compulsory Specifications enforces polymer safety standards that elevate barrier-performance testing costs.
- Spray Bottles:Fine-mist atomizers for liquid formulations serve fragrance and toner applications across Saudi Arabia's retail channels.
- Tubes:Flexible laminated structures with airless pump attachments target travel-size and sample formats in Egypt's emerging dermocosmetic channel.
Pumps retain volume leadership; tubes hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity substrates from performance-engineered alternatives, with margin concentration shifting toward compliance-certified grades.
- Plastic:Multi-layer coextruded polymers and cyclic olefin copolymers deliver cost efficiency and decoration flexibility. Demand concentrates across mass-market cosmetics in South Africa, though converters face import dependency for specialty barrier resins sourced from European and Asian suppliers.
- Glass:Borosilicate bodies paired with polymer pump mechanisms achieve oxygen exclusion below 0.5% residual headspace. Dubai-based beauty brands specify these hybrids for serum and eye-care lines, compressing pure-glass lead times while expanding addressable volume for dual-material converters.
- Metal:Aluminum collapsible tubes and aerosol cans serve pharmaceutical and household segments with high-barrier requirements.
- Paper:Fiber-based outer shells with plastic inner liners target sustainability-positioned brands responding to UAE recyclability mandates.
Plastic commands absolute volume; glass captures concentrated margin pools.
End User:
Application-driven specifications diverge sharply between aesthetic performance priorities and clinical stability requirements.
- Cosmetics:Premium skincare and fragrance brands across the Gulf Cooperation Council states specify airless systems for oxidation-sensitive actives. Dubai's retail cluster concentration enables direct procurement relationships that displace traditional distributor intermediaries.
- Pharmaceuticals:Topical drug manufacturers in Saudi Arabia specify compression-technology pumps to meet SFDA stability guidelines for sensitive formulations, with dose-precision requirements accelerating smart pump adoption.
- Food & Beverages:High-viscosity sauces and condiments deploy bag-on-valve systems for extended shelf-life preservation in South African retail channels.
- Household:Cleaning and personal care products utilize cost-optimized vacuum technology for chemical compatibility and dispensing reliability.
Cosmetics anchors procurement volume; pharmaceuticals is expanding most quickly.
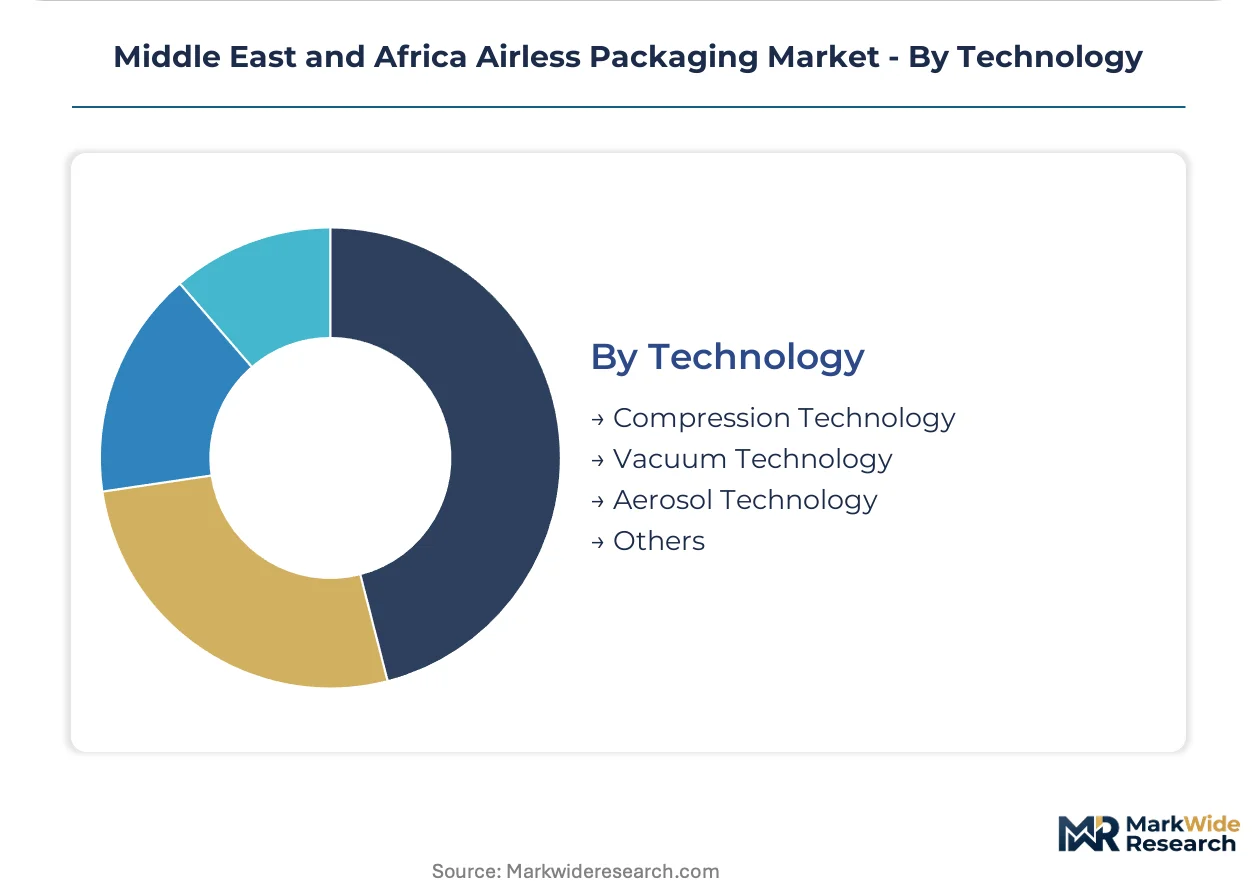
Technology:
Evacuation mechanism selection hinges on viscosity tolerance, dose precision, and sterilization compatibility across end-use environments.
- Vacuum Technology:Piston-based systems evacuate product through upward displacement without air intake. Proven reliability in high-viscosity cosmetic creams makes this the dominant installed base across UAE and South African converter operations.
- Compression Technology:Mechanical pump mechanisms enable precise dose control for topical drug delivery. Pharmaceutical manufacturers in Riyadh and Johannesburg are adopting these systems fastest to meet parallel tightening of polymer migration limits by Saudi SFDA and South Africa's National Regulator for Compulsory Specifications.
- Aerosol Technology:Propellant-driven bag-on-valve systems serve household and food applications with continuous spray requirements.
- Others:Emerging connected dispensing platforms integrating NFC authentication and dose-counters capture pharmaceutical contracts in UAE free-zone manufacturing hubs.
Vacuum technology leads installed capacity; compression technology gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility frameworks and polymer migration standards are redirecting converter investment across the Middle East and Africa toward localized compounding and recyclability-certified production lines.
United Arab Emirates
Dubai's beauty retail cluster drives concentrated procurement of high-end pump and jar formats for prestige skincare lines. The Emirates Authority for Standardization and Metrology mandates recyclability disclosures that accelerate mono-material pump development. Jebel Ali free-zone manufacturing hubs host pharmaceutical contract manufacturers specifying smart pumps with NFC authentication.
Saudi Arabia
Topical drug manufacturers in Riyadh specify compression-technology pumps to meet Saudi Food and Drug Authority stability guidelines for sensitive formulations. The SFDA enforces polymer migration testing protocols that extend approval timelines for new material formulations. King Abdullah Economic City's industrial zones attract converters seeking proximity to pharmaceutical packaging demand.
South Africa
Cosmetics brands expand airless packaging procurement for premium skincare lines targeting middle-class consumption growth. The National Regulator for Compulsory Specifications enforces polymer safety standards that elevate barrier-performance requirements and filter out low-grade imports. Gauteng province concentrates converter operations serving multinational beauty brand direct procurement relationships.
Egypt
Cairo's expanding dermocosmetic channel creates first-mover advantages for integrated toolmakers with airless converter capabilities. The country's national standards body aligns with regional polymer migration limits under harmonization programs. Alexandria's industrial corridor hosts emerging packaging operations targeting North African beauty brand supply chains.
Middle East and Africa Airless Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions defined by technology access and regulatory certification depth. The vendor base organizes around three strategic archetypes: integrated multinationals with Gulf Cooperation Council anchor contracts, regional specialists with toolmaking capabilities, and design-led hybrid material innovators. Dominant competitive moves include backward integration into polymer compounding operations and strategic partnerships with Dubai-based retail operators for dedicated production line allocation.
Among pump technology specialists, AptarGroup, Inc. and Silgan Dispensing Systems occupy positions exemplifying precision-dispersion engineering for pharmaceutical compliance environments. HCP Packaging represents the integrated toolmaking archetype with manufacturing scale advantages, while Quadpack Industries exemplifies design-led differentiation through glass-plastic hybrid solutions. Gerresheimer anchors the glass-dominant premium tier serving dermocosmetic channels with borosilicate barrier performance.
| Leading Market Players |
|---|
| HCP Packaging |
| Quadpack Industries |
| AptarGroup, Inc. |
| Gerresheimer |
| Lumson |
| Silgan Dispensing Systems |
| Berry Global |
| APC Packaging |
| Albea Group |
| Others |
Supply & Pricing Matrix
European specialty resin suppliers anchor upstream concentration for multi-layer coextruded barrier films, feeding margin pools downstream to Gulf Cooperation Council converters with SFDA-certified compounding capabilities.
Pricing Analysis
Certification level (SFDA-grade versus non-regulated) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with volume scale and customization depth as secondary differentiation factors. Pricing pressure stems from freight cost volatility on European resin imports, compressing margins for non-certified converters. Mass-market cosmetics brands in South Africa exhibit highest price sensitivity, while Dubai-based prestige skincare houses absorb premium tiers without volume negotiation.
Supply Chain Analysis
Tariff exposure between European resin exporters and Middle Eastern converters dominates supply chain risk assessment for regional airless packaging operations. Germany, Italy, and South Korea concentrate specialty polymer supply, with cyclic olefin copolymer and multi-layer barrier films as critical inputs. Single-source vulnerability persists for pharmaceutical-grade elastomeric seals. Distribution runs through Jebel Ali free-zone warehousing clusters serving UAE pharmaceutical contract manufacturers and Saudi topical drug producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa airless packaging market is emerging from a cyclical trough driven by post-pandemic normalization of beauty retail foot traffic in Dubai's duty-free corridors.
For Market Incumbents: Pre-empt Egyptian dermocosmetic channel capture by integrated toolmakers through dedicated Cairo technical service presence. Anchor Gulf Cooperation Council market share via backward integration into polymer compounding operations that meet parallel SFDA and South African National Regulator standards. Defend against design-led hybrid specialists by accelerating mono-material pump certification under Emirates Authority for Standardization and Metrology recyclability mandates. For New Entrants and Emerging Players: Egypt's underpenetrated dermocosmetic channel represents the most penetrable entry point for converters with integrated toolmaking capabilities. Cairo's expanding middle-class consumption and limited local airless converter presence reward first-movers with 12-18 month contract windows. Lead with bag-on-valve technology convergence for connected dispensing platforms targeting UAE free-zone pharmaceutical manufacturing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European pump technology specialists seeking Gulf Cooperation Council geographic expansion. Long-term viability hinges on regulatory certification depth across multiple Middle East and Africa jurisdictions rather than single-country market share. Monitor SFDA polymer migration testing protocol harmonization with South African standards as the inflection signal for cross-regional platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Pump Development | Emirates Authority for Standardization and Metrology recyclability mandates reward early compliance with preferential Dubai retail shelf placement. |
| Backward Integration into Polymer Compounding | SFDA and South African National Regulator convergence on migration limits favors converters with captive resin formulation capabilities. |
| Smart Pump Integration with NFC Authentication | UAE free-zone pharmaceutical manufacturers specify dose-counters and authentication for topical drug contract manufacturing. |
| Integrated Toolmaking Capability Expansion | Cairo's dermocosmetic channel growth rewards converters with in-house precision mold design reducing European technical institute dependency. |
| Glass-Plastic Hybrid Production Line Allocation | Dubai-based prestige beauty brands specify borosilicate-polymer hybrids for serum applications compressing pure-glass lead times. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry association reports. Primary interviews engaged packaging procurement managers at multinational beauty brands, technical directors at regional converters, regulatory affairs leads at Saudi Food and Drug Authority, and supply chain planners at Jebel Ali free-zone operators. Secondary validation drew from Emirates Authority for Standardization and Metrology disclosure databases, South African National Regulator for Compulsory Specifications technical bulletins, and European resin supplier customs records. Bottom-up volume aggregation across product format, material substrate, and end-use application triangulates against top-down market sizing.
Forecast inputs incorporate evacuation mechanism adoption curves, polymer migration standard harmonization timelines, and extended producer responsibility framework implementation schedules. Segmentation dimensions span product type, material, end user, and technology across the analysis window. CAGRs derive from regression analysis of historical procurement volumes against regulatory milestone dates and retail cluster expansion patterns. Pharmaceutical dose-precision requirements and connected dispensing platform penetration serve as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in Gulf Cooperation Council beauty retail foot traffic, South African rand volatility against euro-denominated resin contracts, or Egyptian foreign exchange availability would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation pacing and polymer substitution elasticities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Thailand Plastic Packaging Films Market
Packaging Barrier Films
Perforated Packaging Market
Packaging Barrier Films
Heat Seal Coating Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Clear Barrier Films Market
Packaging Barrier Films
Polyethylene Vapor Barrier Films for Under Slab Market
Packaging Barrier Films
Frisket Masking Film Market
Packaging Barrier Films
Barrier Coated Carton Market
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Anti-Static Packaging Film Market
Packaging Barrier Films
Protective Films Market
Packaging Barrier Films
Sealant Films Market
Packaging Barrier Films
PET Release Liner Market
Packaging Barrier Films
Sterile Barrier Packaging Market
Packaging Barrier Films
Global Peelable Lidding Films Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market