
 Multi-Layer Blown Films Market | 2026-2036
Multi-Layer Blown Films Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Layer Blown Films Market Outlook
Polyethylene is pivoting toward post-consumer recycled grades as brand owners face Extended Producer Responsibility mandates. Berry Global Inc. leverages its North American recycling infrastructure to supply certified circular content. Amcor plc anchors European flexible packaging contracts through proprietary barrier coating technologies. DuPont de Nemours, Inc. differentiates via high-performance nylon barrier layers for pharmaceutical serialization requirements.
Multi-layer blown films are coextruded tubular structures combining two or more polymer layers, typically engineered with oxygen transmission rates below 0.5 cc/m²/day for sensitive product protection. These films serve primarily to extend shelf life and reduce material usage versus monolayer alternatives. Polyethylene formulations occupy the largest volume position due to cost scalability across food and beverage packaging. Nylon barrier layers represent the fastest-growing specification as pharmaceutical cold-chain requirements intensify. Thickness segments above 150 microns command premium positioning in industrial bulk containment where puncture resistance determines specification.
The EU Packaging and Packaging Waste Regulation and FDA food contact notification requirements are reshaping material approval pathways and recyclability certification demands. REACH compliance for adhesive tie layers adds formulation complexity and extends qualification timelines for new product introductions. ISO 9001 and BRCGS packaging standards govern supplier qualification for multinational food brands, filtering market access toward integrated film converters. Stakeholders must monitor polymer recycling infrastructure investments and chemical recycling partnerships to secure feedstock positions before regulatory thresholds tighten.
Market Dynamics
Coextrusion technology advancement is compressing barrier layer thicknesses while maintaining oxygen transmission performance, forcing converters to retool lines or cede specification control to integrated film producers.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates are accelerating demand for compatible multi-layer structures that maintain barrier performance without compromising mechanical recycling streams.
- E-commerce grocery channels:Cold-chain fulfillment requirements are pulling high-barrier films into fresh produce and protein packaging applications previously served by simpler formats.
- Nylon barrier specifications:Pharmaceutical serialization and temperature-sensitive biologics are expanding oxygen barrier requirements into medical-grade film segments.
Market Restraints
- Ethylene feedstock volatility:Crude-linked polyethylene resin costs create margin compression for non-integrated converters without captive monomer supply.
- Adhesive tie-layer REACH compliance:ECHA substance evaluation timelines extend new product qualification cycles by 12-18 months.
- Mechanical recycling incompatibility:Current municipal sorting infrastructure cannot separate multi-layer films, limiting post-consumer feedstock access for circular content claims.
Strategic Opportunities
- Chemical recycling partnerships:Pyrolysis and depolymerization investments by petrochemical majors are creating feedstock pathways for certified circular multi-layer films.
- Industrial bulk containment:Films above 150 microns for agricultural chemicals and construction materials remain underpenetrated by coextrusion specialists.
- ISO 9001 and BRCGS certification:Multinational food brands are consolidating supplier bases toward dual-certified converters with integrated laboratory capabilities.
Industry Challenges
- Coextrusion die engineering expertise:The talent pool for multilayer distribution manifold design remains concentrated among a handful of equipment OEM technical specialists.
- Barrier coating integration:Converters face capex intensity for vacuum deposition or plasma coating lines required to match Amcor's proprietary barrier technologies.
- Adhesive tie-layer formulation IP:Licensing complexity around maleic anhydride grafted polyethylene adhesives creates supply concentration with specialty chemical suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Layer Blown Films Market |
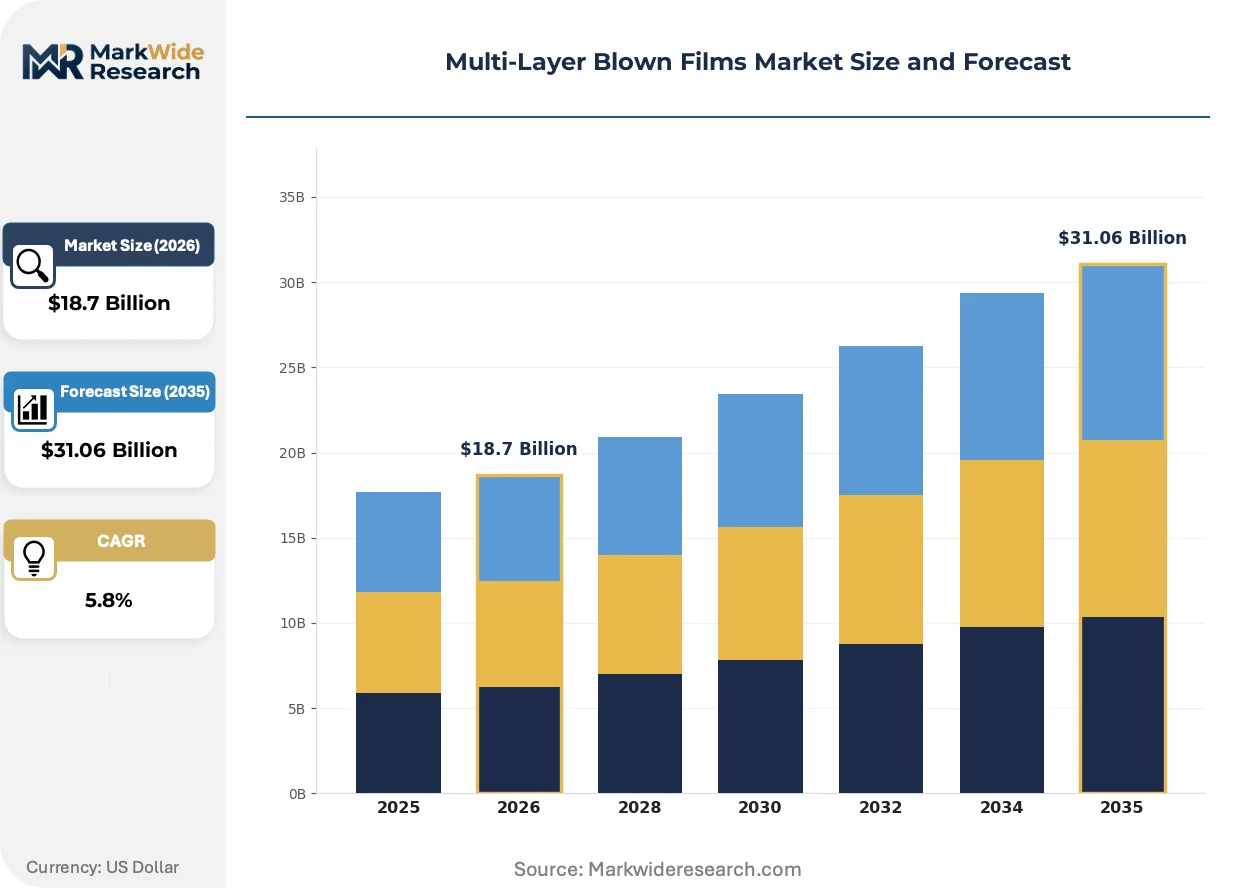
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Nylon, PVC Application: Packaging, Agriculture, Industrial, Construction End User: Food & Beverage, Consumer Goods, Pharmaceutical, Electronics Thickness: Below 50 Microns, 51-100 Microns, 101-150 Microns, Above 150 Microns |
| Companies Covered | Mitsubishi Chemical Group, Winpak Ltd, Berry Global Inc., Coveris Holdings S.A., RKW Group, Amcor plc, Sigma Plastics Group, DuPont de Nemours, Inc., Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Layer Blown Films Market Strategic Shifts
Digital process control and inline spectroscopy are reshaping how coextrusion lines manage layer thickness uniformity, compressing defect rates and enabling thinner overall structures without sacrificing barrier performance.
Machine vision inspection integrated with adaptive die control is automating real-time gauge profile correction across seven-layer and nine-layer blown film lines. Pharmaceutical contract packagers in Germany and Switzerland are adopting these systems fastest, driven by serialization traceability requirements. The technology is automating quality documentation that previously required manual sampling and offline laboratory verification.
REACH authorization requirements for phthalate-based plasticizers in food contact applications are forcing reformulation of adhesive tie layers and slip additives. ECHA's 2024 restriction proposals targeting certain polyolefin additives are extending qualification timelines for new multi-layer structures. Flexible packaging converters in the Netherlands and Belgium are responding by accelerating partnerships with additive suppliers holding early-stage regulatory dossiers.
Brand owner specification consolidation is compressing the approved supplier base toward integrated film converters with captive recycling infrastructure. Unilever and Nestlé procurement teams in France and Germany are shifting from spot purchasing to multi-year supply agreements tied to certified recycled content targets. This pattern is most visible in Central European dairy and ready-meal packaging categories where EPR fee structures now penalize non-circular formats.
Multi-Layer Blown Films Market Segmentation
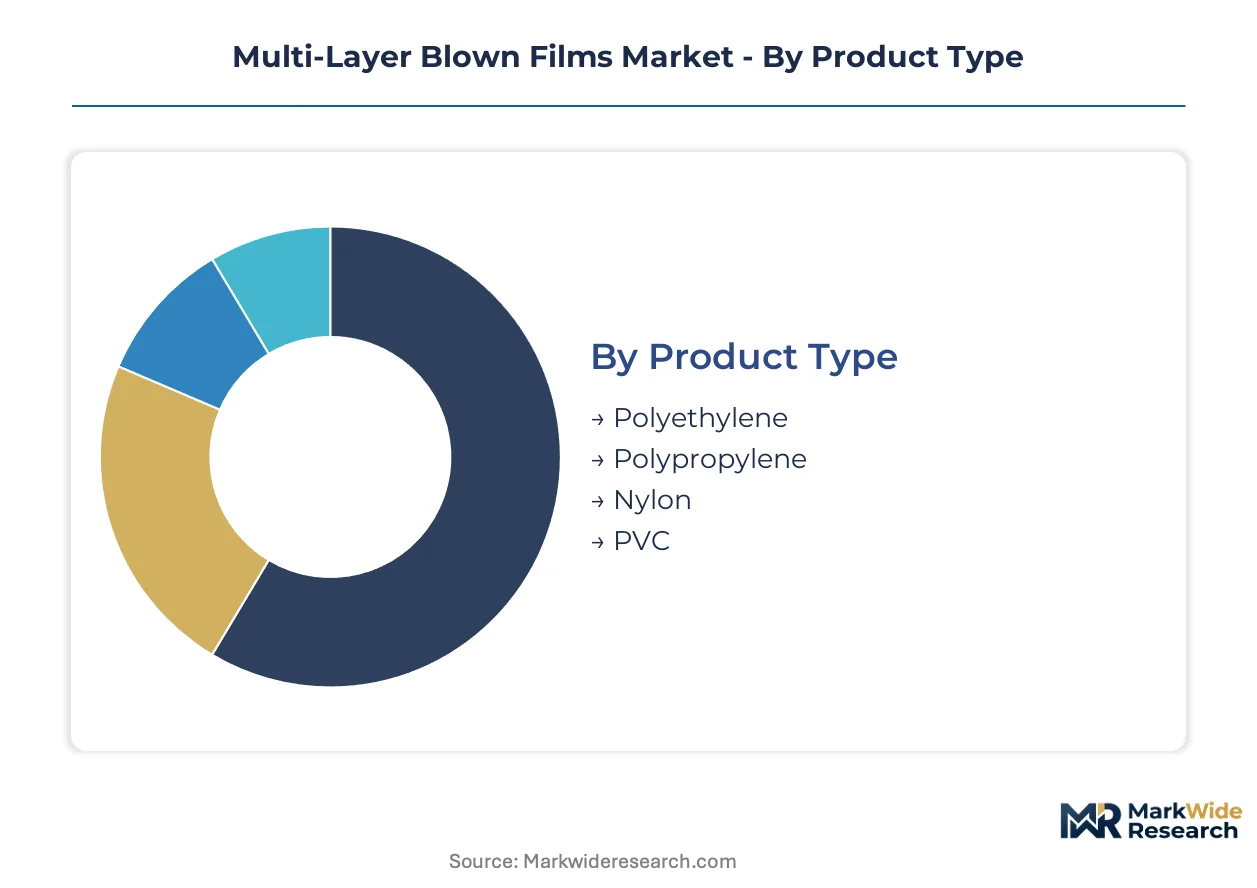
Multi-layer blown films serve heterogeneous buyers with divergent barrier requirements, mechanical specifications, and regulatory obligations. Segmentation reveals where formulation complexity commands premium pricing versus where commodity polyethylene grades dominate procurement decisions.
Product Type:
Buyers differentiate primarily by oxygen transmission specifications and cold-chain performance thresholds.
- Polyethylene:Linear low-density and metallocene grades form the backbone of food packaging structures, prized for heat-seal consistency and cost scalability across high-volume dairy and bakery applications. Demand concentrates in Germany and France where EPR mandates are accelerating post-consumer recycled content specifications for retail-ready formats.
- Nylon:Polyamide barrier layers deliver sub-0.5 cc/m²/day oxygen transmission rates essential for pharmaceutical serialization and protein shelf-life extension. Swiss and German pharmaceutical contract packagers are specifying nylon-rich structures for temperature-sensitive biologics distribution.
- Polypropylene:Offers elevated temperature resistance for retort and hot-fill applications with clarity advantages over polyethylene in premium consumer goods presentation.
- PVC:Retains niche positioning in medical device overwrap and specific industrial containment where legacy qualification protocols resist material substitution.
Polyethylene leads volumes today; nylon is gaining share fastest.
Application:
Volume concentration follows end-use durability requirements and barrier complexity gradients.
- Packaging:Food and beverage formats account for the dominant consumption share, with e-commerce grocery channels pulling high-barrier specifications into fresh produce segments previously served by monolayer alternatives. Cold-chain fulfillment requirements in the Netherlands and Belgium are accelerating seven-layer and nine-layer adoption.
- Industrial:Agricultural chemicals and construction material containment above 150 microns remain underpenetrated by coextrusion specialists, offering margin expansion for converters with heavy-gauge line capabilities.
- Agriculture:Greenhouse films and silage wrap demand UV-stabilized polyethylene structures with multi-season durability specifications.
- Construction:Vapor barrier and temporary enclosure applications prioritize puncture resistance and weathering performance over oxygen barrier precision.
Packaging commands the greatest revenue concentration; industrial applications show the steepest expansion trajectory.
End User:
Regulatory intensity and traceability requirements segment buyers by qualification burden and contract duration.
- Food & Beverage:Multinational brand owners in France and Germany are consolidating supplier bases toward dual ISO 9001 and BRCGS certified converters with integrated laboratory capabilities and captive recycling infrastructure.
- Pharmaceutical:Serialization mandates and EMA cold-chain guidelines are driving specification toward nylon-enhanced structures with documentary traceability for temperature excursion monitoring.
- Consumer Goods:Personal care and household product packagers balance barrier performance with shelf aesthetics, favoring polypropylene clarity in premium positioning.
- Electronics:Static-dissipative and moisture-barrier specifications serve semiconductor and component shipping requirements with cleanroom-compatible packaging protocols.
Food and beverage anchors procurement volumes; pharmaceutical specifications are climbing the fastest.
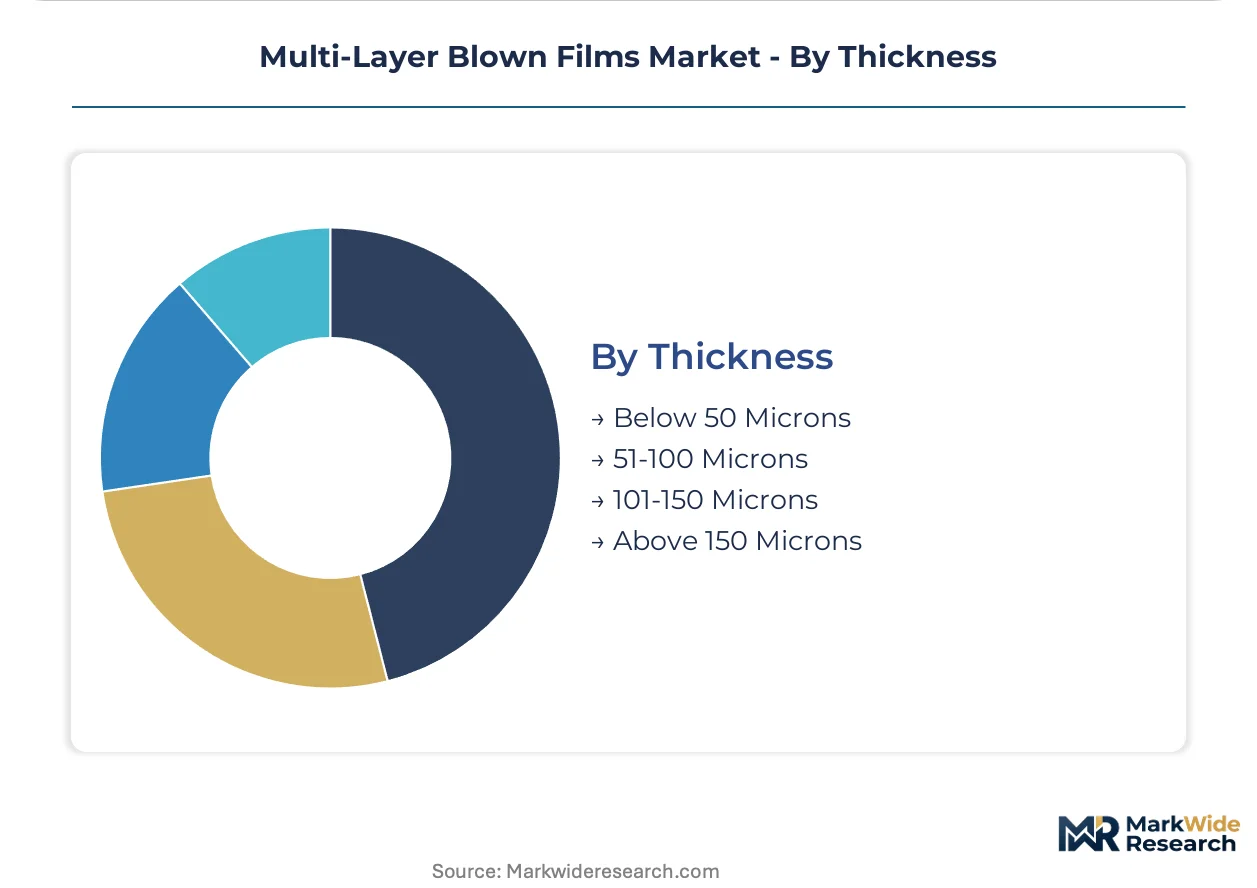
Thickness:
Mechanical performance thresholds and puncture resistance requirements stratify buyers by application severity.
- Above 150 Microns:Heavy-gauge structures command premium positioning in industrial bulk containment where puncture resistance determines specification acceptance. Agricultural chemical and construction material applications in Germany favor these grades for mechanical durability under load.
- Below 50 Microns:Ultra-thin formats serve lightweight food service and overwrap applications where material minimization reduces EPR fee exposure. REACH compliance for adhesive tie layers complicates qualification cycles for these delicate structures.
- 51-100 Microns:Mid-range specifications balance cost and performance across standard food packaging formats with moderate barrier requirements.
- 101-150 Microns:Thicker standard grades serve frozen food and modified atmosphere packaging with enhanced abuse resistance for distribution handling.
Below 50 microns dominates unit volumes; above 150 microns delivers the highest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor anchors European flexible packaging demand, with coextrusion converters scaling capacity to serve Central European brand owners facing tightened recyclability mandates.
Germany
E-commerce grocery fulfillment centers in North Rhine-Westphalia pull high-barrier films into fresh produce segments. The EU Packaging and Packaging Waste Regulation forces converters in the Ruhr region to retool lines for mechanically recyclable structures. Berry Global Inc. leverages its captive recycling infrastructure near Düsseldorf to supply certified circular content to dairy packagers.
United States
FDA food contact notification requirements reshape material approval pathways for multi-layer structures serving protein packaging. Cold-chain pharmaceutical distribution in the Northeast Corridor expands oxygen barrier specifications for temperature-sensitive biologics. Sigma Plastics Group occupies a position among domestic converters scaling metallocene polyethylene capacity for food service applications.
China
Dual carbon goals accelerate pyrolysis investments by petrochemical majors seeking feedstock pathways for circular films. The Yangtze River Delta concentrates blown film extrusion capacity serving export-oriented consumer goods packagers. Ningbo and Shanghai house integrated converters qualifying for ISO 9001 and BRCGS certifications demanded by multinational food brands.
India
FSSAI packaging safety standards extend qualification timelines for adhesive tie layers in food contact applications. Maharashtra's flexible packaging cluster around Mumbai scales seven-layer and nine-layer coextrusion lines for dairy and ready-meal segments. Gujarat-based converters invest in captive recycling infrastructure ahead of anticipated Extended Producer Responsibility fee structures.
Switzerland
Swissmedic pharmaceutical serialization mandates drive specification toward nylon-enhanced barrier structures with documentary traceability. Basel's pharmaceutical contract packaging cluster adopts digital process control systems for real-time gauge profile correction. Temperature-sensitive biologics distribution requirements pull ultra-high-barrier films into medical-grade segments previously served by simpler formats.
Multi-Layer Blown Films Market Competitive Environment
Global majors compete with regional champions across recycling infrastructure and barrier technology differentiation. The vendor base stratifies into three tiers: integrated petrochemical-backed producers with captive resin supply, mid-scale converters with specialized coextrusion expertise, and regional fabricators serving spot markets. Two dominant competitive moves are reshaping positioning: chemical recycling partnerships securing feedstock for circular content claims, and dual ISO 9001 and BRCGS certification investments filtering supplier access to multinational food brands.
Within the integrated tier, Amcor plc and Berry Global Inc. exemplify archetypes combining proprietary barrier coating technologies with captive recycling infrastructure. DuPont de Nemours, Inc. anchors the high-performance materials vector through specialty nylon barrier layer supply. Regional champions including RKW Group and Coveris Holdings S.A. occupy positions among European converters scaling coextrusion capacity to serve Central European procurement consolidation. Mitsubishi Chemical Group represents the Asia-Pacific integrated chemical producer archetype with backward control over polymer feedstocks.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group |
| Winpak Ltd |
| Berry Global Inc. |
| Coveris Holdings S.A. |
| RKW Group |
| Amcor plc |
| Sigma Plastics Group |
| DuPont de Nemours, Inc. |
| Sealed Air Corporation |
| Others |
Value Chain & Pricing Dynamics
Coextrusion die engineering specialists concentrate in Germany's Ruhr region and northern Italy, where labor-cost differentials between these engineering hubs and Eastern European conversion centers drive 15-20% pricing-tier spreads across comparable barrier specifications.
Pricing Analysis
Ethylene feedstock pass-through dominates contract structures, with polyethylene resin indices resetting quarterly and converters bearing 60-90 day lag exposure. Three-tier pricing structure across premium, standard, and economy levels separates Amcor's proprietary barrier-coated films from commodity seven-layer structures and spot-market monolayer alternatives. Price differentiation hinges on ISO 9001 and BRCGS dual certification status plus captive recycling infrastructure access. Cost compression in standard-grade polyethylene is intensifying because EPR fee structures in Germany and France now penalize non-circular formats. Spot-market buyers in industrial bulk containment show highest price sensitivity; pharmaceutical contract packagers in Switzerland exhibit lowest sensitivity due to serialization compliance requirements.
Supply Chain Analysis
Post-consumer film collection and pyrolysis feedstock preparation flows remain underdeveloped, forcing brand owners to source certified circular content through chemical recycling partnerships rather than mechanical reprocessing streams. Raw material supply concentrates in Germany, the United States, and China, with metallocene polyethylene catalyst technology controlled by a handful of petrochemical licensors. Feedstock draws from crude-linked ethylene crackers, specialty polyamide polymerization units, and maleic anhydride grafted adhesive suppliers. Single-source vulnerability around coextrusion die manufacturing equipment creates bottleneck risk for converters scaling nine-layer capacity. Distribution runs through integrated film producers with direct brand-owner contracts, bypassing traditional distributor channels in high-specification segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Multi-Layer Blown Films Market compounds steadily as e-commerce grocery cold-chain requirements structurally expand addressable demand for high-barrier specifications.
For Market Incumbents: Deepen captive recycling infrastructure investments ahead of EU Packaging and Packaging Waste Regulation threshold tightening, particularly in Germany and France where EPR fee structures now penalize non-circular formats. Fortify coextrusion engineering talent pools through technical apprenticeship partnerships with equipment OEMs, as multilayer distribution manifold design expertise concentrates among a shrinking specialist cohort. For New Entrants and Emerging Players: The mid-tier price-point gap between Amcor's proprietary barrier-coated premium films and commodity polyethylene economy grades offers white-space entry for converters with vacuum deposition or plasma coating capabilities. Industrial bulk containment above 150 microns remains underpenetrated by coextrusion specialists, with agricultural chemical and construction material applications in Germany offering margin expansion. Pursue ISO 9001 and BRCGS dual certification as the primary qualification pathway to multinational food brand supply agreements. For Investors and Strategic Acquirers: Petrochemical majors seeking circular feedstock security are the most active acquirer in this space, targeting mid-scale converters with established chemical recycling partnerships and qualified barrier coating lines. Five-to-ten year viability rests on regulatory ratchet mechanics rather than cyclical demand, with EPR mandate expansion providing structural visibility. Monitor ECHA substance evaluation timelines for adhesive tie-layer REACH compliance as the key inflection signal for qualification cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Pyrolysis investments by petrochemical majors create certified circular feedstock pathways for multi-layer films. |
| Coextrusion Capacity Expansion | Seven-layer and nine-layer line additions in Germany serve Central European brand owner procurement consolidation. |
| Dual Certification Investment | ISO 9001 and BRCGS qualification filters supplier access to Unilever and Nestlé supply agreements. |
| Barrier Coating Technology Acquisition | Vacuum deposition capabilities match Amcor's proprietary performance in oxygen transmission specifications. |
| Captive Recycling Infrastructure Buildout | Post-consumer collection and reprocessing assets secure circular content claims under EPR mandates. |
Study Parameters
Coverage spans Germany, the United States, China, India, and Switzerland, with primary inputs from each market gathered through structured interviews with coextrusion line operators, flexible packaging procurement managers at multinational food brands, pharmaceutical contract packaging executives, chemical recycling technology providers, and regulatory affairs specialists at adhesive suppliers. Secondary validation draws from EU Packaging and Packaging Waste Regulation implementation documents, ECHA substance evaluation dossiers, FDA food contact notification databases, and trade association capacity surveys. Bottom-up demand modeling triangulates against top-down petrochemical feedstock consumption analysis.
Rate-of-change decomposition separates volume growth from value expansion across material grade tiers, end-use industry clusters, thickness specifications, and regional regulatory adoption patterns. Segmentation dimensions modeled include polyethylene versus nylon versus polypropylene formulations, packaging versus industrial versus agricultural applications, and above-150-micron versus below-50-micron thickness bands. CAGRs derive from regression analysis of historical resin price elasticities and forward projection of EPR mandate penetration curves. Industry-specific forecast inputs incorporate e-commerce grocery fulfillment center buildout pipelines and pharmaceutical cold-chain infrastructure investment tracking.
Caveats apply where ECHA restriction proposals targeting polyolefin additives or sudden ethylene feedstock price volatility could materially shift the outlook. Forecasts reflect assumptions about mechanical recycling infrastructure deployment timelines and chemical recycling yield rates that remain unproven at commercial scale. Practitioners should monitor ECHA authorization timelines and pyrolysis plant commissioning schedules for early signals of feedstock availability constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
Poly Tubing Market
Poly film
North America Polyimide Films Market
Poly film
Polytetrafluoroethylene (PTFE) Films Market
Poly film
Wrap Around Label Films Market
Poly film
Polyurethane (PU) Film Market
Poly film
Mexico Plastic Packaging Films Market
Poly film
Global BOPP Films Market
Poly film
Polystyrene Films Market
Poly film
France Plastic Packaging Films Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
Co Extruded Films Market
Poly film
Polysaccharide Films Market
Poly film
Nylon Films Market
Poly film
India Plastic Packaging Film Market